

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Disposable Color Contact Lenses Market Tops USD 3,450 Million in 2025, Poised for Strong Growth

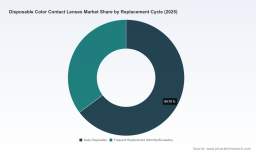
Worldwide Disposable Color Contact Lenses Market: Strategic Preview for 2026 Decision‑Making
PW Consulting’s latest market research brief on the Worldwide Disposable Color Contact Lenses market provides a focused strategic primer for executive teams planning 2026 investments and market plays. The global market—measured at a 2025 base year value of approximately USD 3.45 billion (revenue unit: Million USD)—is positioned for accelerated expansion in the coming cycle. Our model projects a compound annual growth rate (CAGR) of 8.7% over the 2026–2032 forecast window, reaching a market size in excess of USD 6.1 billion by 2032 under the baseline scenario. This preview synthesizes the actionable implications of that trajectory for product, regulatory, commercial and M&A strategies, while preserving the detailed segment-level datapack for subscribers and report purchasers.
Variable Inductance Shunt Reactors Market
Why this market matters for 2026 strategy
- Scale and momentum: Mid‑2020s demand dynamics demonstrate both resilient core replacement demand and an expanding addressable market driven by cosmetic adoption, new toric offerings, and broader retail distribution models.
- Technology inflection: Advances in materials (silicone hydrogel blends, high‑water formulations), pigmenting techniques for natural appearance, and integrated moisture systems are reshaping product differentiation.
- Regulatory and label complexity: Although many color lenses are positioned as cosmetic, regulators treat them as medical devices; obtaining and maintaining 510(k) clearance (or equivalent) and meeting ISO biocompatibility standards are table stakes for scale players.
- Consolidation opportunity: Market concentration measures indicate meaningful consolidation among top suppliers—creating both competitive pressure and M&A pathways to quickly scale capabilities or enter adjacencies.
What the numbers tell us (high‑level)
Our top‑line market model uses historic sales and channel indicators through 2025 as the foundation for the 2026–2032 forecast. The projected 8.7% CAGR reflects a mix of continued replacement demand for daily‑disposable formats, incremental premiumization (higher ASPs for specialty or toric color lenses), and channel migration to omnichannel retailing. Measured concentration metrics also matter: the top three firms control a majority share of the market, and the top five push that concentration above two‑thirds—conditions that make competitive actions by leading incumbents (and entrants backed by capital or strong regulatory positioning) critical to market dynamics.
Medical Protective Textiles Market
Practical content inside the full report
For strategy teams preparing 2026 budgets, PW Consulting’s full study provides an executable toolkit—not simply a forecast. Highlights include:
Worldwide Sugar Candy Market
- Proprietary market model (Excel) with scenario toggles for ASP, channel mix shifts, and regulatory lag assumptions suitable for M&A diligence and capital planning.
- Go‑to‑market playbooks by channel (online retail, optical networks, clinical channels) with measured conversion and margin assumptions calibrated to 2020–2025 performance trends.
- Regulatory and clinical roadmap templates: stepwise timelines for FDA 510(k) submissions, ISO 10993 biocompatibility programs, and post‑market surveillance structures tailored to cosmetic vs. prescription positioning.
- Product development checklists covering material selection, pigment stability testing, toric stabilization engineering and sterility & shelf‑life validation protocols.
- Competitive profiles and capability heat maps for major players, including technology strengths, geographic footprints, certification status, and likely near‑term moves.
- Commercial scenarios articulating pricing levers, bundling approaches, and payor engagement where specialty clinical indications may unlock reimbursement.
- M&A playbook and valuation sensitivity tables that align technology/IP risk with revenue synergies and time‑to‑market assumptions.
Competitive landscape: positioning and implications
The competitive set spans global incumbents with diversified disposable portfolios and smaller specialists that have used product design or channel focus to gain footholds. Noteworthy strategic themes emerging from company actions and filings include:
- Product differentiation via formulation and pigment technology. Established players continue to invest in daily‑disposable platforms with embedded moisture systems and layered pigment gradations to mimic natural irises—an important defensive and offensive lever in a crowded cosmetic space.
- Expansion into toric and prescription variants. Recent product launches and regulatory clearances reflect a clear trend: color lenses are moving beyond purely plano cosmetic positioning toward functional prescription solutions. This changes addressable market economics and raises entry barriers through enhanced clinical development needs.
- Regulatory clearances as market gatekeepers. New 510(k) approvals for silicone hydrogel toric designs and novel lens materials increase the intensity of competition for the prescription‑capable segment. Strategic actors that secure robust regulatory cover earlier can convert cosmetic interest into physician‑prescribed volumes.
- Channel diversification. A two‑track approach—protecting optical channel relationships while scaling direct‑to‑consumer channels—has become a best practice. Balancing margin capture with clinician endorsement is particularly important where clinical safety messaging is a differentiator.
Representative company positioning (high level): leading multinational device manufacturers maintain broad disposable portfolios and heavy regulatory & distribution capability, while regional specialists emphasize niche aesthetics, certifications for multiple markets (FDA, CE), and price/novelty plays—each requiring a distinct competitive response.
Regulatory and reimbursement environment — what changes in 2026?
Regulatory realities are pivotal to strategy. Authorities classify colored and decorative contact lenses as medical devices; that means even “cosmetic” variants require premarket pathways and biocompatibility evidence per ISO 10993. Recent filings and clearances highlight two tactical implications:
- Time to market is strongly driven by regulatory lead time and the robustness of biocompatibility & sterility dossiers; companies should budget regulatory resources and clinical capacity accordingly in 2026 planning cycles.
- Reimbursement remains limited for elective cosmetic use; however, the availability of prescription color or specialty lenses can unlock coverage pathways for clinically indicated products—making clinical differentiation a revenue multiplier in certain segments.
2026 action plan — prioritized strategic recommendations
We recommend a three‑horizon plan for executive teams who want to convert market growth into sustainable advantage in 2026:
- Near term (0–12 months): Harden regulatory pipelines (510(k) and ISO compliance), shore up supply chain redundancies for daily disposable production, and pilot DTC campaigns alongside clinician co‑marketing in selected markets. Validate toric/prescription engineering early to avoid later rework.
- Medium term (12–24 months): Execute channel segmentation playbooks—optimize pricing and bundling for optical partners while capturing higher margins online with subscription models. Deploy targeted product versions (material, pigment, and packaging) for prioritized customer cohorts and lock distribution partnerships in high‑growth territories.
- Longer term (24+ months): Pursue capability‑driven M&A—target players with regulatory clearances, unique pigment IP, or manufacturing scale for daily disposables. Build evidence generation programs to support clinical claims and potential reimbursement where medically indicated.
Risks and mitigants
Key risks for 2026 execution include regulatory delays, pigment stability or biocompatibility failures, channel price erosion, and supply chain constraints for specialized materials. Recommended mitigants:
- Parallelize regulatory and product validation workstreams to reduce schedule risk.
- Lock multiple qualified manufacturers for critical raw materials and consider near‑shoring options if logistics volatility threatens lead times.
- Design flexible commercial models that enable price differentiation by channel and value proposition without undermining optical partnerships.
What PW Consulting will not show here — and why
This article intentionally omits detailed segment and regional breakdowns, fine‑grained channel share tables and proprietary pricing datapoints. The full report contains those detailed matrices, interactive models and state‑by‑state dashboards that senior teams use for investment memos, diligence, and board presentations. This preview is designed to surface the strategic directions and decision levers while encouraging clients to access the complete dataset to execute with precision.
Next steps for executives
If your 2026 plan involves portfolio expansion, regulatory submissions, channel reinvention, or M&A in disposable color lenses, PW Consulting can support three immediate engagements:
- Rapid regulatory readiness audit (6–8 weeks) to map current dossiers to 510(k) and ISO 10993 expectations.
- Commercial channel optimization sprint (8–12 weeks) to define pricing, subscription, and optical partner models with ROI forecasts.
- Target screening and valuation for tuck‑in or platform M&A (12–16 weeks) using our scenario‑based valuation model calibrated to market growth and concentration metrics.
To access the full report, interactive market model and company profiles that contain the granular segment and country data required for transaction diligence or commercial planning, please visit the PW Consulting report page. Our extended dataset includes the detailed market segmentation, country dashboards, and the Excel model referenced in this preview—essential tools for converting the 8.7% CAGR opportunity into measurable enterprise value in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Disposable Color Contact Lenses Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com