

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Luggage Storage Locker Market Surges to USD 1,250.0 Million in 2025

Worldwide Luggage Storage Locker Market — Strategic Preview for 2026 Decision-Makers
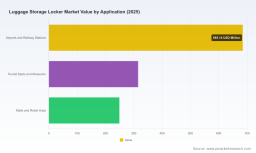
As travel resumes its multi-speed recovery and urban venue operators seek new ways to monetize footfall and improve customer experience, luggage storage lockers have moved from niche amenity to strategic infrastructure. PW Consulting’s latest market study — with a 2025 base year and a 2026–2032 forecast horizon — shows a market that has grown meaningfully over the last half-decade and is poised for steady expansion. Our headline numbers: the global market climbed from roughly USD 890 million in 2020 to about USD 1,250 million in 2025, and PW’s modeling projects continuation to nearly USD 1.84 billion by 2032, reflecting a 2026–2032 compound annual growth rate (CAGR) of approximately 5.66%.
Worldwide Desktop Search Software Market
Why this matters for boards and C-suite teams in 2026
-
Capital allocation: The category’s predictable mid-single-digit CAGR and clear technology-driven migration mean capital allocation timelines can be confidently staged — initial deployments to validate use cases, followed by scale budgets for networked rollouts or partnerships.
Worldwide Bone Marrow Aspiration Device Market -
Operational design: Self-service smart lockers materially reduce recurring staffing needs while unlocking 24/7 revenue windows. For operators focused on margin improvement, lockers represent a low-touch revenue stream with multiple adjacent monetization options (advertising, ancillary services, partnerships with last-mile retail or tourism platforms).
Worldwide High Pressure Boiler Feed Pumps Market -
Risk management: Compliance exposures around personal data handling and payments are now table stakes. Decision-makers must bake CCPA, GDPR and PCI-DSS considerations into procurement and integration timelines to avoid costly retrofits.
Market dynamics and technology trends shaping 2026 strategies
-
Smartification and cloud orchestration. The category is accelerating toward IoT-first architectures: cloud-based locker management, real-time utilization analytics, remote diagnostics and API-driven integrations with booking and payment ecosystems. These capabilities drive network economics — the more integrated the locker becomes within a city’s mobility and tourism stack, the higher the yield per unit.
-
Payment and security convergence. Expect rising demand for lockers that combine secure payment stacks (PCI-DSS-ready), encrypted access logs and modular hardware that supports both electronic and mechanical fail-safes. This dual approach addresses regulatory and vandalism risk without sacrificing the convenience users expect.
-
Service-layer partnerships. Strategic tie-ups between locker OEMs and consumer-facing platforms (travel agents, luggage-on-demand services, parcel networks) are already unlocking densification opportunities in dense urban cores and transit hubs. These partnerships shift the commercial model from one-off sales to recurring service revenues for both vendors and hosts.
-
Fragmentation with opportunity. The market remains fragmented — top vendors account for a modest share of total value, leaving latitude for regional specialists, vertical-focused providers and systems integrators to capture local scale. This low consolidation level creates acquisition and partnership opportunities for players seeking faster route-to-scale.
Regulatory and operational noise that will shape vendor selection
-
Data protection regimes (GDPR in the EU, CCPA-style statutes in the U.S.) now mandate encryption, careful access-log retention policies and vendor-side contractual commitments. Tender teams must include data protection officers at procurement gates.
-
Payment security standards: lockers that accept cards or digital payments need validated PCI-DSS controls; ensuring this is in place at the outset avoids business interruption when transactional services go live.
-
Labor and operating cost dynamics: automated lockers reduce staffing needs and offer predictable remote-management savings — a compelling argument in markets where hourly labor inflation and staffing constraints raise operating costs.
Competitive landscape — who matters and how to think about partners
PW’s competitive mapping identifies a diverse field of incumbents and specialists. From multinational security groups with broad access-control portfolios to agile IoT start-ups, each vendor presents a distinct value proposition.
-
LockTec GmbH (Germany) : Strong in transportation venues, LockTec’s Locksafe offering emphasizes robust mechanical options alongside touchscreen-enabled electronic units. For operators prioritizing durability in high-abuse environments (rail hubs, major stations), LockTec’s modular and vandal-resistant hardware is a practical fit.
-
ASSA ABLOY (Sweden) : As a global access-control leader, ASSA ABLOY brings scale, enterprise-grade security and mature product lines (including package and smart-locker systems). Organizations that need proven integration with broader door and access ecosystems will consider ASSA ABLOY for enterprise consistency and support networks.
-
American Locker & Salsbury Industries (USA) : Both bring manufacturing depth and proven, customizable mechanical/electromechanical designs. Their strength is in tailoring size profiles and finishes for institutional deployments where aesthetic and build standards matter.
-
Vecos (Netherlands) : Representative of the new wave of cloud-native locker providers, Vecos emphasizes IoT-centric management, flexible API access, and SaaS billing models — a fit for operators aiming to monetize via platform partnerships rather than one-off hardware sales.
-
Godrej & Boyce (India) : Offers a mix of high-security mechanical and electronic solutions and retains strong distribution advantages in Asia. For rollouts in emerging markets where local service coverage and compliance with local standards are critical, regional champions like Godrej accelerate deployment timelines.
-
Quadient (France) : Through Parcel Pending and strategic partnerships with consumer-facing luggage services, Quadient demonstrates how parcel locker networks can be repurposed or co-branded for luggage use, delivering fast network density in urban and retail locations.
-
DeBourgh Manufacturing, Alpha Locker Systems, Locker & Lock, Vlocker : These vendors cover the mid-market with durable, customizable modules, while offering varying degrees of IoT enablement and systems-integration support — often chosen by property managers and retail operators seeking tailored deployments without full enterprise overhead.
Recent market moves confirm the strategic direction: Quadient’s multi-phase partnerships to embed parcel-locker networks into luggage services and regional entrants launching tourism-focused offerings demonstrate how platform-led distribution and local-market activation will be central to growth over the next 12–18 months. Corporate teams evaluating vendors should therefore prioritize not just hardware specs, but the partner’s channel strategy, integration API maturity and ability to operate as a service-layer collaborator.
What PW Consulting’s report delivers — practical tools and decision-ready content
Our study is built for commercial leaders, infrastructure planners and strategic investors who need executable insight rather than descriptive noise. The report includes:
-
Market-sizing and forecast models (2020–2032), with scenario-driven sensitivity analyses to stress-test volume and revenue assumptions under alternative travel recovery and adoption curves.
-
Vendor scorecards and an impartial vendor-selection framework covering security, uptime guarantees, API maturity, payment compliance, TCO and lifecycle service economics.
-
Procurement-ready RFP templates and due-diligence checklists that incorporate data protection, PCI-DSS and local regulatory requirements — formatted for immediate use in tender processes.
-
Deployment playbooks with site-selection heuristics, utilization thresholds for economic viability, modular rollout sequencing and a simple TCO calculator that models capex vs. SaaS scenarios and expected payback periods.
-
Commercial partnership playbooks that outline revenue-share models, co-branding opportunities with parcel and tourism platforms, and monetization levers to drive higher yield per unit.
-
Case studies highlighting quick wins and failure modes from recent rollouts — valuable for operations teams to accelerate time-to-stable-state post-installation.
Strategic playbook — five actions for 2026 implementation
-
Prioritize API-first vendors for greenfield network plays. When your objective extends beyond a single site to a city or region, the ability to integrate booking platforms, payment gateways and analytics is critical.
-
Design procurement around compliance. Insist on demonstrable GDPR/CCPA and PCI-DSS controls in contract language, and require vendor liability caps to reflect data-processing risk.
-
Pilot for utilization data before scaling. Run time-boxed pilots in representative venue types to gather utilization and revenue-per-unit metrics; use those inputs to calibrate rollouts and avoid over-deployment.
-
Explore partnership pathways with parcel or tourism networks. Co-locating luggage services with parcel locker networks or booking platforms accelerates user acquisition and reduces customer acquisition costs.
-
Model hybrid ownership and service models. Consider capex-lite SaaS or revenue-share models where vendors operate and maintain the network — useful when speed-to-market and operator cashflow are constraints.
Conclusion — the strategic window in 2026
With a predictable mid-single-digit growth trajectory and clear technology and partnership playbooks, luggage storage lockers represent an infrastructure category that rewards thoughtful, staged investment. The market’s fragmentation creates room for regional champions, platform players and vertically integrated operators to co-exist and prosper. Boards and investment committees should treat lockers not as an isolated amenity, but as a node in mobility, retail and tourism ecosystems — one that can deliver recurring, low-touch revenue if deployed with the right vendor, compliance posture and partnership strategy.
PW Consulting’s full Worldwide Luggage Storage Locker Market report contains the detailed segmentations, regional rollouts, vendor benchmarking matrices and downloadable models you will need to execute in 2026. For the complete data set, granular segmentation and procurement-ready materials, visit PW Consulting’s report page or contact our industry practice for a briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Luggage Storage Locker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com