

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Anti-Emetic Drug Market Poised to Expand at a 4.85% CAGR Through 2032

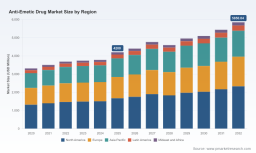
Worldwide Anti-Emetic Drug Market — 2026 Strategic Preview
PW Consulting’s newest market intelligence brief on the Worldwide Anti‑Emetic Drug Market frames the business choices that will determine winners and losers in 2026. Built on a 2020–2025 historical base and a 2026–2032 forecast horizon, the study places the market’s 2025 baseline at USD 4,200 Million and models a compound annual growth rate (CAGR) of 4.85% through the forecast period. Our analysis projects continued expansion, with market upside tied to therapeutic innovation, evolving standard-of-care in oncology, and the balance between branded lifecycle strategies and aggressive generic competition.
Worldwide Portable Storage Containers Market
Why 2026 is a Strategic Inflection Point
-
Convergence of clinical demand and commercial pressure: Oncology treatment volumes, evolving emetogenicity profiles of newer regimens, and a steady baseline of post‑operative care sustain demand—yet pricing dynamics and generic penetration are intensifying margin pressure for incumbent brands.
Oxidation Stability Reactor Market -
Innovation vs. commoditization: Late‑stage clinical activity and extended‑release/pediatric formulations are creating new proprietary slices of value, while mature 5‑HT3 agents face entrenched generic competition that materially compresses unit pricing.
Plumbing Fixtures Market -
Regulatory and reimbursement shifts: Targeted safety risk‑management (for example, REMS obligations associated with certain NK1 agents), changes to provider reimbursement mechanisms, and transparent ASP listings are shifting commercial negotiating power toward large purchasers and payers.
-
Supply chain resilience and cost control: The recent resolution of active ingredient shortages demonstrated how supply shocks can rapidly change competitive availability and create tactical windows for firms with flexible manufacturing or partnering strategies.
What PW Consulting’s Report Delivers — Practical, Executable Intelligence
Beyond headline sizing and a responsible forecast, PW Consulting’s report is structured to be directly usable by strategy, commercial, and BD teams preparing decisions in 2026. Highlights include:
-
Proprietary market model — transparent methodology and sensitivity levers you can re-run for alternative assumptions (pricing, penetration, therapy mix).
-
Scenario-based forecasts — base, conservative and upside cases that stress test regulatory, reimbursement and clinical outcomes.
-
Competitive playbooks — battle-tested GTM options for branded innovation, generic defense, and regional licensing.
-
Clinical pipeline heatmaps — indication and formulation prioritization across late‑stage NK1 and 5‑HT3 innovation.
-
Regulatory & reimbursement matrix — country-by-country guidance for label strategy, REMS compliance, HTA engagement and payer negotiation tactics.
-
Commercial checklists — pricing/contracting templates, hospital formulary engagement scripts, and value‑dossier outlines for oncology care pathways.
-
Operational playbooks — supply chain risk maps, contingency manufacturing options, and cost-to-serve analyses for low‑price generic networks.
Note: This public summary intentionally omits our detailed subsegment tables and underlying numeric splits. The full report contains the complete breakdowns and downloadable datasets essential for transaction diligence and market-entry planning.
Actionable Strategic Recommendations for 2026
-
Prioritize portfolio rationalization. Reassess low-margin legacy assets and redeploy commercial resources into high-value formulations (e.g., extended‑release injectables, fixed‑dose NK1/5‑HT3 combinations, pediatric formulations) where reimbursement is accessible.
-
Defend branded value early. For companies with lead products, accelerate label expansions and health economics studies to lock in hospital formularies before further generic entry erodes price and volume.
-
Adopt segmented pricing tactics. Use tender analytics and payer‑specific value propositions (e.g., bundle pricing for oncology cycles, outcome‑linked arrangements for high‑acuity care) to protect ASP and margin.
-
Build flexible supply chains. Maintain dual-source APIs for vulnerable molecules and qualify co‑manufacturing agreements in regions with spare capacity to avoid repeat shortages.
-
Look for bolt‑on M&A and licensing. Mid‑market generics manufacturers and regional specialty players remain attractive targets to secure route-to-market and cost advantages without full greenfield investments.
-
Invest selectively in pediatric and supportive-care niches. Recent regulatory approvals demonstrate clear demand and differentiation potential for age-appropriate formulations.
-
Prepare for regulatory constraints. Incorporate REMS and other post‑market commitments into early price and access planning to avoid commercialization delays.
Competitive Landscape — What Executives Need to Know
The anti‑emetic space remains a dual ecosystem: global innovators pursuing differentiated formulations and multi‑national generics firms aggressively defending share. Market concentration is meaningful but not prohibitive — our concentration metrics indicate a moderate top‑tier presence that leaves attractive opportunity for nimble challengers and strategic alliances (CR3 ≈ 38.5%, CR5 ≈ 52.2%).
-
Innovator dynamics: Merck (Emend) continues lifecycle management via label expansions; Helsinn’s combo strategies (e.g., fixed‑dose NK1/5‑HT3) and successful Phase III programs are renewing clinical options; Roche, Pfizer and GSK maintain franchise depth across established 5‑HT3 molecules and hospital relationships.
-
Specialty innovators: Heron’s extended‑release formulations and recent pediatric approvals illustrate the commercial payback from formulation innovation even in crowded classes.
-
Generics and scale players: Teva, Viatris (Mylan), Sandoz and regional players like Dr. Reddy’s ensure rapid price competition upon patent expiry, and their manufacturing scale underpins resilience during shortages.
-
Recent, material moves: approvals and positive trial readouts in 2023–2024 expanded tactical choices for market incumbents and entrants, and generic launches have already altered competitive access in major markets.
Regulatory, Pricing and Supply Signals to Monitor
-
REMS and safety programs can materially affect launch timing and commercial reach for certain NK1 agents; compliance costs should be baked into NPV models.
-
Historic patent expirations have shown how quickly branded price power can erode; generics compression (>80% in mature cases) remains the default tail risk.
-
Payer transparency mechanisms (CMS ASP listings and related reimbursement files) create public reference prices that shorten negotiation cycles and influence hospital purchasing behavior.
-
Supply disruptions are no longer hypothetical. The 2023 ondansetron shortage highlights the need for pre‑qualified secondary sources and inventory buffers for critical hospital‑administered formulations.
Risk Scenarios — What Could Move the Market Off‑Model
-
Regulatory tightening: expanded REMS or unforeseen safety signals could reduce accessible patient populations for specific agents and delay label extensions.
-
Clinical disappointments: late‑stage failures for proprietary NK1 candidates would disproportionately affect branded growth scenarios.
-
Accelerated genericization: faster-than‑expected patent challenges or additional compulsory licensing in key markets would compress revenue and increase price-based competition.
-
Supply shocks: API shortages or manufacturing site disruptions would advantage firms with diversified contract manufacturing and penalize single‑source suppliers.
How to Use This Report in the First 90–180 Days
-
90 days — Strategic alignment: run an internal workshop using our scenario outputs to set priorities (e.g., defend, divest, invest). Use our commercial checklists to prioritize five hospital systems or payers for immediate engagement.
-
180 days — Execution and partnerships: launch targeted pilots (pricing pilots, formulary dossiers), initiate supply‑side contingency contracts, and begin diligence on 1–3 identified M&A or licensing targets using our screening template.
-
360 days — Scaling and optimization: roll out successful pilots regionally, finalize partnerships, and formalize lifecycle management plans for priority assets using our regulatory timelines and HEOR playbook.
Conclusion — Where PW Consulting Adds Value
For executives making portfolio, M&A, or commercial access decisions in 2026, the anti‑emetic market presents both stable demand and strategic complexity. PW Consulting’s report combines transparent macro sizing, scenario analytics, executable playbooks and a competitor-signal map that together shorten decision cycles and reduce execution risk. We deliberately present a high‑signal executive summary here while withholding granular subsegment tables and downloadable models to ensure clients receive the full, usable intelligence necessary for transaction-grade decisions.
To access the full dataset, model files, and the complete segmentation and regional breakdowns required for due diligence and operational planning, please visit the PW Consulting report page for the Worldwide Anti‑Emetic Drug Market.
For detailed analysis of this topic, please visit the official page: Worldwide Anti-Emetic Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com