

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Global Mesoporous Carbon Market to Reach $1.85B by 2032 at 9.86% CAGR
By pmarketresearch, 2026-09-16
Navigating the Nano-Scale Revolution: Strategic Insights for the Global Meso-Micro Porous Carbon Materials Market Through 2032
The global landscape for advanced carbon materials is undergoing a structural transformation. No longer confined to traditional filtration roles, meso-micro porous carbon materials are becoming critical enablers in next-generation energy storage, high-purity catalysis, and stringent environmental remediation protocols. For corporate strategists, investors, and R&D directors, understanding the trajectory of this market is not merely an academic exercise—it is a prerequisite for securing supply chains, optimizing capital allocation, and identifying competitive moats in a decarbonizing economy.
PW Consulting's latest comprehensive study, the Worldwide Meso-Micro Porous Carbon Materials Market report, offers a granular roadmap of this evolution. Based on historical data from 2020 through the base year of 2025, the research projects market dynamics through the forecast period ending in 2032. This article serves as a strategic executive summary, highlighting the macro-economic forces, competitive maneuvers, and material science breakthroughs that define the sector, while outlining the actionable intelligence contained within the full dataset.
Macro-Economic Trajectory: From Recovery to Sustained Expansion
The market has demonstrated remarkable resilience and growth over the past half-decade. Following a global market valuation of approximately USD 605.42 million in 2020, the sector navigated post-pandemic supply chain adjustments to reach an estimated USD 958.32 million by 2025. This historical performance underscores a compound annualized growth rate that positions the industry favorably against broader chemical and materials sectors.
Carbon-Carbon Composite Material Market
Looking forward, the forecast period from 2026 to 2032 suggests an acceleration in value creation. The overall market size is projected to breach the USD 1 billion threshold in 2026, reaching USD 1,076.3 million, and continuing its upward march to reach USD 1,849.74 million by 2032. This growth trajectory, supported by a forecast CAGR of 9.86 percent, indicates more than just cyclical recovery; it reflects a fundamental shift in demand drivers. Industries are increasingly specifying porous carbon not as a commodity input, but as a performance-critical component tailored to micro- and mesoporous specifications.
This expansion is not uniform across the timeline. Early forecast years show steady increments, while later periods indicate potential step-changes in adoption rates as technologies mature. For decision-makers, this implies that capacity planning and technology licensing windows are narrowing. Missing the early wave of infrastructure build-out in energy storage or environmental compliance could result in significant long-term disadvantages.
Segmentation Dynamics: Technology, Application, and Regional Fores
While aggregate figures provide the top-line view, the real strategic value lies in understanding the divergent growth engines within the market. The segmentation analysis reveals distinct value pools defined by material type, end-use application, and geographic consumption.
Material Technology Divergence
The market is stratified by the method of pore structure engineering. Ordered mesoporous carbon, characterized by precise pore size distribution and high surface area uniformity, represents a significant portion of the value chain, catering to high-tech applications where consistency is paramount. Template-synthesized carbon offers another high-value avenue, allowing for customizable structures that bridge the gap between microporosity and mesoporosity for specialized catalytic and adsorption uses. Meanwhile, activated porous carbon remains the volume leader, driven by established infrastructure in purification and filtration. The interplay between these types dictates margin profiles; engineered variants typically command premium pricing compared to traditional activated grades, influencing R&D focus for material producers.
Application-Driven Demand Shifts
Demand is increasingly being pulled by specific application verticals rather than pushed by general industrial supply. Energy storage systems have emerged as a dominant force, leveraging the high surface area and conductivity of porous carbons for supercapacitors and advanced battery electrodes. Catalysis and chemical processing constitute another major pillar, where porous supports enhance reaction efficiency and selectivity in fine chemical synthesis. Environmental remediation continues to be a stable and growing driver, particularly as regulatory frameworks tighten around water and air quality.
The weight of these applications varies by region and by maturity of local industry. For instance, regions with aggressive renewable energy targets may see faster penetration in energy storage, while industrialized zones with strict emission standards may prioritize catalysis and remediation. Understanding the local mix is essential for market entry strategies.
Regional Consumption Patterns
Geographic distribution of revenue highlights where the demand is physically manifesting. Asia Pacific has established itself as a massive consumption hub, reflecting its manufacturing base and growing energy infrastructure. Europe and North America follow as significant markets, driven by high regulatory standards and advanced chemical industries. The Rest of World segment, while smaller in current valuation, represents an emerging frontier where infrastructure development could unlock latent demand.
However, regional analysis is not static. Trade flows, local content requirements, and logistical constraints are reshaping these maps. The full report dissects these regional nuances without relying on simplistic percentage splits, instead focusing on the absolute value flows and the strategic implications of regional dominance.
Competitive Landscape: Consolidation and Strategic Maneuvers
The market structure indicates a moderately concentrated environment, with the top three players holding a significant combined market share and the top five controlling a majority of the revenue. This concentration suggests that scale advantages in feedstock procurement, production technology, and distribution networks are critical barriers to entry. However, niche players with proprietary pore-engineering technologies can still capture high-margin segments.
Several key companies are actively shaping the market through capacity expansions, technological collaborations, and strategic repositioning. Kuraray Co., Ltd., including its Calgon Carbon Corporation subsidiary, remains a global heavyweight in activated carbons and porous materials. Their portfolio, featuring brands like KURARAY COAL and FILTRASORB, spans water and air purification to energy storage applications. In February 2026, Kuraray announced a substantial investment of nearly USD 100 million to expand reactivated carbon production capacity at their Columbus, Ohio plant by approximately 27 million pounds annually. This move targets the surging demand for drinking water treatment and PFAS removal, with operations expected to commence in 2028. Additionally, advancements at the Tyger River Plant in South Carolina signal a dual focus on capacity and geographic resilience.
In the specialty carbon sector, Cabot Corporation, including Norit, continues to lead with engineered porous and activated carbons focused on purification and performance applications. Their expertise in carbon black and porous variants positions them well for filtration and high-tech uses. Ingevity Corporation is another key player, optimizing activated and porous carbons for high BET surface area and mesopore development. Serving automotive emission control, pharmaceutical, and food contact sectors, Ingevity has also been exploring biomass-derived precursors, including pine wood and agricultural residues, to mitigate fossil feedstock volatility, as evidenced by their pilot unit announcements in 2025.
Japanese manufacturers are pushing the boundaries of mesoporous technology. Toyo Tanso Co., Ltd. specializes in proprietary CNovel® mesoporous carbon, featuring a unique inter-connected 3D mesopore network distinct from conventional activated carbon. This material offers controlled pore sizes and high dispersibility, finding applications in lithium-air battery electrodes, fuel cells, and analytical instruments. Toyo Tanso has been highly active in R&D collaborations. In September 2025, they collaborated with NIMS to develop a self-standing carbon membrane electrode using CNovel® for stable 1-Wh-class stacked lithium-air battery operation, demonstrating higher output and scalability. Furthering their innovation pipeline, April 2026 saw the establishment of the Toyo Tanso Carbon Recycling Design Joint Research Laboratory with Gifu University.
Other notable participants include Jacobi Carbons AB and Kureha Corporation in Europe and Japan, respectively, focusing on specialized grades for purification and energy-related uses. In the commodity and regional segments, Haycarb PLC leverages coconut shell-based activated carbons for high-purity adsorption in water treatment and gold recovery, particularly from their base in Colombo, Sri Lanka. European suppliers like Donau Carbon GmbH and Carbotech AC GmbH provide activated carbons with micro/mesoporous properties tailored for environmental purification and gas/liquid phase applications. In North America, Carbon Activated Corporation offers a wide range of filtration and purification products with controlled porosity structures.
Worldwide Meso-Micro Porous Carbon Materials Market
The competitive dynamic is further influenced by raw material constraints. In 2025, coconut shell charcoal feedstock prices surged significantly due to supply constraints from prior drought conditions. Prices in Sri Lanka rose from USD 522/MT to USD 860/MT, Indonesia increased from USD 622/MT to USD 1,045/MT, and India jumped from USD 551/MT to USD 983/MT between December 2024 and July 2025. This volatility, coupled with tightened availability of coal-based feedstocks, directly increased manufacturing costs for micro- and mesoporous carbon materials, forcing producers to navigate margin pressures or pass through costs.
Regulatory and Supply Chain Pressures Reshaping Dynamics
Regulatory frameworks are acting as potent demand catalysts. As of 2025-2026, U.S. EPA PFAS regulations and strengthened Mercury and Air Toxics Standards (MATS) have continued to drive demand for high-performance mesoporous and activated carbon adsorbents in water treatment and emission control. These regulations effectively mandate the use of materials with specific adsorption capacities and pore structures, favoring suppliers who can certify performance and compliance.
Simultaneously, supply chain sovereignty is gaining prominence. In response to global trade volatility and import tariff impacts, Calgon Carbon launched Operation Bedrock in 2025. This initiative aims to provide tariff-free, domestically sourced U.S. coal-based activated carbon supply, highlighting a strategic shift towards regionalization to ensure continuity for critical infrastructure projects.
These dynamics create a complex environment where regulatory compliance, feedstock security, and logistical resilience are as valuable as the material properties themselves. Companies must align their sourcing strategies with regulatory requirements while managing cost volatility.
Inside the Report: Operational Intelligence for Decision Makers
The PW Consulting Worldwide Meso-Micro Porous Carbon Materials Market report is designed to translate these macro trends into actionable intelligence. Beyond the high-level market sizing and CAGR projections, the document provides a deep dive into the operational realities of the sector.
The research methodology encompasses a rigorous analysis of historical data from 2020 to 2025, establishing a robust baseline for forecasting. The forecast period extends through 2032, allowing for long-term strategic planning. The report details the segmentation splits across type, application, and region, providing absolute revenue estimates that allow stakeholders to quantify opportunity sizes without relying on ambiguous market shares. This approach facilitates precise market sizing for product launches and capacity investments.
Furthermore, the report includes detailed company profiles, encompassing headquarters locations, official web resources, and comprehensive summaries of product portfolios and strategic positioning. The competitive landscape section goes beyond static descriptions to analyze recent developments, such as capacity expansions, technology collaborations, and joint research laboratories. These event analyses provide early signals of where competitors are allocating capital and where technological breakthroughs are emerging.
Industry context is also thoroughly examined. The report integrates data on raw material price volatility, such as the coconut shell and coal feedstock surges, and explains their impact on manufacturing costs. It details regulatory drivers, including specific EPA mandates, and their direct correlation with demand shifts in remediation and purification segments. Regional initiatives like Operation Bedrock are analyzed to illustrate the interplay between trade policy and supply chain strategy.
By synthesizing these elements, the report enables readers to conduct scenario planning. Stakeholders can assess how changes in feedstock prices might alter margin structures, how new regulations could open or close market segments, and how competitor movements might shift market shares. The granularity of the data supports detailed financial modeling and risk assessment.
Strategic Implications for 2026 and Beyond
As the market crosses the USD 1 billion milestone in 2026, the window for strategic positioning is open but narrowing. The growth rate of 9.86 percent suggests that the market will nearly double in value over the forecast period, creating substantial wealth generation opportunities for those who can navigate the complexities of material specification, regulatory compliance, and supply chain management.
For technology developers, the demand for ordered mesoporous and template-synthesized carbons in energy storage and catalysis presents a high-value target. Collaborations, such as those seen with Toyo Tanso and NIMS, underscore the importance of partnering with research institutions to accelerate commercialization of novel pore structures. For producers, the focus must be on securing feedstock resilience, as evidenced by the shift towards biomass precursors and domestic sourcing initiatives. Margin protection will depend on the ability to differentiate through performance certifications that meet tightening regulatory standards.
Investors and corporate strategists should look beyond the aggregate numbers. The divergence between high-growth application segments and mature commodity segments requires a nuanced portfolio approach. Understanding the regional concentration of demand and the specific competitive maneuvers of key players like Kuraray, Cabot, Ingevity, and Toyo Tanso is essential for identifying white spaces and potential disruption risks.
Accessing Complete Market Intelligence
This overview provides a foundational understanding of the drivers, dynamics, and key players shaping the global meso-micro porous carbon materials market. However, the full strategic picture requires access to the complete dataset. The specific revenue estimates for each segment, the detailed regional breakdowns, the precise market concentration metrics, and the exhaustive list of competitive developments are critical for precise budgeting and planning.
PW Consulting's Worldwide Meso-Micro Porous Carbon Materials Market report contains the depth of analysis required to transform these insights into executed strategy. From granular historical data to forward-looking forecasts, the report serves as an indispensable tool for navigating the complexities of this evolving market. Readers are encouraged to consult the full source document to obtain the comprehensive intelligence necessary for making informed decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Meso-Micro Porous Carbon Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide MCT Diet Market Hits $868M in 2025, Projected 6.85% CAGR Through 2032
By pmarketresearch, 2026-09-16
Global Medium Chain Triglyceride (MCT) Diet Market: Strategic Intelligence for 2026 Decision-Makers
Executive Summary: Navigating a High-Growth Diet Sector
The global Medium Chain Triglyceride (MCT) diet market has matured from a niche nutritional curiosity into a core component of modern dietary planning, functional wellness, and performance nutrition. Built on a foundation of consistent historical expansion between 2020 and 2025, the sector has crossed a critical scale threshold, with total market revenue surpassing 868 million USD in the base year of 2025. As we enter the 2026 forecast period, the trajectory points toward sustained demand acceleration, with a projected compound annual growth rate of 6.85 percent extending through 2032. For strategic leaders, investors, and product development teams, this inflection point demands more than surface-level trend monitoring. It requires granular, forward-looking intelligence that maps supply chain realities, evolving regulatory postures, formulation innovations, and competitive positioning across multiple usage verticals. This comprehensive market research study delivers exactly that: a structured, data-grounded examination of where the MCT diet market stands today and how it will reshape commercial strategy over the next seven years.
The 2026 Strategic Imperative: Why Timing and Intelligence Matter
Entering 2026, organizations operating within or adjacent to the MCT diet ecosystem face a convergence of forces that will separate agile strategists from reactive followers. On the demand side, consumer preferences have increasingly fused around metabolic wellness, ketogenic and low-carbohydrate dietary frameworks, and the search for fast-absorbing, sustained-energy lipid sources. This shift has pulled MCT products beyond traditional dietary supplement aisles into functional food and beverage formulations, clinical nutrition protocols, and infant nutrition applications. On the supply and compliance side, the landscape is being reshaped by raw material price dynamics for coconut oil and palm kernel oil, evolving labeling mandates from regulatory bodies such as the FDA, tariff structures in key import markets including the European Union, and packaging safety requirements for liquid supplement formats sold above specific volume thresholds. These intersecting pressures mean that 2026 is not simply another year of incremental growth. It is a year where formulation choices, sourcing strategies, regulatory preparedness, and channel positioning will directly influence margin resilience and market share retention. Decision-makers who attempt to navigate these variables without structured, scenario-tested intelligence risk misallocating R&D budgets, misreading regional opportunity densities, or underestimating competitive responses from established players.
Research Scope and Methodology: What the Study Delivers
Designed as a decision-grade intelligence asset, this Worldwide Medium Chain Triglyceride (MCT) Diet Market study combines multi-year historical reconstructions with a forward-looking forecast framework covering 2026 through 2032. The analytical architecture is built to support three core planning functions: market sizing with directional confidence, segmentation mapping across material sources, product forms, end-use applications, and geographic footprints, and competitive movement tracking across both consumer-facing and industrial-grade suppliers. Rather than presenting a monolithic view of demand, the research disaggregates growth drivers to reveal where consumption intensity is highest, which product formats are gaining traction, and how sourcing origins influence cost structures and brand positioning. The study also integrates regulatory and trade-environment analysis, incorporating food labeling updates, pediatric safety packaging expectations, and evolving tariff classifications that affect cross-border coconut and palm kernel oil flows. Operational developments within the competitive field are tracked alongside these structural factors, allowing readers to see how product launches, SKU expansions, and certification renewals interact with broader demand signals.
Market Trajectory: From Established Growth to Forecasted Expansion
Historical revenue data from 2020 through 2025 demonstrates a durable expansion curve, reflecting both steady consumer adoption and broader commercial integration of MCT lipids into everyday diet and wellness routines. Starting from a global base above 620 million USD in 2020, the market advanced consistently year over year, reaching approximately 868 million USD by 2025. This uninterrupted ascent underscores the sector’s transition from early-adopter enthusiasm to mainstream dietary utility, particularly as MCT-based products became more visible in functional beverages, meal-replacement formats, and performance-focused nutritional stacks. Looking ahead, the 2026 to 2032 forecast period projects continued revenue escalation, beginning near 924 million USD in 2026 and progressing toward a higher multi-hundred-million-dollar threshold by 2032. The implied growth rate of 6.85 percent CAGR reflects a market that is expanding not merely through population or inflation effects, but through formulation innovation, category extension, and deeper penetration across both supplement and functional food channels. For executives, this trajectory signals that the window to establish brand differentiation, secure preferred supplier relationships, and align product pipelines with emerging application demand is open now, but will narrow as adoption becomes more crowded and more regulated.
Segmentation Architecture: Decoding Sources, Forms, Applications, and Regional Demand
The research dissects the broader market into multiple analytical dimensions so that strategic planning can move beyond aggregate figures and into actionable segmentation logic. On the sourcing side, coconut oil and palm kernel oil represent the two principal feedstocks feeding MCT production, each carrying distinct cost profiles, sustainability perceptions, regional supply concentrations, and formulation implications for C8 versus C10 fatty acid balance. The study examines how sourcing economics influence end-product pricing, label positioning, and consumer trust, particularly as organic certification and clean-label expectations continue to shape premium-tier product design.
In terms of product form, the market is divided between MCT oil and MCT powder, each serving different consumption contexts, convenience requirements, and formulation constraints. Liquid oil formats remain central to direct supplementation, beverage mixing, and culinary integration, while powder variants are increasingly positioned for portability, dosing control, and compatibility with dry-mix meal replacements, keto baking applications, and post-workout recovery blends. The research evaluates how form preferences are shifting across usage occasions and how manufacturers are adapting production processes to meet texture, solubility, and stability expectations in each format.
End-use application segmentation reveals where commercial value is being generated and where expansion potential remains strongest. Dietary supplements continue to anchor a significant share of demand, reflecting MCT’s established role in metabolic support, energy stabilization, and intermittent fasting or ketogenic diet protocols. Functional food and beverages represent a rapidly evolving channel, with product developers embedding MCT lipids into coffee blends, smoothie bases, bars, and ready-to-drink formats. Infant nutrition and pharmaceutical applications further diversify the demand base, introducing distinct regulatory, purity, and clinical consideration requirements that separate healthcare-adjacent formulations from mainstream consumer wellness products. The study provides the segmentation framework needed to identify which application pathways present the strongest margin opportunity, the highest compliance complexity, or the greatest risk of competitive saturation.
At the regional level, the analysis maps how consumption patterns and commercial opportunity distribute across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Rather than treating geography as a static backdrop, the research examines how regional preferences, import dependencies, trade tariffs, dietary culture, and retail infrastructure shape localized growth trajectories. This regional lens is critical for companies evaluating distribution expansion, sourcing diversification, or form-specific market entry strategies.
Worldwide Medium Chain Triglyceride (MCT) Diet Market
Competitive Landscape: Positioning, Innovation, and Strategic Movement
The competitive environment reflects a blend of consumer-brand specialists and industrial-grade suppliers, each pursuing distinct value propositions within the MCT diet ecosystem. Several prominent companies anchor the landscape with differentiated product strategies and targeted audience positioning. Sports Research offers premium coconut-derived MCT oil and powder formats optimized for ketogenic diets and performance nutrition, with recent 2025 expansion activity highlighting continued investment in organic powder formats for broader consumer accessibility. Perfect Keto has concentrated on MCT oil powders and exogenous ketone blends featuring C8 MCT for low-carb diets and meal replacement use, while also broadening SKU variety to support keto baking and flavor diversification. Onnit positions MCT oil within a broader Total Human Optimization framework, emphasizing sustained energy and compatibility with bulletproof coffee and keto-oriented applications. Nutiva focuses on organic coconut-based MCT oil for vegan keto diets and culinary uses, and its 2024 USDA Organic recertification reinforced its clean-label positioning in a market where certification status increasingly influences purchase confidence. Ancient Nutrition combines keto-friendly MCT oil powders with collagen, targeting post-workout recovery and intermittent fasting support, illustrating how MCT is being integrated into multi-ingredient functional stacks.
Beyond the consumer-facing brands, the landscape includes industrial and formulation-oriented suppliers that underpin broader food, beverage, and supplement development pipelines. IOI Oleo GmbH serves as a global supplier of high-purity MCT oils for food, beverage, and diet supplement formulations, while Stepan Company manufactures Captex MCT triglycerides used in nutritional bars, beverages, and clinical diet products. KLK Oleo contributes palm kernel-derived MCT oils for global food and pharmaceutical-grade diet applications, reflecting the role of palm kernel supply chains in scaling specific form and purity requirements. Together, these players demonstrate that the competitive field is not defined solely by shelf presence but also by formulation capability, purity standards, supply chain reach, and B2B relationship strength. The study tracks how product launches, SKU expansions, certification updates, and supply positioning interact to shape competitive advantage, enabling readers to benchmark their own strategies against active market movements rather than relying on static competitor lists.
Regulatory, Trade, and Supply Environment: Managing Risk and Compliance
Strategic planning in the MCT diet market cannot ignore the operational realities of regulation, trade policy, and raw material volatility. Food and supplement labeling requirements have tightened around fat content disclosure and per-serving nutrient transparency, making accurate formulation documentation and compliant label design essential for market access and consumer trust. In parallel, packaging mandates for liquid MCT oils sold as dietary supplements above certain volume thresholds have introduced child-resistance requirements that affect packaging cost, design choices, and retail handling protocols. These compliance layers may appear incremental in isolation, but they compound quickly when scaled across product lines, export markets, and SKU proliferation.
Trade and tariff conditions further influence regional profitability and sourcing logic. Tariff classifications affecting coconut oil imports into the European Union, for example, can alter the cost competitiveness of specific sourcing origins and change the calculus for brands that rely on cross-border ingredient flows. At the same time, raw material pricing dynamics for coconut oil remain sensitive to supply conditions in major producing regions, meaning that procurement teams must weigh spot-market exposure against long-term supply agreements and alternative feedstock strategies. The research integrates these environmental factors so that market sizing and growth projections can be interpreted with realistic awareness of margin sensitivity, regional cost differences, and the operational burden of regulatory adaptation.
Strategic Takeaways for Corporate Decision-Making in 2026
The overarching message of this study is that the MCT diet market is entering a phase where superior intelligence translates directly into commercial advantage. Companies that treat the category as a single growth curve will miss the segmentation-specific dynamics that determine which products win shelf space, which applications attract reformulation investment, and which regions offer the most favorable balance of demand and cost exposure. The research is structured to help leadership teams answer higher-order strategic questions: Which product forms and application channels align most closely with target consumer behavior? How should sourcing portfolios be constructed to balance cost, purity, and regulatory compliance? Where do certification, labeling, and packaging requirements create barriers that can be turned into differentiators? How do competitor moves in product launches and SKU expansion signal broader category shifts?
Medium-chain Triglycerides (MCT) Market
By grounding these strategic questions in a multi-year historical context and a clearly modeled forecast horizon, the study provides a practical decision-support framework rather than a simple market snapshot. It enables R&D, commercial, procurement, and market-access teams to align on a shared view of opportunity, risk, and timing. In a sector where growth is strong but competitive density is increasing, the ability to anticipate formulation trends, regulatory adjustments, and competitor behavior will determine whether organizations capture disproportionate value or merely follow the market at a distance.
Next Steps: Accessing the Full Intelligence Framework
This article provides a structured preview of the analytical scope, market logic, and strategic relevance embedded in the full report. However, the complete research asset goes far beyond the directional insights summarized here. It delivers comprehensive segmentation data, detailed regional assessments, competitive profiling, supply-chain and regulatory analysis, and forward-looking scenario perspectives that together form a complete decision-making toolkit. For executives and strategy teams planning 2026 initiatives, the full study offers the depth required to validate product roadmap choices, refine market-entry assumptions, and prioritize resource allocation across formulations, channels, and geographies. Readers seeking the complete quantitative and qualitative intelligence framework are encouraged to access the full report directly, where the underlying data, segmentation breakdowns, and competitive timelines can be examined in detail and applied to specific corporate planning needs.
For detailed analysis of this topic, please visit the official page: Worldwide Medium Chain Triglyceride (MCT) Diet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Microencapsulated Paraffin PCM Market Hits $486M in 2025, Forecast 13.52% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Growth Cycle: Inside the Worldwide Microencapsulated Paraffin Phase Change Materials Market
In an era where thermal efficiency dictates competitive advantage across construction, electronics, and energy storage, microencapsulated paraffin phase change materials (PCMs) have evolved from niche additives to foundational components of sustainable infrastructure. As organizations navigate complex supply chains, volatile raw material costs, and tightening energy regulations, access to precise, forward-looking market intelligence is no longer optional—it is a prerequisite for strategic resilience. Our newly released Worldwide Microencapsulated Paraffin Phase Change Materials Market study delivers exactly that: a comprehensive, data-driven blueprint designed to inform capital allocation, product development, and partnership strategies through 2032.
The Macro Trajectory: Sustained Expansion Anchored by Technological Convergence
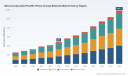
The market for microencapsulated paraffin PCMs has demonstrated remarkable momentum over the past half-decade. Valued at approximately 254.12 million USD in 2020, the sector expanded steadily to reach 486.0 million USD by 2025. This trajectory reflects more than incremental growth; it signals a structural shift in how industries approach thermal management. Drivers include the global push toward net-zero building standards, the proliferation of high-density electronic systems requiring precise temperature regulation, and the rapid scaling of thermal energy storage solutions integrated with renewable generation.
Looking ahead, the forecast period from 2026 to 2032 projects a compound annual growth rate of 13.52 percent. By 2032, the market is positioned to surpass 1.18 billion USD, underscoring a sustained demand environment that rewards early movers with robust R&D pipelines and strategic distribution networks. This growth is not uniform across all vectors. Instead, it is being shaped by divergent regional adoption curves, material science breakthroughs in shell chemistry, and application-specific performance requirements that are redefining procurement priorities for engineering and procurement leaders worldwide.
Beyond Headline Figures: Real-Time Dynamics Shaping Procurement and Pricing
Market sizing alone cannot capture the operational realities facing manufacturers and end-users. Raw material volatility remains a critical variable. Paraffin wax pricing has exhibited notable regional divergence, with feedstock costs in Europe tracking higher than those in Asia and North America. As of late 2025 and into early 2026, benchmark pricing has shown moderate downward corrections in several key markets, yet the correlation with crude oil feedstock costs continues to introduce short-term forecasting complexity. For procurement teams, this environment demands agility: negotiating long-term supply agreements, diversifying shell material sourcing, and evaluating bio-based alternatives that can insulate value chains from fossil fuel price swings.
Simultaneously, recent corporate developments illustrate how established players and new entrants are responding to these pressures. In mid-2025, BASF SE announced a dedicated product line targeting construction-sector thermal regulation, reinforcing the industry's focus on building envelope efficiency. Honeywell International Inc. subsequently expanded a strategic partnership with a leading HVAC manufacturer to embed microencapsulated phase change materials into smart building ecosystems. Meanwhile, Dow Inc. unveiled an initiative focused on bio-based microencapsulated paraffin development, signaling a broader industry pivot toward sustainable feedstock alternatives. These moves are not isolated; they reflect a coordinated acceleration in commercialization, cross-industry integration, and material innovation that will directly influence competitive positioning over the forecast horizon.
Report Architecture: Actionable Intelligence for Cross-Functional Decision Makers
This study is engineered for practitioners who require more than aggregated market estimates. The analysis framework is structured to translate macro trends into executable strategies across R&D, sales, supply chain, and corporate development functions. The report encompasses the following core components:
- Historical Baseline and Forecast Modeling: A detailed reconstruction of market performance from 2020 through 2025, paired with a segment-level projection extending through 2032. The modeling methodology accounts for adoption lag curves, regulatory impact timelines, andSubstitution dynamics across competing thermal management technologies.
- Segmentation Deep Dives: Granular analysis across three primary dimensions—geographic regions, shell material chemistries, and end-use applications. Rather than presenting static volumes, the study maps adoption intensity, performance requirements, and cost sensitivity to help stakeholders identify high-return entry points and avoid saturated or margin-thin segments.
- Competitive Landscape and Strategic Positioning: Comprehensive profiles of the companies shaping the market, including technology differentiation, geographic reach, product portfolio breadth, and recent commercial moves. The analysis highlights concentration dynamics, partnership patterns, and whitespace opportunities for new entrants or expansion-focused incumbents.
- Supply Chain and Raw Material Intelligence: Tracking of paraffin wax pricing trends, feedstock cost correlations, and regional supply constraints. This section equips procurement and finance teams with the context needed to structure resilient sourcing strategies and evaluate the economic viability of bio-based or alternative shell formulations.
- Regulatory and Sustainability Context: An assessment of how building energy codes, industrial efficiency mandates, and corporate ESG commitments are accelerating PCM integration. The report connects policy trajectories to demand forecasting, helping organizations align product roadmaps with compliance timelines and incentive structures.
- Scenario Planning and Risk Assessment: Structured evaluations of upside and downside scenarios, including feedstock disruption, technological substitution, and regional policy divergence. These frameworks enable leadership teams to stress-test investment decisions and prioritize initiatives with the highest risk-adjusted returns.
Each section is designed to function independently for quick reference while maintaining coherence when reviewed as a complete dossier. Executive summaries, data tables, and strategic takeaways are integrated throughout, ensuring that both technical teams and C-suite stakeholders can extract relevant insights without navigating redundant content.
Navigating the Competitive Field: Leaders, Specialists, and Emerging Contenders
The market structure reflects a blend of specialized PCM manufacturers, diversified materials science firms, and large industrials leveraging thermal management as part of broader energy efficiency portfolios. Concentration metrics indicate a moderately consolidated landscape, with the top three players collectively capturing a significant portion of revenue and the top five extending their share further. This structure creates both barriers and opportunities: established firms benefit from scale, regulatory track records, and embedded customer relationships, while agile specialists can differentiate through niche formulations, faster customization cycles, or application-specific performance tuning.
Several organizations exemplify the strategic diversity within the sector. Microtek Laboratories, based in Dayton, Ohio, has built a reputation around paraffin-based microPCM products tailored for thermal regulation across building materials, textiles, logistics, and electronics. Rubitherm Technologies GmbH, headquartered in Berlin, focuses on organic phase change materials, including microencapsulated paraffin solutions for construction, cold chain logistics, and industrial thermal energy storage. Croda International Plc, operating from Snaith in the United Kingdom, offers a portfolio that spans bio-based and microencapsulated PCM products in powder or dispersion formats, with paraffin wax-based options designed for precise temperature control across varied ranges.
Additional players contribute distinct capabilities to the ecosystem. PCM Products Ltd, based in the United Kingdom, provides the PlusICE range, covering microencapsulated and encapsulated paraffin-based PCMs for HVAC, thermal energy storage, and wide-temperature applications. Andores New Energy Co., Ltd, a Chinese manufacturer, supplies microencapsulated paraffin PCMs and grain compositions targeting cold chain, building, and energy storage markets. Honeywell International Inc., with a major presence in Charlotte, North Carolina, develops advanced microencapsulated paraffin PCM solutions integrated into thermal management systems for buildings, electronics, and industrial uses. Encapsys, LLC, located in Appleton, Wisconsin, specializes in microencapsulation technologies for paraffin-based cores applicable to textiles, coatings, and construction. PureTemp LLC, operating in the United States, emphasizes bio-based and organic PCM options, including microencapsulated paraffin variants for commercial temperature control. Climator Sweden AB produces microencapsulated paraffin PCMs oriented toward energy-efficient building and thermal storage solutions, while Phase Change Energy Solutions Inc., also U.S.-based, develops both microencapsulated and macroencapsulated paraffin products for building envelopes, HVAC, and thermal regulation.
The competitive narrative is further enriched by recent commercial activity. BASF SE's August 2025 product launch for construction thermal regulation, Honeywell's September 2025 partnership expansion with an HVAC leader for smart building integration, and Dow Inc.'s July 2025 initiative on bio-based microencapsulated materials collectively illustrate how product innovation, cross-industry collaboration, and sustainability-driven R&D are converging. For stakeholders evaluating market entry, partnership structures, or portfolio expansion, understanding these dynamics is essential to anticipating pricing pressure, technology substitution risk, and the pace at which new formulations will reach commercial scale.
Strategic Imperatives for 2026 and Beyond
As organizations transition from planning to execution in 2026, several priorities will separate leaders from followers in the microencapsulated paraffin PCM market. First, material selection must be evaluated through a dual lens of performance and supply resilience. Shell chemistry choices—ranging from polymethyl methacrylate and melamine-formaldehyde resin to urea-formaldehyde resin and bio-based polymers—carry distinct trade-offs in terms of thermal stability, processing compatibility, regulatory acceptance, and cost structure. The study's segmentation analysis provides the comparative context needed to align material strategy with application requirements rather than defaulting to legacy specifications.
Worldwide Microencapsulated Paraffin Phase Change Materials Market
Second, geographic strategy requires nuance. Demand intensity, regulatory momentum, and raw material cost environments vary significantly across regions. Companies that treat geographic expansion as a uniform rollout often encounter margin compression or delayed adoption. Instead, the report's regional framework helps identify where infrastructure investment, building retrofit cycles, electronics manufacturing growth, and energy storage policy incentives are converging to create near-term demand pockets. This enables phased market entry, targeted distribution partnerships, and resource allocation that matches local adoption readiness.
Third, integration with broader thermal management ecosystems is becoming a competitive differentiator. The expansion of smart building platforms, the scaling of HVAC system upgrades, and the increasing density of electronic and battery applications are creating demand for PCM solutions that are not merely commodities but engineered components within larger system architectures. Firms that invest in application engineering, testing partnerships, and co-development arrangements are better positioned to capture value beyond unit volume, including long-term service contracts, specification lock-in, and cross-selling opportunities across adjacent thermal management segments.
Worldwide Paraffin Phase Change Material (PCM) Market
Finally, sustainability and feedstock strategy will increasingly influence procurement decisions and regulatory compliance pathways. The industry's movement toward bio-based alternatives, coupled with raw material price fluctuations tied to crude oil dynamics, means that organizations must evaluate total cost of ownership, carbon footprint implications, and supply continuity in tandem. The report's raw material tracking and scenario planning sections provide the analytical foundation to model these variables and align sourcing strategies with both financial and ESG objectives.
Accessing the Full Intelligence Framework
The Worldwide Microencapsulated Paraffin Phase Change Materials Market study is built to support decision-making at multiple levels—from product portfolio reviews and regional expansion plans to supplier negotiations and M&A screening. While this overview highlights the macro trajectory, competitive dynamics, and strategic themes shaping the sector, the complete research dossier contains the detailed segmentation data, company benchmarking matrices, pricing trend analysis, and scenario models required to translate insight into action. Organizations seeking to quantify opportunity sizes, compare shell material economics across applications, or evaluate competitive positioning with precision will find the full dataset essential to validating investment theses and operational plans.
As thermal efficiency continues to migrate from a compliance consideration to a core value driver, the ability to act on accurate, forward-looking market intelligence will define which companies capture growth and which respond reactively to shifting demand. This study is designed to provide that clarity, offering a structured, evidence-based foundation for the strategic decisions that will shape performance through 2032 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Microencapsulated Paraffin Phase Change Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Office Building Design Market Hits $42.5B in 2025, Projects 4.65% CAGR to 2032
By pmarketresearch, 2026-09-16
Global Office Building Design Market: Strategic Intelligence for 2026 Decision-Makers
The global office building design market stands at a critical inflection point. As organizations navigate post-pandemic workplace paradigms, sustainability mandates, and technological disruption, the design of commercial office spaces has evolved from a purely architectural exercise into a strategic imperative that directly impacts talent retention, operational efficiency, and corporate ESG performance. Our latest Worldwide Office Building Design Market research provides a comprehensive, data-driven blueprint for executives, developers, and design professionals seeking to capitalize on the market's trajectory through 2032.
Drawing on historical performance from 2020 through 2025 and projecting forward across a seven-year forecast horizon, this study captures the market at an estimated valuation of over 42.5 billion USD in the base year, with a clear acceleration trajectory toward more than 58.4 billion USD by 2032. The compound annual growth rate of 4.65 percent reflects the steady, structural demand reshaping how offices are conceived, engineered, and delivered worldwide. For corporate strategists, real estate investors, and design firm leaders, this report translates macroeconomic momentum into actionable intelligence, mapping the forces that will define competitive advantage in the years ahead.
The Macro Landscape: Growth Trajectory and Structural Shifts
Over the past five years, the office building design sector has demonstrated remarkable resilience, absorbing the shock of hybrid work adoption while simultaneously reorienting around wellness, sustainability, and digital integration. Historical data reveals a market that not only recovered from pandemic-era disruption but expanded its value proposition, moving beyond square footage allocation to encompass holistic workplace strategy. The forecast period from 2026 to 2032 signals a market characterized by compounding growth, driven by capital reinvestment in commercial real estate, regulatory pressure toward net-zero performance, and the ongoing digitalization of design workflows.
A defining feature of the current market structure is its highly fragmented competitive landscape. The combined market share of the top three firms remains modest, and even the top five players account for less than one-fifth of total industry revenue. This fragmentation creates both opportunity and complexity: no single entity dominates the value chain, allowing regional specialists, technology providers, and interdisciplinary consortia to compete on innovation, service depth, and domain expertise. For clients evaluating design partners, this means a rich ecosystem of alternatives, each bringing differentiated capabilities in sustainability integration, BIM coordination, spatial programming, and regulatory compliance.
The report dissects this landscape across multiple dimensions, examining how design services are allocated across architectural, interior, structural, and landscape/urban planning disciplines, as well as how project categories split between new construction and renovation or retrofitting. Rather than presenting static allocations, the analysis contextualizes these splits within evolving client priorities—where retrofitting existing stock gains traction against demolition-and-rebuild approaches, and where interior and architectural design converge to address hybrid work rhythms. Understanding these structural dynamics is essential for firms positioning their service portfolios and for corporate real estate leaders allocating capital across design phases.
Competitive Arena: Key Players and Recent Strategic Moves
The competitive environment is shaped by a blend of global architecture firms, multidisciplinary engineering consultancies, and software platforms that underpin the design process itself. The report profiles the principal actors driving innovation, each representing distinct strategic positioning within the market.
Office Furniture Market
Gensler, headquartered in San Francisco, continues to advance workplace strategy at scale, integrating biophilic design, wellness features, and flexible layouts tailored to hybrid environments. A notable recent milestone includes the completion of a 1,000+ desk workplace for Amazon in London, featuring hybrid work zones and biophilic elements, underscoring the firm's capacity to deliver large-scale projects that reconcile density with human-centered design.
AECOM, based in Dallas, provides comprehensive office building design services with a strong emphasis on sustainable architecture, BIM integration, and adaptive reuse. Its September 2025 collaboration announcement with Microsoft on AI-integrated office design for headquarters expansion highlights a growing trend: technology giants partnering with design firms to embed adaptive, intelligent spatial systems into flagship corporate campuses.
HOK, from St. Louis, emphasizes human-centered design, net-zero energy buildings, and technology-enabled workspaces for multinational enterprises. The firm's recognition with an AIA COTE Top Ten Award in April 2025 for a net-zero office building design project in Seattle reinforces the industry's shift toward demonstrable environmental performance as a market differentiator.
Perkins&Will, headquartered in Chicago, leads in resilient, inclusive spaces incorporating WELL Building Standards and circular economy principles. Its work aligns with a broader regulatory and client-driven push for health-and-wellness certification as a baseline, not a premium. Skidmore, Owings & Merrill (SOM), also Chicago-based, remains renowned for high-rise office towers and innovative designs featuring advanced structural engineering, daylight optimization, and smart building systems—capabilities increasingly relevant as urban density and performance standards intensify.
On the technology side, Autodesk, Bentley Systems, and Graphisoft serve as critical enablers. Autodesk's Revit and BIM 360 platforms support collaborative 3D modeling, simulation, and construction documentation, while its June 2025 release of Revit 2026 introduced enhanced generative design tools for office layouts, optimizing space utilization and sustainability metrics. Bentley Systems' AECOsim and OpenBuildings Designer facilitate infrastructure modeling and digital twin creation, with a March 2025 product launch improving interoperability for multi-disciplinary office design teams. Graphisoft's Archicad supports openBIM workflows and energy analysis, enabling sustainable design decisions at the architectural level. Together, these platforms are reshaping how design teams collaborate, iterate, and validate performance before ground is broken.
Market Dynamics: Regulations, Talent, and Technology Pressures
Beyond firm-level competition, the market is being reshaped by regulatory frameworks, labor economics, and technology adoption cycles that directly affect project feasibility, cost structures, and design outcomes. The report synthesizes these forces into a cohesive dynamics analysis, enabling stakeholders to anticipate compliance burdens, workforce constraints, and digital transformation requirements.
Regulatory momentum is accelerating. The WELL Building Standard v2, updated in 2024, mandates performance verification for office designs, requiring more than 40 metrics across air, water, and thermal comfort. This elevates wellness from design aspiration to measurable obligation, impacting material selection, mechanical systems, and commissioning protocols. In Europe, the recast Energy Performance of Buildings Directive requires all new office buildings to achieve near-zero energy standards by 2030, compressing design timelines for energy modeling and envelope performance. Meanwhile, LEED v5, launched in 2024, introduces social equity credits for office designs, emphasizing inclusive access and community impact—expanding the scope of sustainability to encompass social dimensions alongside environmental ones.
Labor market dynamics present both constraints and incentives. The average salary for architectural designers in the office building sector reached approximately 105,000 USD annually in the United States, reflecting a 5 percent year-over-year increase driven by demand for BIM expertise. Concurrently, a global shortage of an estimated 1.5 million construction professionals is projected by 2030, fueling 15 to 20 percent cost inflation for specialized office design labor. These pressures are compressing margins for firms reliant on traditional delivery models while incentivizing investment in digital tools, prefabrication, and outcome-based service contracts.
Technology is simultaneously alleviating and intensifying these pressures. Generative design, digital twins, and integrated BIM workflows are reducing iterative cycles, improving performance prediction, and enabling earlier stakeholder alignment. Yet the same tools raise the bar for competency, requiring firms to upskill teams, standardize data pipelines, and integrate software ecosystems across architects, engineers, and owners. The report maps these technology adoption patterns, highlighting where software capabilities translate into competitive differentiation and where integration gaps create execution risk.
What the Report Delivers: Operational Intelligence for 2026 Strategy
This Worldwide Office Building Design Market study is designed for practitioners who need more than top-line figures. It offers an operational lens on how market structure, competitive behavior, regulatory mandates, and technology trends intersect to shape deal flow, pricing, and project delivery.
The report examines demand drivers across major geographies, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, situating each region within its own regulatory cadence, urbanization patterns, and corporate real estate priorities. It allocates market value across design service categories—architectural design, interior design, structural engineering, and landscape and urban planning—and across project categories spanning new construction and renovation or retrofitting. Rather than presenting these splits as static percentages, the analysis interprets them as strategic signals: where client budgets are migrating, which service lines face capacity constraints, and how renovation activity competes with new builds for design resources.
Worldwide Office Building Design Market
In addition, the report profiles the competitive set with granular detail on firm capabilities, recent project completions, partnership announcements, awards, and software releases. This temporal view of recent developments enables readers to identify momentum patterns— Which firms are scaling hybrid workplace delivery? Which are embedding AI into design workflows? Which are distinguishing themselves through net-zero performance or WELL certification? Such signals matter for procurement teams evaluating design partners, for firms benchmarking their own pipeline strategy, and for investors assessing where value is concentrating.
The analysis also translates regulatory and labor dynamics into practical implications. It connects WELL v2 verification requirements to commissioning and post-occupancy evaluation; links EPBD near-zero standards to envelope design and mechanical system selection; and correlates LEED v5 social equity credits with site planning and community engagement. By tying compliance obligations to design decisions and cost structures, the report equips teams to plan for verification, budget for specialized labor, and sequence design activities to avoid late-stage rework.
Technology adoption is treated with the same operational rigor. The report evaluates how generative design tools, BIM collaboration platforms, and digital twin capabilities influence space utilization, sustainability metrics, and interdisciplinary coordination. It identifies where software investments yield measurable returns in design quality and schedule compression, and where fragmented toolchains create interoperability friction. For firms evaluating platform strategies or clients specifying delivery requirements, this technology mapping clarifies where standards adoption, data continuity, and workforce training will determine project success.
Strategic Implications for 2026 and Beyond
For corporate real estate leaders, the market's trajectory through 2032 presents a mandate to reevaluate workplace strategy as a core business capability. The convergence of hybrid work patterns, sustainability mandates, and wellness certification expectations means office design is no longer a one-time capital project but an ongoing program of spatial optimization, performance verification, and employee experience management. Firms that integrate design strategy with occupancy analytics, post-occupancy evaluation, and flexible lease structures will be better positioned to align real estate portfolios with evolving organizational needs.
For design firms and consultancies, the fragmented competitive landscape offers room to differentiate through specialization, regional depth, and technology-enhanced delivery. The growth rate and market size trajectory indicate sustained demand, but profit pools will increasingly reward firms that can demonstrate performance outcomes, integrate software tools into repeatable workflows, and navigate regulatory verification with minimal client friction. Firms that invest in BIM competency, generative design, and sustainability analytics will be better equipped to absorb labor cost inflation while maintaining margin integrity.
For technology providers, the market underscores the strategic importance of interoperability, data continuity, and user-centric tooling. Revit, OpenBuildings, and Archicad ecosystems are not merely production tools; they are coordination layers that shape how multidisciplinary teams collaborate, how performance is simulated, and how compliance is documented. Enhancements in generative layout optimization, openBIM workflows, and digital twin integration directly influence design quality and project outcomes, making platform strategy a competitive variable rather than a back-office consideration.
Access the Full Intelligence
The Worldwide Office Building Design Market research synthesizes historical performance, forward-looking forecasts, competitive profiling, regulatory and labor dynamics, and technology adoption patterns into a single strategic reference. The executive summary and market overview presented here capture the contours of a market growing from approximately 42.5 billion USD in the base year toward more than 58.4 billion USD by 2032, with a compound annual growth rate of 4.65 percent and a competitive landscape that remains broadly fragmented. Yet the true operational value lies in the detailed segmentation, regional analysis, firm-level profiles, and regulatory-technology implications that enable precise strategic planning.
To access the complete dataset, segmentation breakdowns, competitive assessments, and region-specific demand drivers, visit the full report page. The comprehensive study provides the depth required to inform 2026 capital allocation, design partner selection, service portfolio strategy, and technology investment decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Office Building Design Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Dienogest Market Hits $532M in 2025, Projected to Reach $882.61M by 2032; Endometriosis Treatment Leads
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Horizon: Inside the Worldwide Dienogest Market Research 2026–2032
Decision-makers in women’s health, specialty pharmaceuticals, and global market access face a pivotal moment. Over the past half-decade, dienogest has transitioned from a niche hormonal therapy to a cornerstone treatment for endometriosis, while simultaneously anchoring a growing segment of contraceptive and combined formulations. The release of our Worldwide Dienogest Market study is designed to convert this complexity into executable strategy for the 2026 planning cycle and beyond. Rather than offering static snapshots, this research maps the structural shifts, competitive fault lines, and regulatory inflection points that will determine share, margin, and market access over the next seven years.
A Market in Transition: Baseline Velocity and Directional Signals
Drawing on a comprehensive historical reconstruction and a forward-looking forecast window spanning 2026 to 2032, the analysis places the global market on a clear upward trajectory. Base-year revenue for 2025 is positioned at 532.0 million USD, reflecting sustained adoption across established therapeutic indications and expanding access in high-prevalence regions. From this anchor point, the market is projected to advance at a compound annual growth rate of 7.51 percent, culminating in a 2032 revenue threshold of 882.61 million USD. This growth curve is not merely a function of prescription volume; it is the product of converging forces: patent expirations unlocking generic supply, reimbursement frameworks stabilizing patient access in core European markets, and deliberate portfolio expansion by both originator and generic manufacturers.
The narrative arc from 2020 through 2025 already illustrates the acceleration pattern that decision-makers must internalize. Sequential year-over-year expansion moved from 385.4 million USD in 2020 to 532.0 million USD in 2025, signaling that dienogest-based therapies have secured durable positioning in treatment algorithms where endometriosis management demands long-term, tolerable hormonal suppression. Looking ahead, the forecast band maintains momentum through 2027 and 2028, with returns expected to compound more steeply as generic penetration matures and emerging-market distribution networks strengthen. For strategy teams, the practical implication is straightforward: growth is real, but it will be captured by players who align supply strategy, pricing architecture, and market-access positioning with the timing of regulatory and competitive shifts rather than by those who rely on legacy volume assumptions.
Worldwide Dienogest Market
Worldwide Danazol Market
What the Study Delivers: Operational Intelligence, Not Just Headlines
Our methodology is built around actionable deliverables. The report dissects the commercial ecosystem across product type, therapeutic application, and regional demand architecture, then ties each dimension to the operational decisions that shape performance. Readers will find a granular assessment of how tablet-based monotherapy and combined formulations occupy distinct value positions in physician prescribing behavior, reimbursement logic, and patient adherence profiles. The analysis connects these product dynamics to application-level demand, clarifying how endometriosis treatment continues to function as the dominant volume driver while contraceptive and combined-use pathways contribute differentiated margin and formulation opportunities.
Equally important, the research translates market structure into execution-ready frameworks. The segmentation architecture is paired with a competitive intensity model that evaluates concentration, pricing behavior, and entry timing. By examining market concentration through a consolidated lens, the study highlights how a relatively small group of multinational and specialized generic manufacturers command the majority of share, while a broader field of regional suppliers competes on distribution reach, local market access, and formulation agility. This is not a theoretical exercise; it is a practical map for assessing where competitive pressure will intensify, where pricing endurance will be tested, and where partnership or licensing strategies can create durable positioning.
To support planning teams, the report also integrates supply-side realities that often remain siloed from commercial strategy. It examines the manufacturing geography that underpins active pharmaceutical ingredient flow, the logistics corridors that determine time-to-market for generic entries, and the procurement patterns that influence cost structures across markets. These operational layers are essential for anyone evaluating launch sequencing, inventory strategy, or the economics of entering markets where dienogest is already established versus markets where awareness and access are still building.
Competitive Architecture: Originator Positioning and the Generic Wave
The competitive landscape is defined by a clear structural split between the originator franchise and the expanding generic field. Bayer AG remains the reference point for dienogest-based endometriosis therapy through its Visanne portfolio, marketed internationally outside the United States. The company’s positioning reflects decades of clinical familiarity, established physician trust, and a brand architecture that has shaped treatment norms across multiple regions. Yet the strategic context around this franchise has changed materially. Patent protection in key European markets expired across 2022 and 2023, opening the door to a wave of generic entrants and fundamentally altering the pricing and share dynamics that had previously supported premium positioning.
The generic cohort now includes a dense field of capable manufacturers. Teva Pharmaceutical Industries Ltd. captured an early mover advantage by launching generic dienogest 2mg tablets in Germany following patent expiry, a move that signaled both the timing and the commercial seriousness of the generic wave. Mylan N.V., operating under Viatris, has extended generic dienogest formulations for endometriosis across multiple global markets, reinforcing the shift from single-source supply to a multi-channel competitive environment. Sun Pharmaceutical Industries Ltd. and Dr. Reddy’s Laboratories Ltd. have built substantial international supply footprints, with Sun Pharmaceutical explicitly expanding generic dienogest availability into Southeast Asian markets through new partnerships and Dr. Reddy’s continuing global production and export of generic formulations for endometriosis treatment. Zydus Lifesciences, formerly Zydus Cadila, rounds out the field with generic dienogest 2mg tablets available across both emerging and developed markets, while Perrigo Company plc provides additional generic coverage in select international markets.
This competitive mix matters because the market is no longer governed by a single pricing anchor. Instead, it is shaped by the interaction between originator brand equity, generic price erosion, tender dynamics, and the speed at which local distributors and market-access teams can convert regulatory approval into realized volume. Recent developments illustrate the pace of change: a generic launch in Germany after patent expiry, expanded approval activity for additional generic versions across EU member states, and deliberate supply expansion into Southeast Asia. Each event is a signal that the market’s center of gravity is moving from exclusivity-driven pricing to access-driven competition. Our study maps these events against a forward competitive model so that readers can anticipate where share shifts are most likely to occur and how pricing resilience should be structured.
Market Dynamics: Regulation, Access, Supply, and Geographic Realities
No dienogest strategy is complete without confronting the regulatory and access realities that shape commercial feasibility. The therapy enjoys approval in more than 100 countries for endometriosis, yet its market architecture is uneven. In the United States, dienogest monotherapy is not FDA-approved for the endometriosis indication, creating a structural divergence between global demand patterns and US market availability. In that context, dienogest appears in combination with estradiol in an oral contraceptive formulation, illustrating how regulatory pathways can redirect product positioning rather than eliminate therapeutic relevance. This divergence is a critical lens for any organization evaluating cross-market expansion, licensing, or partnership opportunities, because the same molecule can function as a specialty therapy in one region and a combined contraceptive component in another.
Reimbursement and pricing access are equally decisive. In Germany, both the originator and generic offerings are reimbursed under statutory health insurance for endometriosis, with monthly pack pricing positioned in the €25–30 range. This reimbursement architecture supports patient continuity and stabilizes demand, but it also imposes pricing discipline that generic entrants must navigate carefully. The existence of reimbursement does not automatically translate into uniform market capture; it creates a structured environment where procurement channels, health-system relationships, and formulary positioning determine how volume is distributed among competing products. For strategy teams, the practical challenge is to model not just approval status but the path to realized access within each health system.
Supply-side dynamics further complicate the picture. The active pharmaceutical ingredient for dienogest is primarily sourced from Indian manufacturers, with export volumes to Europe exceeding 500 kilograms annually. This dependency creates both opportunity and vulnerability. On one hand, it supports a scalable generic supply base that can respond to demand growth and multi-market launches. On the other hand, it concentrates a critical portion of the value chain in a limited set of manufacturing geographies, making supply continuity, quality assurance, and logistics resilience central to commercial execution. Organizations that treat supply chain design as a strategic variable rather than an operational afterthought will be better positioned to manage launch timing, cost control, and market reliability.
Why This Research Matters for 2026 Decision-Making
The 2026 decision environment is defined by timing. Patent-driven exclusivity has given way to a multi-player competitive field, reimbursement pathways are stabilizing in core markets, and supply networks are expanding into higher-growth regions. In this environment, organizations need more than a market size figure; they need a framework for interpreting where value will accrue and what levers will determine outcomes. The Worldwide Dienogest Market study is built to provide that framework. It equips teams to evaluate pipeline and portfolio decisions against realistic share trajectories, to assess pricing and market-access strategies in light of reimbursement and generic pressure, and to align supply and distribution plans with the geographies and channels that will shape demand over the forecast period.
For commercial leaders, the research clarifies where brand equity still commands premium positioning and where generic competition will compress margins and accelerate switching. For market-access and policy teams, it provides the context needed to understand how approval status, reimbursement design, and health-system procurement interact to create or constrain commercial opportunity. For supply chain and manufacturing strategy, it connects API sourcing patterns and export flows to the practical requirements of multi-market launch execution. Taken together, these insights support a more disciplined approach to budgeting, launch sequencing, and partnership selection in a market where decisive timing can separate durable positioning from reactive catch-up.
What Remains Inside the Full Study
The analysis presented here is intended as a professional preview: a demonstration of the strategic depth, structural clarity, and operational relevance that define the full report. The complete study goes further. It breaks down regional demand architecture, product-type value distribution, and application-level commercial logic with the precision required for planning, forecasting, and negotiation. It also maps the competitive field in greater detail, integrating company profiles, recent development timelines, and market-concentration signals into a coherent view of where incumbents, generic challengers, and regional suppliers are positioned to win or lose share.
Readers who need the underlying segmentation values, regional revenue architecture, and formulation-level demand splits will find them inside the full report, along with the interpretive frameworks that translate those figures into decision-ready intelligence. The goal of this preview is not to replace that depth but to show why it matters and how it connects to the strategic questions that 2026 planning teams must answer now. For organizations that treat dienogest as a therapeutic category, a market opportunity, or a competitive battleground, the full Worldwide Dienogest Market research provides the structured intelligence required to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Worldwide Dienogest Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Smart Antimicrobial Surface Market to Hit $3.697B by 2032, CAGR 12.0%
By pmarketresearch, 2026-09-16
Global Smart Antimicrobial Surface Market 2026-2032: Strategic Intelligence for Market Leadership
The global landscape for infection control is undergoing a fundamental structural shift. No longer confined to passive hygiene protocols, the market is moving decisively toward active, engineered surface technologies designed to disrupt microbial adhesion, biofilm formation, and pathogen transmission across high-touch environments. For C-suite executives, R&D leaders, and commercial strategy teams, understanding the trajectory of the smart antimicrobial surface market is no longer optional. It is a core determinant of competitiveness, regulatory readiness, and long-term margin protection.
PW Consulting’s newly released Worldwide Smart Antimicrobial Surface Market research report delivers exactly that intelligence. Spanning historical validation from 2020 through baseline year 2025, and projecting a rigorous forecast window from 2026 to 2032, this study equips decision-makers with a comprehensive, data-grounded view of market scale, technology adoption curves, competitive positioning, and the regulatory-commercial dynamics shaping the next seven years.
Market Scale, Growth Trajectory, and Strategic Context
The smart antimicrobial surface market has demonstrated consistent, structurally driven expansion. Revenue climbed from $980.5 million in 2020 to $1,672.4 million in 2025, reflecting an accelerating adoption cycle fueled by heightened institutional focus on infection prevention, the proliferation of high-touch public and clinical environments, and material science breakthroughs that have moved antimicrobial functionality from additive afterthoughts to integrated surface architectures.
Forecasts point to sustained momentum. The market is projected to reach $1,896.39 million in 2026 and continue its upward trajectory, ultimately approaching $3,697.14 million by 2032. With a compound annual growth rate of 12.0 percent across the 2026-2032 forecast horizon, growth will be driven by simultaneous expansion across multiple application verticals, technology substitution dynamics, and geographic penetration in both mature and emerging regions. This growth rate signals more than incremental demand. It reflects a structural realignment in how industries approach surface-mediated infection risk.
For corporate strategists, the 12 percent CAGR frames a clear reality. Companies that delay market entry, licensing partnerships, or portfolio integration risk ceding share to faster-moving players and vertically integrated technology providers. Conversely, organizations that align their product roadmaps, supply chain capacity, and commercialization strategies with the market’s expansion curve can capture premium positioning across healthcare, consumer, infrastructure, and industrial segments.
Technology Diversification: The Core Value Drivers
The market’s evolution is not monolithic. It is defined by a widening spectrum of material platforms and active mechanisms, each with distinct efficacy profiles, manufacturing requirements, regulatory pathways, and total cost structures. The report provides a granular breakdown of these technology families, analyzing how each is shaping demand, performance expectations, and competitive differentiation.
Silver-based responsive coatings continue to anchor a significant share of the market, particularly in healthcare facility applications where broad-spectrum activity against gram-positive and gram-negative bacteria and viruses is essential. These formulations benefit from established clinical familiarity and transparent, abrasion-resistant delivery formats suitable for high-touch door handles, handrails, and medical tools. Copper-based active surfaces represent another established pillar, leveraging inherent antimicrobial properties for surface integration across both clinical and public infrastructure contexts.
Polymer-based smart surfaces are expanding rapidly as manufacturers seek conformal, durable, and chemically stable integration options. These technologies are increasingly paired with hydrophilic or thromboresistant formulations, enabling dual-function performance on medical devices and implantable surfaces. Meanwhile, bio-based and enzymatic smart surfaces are emerging as a differentiating category for organizations targeting sustainability-aligned product design, non-leaching contact-kill mechanisms, and long-duration performance without continuous active release.
A critical insight for procurement leaders and product developers is that technology selection is no longer purely a performance equation. It is a strategic decision involving regulatory classification, biocompatibility documentation, abrasion and chemical resistance requirements, manufacturing scalability, and total cost of ownership. The report dissects these trade-offs in detail, enabling teams to evaluate not just which technology is currently dominant, but which is structurally positioned to capture share as performance thresholds rise and regulatory frameworks evolve.
Application Expansion Across Verticals
Demand is dispersing across a broad and growing set of end-use applications. Healthcare and medical devices remain the central anchor of market activity, driven by persistent pressure to reduce healthcare-associated infections, strengthen device-level protection, and integrate antimicrobial functionality into both implantable and non-implantable products. Vascular access devices, wound care platforms, catheters, surgical instruments, and high-touch clinical surfaces continue to represent high-value adoption environments.
Food and beverage packaging is another expanding vertical, where antimicrobial surface integration intersects with shelf-life optimization, regulatory expectations, and consumer safety demands. Public infrastructure and transport applications are gaining traction as municipalities, transit authorities, and building operators invest in durable, high-contact surface protection for handrails, touchpoints, and shared environments. Consumer electronics and ancillary application segments are also contributing incremental growth, particularly where device intimacy, hygiene awareness, and surface-touch frequency elevate user expectations.
Importantly, the report emphasizes that application expansion is not uniform. Adoption velocity varies significantly by region, by procurement cycle, by infection-control policy mandates, and by the availability of validated, biocompatible, and scaled manufacturing pathways. By mapping these adoption drivers and barriers across segments, the study provides leaders with a practical framework for prioritizing commercialization focus and aligning go-to-market investment with the highest-probability opportunities.
Worldwide Smart Antimicrobial Surface Market
Competitive Landscape and Strategic Positioning
The competitive arena is defined by a combination of material-science specialists, medical device coating suppliers, and technology developers pursuing differentiated performance through non-leaching contact-kill mechanisms, covalent surface binding, galvanic metal effects, and polymer-integrated antimicrobial architectures. Market concentration reflects an environment where leading players command meaningful share while still leaving substantial space for innovation-driven entrants and partnership-led scaling strategies.
HeiQ Materials AG has built a recognized position around silver-based, ready-to-use antimicrobial surface coatings engineered for high efficacy and transparent, biocompatible performance on high-touch surfaces in healthcare settings. Covalon Technologies Ltd. focuses on custom medical device coatings, including dual-antimicrobial silicone adhesive technologies for vascular access, wound care, and catheter applications. Hydromer, Inc. has strengthened its profile through hydrophilic, thromboresistant, and antimicrobial coating technologies, and has recently expanded into manufacturing and global supply of high-speed automated coating and UV cure equipment, integrating these capabilities directly with its antimicrobial platforms.
Specialty Coating Systems (SCS) offers conformal parylene-based antimicrobial coating technology designed to deliver substantial pathogen reduction across implantable and non-implantable medical devices. BioInteractions Ltd. has advanced the conversation around permanent, non-leaching, contact-kill surface-active technologies, underscoring the industry’s move toward long-duration implant and device protection without active release. Orthobond Corporation has moved covalently bound antimicrobial nanosurface technology into commercial delivery for spinal fusion devices, representing a notable milestone for non-eluting approaches on metallic and polymeric implant surfaces. SurModics, Inc. continues to supply performance coatings integrated with antimicrobial and infection-resistance properties within broader device and drug-delivery systems. Parx Materials N.V. is developing biocide-free passive action polymer technologies using zinc-based compounds to prevent bacterial adhesion and biofilm formation without releasing active substances, extending applicability across medical devices and textiles.
Recent corporate activity reinforces the strategic intensity of this space. Hydromer’s 2026 expansion into automated coating and UV cure equipment supply illustrates how antimicrobial leadership is increasingly tied to process technology, throughput, and global manufacturing readiness. BioInteractions’ 2025 launch of its surface-active systems category and Orthobond’s 2025 first-in-human commercial delivery of coated spinal implant components both signal that advanced antimicrobial surface technologies are crossing from development-stage promise into commercial deployment. The report analyzes these developments in context, helping readers distinguish between one-off announcements and durable competitive shifts.
Regulatory, Reimbursement, and Commercial Dynamics
No strategic assessment of this market is complete without confronting the regulatory and commercial environment. Antimicrobial surface technologies on medical devices must navigate rigorous biocompatibility expectations, including ISO 10993 standards, and in many jurisdictions may require EPA or ECHA registration pathways when public health or biocidal claims are made. The regulatory classification of non-leaching, contact-kill mechanisms is particularly important, as developers must demonstrate that these technologies do not function as drugs within or on the body while still delivering clinically meaningful surface protection.
A notable regulatory milestone in this space is the classification pathway for covalently bonded antimicrobial coating technologies on rigid metallic implant devices, designed to reduce pre-implantation microbial contamination on the device surface. Such determinations shape not only product development timelines but also the competitive entry barriers for new solutions.
Reimbursement dynamics add another layer of commercial complexity. As of 2026, there are no specific CPT or DRG reimbursement code updates identified exclusively for smart antimicrobial surface coatings on medical devices or hospital surfaces. This reality does not diminish the strategic value of antimicrobial surfaces; rather, it elevates the importance of value-based commercialization narratives. Hospital procurement, device OEM integration, infection prevention economics, and total cost-of-care arguments increasingly determine adoption, especially where direct reimbursement is not a primary pull-through mechanism.
Raw material and formulation considerations also play a decisive role. Silver-based technologies remain widely used in healthcare surface coatings due to broad-spectrum efficacy, but product architects must balance antimicrobial performance with controlled integration strategies to maintain biocompatibility and avoid excessive leaching. These engineering and regulatory trade-offs are central to long-term commercial viability and are examined in depth within the report.
What the Report Delivers for Strategic Decision-Makers
This study is designed to support concrete, time-sensitive decisions. It goes beyond aggregate market sizing to provide a multi-dimensional view of the smart antimicrobial surface ecosystem, enabling strategy, operations, and commercial teams to act with precision.
Inside the report, readers will find:
- Historical market sizing and forecast modeling covering the 2020-2032 period, with a clearly defined 2026-2032 forecast structure that supports scenario planning, capacity decisions, and investment prioritization.
- Technology segmentation analysis that compares material platforms, performance characteristics, and strategic implications across silver-based responsive coatings, copper-based active surfaces, polymer-based smart surfaces, and bio-based and enzymatic smart surfaces.
- Application-level insights across healthcare and medical devices, food and beverage packaging, public infrastructure and transport, consumer electronics, and other end-use segments, with a focus on adoption drivers, procurement dynamics, and segment-specific barriers.
- Geographic market distribution and regional opportunity mapping, enabling readers to assess where mature demand is concentrated and where expansion potential is accelerating.
- Competitive profiling of leading market participants, including technology positioning, product strategy, geographic footprint, and recent strategic developments.
- Analysis of regulatory, biocidal registration, biocompatibility, and reimbursement dynamics that influence product development timelines, market access, and commercialization strategy.
- Assessment of raw material considerations, manufacturing scalability, and process integration factors that affect cost structure, differentiation, and supply-chain resilience.
- Strategic implications for OEMs, coatings suppliers, device manufacturers, procurement leaders, and investors seeking to align portfolios with the market’s growth trajectory.
The report is structured to serve both strategic planning and tactical execution. Executive teams can use it to prioritize R&D investment, assess partnership and licensing opportunities, and refine geographic or segment entry timing. Commercial and marketing teams can leverage the segmentation and competitive analysis to sharpen value propositions and align messaging with the performance, regulatory, and procurement criteria that actually drive purchasing decisions. Operations and supply-chain leaders can use the technology and process insights to evaluate manufacturing readiness, material sourcing constraints, and scalability considerations that will determine long-term margin performance.
Why the 2026 Outlook Matters Now
The 2026 baseline is not an arbitrary checkpoint. It marks the point at which several concurrent forces are converging: increasing institutional investment in infection-control infrastructure, maturation of non-leaching and contact-kill surface technologies, expanding device-level integration requirements, and growing demand for durable antimicrobial performance across both clinical and public environments. Companies that treat antimicrobial surface capability as a strategic asset rather than a tactical feature will be better positioned to capture share in a market expanding at a sustained double-digit CAGR.
At the same time, the market’s growth is creating sharper competitive scrutiny. Differentiation now depends on validated efficacy, biocompatibility documentation, manufacturing reliability, regulatory navigation, and the ability to integrate antimicrobial functionality into broader product architectures without compromising device performance or usability. The report provides the structured intelligence needed to evaluate these variables and make informed decisions with confidence.
Access the Full Strategic Briefing
This article previews the scope, analytical depth, and decision-support orientation of PW Consulting’s Worldwide Smart Antimicrobial Surface Market research. It highlights the structural growth trajectory, technology diversification, application expansion, competitive intensity, and regulatory-commercial dynamics that define the market’s next phase. However, the complete intelligence required for precise market entry timing, segment prioritization, competitive benchmarking, and investment planning resides in the full report.
To access the detailed forecasts, segmentation breakdowns, competitive evaluations, regulatory context, and executive strategic recommendations, visit the source page for the full Worldwide Smart Antimicrobial Surface Market study. For leaders responsible for shaping product strategy, infection-control portfolios, device coating roadmaps, or commercial expansion plans, the complete dataset and analysis provide the evidence base needed to move decisively in 2026 and beyond.
Anti-Microbial Coatings Market
For detailed analysis of this topic, please visit the official page: Worldwide Smart Antimicrobial Surface Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Lens Measuring Device Market Hits $465.5M in 2025, Forecast 4.58% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Vision in Focus: Navigating the Worldwide Lens Measuring Device Market
The global ophthalmic equipment sector is undergoing a period of disciplined expansion, driven by aging demographics, rising prevalence of refractive errors, and the accelerating integration of digital workflows into clinical and retail environments. Within this broader ecosystem, lens measuring devices—commonly referred to as lensmeters or lensometers—represent a critical capital equipment category. These instruments serve as the backbone of accurate spectacle and contact lens verification, pricing, and quality control across optical retail, clinical practices, and manufacturing facilities.
As businesses plan their capital allocation, product roadmaps, and regional entry strategies for the 2026–2032 horizon, having access to rigorously validated market intelligence is no longer a luxury; it is a strategic necessity. Our latest research publication, the Worldwide Lens Measuring Device Market study, provides a comprehensive, data-driven framework for executives, investors, and procurement leaders to navigate this evolving landscape with precision.
Worldwide Lens Measuring Device Market
The Macro Trajectory: Growth Anchored in Structural Demand
The market has demonstrated steady, compounding growth over the past half-decade. Historical revenue tracking from 2020 through the base year of 2025 reveals a consistent upward trajectory, with total market valuation crossing the 465 million USD threshold by 2025. This momentum is projected to accelerate modestly but persistently through the end of the forecast period, reflecting sustained investment in ophthalmic infrastructure across mature and emerging economies alike.
Our forecasting models indicate a compound annual growth rate of approximately 4.58 percent across the 2026–2032 window. While the growth rate may appear measured at first glance, it reflects a mature yet resilient capital equipment category where incremental innovations in measurement accuracy, automation, and digital integration are steadily expanding total addressable demand. The projection underscores a market that is not experiencing speculative volatility, but rather structured, usage-driven expansion tied to clinical standardization and retail modernization.
Importantly, the revenue trajectory suggests that growth will not be uniformly distributed across all sub-segments or geographic corridors. Enterprises that map their strategic initiatives to the regions and application verticals exhibiting the strongest underlying demand drivers will be best positioned to capture disproportionate share. The full report decomposes these dynamics with granular regional and application-level analysis, providing the granularity needed to align distribution partnerships, pricing architecture, and localized compliance strategies.
What the Report Delivers: Operational Intelligence for Decision-Makers
This study is structured to move beyond high-level summaries and deliver actionable intelligence that can be directly integrated into corporate strategy, product planning, and market-entry evaluations. The report architecture is designed for cross-functional utility, serving strategy teams, engineering leadership, commercial directors, and procurement professionals alike.
Key analytical components include:
- Historical Revenue Reconstruction and Baseline Calibration: A year-by-year analysis from 2020 through 2025 that establishes accurate baselines, corrects for reporting inconsistencies, and isolates underlying demand trends from short-term promotional or supply-chain fluctuations.
- Forward-Looking Revenue Modeling (2026–2032): Scenario-based projections that account for macroeconomic variables, regulatory pacing, and technology adoption curves, providing a realistic range of outcomes rather than a single-point estimate.
- Segment-Level Demand Mapping: Comprehensive breakdowns across device type, end-use application, and regional distribution. Each segment is evaluated for growth velocity, pricing dynamics, and adoption barriers, enabling targeted resource allocation.
- Competitive Positioning and Company Profiling: In-depth assessments of leading manufacturers, including product portfolio architecture, technological differentiators, regional footprint, and strategic focus areas.
- Regulatory, Reimbursement, and Procurement Context: Analysis of how classification frameworks, quality management requirements, and bundled reimbursement structures influence purchasing behavior, product design priorities, and sales cycle timelines.
- Market Concentration and Share Dynamics: Evaluation of how revenue is distributed across the competitive landscape, highlighting the scale advantages of established players and the positioning strategies of emerging entrants.
- Technology and Workflow Integration Trends: Examination of how digital interfaces, wavefront sensing, UV and blue-light measurement capabilities, and integration into broader vision exam suites are shaping procurement requirements and end-user expectations.
Each section is written to support concrete decision-making. Whether you are evaluating a potential acquisition target, planning a product refresh cycle, assessing distributor partnerships, or benchmarking your market position against global peers, the report provides the evidentiary foundation required to reduce uncertainty and accelerate execution.
Competitive Landscape: Established Incumbents and Technology-Driven Positioning
The global lens measuring device market features a diverse cohort of manufacturers spanning Europe, East Asia, and North America. Competitive differentiation is increasingly anchored in measurement precision, automation levels, and compatibility with digital clinical workflows rather than price competition alone. Several key companies illustrate the strategic contours of this landscape.
Carl Zeiss Meditec AG, headquartered in Jena, Germany, continues to reinforce its position through advanced optical instrumentation, exemplified by the VISULENS 550 digital lensmeter. The device leverages wavefront technology and an integrated UV spectrometer to deliver precise measurement of both spectacle and contact lenses, including detailed UV protection analysis. This emphasis on diagnostic-grade accuracy and multi-parameter measurement aligns with clinical buyers who prioritize equipment that enhances exam suite efficiency and patient counseling capabilities.
In Japan, Topcon Corporation and NIDEK Co., Ltd. represent two of the most recognized names in ophthalmic instrumentation. Topcon offers a broad spectrum of solutions, from manual lensmeters such as the LM-8/8E series, which utilize LED illumination for reliable power verification, to computerized models like the CL-300 and SOLOS automated lens analyzer. These platforms deliver accurate lens power, progressive lens, and UV measurements, supporting both independent practices and larger optical networks. NIDEK complements this landscape with automated lensmeters such as the LM-1800PD/1800P and LM-7P/7 series, which employ Hartmann sensor technology with 108 measurement points to achieve high-accuracy lens verification. The inclusion of pupillary distance and UV measurement features further broadens their utility across clinical and retail settings.
Reichert Technologies, operating under AMETEK and based in Buffalo, New York, has built strong recognition around the LensChek Pro and LensChek Plus digital lensometers. These instruments are designed with intuitive interfaces and built-in PD/UV measurement capabilities, supporting a wide range of lens types as part of the broader VisionChek Digital Exam Suite. By embedding lens measurement into integrated exam workflows, Reichert addresses a growing institutional preference for equipment that reduces manual steps and standardizes measurement protocols across multiple sites.
Marco Ophthalmic, Inc., headquartered in Jacksonville, Florida, offers the LM-7/7P and LM-1800/1800PD automated lensmeters, often in partnership with NIDEK, alongside the LM-101 manual lensmeter. This portfolio strategy provides flexibility for buyers seeking both automated throughput and manual verification options, catering to a wide range of practice sizes and operational models. Huvitz Co., Ltd., based in Anyang, South Korea, has expanded its presence with the HLM-9000 premium auto lensmeter, which includes blue light and UV measurement capabilities, the HLM-7000P standard model, and the HLM-1 basic wavefront-based lensmeter. Huvitz’s product ladder illustrates a deliberate approach to serving multiple price-performance tiers while maintaining consistent measurement reliability.
Additional contributors to the competitive field include Keeler Ltd. in Windsor, United Kingdom, which supplies lensmeters within its broader ophthalmic diagnostic portfolio with a focus on dependable lens power verification for optometry practices. Oculus Optikgeräte GmbH, located in Wetzlar, Germany, provides lens measuring devices integrated into its optometry equipment lineup, emphasizing clinical lens analysis within a cohesive diagnostic ecosystem. Takagi Seiko Co., Ltd., based in Nakano, Japan, offers lensmeters within its wider range of ophthalmic instruments, targeting eye care settings that require accurate measurement as part of routine clinical operations.
The market structure reflects meaningful concentration at the top tier. Aggregate revenue is distributed such that a relatively small group of leading manufacturers commands a substantial share of total market value, while a longer tail of specialized and regional providers competes on service, distribution reach, and segment-specific features. Understanding the precise share distribution, brand loyalty dynamics, and substitution patterns across tiers is essential for any company evaluating partnership opportunities, competitive threats, or market entry feasibility. The complete report maps these concentration patterns in detail.
Market Dynamics: Regulation, Reimbursement, and Capital Equipment Behavior
The commercial environment for lens measuring devices is shaped by several interrelated forces that influence both product development priorities and purchasing behavior. Regulatory classification plays a foundational role. In the United States, lens measuring devices such as lensmeters are generally classified as Class II medical devices under FDA regulations, requiring 510(k) clearance for marketing. This regulatory pathway creates a structured barrier to entry that rewards manufacturers with established compliance infrastructure and disciplined product reporting, while also shaping the pace at which new features can be introduced and commercialized.
Beyond regulatory clearance, quality management expectations further influence competitive dynamics. Ophthalmic diagnostic equipment, including lensmeters, must typically comply with ISO 13485 quality management systems for medical devices. Adherence to these standards affects manufacturing consistency, supplier qualification, and the credibility of manufacturers seeking to serve hospital systems, regulated retail chains, and institutional buyers who integrate device quality into vendor selection criteria.
Laser Distance Measuring Devices Market
On the procurement side, lensmeters function as capital equipment within optometry and ophthalmology practices. Hospital and clinic capital expenditure budgets increasingly prioritize equipment that integrates into digital exam suites, reflecting a broader institutional push toward workflow efficiency, data capture standardization, and reduced manual handling. Devices that offer seamless data transfer, intuitive operator interfaces, and compatibility with existing practice management or electronic health record environments are therefore gaining preferential consideration during purchasing cycles.
Reimbursement structures also shape end-user demand, though indirectly. Lens measurement procedures performed during eye exams are typically bundled into routine vision or refraction CPT codes rather than carrying dedicated device-specific reimbursement codes. This bundling means that procurement decisions are driven less by direct device reimbursement and more by overall practice efficiency, throughput, accuracy, and patient experience. Manufacturers that can demonstrate how their instruments reduce measurement time, minimize remakes, or improve spectacle and contact lens fitting accuracy are better aligned with how eye care providers evaluate return on investment.
Recent industry activity reinforces the momentum around automation and feature integration. For example, in September 2025, Visionix USA debuted the VX 40 Couture auto lensmeter at Vision Expo West, highlighting advanced automated lens analysis capabilities. Product launches of this nature signal that competition is intensifying around measurement speed, parameter depth, and presentation of results in formats that support both clinical decision-making and retail customer engagement.
Strategic Implications for 2026 and Beyond
For executives planning their 2026 agendas, the lens measuring device market offers a clear but nuanced set of strategic implications. First, the steady growth trajectory suggests that demand will remain resilient, but competitive advantage will accrue to organizations that align product capabilities with the operational priorities of their target buyers. Automated measurement, multi-parameter analysis, and workflow integration are not merely technical specifications; they are purchasing criteria that reflect how eye care providers and optical retailers measure efficiency and service quality.
Second, the regulatory and quality management environment means that compliance readiness and manufacturing consistency are strategic assets. Companies entering new geographies or expanding into regulated institutional channels should evaluate certification pathways, local registration requirements, and quality system compatibility before finalizing go-to-market plans. A disciplined regulatory strategy can reduce launch delays and strengthen credibility with procurement teams.
Third, market concentration indicates that scale, brand recognition, and established distribution relationships continue to matter. At the same time, segmentation data suggests that differentiated positioning remains viable, particularly for manufacturers that can serve specific application verticals or regional demand pockets with tailored product configurations, support models, and pricing structures. Detailed segment analysis is essential for identifying where such positioning can be most effective.
Finally, reimbursement bundling and capital equipment purchasing behavior underscore the importance of demonstrating operational value. Sales narratives, training programs, and service offerings should be designed around how a device improves measurement consistency, speeds patient or customer throughput, and integrates with broader digital workflows. In a category where direct device reimbursement is not the primary purchasing driver, total value proposition becomes the critical differentiator.
Accessing the Complete Intelligence
The Worldwide Lens Measuring Device Market study is designed to provide the depth, structure, and forward-looking modeling that senior decision-makers require. It combines historical calibration, multi-year forecasting, segment-level demand mapping, competitive profiling, and regulatory and procurement context into a single cohesive analytical framework. For organizations evaluating product strategy, market entry, partnership selection, or capital allocation, the report offers a rigorous basis for reducing uncertainty and sharpening execution.
To explore the full segmentation breakdowns, regional demand profiles, company-level assessments, and detailed forecast tables, visit the source webpage where the complete report and associated data modules are available. The full intelligence package provides the granular visibility required to translate market dynamics into precise, defensible strategic decisions for 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Lens Measuring Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Custom Gene Synthesis Market Hits $3.15B in 2025, Projected to Reach $9.47B by 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave in Custom Gene Synthesis: Strategic Intelligence for 2026 and Beyond
The global custom gene synthesis service market stands at a critical inflection point. With a reported valuation of approximately USD 3,150 million in the base year of 2025 and a projected expansion to over USD 9,465 million by 2032, the sector is experiencing a compound annual growth rate of 17.02 percent. These figures signal more than incremental progress. They reflect a structural acceleration in how life sciences organizations design, validate, and deploy synthetic nucleic acids across research, translational development, and increasingly, clinical manufacturing. For executives, investors, and R&D leaders, the ability to interpret this trajectory with precision is no longer optional. It is a core component of portfolio planning, vendor selection, and risk-managed growth.
PW Consulting’s newly released Worldwide Custom Gene Synthesis Service Market study offers a comprehensive, decision-ready view of this rapidly evolving landscape. Designed as an operational intelligence resource rather than a static market summary, the report maps historical performance from 2020 through 2025 and extends a disciplined forecast through 2032. The analysis situates macro growth within the operational realities that shape procurement cycles, capacity commitments, service-level expectations, and competitive positioning.
Why This Research Matters for 2026 Decision-Making
As organizations move from exploratory synthetic biology programs into scaled therapeutic, diagnostic, and industrial applications, the cost-of-error in supplier selection and capacity planning rises sharply. The difference between a service partner that delivers reliable, NGS-verified clonal constructs and one that introduces sequence failures, turnaround variability, or compliance bottlenecks can cascade into delayed preclinical milestones, budget overruns, and reputational exposure. The current market environment amplifies these stakes. Rapid service innovations, regulatory tightening around sequence screening, and consolidation-driven capability upgrades are reshaping what buyers should prioritize when evaluating gene synthesis providers.
This study is built to translate market momentum into executable strategy. It examines how demand patterns are shifting across end-user segments, how service-type preferences are evolving as projects grow in sequence complexity, and how regional capabilities are aligning with localized regulatory and manufacturing expectations. By anchoring discussion in verified commercial behavior rather than speculative projections, the report equips leadership teams to calibrate investment timing, negotiate service agreements with greater confidence, and anticipate the operational implications of new compliance frameworks.
Equally important, the analysis recognizes that gene synthesis is no longer a commoditized utility. It is becoming a differentiated enabler of speed, accuracy, and biological functionality. From codon optimization and vector design to rapid gene-to-plasmid delivery and large-scale construct generation, service capabilities increasingly influence downstream success in protein production, functional genomics, and therapeutic development. Understanding where capabilities are converging, where differentiation remains defensible, and where pricing pressure is most intense is essential for any organization that depends on synthetic DNA as a core input.
What the Report Delivers: A Practical, Execution-Focused View
The study provides a structured, multi-dimensional assessment of the worldwide custom gene synthesis service market. Rather than presenting high-level trends in isolation, it ties market sizing to the operational and commercial variables that actually drive outcomes. Key areas of coverage include:
-
Historical and Forecast Trajectory
The report traces market development from 2020 through the 2025 base year and projects forward through 2032, providing a continuous view of growth momentum. This longitudinal perspective helps readers distinguish cyclical fluctuations from durable structural expansion and identify the demand signals most relevant to near-term planning.
-
Service-Type Segmentation in Operational Context
Custom gene synthesis is not a single product category. The analysis examines how standard gene synthesis, complex and large gene synthesis, and custom DNA libraries each serve distinct project requirements, lead-time expectations, and precision thresholds. This framing helps organizations match service portfolios to real-world application needs rather than relying on broad market averages.
Gene Synthesis Market -
End-User Demand Architecture
The study evaluates how biopharmaceutical companies, academic and research institutes, diagnostic centers, and contract research organizations shape procurement behavior, volume concentration, and service expectations. Understanding these demand profiles is central to forecasting where growth will materialize fastest and which customer segments will drive the most consequential capability requirements.
-
Regional Capability Mapping
The report assesses how major geographic markets are positioning themselves across supply, expertise, and compliance readiness. Regional analysis is presented as a strategic lens for sourcing strategy, capacity diversification, and regulatory alignment rather than as a simple ranking of market share.
Worldwide Custom Gene Synthesis Service Market -
Competitive Benchmarking and Strategic Positioning
A detailed review of leading service providers highlights differences in turnaround models, sequence complexity handling, vector and cloning support, codon optimization capabilities, and quality verification practices. This competitive layer supports vendor evaluation, partnership planning, and long-term capability roadmapping.
-
Regulatory and Biosecurity Context
The study integrates the evolving compliance environment into market interpretation, including screening expectations, quality standards, and the operational burden they place on providers and buyers alike. This dimension is increasingly decisive in procurement decisions, especially for organizations connected to federally funded research or clinical-stage programs.
Competitive Landscape: Capability, Speed, and Differentiation at Scale
The custom gene synthesis market features a diverse set of established providers and specialized entrants, each pursuing distinct value propositions around speed, accuracy, complexity handling, and application breadth. PW Consulting’s analysis evaluates these players through the lens of operational execution and strategic positioning, highlighting how service design is becoming a competitive moat.
Several globally recognized providers anchor the market with broad service portfolios and differentiated throughput models. One major East Asia-rooted global provider has emphasized rapid gene-to-plasmid turnaround alongside premium offerings for complex sequences extending to substantial lengths, paired with extensive codon optimization and high-accuracy synthesis for both research and therapeutic applications. A prominent silicon-based synthesis specialist has built its position on high-throughput DNA production, expedited clonal gene services for sequences up to defined size thresholds, and large-scale support for synthetic biology and biopharmaceutical programs. Another long-standing nucleic acid supplier has focused on NGS-verified clonal DNA in standard vectors, enhanced gene synthesis workflows for research requirements, rapid gene options, and gene fragment solutions designed for accuracy and quick delivery.
Large instrumentation and life sciences conglomerates also play a meaningful role. Through dedicated synthetic biology platforms, one global leader supplies optimized synthetic genes, gene libraries, and cloning solutions that span research and industrial use cases. In parallel, regionally anchored and specialty providers continue to expand the competitive field by addressing nuanced customer needs. These include providers with strong emphasis on complex sequences characterized by high GC content or repetitive regions, full subcloning support, and high-quality DNA constructs for both research and commercial applications. Others compete on expedited turnaround, high completion reliability, and priority shipping pathways that appeal to time-sensitive R&D and CRO workflows.
Additional participants extend the market’s functional range. Some providers bundle custom gene synthesis with mRNA and protein synthesis capabilities, offering integrated workflows and accessible codon optimization tools for synthetic biology projects. Cost-conscious research buyers often evaluate providers that combine affordability with quick turnaround, cloning support, and recombinant expression services. Others differentiate through protein design optimization, ORF clone and expression vector portfolios, or precision-focused guarantees tied to sequence accuracy and ready-to-use delivery. Across this landscape, the strategic question for buyers is not simply who offers the lowest price, but which provider’s capabilities best match the complexity, compliance, and timeline requirements of each program.
Recent corporate activity reinforces the market’s consolidation-and-capability dynamic. Provider announcements in 2024 and 2025 reflect a push toward faster delivery models, regional expansion, and GMP-aligned manufacturing capacity. Notable moves include the introduction of accelerated gene-to-plasmid services, expansion into new facilities designed for high-quality synthetic DNA and RNA production, and targeted acquisitions intended to strengthen regional presence and technical capabilities. In parallel, certification and product milestones among specialty providers indicate growing attention to clinical-grade readiness and improved DNA production technologies for genetic medicine applications. These developments matter because they reshape supply reliability, service tier availability, and the compliance posture of the provider base.
Market Dynamics: Growth Drivers, Regulatory Pressure, and Strategic Risk
Several interrelated forces are propelling the market’s expansion. The broader adoption of synthetic biology approaches, the increasing reliance on synthetic genes in therapeutic and vaccine development pipelines, and the growing use of custom DNA libraries for screening and functional studies all contribute to sustained demand. At the same time, advances in synthesis throughput, quality verification, and bioinformatics-supported design are making it easier for organizations to move from sequence concept to validated construct with shorter lead times. As projects become more complex and application goals more ambitious, buyers are increasingly willing to pay for reliability, rapid turnaround, and specialized handling of difficult sequences.
However, growth is occurring within an environment of intensifying regulatory and biosecurity scrutiny. In the United States, the OSTP Framework for Nucleic Acid Synthesis Screening has established expectations for providers to screen orders for sequences of concern, verify customer legitimacy, and self-attest compliance for federally funded life sciences research procurement. Notably, oligonucleotide screening thresholds are tightening, with stricter requirements scheduled to take effect as screening thresholds move toward 50 base pairs beginning in October 2026. These expectations have direct implications for provider operating procedures, buyer documentation burdens, and procurement timelines.
International standards and voluntary consortium protocols are reinforcing this trajectory. ISO 20688-2:2024 specifies requirements for the production and quality control of synthesized gene fragments, genes, and genomes in biotechnology nucleic acid synthesis, creating a clearer benchmark for manufacturing discipline and quality assurance. Alongside this, the International Gene Synthesis Consortium maintains a harmonized voluntary screening protocol that addresses sequence and customer screening practices for synthetic nucleic acids. In the United Kingdom, screening guidance issued by the Department for Science, Innovation and Technology aligns on tiered screening, customer identity verification, and legitimate use assessment, adding another layer of expectation for providers and users operating in or serving that market.
For market participants, these developments create both constraint and opportunity. Providers that invest early in robust screening workflows, transparent compliance documentation, and quality system alignment can convert regulatory pressure into competitive advantage. Buyers, in turn, must ensure that their sourcing strategies account for compliance readiness, especially when projects intersect with government funding, clinical development, or international collaboration. The result is a market in which biosecurity and quality are no longer back-office concerns; they are front-line selection criteria.
Importantly, custom gene synthesis services are provided strictly for research use only in many contexts, and responsible procurement increasingly requires demonstrable compliance with biosecurity screening frameworks to prevent misuse of sequences of concern. This compliance-oriented operating model is becoming a defining feature of credible provider-customer relationships and should be treated as a strategic variable in vendor evaluation and contract design.
Conclusion: Turning Market Intelligence into Strategic Advantage
The worldwide custom gene synthesis service market is expanding at a pace that demands more than reactive procurement. With a base-year valuation near USD 3,150 million in 2025 and a forecast trajectory that points toward nearly USD 9,465 million by 2032, the sector is being reshaped by faster service models, broader application scope, and a compliance environment that is becoming more prescriptive by the quarter. Organizations that treat gene synthesis as a strategic capability rather than a transactional purchase will be better positioned to protect timelines, manage risk, and capture value from synthetic biology-driven innovation.
PW Consulting’s Worldwide Custom Gene Synthesis Service Market report is designed to support that shift. It provides the macro context, segmentation logic, competitive framing, and regulatory awareness needed to make informed decisions in 2026 and throughout the forecast period. To access the full segmentation detail, regional and service-type breakdowns, end-user dynamics, and complete competitive profiles, we invite you to explore the complete report on our website. The full intelligence package is built to translate market complexity into clear, actionable direction for executive, R&D, and procurement teams alike.
For detailed analysis of this topic, please visit the official page: Worldwide Custom Gene Synthesis Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com