

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Office Building Design Market Hits $42.5B in 2025, Projects 4.65% CAGR to 2032

Global Office Building Design Market: Strategic Intelligence for 2026 Decision-Makers
The global office building design market stands at a critical inflection point. As organizations navigate post-pandemic workplace paradigms, sustainability mandates, and technological disruption, the design of commercial office spaces has evolved from a purely architectural exercise into a strategic imperative that directly impacts talent retention, operational efficiency, and corporate ESG performance. Our latest Worldwide Office Building Design Market research provides a comprehensive, data-driven blueprint for executives, developers, and design professionals seeking to capitalize on the market's trajectory through 2032.
Drawing on historical performance from 2020 through 2025 and projecting forward across a seven-year forecast horizon, this study captures the market at an estimated valuation of over 42.5 billion USD in the base year, with a clear acceleration trajectory toward more than 58.4 billion USD by 2032. The compound annual growth rate of 4.65 percent reflects the steady, structural demand reshaping how offices are conceived, engineered, and delivered worldwide. For corporate strategists, real estate investors, and design firm leaders, this report translates macroeconomic momentum into actionable intelligence, mapping the forces that will define competitive advantage in the years ahead.
The Macro Landscape: Growth Trajectory and Structural Shifts
Over the past five years, the office building design sector has demonstrated remarkable resilience, absorbing the shock of hybrid work adoption while simultaneously reorienting around wellness, sustainability, and digital integration. Historical data reveals a market that not only recovered from pandemic-era disruption but expanded its value proposition, moving beyond square footage allocation to encompass holistic workplace strategy. The forecast period from 2026 to 2032 signals a market characterized by compounding growth, driven by capital reinvestment in commercial real estate, regulatory pressure toward net-zero performance, and the ongoing digitalization of design workflows.
A defining feature of the current market structure is its highly fragmented competitive landscape. The combined market share of the top three firms remains modest, and even the top five players account for less than one-fifth of total industry revenue. This fragmentation creates both opportunity and complexity: no single entity dominates the value chain, allowing regional specialists, technology providers, and interdisciplinary consortia to compete on innovation, service depth, and domain expertise. For clients evaluating design partners, this means a rich ecosystem of alternatives, each bringing differentiated capabilities in sustainability integration, BIM coordination, spatial programming, and regulatory compliance.
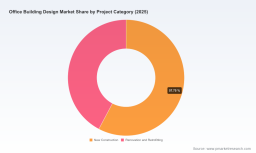
The report dissects this landscape across multiple dimensions, examining how design services are allocated across architectural, interior, structural, and landscape/urban planning disciplines, as well as how project categories split between new construction and renovation or retrofitting. Rather than presenting static allocations, the analysis contextualizes these splits within evolving client priorities—where retrofitting existing stock gains traction against demolition-and-rebuild approaches, and where interior and architectural design converge to address hybrid work rhythms. Understanding these structural dynamics is essential for firms positioning their service portfolios and for corporate real estate leaders allocating capital across design phases.
Competitive Arena: Key Players and Recent Strategic Moves
The competitive environment is shaped by a blend of global architecture firms, multidisciplinary engineering consultancies, and software platforms that underpin the design process itself. The report profiles the principal actors driving innovation, each representing distinct strategic positioning within the market.
Office Furniture Market
Gensler, headquartered in San Francisco, continues to advance workplace strategy at scale, integrating biophilic design, wellness features, and flexible layouts tailored to hybrid environments. A notable recent milestone includes the completion of a 1,000+ desk workplace for Amazon in London, featuring hybrid work zones and biophilic elements, underscoring the firm's capacity to deliver large-scale projects that reconcile density with human-centered design.
AECOM, based in Dallas, provides comprehensive office building design services with a strong emphasis on sustainable architecture, BIM integration, and adaptive reuse. Its September 2025 collaboration announcement with Microsoft on AI-integrated office design for headquarters expansion highlights a growing trend: technology giants partnering with design firms to embed adaptive, intelligent spatial systems into flagship corporate campuses.
HOK, from St. Louis, emphasizes human-centered design, net-zero energy buildings, and technology-enabled workspaces for multinational enterprises. The firm's recognition with an AIA COTE Top Ten Award in April 2025 for a net-zero office building design project in Seattle reinforces the industry's shift toward demonstrable environmental performance as a market differentiator.
Perkins&Will, headquartered in Chicago, leads in resilient, inclusive spaces incorporating WELL Building Standards and circular economy principles. Its work aligns with a broader regulatory and client-driven push for health-and-wellness certification as a baseline, not a premium. Skidmore, Owings & Merrill (SOM), also Chicago-based, remains renowned for high-rise office towers and innovative designs featuring advanced structural engineering, daylight optimization, and smart building systems—capabilities increasingly relevant as urban density and performance standards intensify.
On the technology side, Autodesk, Bentley Systems, and Graphisoft serve as critical enablers. Autodesk's Revit and BIM 360 platforms support collaborative 3D modeling, simulation, and construction documentation, while its June 2025 release of Revit 2026 introduced enhanced generative design tools for office layouts, optimizing space utilization and sustainability metrics. Bentley Systems' AECOsim and OpenBuildings Designer facilitate infrastructure modeling and digital twin creation, with a March 2025 product launch improving interoperability for multi-disciplinary office design teams. Graphisoft's Archicad supports openBIM workflows and energy analysis, enabling sustainable design decisions at the architectural level. Together, these platforms are reshaping how design teams collaborate, iterate, and validate performance before ground is broken.
Market Dynamics: Regulations, Talent, and Technology Pressures
Beyond firm-level competition, the market is being reshaped by regulatory frameworks, labor economics, and technology adoption cycles that directly affect project feasibility, cost structures, and design outcomes. The report synthesizes these forces into a cohesive dynamics analysis, enabling stakeholders to anticipate compliance burdens, workforce constraints, and digital transformation requirements.
Regulatory momentum is accelerating. The WELL Building Standard v2, updated in 2024, mandates performance verification for office designs, requiring more than 40 metrics across air, water, and thermal comfort. This elevates wellness from design aspiration to measurable obligation, impacting material selection, mechanical systems, and commissioning protocols. In Europe, the recast Energy Performance of Buildings Directive requires all new office buildings to achieve near-zero energy standards by 2030, compressing design timelines for energy modeling and envelope performance. Meanwhile, LEED v5, launched in 2024, introduces social equity credits for office designs, emphasizing inclusive access and community impact—expanding the scope of sustainability to encompass social dimensions alongside environmental ones.
Labor market dynamics present both constraints and incentives. The average salary for architectural designers in the office building sector reached approximately 105,000 USD annually in the United States, reflecting a 5 percent year-over-year increase driven by demand for BIM expertise. Concurrently, a global shortage of an estimated 1.5 million construction professionals is projected by 2030, fueling 15 to 20 percent cost inflation for specialized office design labor. These pressures are compressing margins for firms reliant on traditional delivery models while incentivizing investment in digital tools, prefabrication, and outcome-based service contracts.
Technology is simultaneously alleviating and intensifying these pressures. Generative design, digital twins, and integrated BIM workflows are reducing iterative cycles, improving performance prediction, and enabling earlier stakeholder alignment. Yet the same tools raise the bar for competency, requiring firms to upskill teams, standardize data pipelines, and integrate software ecosystems across architects, engineers, and owners. The report maps these technology adoption patterns, highlighting where software capabilities translate into competitive differentiation and where integration gaps create execution risk.
What the Report Delivers: Operational Intelligence for 2026 Strategy
This Worldwide Office Building Design Market study is designed for practitioners who need more than top-line figures. It offers an operational lens on how market structure, competitive behavior, regulatory mandates, and technology trends intersect to shape deal flow, pricing, and project delivery.
The report examines demand drivers across major geographies, including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa, situating each region within its own regulatory cadence, urbanization patterns, and corporate real estate priorities. It allocates market value across design service categories—architectural design, interior design, structural engineering, and landscape and urban planning—and across project categories spanning new construction and renovation or retrofitting. Rather than presenting these splits as static percentages, the analysis interprets them as strategic signals: where client budgets are migrating, which service lines face capacity constraints, and how renovation activity competes with new builds for design resources.
Worldwide Office Building Design Market
In addition, the report profiles the competitive set with granular detail on firm capabilities, recent project completions, partnership announcements, awards, and software releases. This temporal view of recent developments enables readers to identify momentum patterns— Which firms are scaling hybrid workplace delivery? Which are embedding AI into design workflows? Which are distinguishing themselves through net-zero performance or WELL certification? Such signals matter for procurement teams evaluating design partners, for firms benchmarking their own pipeline strategy, and for investors assessing where value is concentrating.
The analysis also translates regulatory and labor dynamics into practical implications. It connects WELL v2 verification requirements to commissioning and post-occupancy evaluation; links EPBD near-zero standards to envelope design and mechanical system selection; and correlates LEED v5 social equity credits with site planning and community engagement. By tying compliance obligations to design decisions and cost structures, the report equips teams to plan for verification, budget for specialized labor, and sequence design activities to avoid late-stage rework.
Technology adoption is treated with the same operational rigor. The report evaluates how generative design tools, BIM collaboration platforms, and digital twin capabilities influence space utilization, sustainability metrics, and interdisciplinary coordination. It identifies where software investments yield measurable returns in design quality and schedule compression, and where fragmented toolchains create interoperability friction. For firms evaluating platform strategies or clients specifying delivery requirements, this technology mapping clarifies where standards adoption, data continuity, and workforce training will determine project success.
Strategic Implications for 2026 and Beyond
For corporate real estate leaders, the market's trajectory through 2032 presents a mandate to reevaluate workplace strategy as a core business capability. The convergence of hybrid work patterns, sustainability mandates, and wellness certification expectations means office design is no longer a one-time capital project but an ongoing program of spatial optimization, performance verification, and employee experience management. Firms that integrate design strategy with occupancy analytics, post-occupancy evaluation, and flexible lease structures will be better positioned to align real estate portfolios with evolving organizational needs.
For design firms and consultancies, the fragmented competitive landscape offers room to differentiate through specialization, regional depth, and technology-enhanced delivery. The growth rate and market size trajectory indicate sustained demand, but profit pools will increasingly reward firms that can demonstrate performance outcomes, integrate software tools into repeatable workflows, and navigate regulatory verification with minimal client friction. Firms that invest in BIM competency, generative design, and sustainability analytics will be better equipped to absorb labor cost inflation while maintaining margin integrity.
For technology providers, the market underscores the strategic importance of interoperability, data continuity, and user-centric tooling. Revit, OpenBuildings, and Archicad ecosystems are not merely production tools; they are coordination layers that shape how multidisciplinary teams collaborate, how performance is simulated, and how compliance is documented. Enhancements in generative layout optimization, openBIM workflows, and digital twin integration directly influence design quality and project outcomes, making platform strategy a competitive variable rather than a back-office consideration.
Access the Full Intelligence
The Worldwide Office Building Design Market research synthesizes historical performance, forward-looking forecasts, competitive profiling, regulatory and labor dynamics, and technology adoption patterns into a single strategic reference. The executive summary and market overview presented here capture the contours of a market growing from approximately 42.5 billion USD in the base year toward more than 58.4 billion USD by 2032, with a compound annual growth rate of 4.65 percent and a competitive landscape that remains broadly fragmented. Yet the true operational value lies in the detailed segmentation, regional analysis, firm-level profiles, and regulatory-technology implications that enable precise strategic planning.
To access the complete dataset, segmentation breakdowns, competitive assessments, and region-specific demand drivers, visit the full report page. The comprehensive study provides the depth required to inform 2026 capital allocation, design partner selection, service portfolio strategy, and technology investment decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Office Building Design Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com