

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Custom Gene Synthesis Market Hits $3.15B in 2025, Projected to Reach $9.47B by 2032

Navigating the Next Wave in Custom Gene Synthesis: Strategic Intelligence for 2026 and Beyond
The global custom gene synthesis service market stands at a critical inflection point. With a reported valuation of approximately USD 3,150 million in the base year of 2025 and a projected expansion to over USD 9,465 million by 2032, the sector is experiencing a compound annual growth rate of 17.02 percent. These figures signal more than incremental progress. They reflect a structural acceleration in how life sciences organizations design, validate, and deploy synthetic nucleic acids across research, translational development, and increasingly, clinical manufacturing. For executives, investors, and R&D leaders, the ability to interpret this trajectory with precision is no longer optional. It is a core component of portfolio planning, vendor selection, and risk-managed growth.
PW Consulting’s newly released Worldwide Custom Gene Synthesis Service Market study offers a comprehensive, decision-ready view of this rapidly evolving landscape. Designed as an operational intelligence resource rather than a static market summary, the report maps historical performance from 2020 through 2025 and extends a disciplined forecast through 2032. The analysis situates macro growth within the operational realities that shape procurement cycles, capacity commitments, service-level expectations, and competitive positioning.
Why This Research Matters for 2026 Decision-Making
As organizations move from exploratory synthetic biology programs into scaled therapeutic, diagnostic, and industrial applications, the cost-of-error in supplier selection and capacity planning rises sharply. The difference between a service partner that delivers reliable, NGS-verified clonal constructs and one that introduces sequence failures, turnaround variability, or compliance bottlenecks can cascade into delayed preclinical milestones, budget overruns, and reputational exposure. The current market environment amplifies these stakes. Rapid service innovations, regulatory tightening around sequence screening, and consolidation-driven capability upgrades are reshaping what buyers should prioritize when evaluating gene synthesis providers.
This study is built to translate market momentum into executable strategy. It examines how demand patterns are shifting across end-user segments, how service-type preferences are evolving as projects grow in sequence complexity, and how regional capabilities are aligning with localized regulatory and manufacturing expectations. By anchoring discussion in verified commercial behavior rather than speculative projections, the report equips leadership teams to calibrate investment timing, negotiate service agreements with greater confidence, and anticipate the operational implications of new compliance frameworks.
Equally important, the analysis recognizes that gene synthesis is no longer a commoditized utility. It is becoming a differentiated enabler of speed, accuracy, and biological functionality. From codon optimization and vector design to rapid gene-to-plasmid delivery and large-scale construct generation, service capabilities increasingly influence downstream success in protein production, functional genomics, and therapeutic development. Understanding where capabilities are converging, where differentiation remains defensible, and where pricing pressure is most intense is essential for any organization that depends on synthetic DNA as a core input.
What the Report Delivers: A Practical, Execution-Focused View
The study provides a structured, multi-dimensional assessment of the worldwide custom gene synthesis service market. Rather than presenting high-level trends in isolation, it ties market sizing to the operational and commercial variables that actually drive outcomes. Key areas of coverage include:
-
Historical and Forecast Trajectory
The report traces market development from 2020 through the 2025 base year and projects forward through 2032, providing a continuous view of growth momentum. This longitudinal perspective helps readers distinguish cyclical fluctuations from durable structural expansion and identify the demand signals most relevant to near-term planning.
-
Service-Type Segmentation in Operational Context
Custom gene synthesis is not a single product category. The analysis examines how standard gene synthesis, complex and large gene synthesis, and custom DNA libraries each serve distinct project requirements, lead-time expectations, and precision thresholds. This framing helps organizations match service portfolios to real-world application needs rather than relying on broad market averages.
Gene Synthesis Market -
End-User Demand Architecture
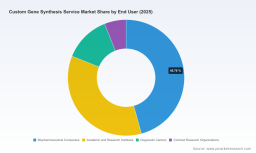
The study evaluates how biopharmaceutical companies, academic and research institutes, diagnostic centers, and contract research organizations shape procurement behavior, volume concentration, and service expectations. Understanding these demand profiles is central to forecasting where growth will materialize fastest and which customer segments will drive the most consequential capability requirements.
-
Regional Capability Mapping
The report assesses how major geographic markets are positioning themselves across supply, expertise, and compliance readiness. Regional analysis is presented as a strategic lens for sourcing strategy, capacity diversification, and regulatory alignment rather than as a simple ranking of market share.
Worldwide Custom Gene Synthesis Service Market -
Competitive Benchmarking and Strategic Positioning
A detailed review of leading service providers highlights differences in turnaround models, sequence complexity handling, vector and cloning support, codon optimization capabilities, and quality verification practices. This competitive layer supports vendor evaluation, partnership planning, and long-term capability roadmapping.
-
Regulatory and Biosecurity Context
The study integrates the evolving compliance environment into market interpretation, including screening expectations, quality standards, and the operational burden they place on providers and buyers alike. This dimension is increasingly decisive in procurement decisions, especially for organizations connected to federally funded research or clinical-stage programs.
Competitive Landscape: Capability, Speed, and Differentiation at Scale
The custom gene synthesis market features a diverse set of established providers and specialized entrants, each pursuing distinct value propositions around speed, accuracy, complexity handling, and application breadth. PW Consulting’s analysis evaluates these players through the lens of operational execution and strategic positioning, highlighting how service design is becoming a competitive moat.
Several globally recognized providers anchor the market with broad service portfolios and differentiated throughput models. One major East Asia-rooted global provider has emphasized rapid gene-to-plasmid turnaround alongside premium offerings for complex sequences extending to substantial lengths, paired with extensive codon optimization and high-accuracy synthesis for both research and therapeutic applications. A prominent silicon-based synthesis specialist has built its position on high-throughput DNA production, expedited clonal gene services for sequences up to defined size thresholds, and large-scale support for synthetic biology and biopharmaceutical programs. Another long-standing nucleic acid supplier has focused on NGS-verified clonal DNA in standard vectors, enhanced gene synthesis workflows for research requirements, rapid gene options, and gene fragment solutions designed for accuracy and quick delivery.
Large instrumentation and life sciences conglomerates also play a meaningful role. Through dedicated synthetic biology platforms, one global leader supplies optimized synthetic genes, gene libraries, and cloning solutions that span research and industrial use cases. In parallel, regionally anchored and specialty providers continue to expand the competitive field by addressing nuanced customer needs. These include providers with strong emphasis on complex sequences characterized by high GC content or repetitive regions, full subcloning support, and high-quality DNA constructs for both research and commercial applications. Others compete on expedited turnaround, high completion reliability, and priority shipping pathways that appeal to time-sensitive R&D and CRO workflows.
Additional participants extend the market’s functional range. Some providers bundle custom gene synthesis with mRNA and protein synthesis capabilities, offering integrated workflows and accessible codon optimization tools for synthetic biology projects. Cost-conscious research buyers often evaluate providers that combine affordability with quick turnaround, cloning support, and recombinant expression services. Others differentiate through protein design optimization, ORF clone and expression vector portfolios, or precision-focused guarantees tied to sequence accuracy and ready-to-use delivery. Across this landscape, the strategic question for buyers is not simply who offers the lowest price, but which provider’s capabilities best match the complexity, compliance, and timeline requirements of each program.
Recent corporate activity reinforces the market’s consolidation-and-capability dynamic. Provider announcements in 2024 and 2025 reflect a push toward faster delivery models, regional expansion, and GMP-aligned manufacturing capacity. Notable moves include the introduction of accelerated gene-to-plasmid services, expansion into new facilities designed for high-quality synthetic DNA and RNA production, and targeted acquisitions intended to strengthen regional presence and technical capabilities. In parallel, certification and product milestones among specialty providers indicate growing attention to clinical-grade readiness and improved DNA production technologies for genetic medicine applications. These developments matter because they reshape supply reliability, service tier availability, and the compliance posture of the provider base.
Market Dynamics: Growth Drivers, Regulatory Pressure, and Strategic Risk
Several interrelated forces are propelling the market’s expansion. The broader adoption of synthetic biology approaches, the increasing reliance on synthetic genes in therapeutic and vaccine development pipelines, and the growing use of custom DNA libraries for screening and functional studies all contribute to sustained demand. At the same time, advances in synthesis throughput, quality verification, and bioinformatics-supported design are making it easier for organizations to move from sequence concept to validated construct with shorter lead times. As projects become more complex and application goals more ambitious, buyers are increasingly willing to pay for reliability, rapid turnaround, and specialized handling of difficult sequences.
However, growth is occurring within an environment of intensifying regulatory and biosecurity scrutiny. In the United States, the OSTP Framework for Nucleic Acid Synthesis Screening has established expectations for providers to screen orders for sequences of concern, verify customer legitimacy, and self-attest compliance for federally funded life sciences research procurement. Notably, oligonucleotide screening thresholds are tightening, with stricter requirements scheduled to take effect as screening thresholds move toward 50 base pairs beginning in October 2026. These expectations have direct implications for provider operating procedures, buyer documentation burdens, and procurement timelines.
International standards and voluntary consortium protocols are reinforcing this trajectory. ISO 20688-2:2024 specifies requirements for the production and quality control of synthesized gene fragments, genes, and genomes in biotechnology nucleic acid synthesis, creating a clearer benchmark for manufacturing discipline and quality assurance. Alongside this, the International Gene Synthesis Consortium maintains a harmonized voluntary screening protocol that addresses sequence and customer screening practices for synthetic nucleic acids. In the United Kingdom, screening guidance issued by the Department for Science, Innovation and Technology aligns on tiered screening, customer identity verification, and legitimate use assessment, adding another layer of expectation for providers and users operating in or serving that market.
For market participants, these developments create both constraint and opportunity. Providers that invest early in robust screening workflows, transparent compliance documentation, and quality system alignment can convert regulatory pressure into competitive advantage. Buyers, in turn, must ensure that their sourcing strategies account for compliance readiness, especially when projects intersect with government funding, clinical development, or international collaboration. The result is a market in which biosecurity and quality are no longer back-office concerns; they are front-line selection criteria.
Importantly, custom gene synthesis services are provided strictly for research use only in many contexts, and responsible procurement increasingly requires demonstrable compliance with biosecurity screening frameworks to prevent misuse of sequences of concern. This compliance-oriented operating model is becoming a defining feature of credible provider-customer relationships and should be treated as a strategic variable in vendor evaluation and contract design.
Conclusion: Turning Market Intelligence into Strategic Advantage
The worldwide custom gene synthesis service market is expanding at a pace that demands more than reactive procurement. With a base-year valuation near USD 3,150 million in 2025 and a forecast trajectory that points toward nearly USD 9,465 million by 2032, the sector is being reshaped by faster service models, broader application scope, and a compliance environment that is becoming more prescriptive by the quarter. Organizations that treat gene synthesis as a strategic capability rather than a transactional purchase will be better positioned to protect timelines, manage risk, and capture value from synthetic biology-driven innovation.
PW Consulting’s Worldwide Custom Gene Synthesis Service Market report is designed to support that shift. It provides the macro context, segmentation logic, competitive framing, and regulatory awareness needed to make informed decisions in 2026 and throughout the forecast period. To access the full segmentation detail, regional and service-type breakdowns, end-user dynamics, and complete competitive profiles, we invite you to explore the complete report on our website. The full intelligence package is built to translate market complexity into clear, actionable direction for executive, R&D, and procurement teams alike.
For detailed analysis of this topic, please visit the official page: Worldwide Custom Gene Synthesis Service Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com