

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Mesoporous Carbon Market to Reach $1.85B by 2032 at 9.86% CAGR

Navigating the Nano-Scale Revolution: Strategic Insights for the Global Meso-Micro Porous Carbon Materials Market Through 2032
The global landscape for advanced carbon materials is undergoing a structural transformation. No longer confined to traditional filtration roles, meso-micro porous carbon materials are becoming critical enablers in next-generation energy storage, high-purity catalysis, and stringent environmental remediation protocols. For corporate strategists, investors, and R&D directors, understanding the trajectory of this market is not merely an academic exercise—it is a prerequisite for securing supply chains, optimizing capital allocation, and identifying competitive moats in a decarbonizing economy.
PW Consulting's latest comprehensive study, the Worldwide Meso-Micro Porous Carbon Materials Market report, offers a granular roadmap of this evolution. Based on historical data from 2020 through the base year of 2025, the research projects market dynamics through the forecast period ending in 2032. This article serves as a strategic executive summary, highlighting the macro-economic forces, competitive maneuvers, and material science breakthroughs that define the sector, while outlining the actionable intelligence contained within the full dataset.
Macro-Economic Trajectory: From Recovery to Sustained Expansion
The market has demonstrated remarkable resilience and growth over the past half-decade. Following a global market valuation of approximately USD 605.42 million in 2020, the sector navigated post-pandemic supply chain adjustments to reach an estimated USD 958.32 million by 2025. This historical performance underscores a compound annualized growth rate that positions the industry favorably against broader chemical and materials sectors.
Carbon-Carbon Composite Material Market
Looking forward, the forecast period from 2026 to 2032 suggests an acceleration in value creation. The overall market size is projected to breach the USD 1 billion threshold in 2026, reaching USD 1,076.3 million, and continuing its upward march to reach USD 1,849.74 million by 2032. This growth trajectory, supported by a forecast CAGR of 9.86 percent, indicates more than just cyclical recovery; it reflects a fundamental shift in demand drivers. Industries are increasingly specifying porous carbon not as a commodity input, but as a performance-critical component tailored to micro- and mesoporous specifications.
This expansion is not uniform across the timeline. Early forecast years show steady increments, while later periods indicate potential step-changes in adoption rates as technologies mature. For decision-makers, this implies that capacity planning and technology licensing windows are narrowing. Missing the early wave of infrastructure build-out in energy storage or environmental compliance could result in significant long-term disadvantages.
Segmentation Dynamics: Technology, Application, and Regional Fores
While aggregate figures provide the top-line view, the real strategic value lies in understanding the divergent growth engines within the market. The segmentation analysis reveals distinct value pools defined by material type, end-use application, and geographic consumption.
Material Technology Divergence
The market is stratified by the method of pore structure engineering. Ordered mesoporous carbon, characterized by precise pore size distribution and high surface area uniformity, represents a significant portion of the value chain, catering to high-tech applications where consistency is paramount. Template-synthesized carbon offers another high-value avenue, allowing for customizable structures that bridge the gap between microporosity and mesoporosity for specialized catalytic and adsorption uses. Meanwhile, activated porous carbon remains the volume leader, driven by established infrastructure in purification and filtration. The interplay between these types dictates margin profiles; engineered variants typically command premium pricing compared to traditional activated grades, influencing R&D focus for material producers.
Application-Driven Demand Shifts
Demand is increasingly being pulled by specific application verticals rather than pushed by general industrial supply. Energy storage systems have emerged as a dominant force, leveraging the high surface area and conductivity of porous carbons for supercapacitors and advanced battery electrodes. Catalysis and chemical processing constitute another major pillar, where porous supports enhance reaction efficiency and selectivity in fine chemical synthesis. Environmental remediation continues to be a stable and growing driver, particularly as regulatory frameworks tighten around water and air quality.
The weight of these applications varies by region and by maturity of local industry. For instance, regions with aggressive renewable energy targets may see faster penetration in energy storage, while industrialized zones with strict emission standards may prioritize catalysis and remediation. Understanding the local mix is essential for market entry strategies.
Regional Consumption Patterns
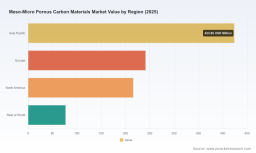
Geographic distribution of revenue highlights where the demand is physically manifesting. Asia Pacific has established itself as a massive consumption hub, reflecting its manufacturing base and growing energy infrastructure. Europe and North America follow as significant markets, driven by high regulatory standards and advanced chemical industries. The Rest of World segment, while smaller in current valuation, represents an emerging frontier where infrastructure development could unlock latent demand.
However, regional analysis is not static. Trade flows, local content requirements, and logistical constraints are reshaping these maps. The full report dissects these regional nuances without relying on simplistic percentage splits, instead focusing on the absolute value flows and the strategic implications of regional dominance.
Competitive Landscape: Consolidation and Strategic Maneuvers
The market structure indicates a moderately concentrated environment, with the top three players holding a significant combined market share and the top five controlling a majority of the revenue. This concentration suggests that scale advantages in feedstock procurement, production technology, and distribution networks are critical barriers to entry. However, niche players with proprietary pore-engineering technologies can still capture high-margin segments.
Several key companies are actively shaping the market through capacity expansions, technological collaborations, and strategic repositioning. Kuraray Co., Ltd., including its Calgon Carbon Corporation subsidiary, remains a global heavyweight in activated carbons and porous materials. Their portfolio, featuring brands like KURARAY COAL and FILTRASORB, spans water and air purification to energy storage applications. In February 2026, Kuraray announced a substantial investment of nearly USD 100 million to expand reactivated carbon production capacity at their Columbus, Ohio plant by approximately 27 million pounds annually. This move targets the surging demand for drinking water treatment and PFAS removal, with operations expected to commence in 2028. Additionally, advancements at the Tyger River Plant in South Carolina signal a dual focus on capacity and geographic resilience.
In the specialty carbon sector, Cabot Corporation, including Norit, continues to lead with engineered porous and activated carbons focused on purification and performance applications. Their expertise in carbon black and porous variants positions them well for filtration and high-tech uses. Ingevity Corporation is another key player, optimizing activated and porous carbons for high BET surface area and mesopore development. Serving automotive emission control, pharmaceutical, and food contact sectors, Ingevity has also been exploring biomass-derived precursors, including pine wood and agricultural residues, to mitigate fossil feedstock volatility, as evidenced by their pilot unit announcements in 2025.
Japanese manufacturers are pushing the boundaries of mesoporous technology. Toyo Tanso Co., Ltd. specializes in proprietary CNovel® mesoporous carbon, featuring a unique inter-connected 3D mesopore network distinct from conventional activated carbon. This material offers controlled pore sizes and high dispersibility, finding applications in lithium-air battery electrodes, fuel cells, and analytical instruments. Toyo Tanso has been highly active in R&D collaborations. In September 2025, they collaborated with NIMS to develop a self-standing carbon membrane electrode using CNovel® for stable 1-Wh-class stacked lithium-air battery operation, demonstrating higher output and scalability. Furthering their innovation pipeline, April 2026 saw the establishment of the Toyo Tanso Carbon Recycling Design Joint Research Laboratory with Gifu University.
Other notable participants include Jacobi Carbons AB and Kureha Corporation in Europe and Japan, respectively, focusing on specialized grades for purification and energy-related uses. In the commodity and regional segments, Haycarb PLC leverages coconut shell-based activated carbons for high-purity adsorption in water treatment and gold recovery, particularly from their base in Colombo, Sri Lanka. European suppliers like Donau Carbon GmbH and Carbotech AC GmbH provide activated carbons with micro/mesoporous properties tailored for environmental purification and gas/liquid phase applications. In North America, Carbon Activated Corporation offers a wide range of filtration and purification products with controlled porosity structures.
Worldwide Meso-Micro Porous Carbon Materials Market
The competitive dynamic is further influenced by raw material constraints. In 2025, coconut shell charcoal feedstock prices surged significantly due to supply constraints from prior drought conditions. Prices in Sri Lanka rose from USD 522/MT to USD 860/MT, Indonesia increased from USD 622/MT to USD 1,045/MT, and India jumped from USD 551/MT to USD 983/MT between December 2024 and July 2025. This volatility, coupled with tightened availability of coal-based feedstocks, directly increased manufacturing costs for micro- and mesoporous carbon materials, forcing producers to navigate margin pressures or pass through costs.
Regulatory and Supply Chain Pressures Reshaping Dynamics
Regulatory frameworks are acting as potent demand catalysts. As of 2025-2026, U.S. EPA PFAS regulations and strengthened Mercury and Air Toxics Standards (MATS) have continued to drive demand for high-performance mesoporous and activated carbon adsorbents in water treatment and emission control. These regulations effectively mandate the use of materials with specific adsorption capacities and pore structures, favoring suppliers who can certify performance and compliance.
Simultaneously, supply chain sovereignty is gaining prominence. In response to global trade volatility and import tariff impacts, Calgon Carbon launched Operation Bedrock in 2025. This initiative aims to provide tariff-free, domestically sourced U.S. coal-based activated carbon supply, highlighting a strategic shift towards regionalization to ensure continuity for critical infrastructure projects.
These dynamics create a complex environment where regulatory compliance, feedstock security, and logistical resilience are as valuable as the material properties themselves. Companies must align their sourcing strategies with regulatory requirements while managing cost volatility.
Inside the Report: Operational Intelligence for Decision Makers
The PW Consulting Worldwide Meso-Micro Porous Carbon Materials Market report is designed to translate these macro trends into actionable intelligence. Beyond the high-level market sizing and CAGR projections, the document provides a deep dive into the operational realities of the sector.
The research methodology encompasses a rigorous analysis of historical data from 2020 to 2025, establishing a robust baseline for forecasting. The forecast period extends through 2032, allowing for long-term strategic planning. The report details the segmentation splits across type, application, and region, providing absolute revenue estimates that allow stakeholders to quantify opportunity sizes without relying on ambiguous market shares. This approach facilitates precise market sizing for product launches and capacity investments.
Furthermore, the report includes detailed company profiles, encompassing headquarters locations, official web resources, and comprehensive summaries of product portfolios and strategic positioning. The competitive landscape section goes beyond static descriptions to analyze recent developments, such as capacity expansions, technology collaborations, and joint research laboratories. These event analyses provide early signals of where competitors are allocating capital and where technological breakthroughs are emerging.
Industry context is also thoroughly examined. The report integrates data on raw material price volatility, such as the coconut shell and coal feedstock surges, and explains their impact on manufacturing costs. It details regulatory drivers, including specific EPA mandates, and their direct correlation with demand shifts in remediation and purification segments. Regional initiatives like Operation Bedrock are analyzed to illustrate the interplay between trade policy and supply chain strategy.
By synthesizing these elements, the report enables readers to conduct scenario planning. Stakeholders can assess how changes in feedstock prices might alter margin structures, how new regulations could open or close market segments, and how competitor movements might shift market shares. The granularity of the data supports detailed financial modeling and risk assessment.
Strategic Implications for 2026 and Beyond
As the market crosses the USD 1 billion milestone in 2026, the window for strategic positioning is open but narrowing. The growth rate of 9.86 percent suggests that the market will nearly double in value over the forecast period, creating substantial wealth generation opportunities for those who can navigate the complexities of material specification, regulatory compliance, and supply chain management.
For technology developers, the demand for ordered mesoporous and template-synthesized carbons in energy storage and catalysis presents a high-value target. Collaborations, such as those seen with Toyo Tanso and NIMS, underscore the importance of partnering with research institutions to accelerate commercialization of novel pore structures. For producers, the focus must be on securing feedstock resilience, as evidenced by the shift towards biomass precursors and domestic sourcing initiatives. Margin protection will depend on the ability to differentiate through performance certifications that meet tightening regulatory standards.
Investors and corporate strategists should look beyond the aggregate numbers. The divergence between high-growth application segments and mature commodity segments requires a nuanced portfolio approach. Understanding the regional concentration of demand and the specific competitive maneuvers of key players like Kuraray, Cabot, Ingevity, and Toyo Tanso is essential for identifying white spaces and potential disruption risks.
Accessing Complete Market Intelligence
This overview provides a foundational understanding of the drivers, dynamics, and key players shaping the global meso-micro porous carbon materials market. However, the full strategic picture requires access to the complete dataset. The specific revenue estimates for each segment, the detailed regional breakdowns, the precise market concentration metrics, and the exhaustive list of competitive developments are critical for precise budgeting and planning.
PW Consulting's Worldwide Meso-Micro Porous Carbon Materials Market report contains the depth of analysis required to transform these insights into executed strategy. From granular historical data to forward-looking forecasts, the report serves as an indispensable tool for navigating the complexities of this evolving market. Readers are encouraged to consult the full source document to obtain the comprehensive intelligence necessary for making informed decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Meso-Micro Porous Carbon Materials Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com