

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Lens Measuring Device Market Hits $465.5M in 2025, Forecast 4.58% CAGR Through 2032

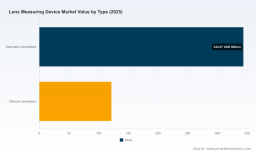
Strategic Vision in Focus: Navigating the Worldwide Lens Measuring Device Market
The global ophthalmic equipment sector is undergoing a period of disciplined expansion, driven by aging demographics, rising prevalence of refractive errors, and the accelerating integration of digital workflows into clinical and retail environments. Within this broader ecosystem, lens measuring devices—commonly referred to as lensmeters or lensometers—represent a critical capital equipment category. These instruments serve as the backbone of accurate spectacle and contact lens verification, pricing, and quality control across optical retail, clinical practices, and manufacturing facilities.
As businesses plan their capital allocation, product roadmaps, and regional entry strategies for the 2026–2032 horizon, having access to rigorously validated market intelligence is no longer a luxury; it is a strategic necessity. Our latest research publication, the Worldwide Lens Measuring Device Market study, provides a comprehensive, data-driven framework for executives, investors, and procurement leaders to navigate this evolving landscape with precision.
Worldwide Lens Measuring Device Market
The Macro Trajectory: Growth Anchored in Structural Demand
The market has demonstrated steady, compounding growth over the past half-decade. Historical revenue tracking from 2020 through the base year of 2025 reveals a consistent upward trajectory, with total market valuation crossing the 465 million USD threshold by 2025. This momentum is projected to accelerate modestly but persistently through the end of the forecast period, reflecting sustained investment in ophthalmic infrastructure across mature and emerging economies alike.
Our forecasting models indicate a compound annual growth rate of approximately 4.58 percent across the 2026–2032 window. While the growth rate may appear measured at first glance, it reflects a mature yet resilient capital equipment category where incremental innovations in measurement accuracy, automation, and digital integration are steadily expanding total addressable demand. The projection underscores a market that is not experiencing speculative volatility, but rather structured, usage-driven expansion tied to clinical standardization and retail modernization.
Importantly, the revenue trajectory suggests that growth will not be uniformly distributed across all sub-segments or geographic corridors. Enterprises that map their strategic initiatives to the regions and application verticals exhibiting the strongest underlying demand drivers will be best positioned to capture disproportionate share. The full report decomposes these dynamics with granular regional and application-level analysis, providing the granularity needed to align distribution partnerships, pricing architecture, and localized compliance strategies.
What the Report Delivers: Operational Intelligence for Decision-Makers
This study is structured to move beyond high-level summaries and deliver actionable intelligence that can be directly integrated into corporate strategy, product planning, and market-entry evaluations. The report architecture is designed for cross-functional utility, serving strategy teams, engineering leadership, commercial directors, and procurement professionals alike.
Key analytical components include:
- Historical Revenue Reconstruction and Baseline Calibration: A year-by-year analysis from 2020 through 2025 that establishes accurate baselines, corrects for reporting inconsistencies, and isolates underlying demand trends from short-term promotional or supply-chain fluctuations.
- Forward-Looking Revenue Modeling (2026–2032): Scenario-based projections that account for macroeconomic variables, regulatory pacing, and technology adoption curves, providing a realistic range of outcomes rather than a single-point estimate.
- Segment-Level Demand Mapping: Comprehensive breakdowns across device type, end-use application, and regional distribution. Each segment is evaluated for growth velocity, pricing dynamics, and adoption barriers, enabling targeted resource allocation.
- Competitive Positioning and Company Profiling: In-depth assessments of leading manufacturers, including product portfolio architecture, technological differentiators, regional footprint, and strategic focus areas.
- Regulatory, Reimbursement, and Procurement Context: Analysis of how classification frameworks, quality management requirements, and bundled reimbursement structures influence purchasing behavior, product design priorities, and sales cycle timelines.
- Market Concentration and Share Dynamics: Evaluation of how revenue is distributed across the competitive landscape, highlighting the scale advantages of established players and the positioning strategies of emerging entrants.
- Technology and Workflow Integration Trends: Examination of how digital interfaces, wavefront sensing, UV and blue-light measurement capabilities, and integration into broader vision exam suites are shaping procurement requirements and end-user expectations.
Each section is written to support concrete decision-making. Whether you are evaluating a potential acquisition target, planning a product refresh cycle, assessing distributor partnerships, or benchmarking your market position against global peers, the report provides the evidentiary foundation required to reduce uncertainty and accelerate execution.
Competitive Landscape: Established Incumbents and Technology-Driven Positioning
The global lens measuring device market features a diverse cohort of manufacturers spanning Europe, East Asia, and North America. Competitive differentiation is increasingly anchored in measurement precision, automation levels, and compatibility with digital clinical workflows rather than price competition alone. Several key companies illustrate the strategic contours of this landscape.
Carl Zeiss Meditec AG, headquartered in Jena, Germany, continues to reinforce its position through advanced optical instrumentation, exemplified by the VISULENS 550 digital lensmeter. The device leverages wavefront technology and an integrated UV spectrometer to deliver precise measurement of both spectacle and contact lenses, including detailed UV protection analysis. This emphasis on diagnostic-grade accuracy and multi-parameter measurement aligns with clinical buyers who prioritize equipment that enhances exam suite efficiency and patient counseling capabilities.
In Japan, Topcon Corporation and NIDEK Co., Ltd. represent two of the most recognized names in ophthalmic instrumentation. Topcon offers a broad spectrum of solutions, from manual lensmeters such as the LM-8/8E series, which utilize LED illumination for reliable power verification, to computerized models like the CL-300 and SOLOS automated lens analyzer. These platforms deliver accurate lens power, progressive lens, and UV measurements, supporting both independent practices and larger optical networks. NIDEK complements this landscape with automated lensmeters such as the LM-1800PD/1800P and LM-7P/7 series, which employ Hartmann sensor technology with 108 measurement points to achieve high-accuracy lens verification. The inclusion of pupillary distance and UV measurement features further broadens their utility across clinical and retail settings.
Reichert Technologies, operating under AMETEK and based in Buffalo, New York, has built strong recognition around the LensChek Pro and LensChek Plus digital lensometers. These instruments are designed with intuitive interfaces and built-in PD/UV measurement capabilities, supporting a wide range of lens types as part of the broader VisionChek Digital Exam Suite. By embedding lens measurement into integrated exam workflows, Reichert addresses a growing institutional preference for equipment that reduces manual steps and standardizes measurement protocols across multiple sites.
Marco Ophthalmic, Inc., headquartered in Jacksonville, Florida, offers the LM-7/7P and LM-1800/1800PD automated lensmeters, often in partnership with NIDEK, alongside the LM-101 manual lensmeter. This portfolio strategy provides flexibility for buyers seeking both automated throughput and manual verification options, catering to a wide range of practice sizes and operational models. Huvitz Co., Ltd., based in Anyang, South Korea, has expanded its presence with the HLM-9000 premium auto lensmeter, which includes blue light and UV measurement capabilities, the HLM-7000P standard model, and the HLM-1 basic wavefront-based lensmeter. Huvitz’s product ladder illustrates a deliberate approach to serving multiple price-performance tiers while maintaining consistent measurement reliability.
Additional contributors to the competitive field include Keeler Ltd. in Windsor, United Kingdom, which supplies lensmeters within its broader ophthalmic diagnostic portfolio with a focus on dependable lens power verification for optometry practices. Oculus Optikgeräte GmbH, located in Wetzlar, Germany, provides lens measuring devices integrated into its optometry equipment lineup, emphasizing clinical lens analysis within a cohesive diagnostic ecosystem. Takagi Seiko Co., Ltd., based in Nakano, Japan, offers lensmeters within its wider range of ophthalmic instruments, targeting eye care settings that require accurate measurement as part of routine clinical operations.
The market structure reflects meaningful concentration at the top tier. Aggregate revenue is distributed such that a relatively small group of leading manufacturers commands a substantial share of total market value, while a longer tail of specialized and regional providers competes on service, distribution reach, and segment-specific features. Understanding the precise share distribution, brand loyalty dynamics, and substitution patterns across tiers is essential for any company evaluating partnership opportunities, competitive threats, or market entry feasibility. The complete report maps these concentration patterns in detail.
Market Dynamics: Regulation, Reimbursement, and Capital Equipment Behavior
The commercial environment for lens measuring devices is shaped by several interrelated forces that influence both product development priorities and purchasing behavior. Regulatory classification plays a foundational role. In the United States, lens measuring devices such as lensmeters are generally classified as Class II medical devices under FDA regulations, requiring 510(k) clearance for marketing. This regulatory pathway creates a structured barrier to entry that rewards manufacturers with established compliance infrastructure and disciplined product reporting, while also shaping the pace at which new features can be introduced and commercialized.
Beyond regulatory clearance, quality management expectations further influence competitive dynamics. Ophthalmic diagnostic equipment, including lensmeters, must typically comply with ISO 13485 quality management systems for medical devices. Adherence to these standards affects manufacturing consistency, supplier qualification, and the credibility of manufacturers seeking to serve hospital systems, regulated retail chains, and institutional buyers who integrate device quality into vendor selection criteria.
Laser Distance Measuring Devices Market
On the procurement side, lensmeters function as capital equipment within optometry and ophthalmology practices. Hospital and clinic capital expenditure budgets increasingly prioritize equipment that integrates into digital exam suites, reflecting a broader institutional push toward workflow efficiency, data capture standardization, and reduced manual handling. Devices that offer seamless data transfer, intuitive operator interfaces, and compatibility with existing practice management or electronic health record environments are therefore gaining preferential consideration during purchasing cycles.
Reimbursement structures also shape end-user demand, though indirectly. Lens measurement procedures performed during eye exams are typically bundled into routine vision or refraction CPT codes rather than carrying dedicated device-specific reimbursement codes. This bundling means that procurement decisions are driven less by direct device reimbursement and more by overall practice efficiency, throughput, accuracy, and patient experience. Manufacturers that can demonstrate how their instruments reduce measurement time, minimize remakes, or improve spectacle and contact lens fitting accuracy are better aligned with how eye care providers evaluate return on investment.
Recent industry activity reinforces the momentum around automation and feature integration. For example, in September 2025, Visionix USA debuted the VX 40 Couture auto lensmeter at Vision Expo West, highlighting advanced automated lens analysis capabilities. Product launches of this nature signal that competition is intensifying around measurement speed, parameter depth, and presentation of results in formats that support both clinical decision-making and retail customer engagement.
Strategic Implications for 2026 and Beyond
For executives planning their 2026 agendas, the lens measuring device market offers a clear but nuanced set of strategic implications. First, the steady growth trajectory suggests that demand will remain resilient, but competitive advantage will accrue to organizations that align product capabilities with the operational priorities of their target buyers. Automated measurement, multi-parameter analysis, and workflow integration are not merely technical specifications; they are purchasing criteria that reflect how eye care providers and optical retailers measure efficiency and service quality.
Second, the regulatory and quality management environment means that compliance readiness and manufacturing consistency are strategic assets. Companies entering new geographies or expanding into regulated institutional channels should evaluate certification pathways, local registration requirements, and quality system compatibility before finalizing go-to-market plans. A disciplined regulatory strategy can reduce launch delays and strengthen credibility with procurement teams.
Third, market concentration indicates that scale, brand recognition, and established distribution relationships continue to matter. At the same time, segmentation data suggests that differentiated positioning remains viable, particularly for manufacturers that can serve specific application verticals or regional demand pockets with tailored product configurations, support models, and pricing structures. Detailed segment analysis is essential for identifying where such positioning can be most effective.
Finally, reimbursement bundling and capital equipment purchasing behavior underscore the importance of demonstrating operational value. Sales narratives, training programs, and service offerings should be designed around how a device improves measurement consistency, speeds patient or customer throughput, and integrates with broader digital workflows. In a category where direct device reimbursement is not the primary purchasing driver, total value proposition becomes the critical differentiator.
Accessing the Complete Intelligence
The Worldwide Lens Measuring Device Market study is designed to provide the depth, structure, and forward-looking modeling that senior decision-makers require. It combines historical calibration, multi-year forecasting, segment-level demand mapping, competitive profiling, and regulatory and procurement context into a single cohesive analytical framework. For organizations evaluating product strategy, market entry, partnership selection, or capital allocation, the report offers a rigorous basis for reducing uncertainty and sharpening execution.
To explore the full segmentation breakdowns, regional demand profiles, company-level assessments, and detailed forecast tables, visit the source webpage where the complete report and associated data modules are available. The full intelligence package provides the granular visibility required to translate market dynamics into precise, defensible strategic decisions for 2026 and the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Lens Measuring Device Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com