

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Dienogest Market Hits $532M in 2025, Projected to Reach $882.61M by 2032; Endometriosis Treatment Leads

Strategic Intelligence for the Next Horizon: Inside the Worldwide Dienogest Market Research 2026–2032
Decision-makers in women’s health, specialty pharmaceuticals, and global market access face a pivotal moment. Over the past half-decade, dienogest has transitioned from a niche hormonal therapy to a cornerstone treatment for endometriosis, while simultaneously anchoring a growing segment of contraceptive and combined formulations. The release of our Worldwide Dienogest Market study is designed to convert this complexity into executable strategy for the 2026 planning cycle and beyond. Rather than offering static snapshots, this research maps the structural shifts, competitive fault lines, and regulatory inflection points that will determine share, margin, and market access over the next seven years.
A Market in Transition: Baseline Velocity and Directional Signals
Drawing on a comprehensive historical reconstruction and a forward-looking forecast window spanning 2026 to 2032, the analysis places the global market on a clear upward trajectory. Base-year revenue for 2025 is positioned at 532.0 million USD, reflecting sustained adoption across established therapeutic indications and expanding access in high-prevalence regions. From this anchor point, the market is projected to advance at a compound annual growth rate of 7.51 percent, culminating in a 2032 revenue threshold of 882.61 million USD. This growth curve is not merely a function of prescription volume; it is the product of converging forces: patent expirations unlocking generic supply, reimbursement frameworks stabilizing patient access in core European markets, and deliberate portfolio expansion by both originator and generic manufacturers.
The narrative arc from 2020 through 2025 already illustrates the acceleration pattern that decision-makers must internalize. Sequential year-over-year expansion moved from 385.4 million USD in 2020 to 532.0 million USD in 2025, signaling that dienogest-based therapies have secured durable positioning in treatment algorithms where endometriosis management demands long-term, tolerable hormonal suppression. Looking ahead, the forecast band maintains momentum through 2027 and 2028, with returns expected to compound more steeply as generic penetration matures and emerging-market distribution networks strengthen. For strategy teams, the practical implication is straightforward: growth is real, but it will be captured by players who align supply strategy, pricing architecture, and market-access positioning with the timing of regulatory and competitive shifts rather than by those who rely on legacy volume assumptions.
Worldwide Dienogest Market
Worldwide Danazol Market
What the Study Delivers: Operational Intelligence, Not Just Headlines
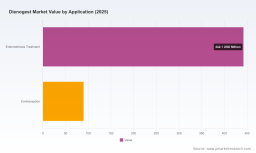
Our methodology is built around actionable deliverables. The report dissects the commercial ecosystem across product type, therapeutic application, and regional demand architecture, then ties each dimension to the operational decisions that shape performance. Readers will find a granular assessment of how tablet-based monotherapy and combined formulations occupy distinct value positions in physician prescribing behavior, reimbursement logic, and patient adherence profiles. The analysis connects these product dynamics to application-level demand, clarifying how endometriosis treatment continues to function as the dominant volume driver while contraceptive and combined-use pathways contribute differentiated margin and formulation opportunities.
Equally important, the research translates market structure into execution-ready frameworks. The segmentation architecture is paired with a competitive intensity model that evaluates concentration, pricing behavior, and entry timing. By examining market concentration through a consolidated lens, the study highlights how a relatively small group of multinational and specialized generic manufacturers command the majority of share, while a broader field of regional suppliers competes on distribution reach, local market access, and formulation agility. This is not a theoretical exercise; it is a practical map for assessing where competitive pressure will intensify, where pricing endurance will be tested, and where partnership or licensing strategies can create durable positioning.
To support planning teams, the report also integrates supply-side realities that often remain siloed from commercial strategy. It examines the manufacturing geography that underpins active pharmaceutical ingredient flow, the logistics corridors that determine time-to-market for generic entries, and the procurement patterns that influence cost structures across markets. These operational layers are essential for anyone evaluating launch sequencing, inventory strategy, or the economics of entering markets where dienogest is already established versus markets where awareness and access are still building.
Competitive Architecture: Originator Positioning and the Generic Wave
The competitive landscape is defined by a clear structural split between the originator franchise and the expanding generic field. Bayer AG remains the reference point for dienogest-based endometriosis therapy through its Visanne portfolio, marketed internationally outside the United States. The company’s positioning reflects decades of clinical familiarity, established physician trust, and a brand architecture that has shaped treatment norms across multiple regions. Yet the strategic context around this franchise has changed materially. Patent protection in key European markets expired across 2022 and 2023, opening the door to a wave of generic entrants and fundamentally altering the pricing and share dynamics that had previously supported premium positioning.
The generic cohort now includes a dense field of capable manufacturers. Teva Pharmaceutical Industries Ltd. captured an early mover advantage by launching generic dienogest 2mg tablets in Germany following patent expiry, a move that signaled both the timing and the commercial seriousness of the generic wave. Mylan N.V., operating under Viatris, has extended generic dienogest formulations for endometriosis across multiple global markets, reinforcing the shift from single-source supply to a multi-channel competitive environment. Sun Pharmaceutical Industries Ltd. and Dr. Reddy’s Laboratories Ltd. have built substantial international supply footprints, with Sun Pharmaceutical explicitly expanding generic dienogest availability into Southeast Asian markets through new partnerships and Dr. Reddy’s continuing global production and export of generic formulations for endometriosis treatment. Zydus Lifesciences, formerly Zydus Cadila, rounds out the field with generic dienogest 2mg tablets available across both emerging and developed markets, while Perrigo Company plc provides additional generic coverage in select international markets.
This competitive mix matters because the market is no longer governed by a single pricing anchor. Instead, it is shaped by the interaction between originator brand equity, generic price erosion, tender dynamics, and the speed at which local distributors and market-access teams can convert regulatory approval into realized volume. Recent developments illustrate the pace of change: a generic launch in Germany after patent expiry, expanded approval activity for additional generic versions across EU member states, and deliberate supply expansion into Southeast Asia. Each event is a signal that the market’s center of gravity is moving from exclusivity-driven pricing to access-driven competition. Our study maps these events against a forward competitive model so that readers can anticipate where share shifts are most likely to occur and how pricing resilience should be structured.
Market Dynamics: Regulation, Access, Supply, and Geographic Realities
No dienogest strategy is complete without confronting the regulatory and access realities that shape commercial feasibility. The therapy enjoys approval in more than 100 countries for endometriosis, yet its market architecture is uneven. In the United States, dienogest monotherapy is not FDA-approved for the endometriosis indication, creating a structural divergence between global demand patterns and US market availability. In that context, dienogest appears in combination with estradiol in an oral contraceptive formulation, illustrating how regulatory pathways can redirect product positioning rather than eliminate therapeutic relevance. This divergence is a critical lens for any organization evaluating cross-market expansion, licensing, or partnership opportunities, because the same molecule can function as a specialty therapy in one region and a combined contraceptive component in another.
Reimbursement and pricing access are equally decisive. In Germany, both the originator and generic offerings are reimbursed under statutory health insurance for endometriosis, with monthly pack pricing positioned in the €25–30 range. This reimbursement architecture supports patient continuity and stabilizes demand, but it also imposes pricing discipline that generic entrants must navigate carefully. The existence of reimbursement does not automatically translate into uniform market capture; it creates a structured environment where procurement channels, health-system relationships, and formulary positioning determine how volume is distributed among competing products. For strategy teams, the practical challenge is to model not just approval status but the path to realized access within each health system.
Supply-side dynamics further complicate the picture. The active pharmaceutical ingredient for dienogest is primarily sourced from Indian manufacturers, with export volumes to Europe exceeding 500 kilograms annually. This dependency creates both opportunity and vulnerability. On one hand, it supports a scalable generic supply base that can respond to demand growth and multi-market launches. On the other hand, it concentrates a critical portion of the value chain in a limited set of manufacturing geographies, making supply continuity, quality assurance, and logistics resilience central to commercial execution. Organizations that treat supply chain design as a strategic variable rather than an operational afterthought will be better positioned to manage launch timing, cost control, and market reliability.
Why This Research Matters for 2026 Decision-Making
The 2026 decision environment is defined by timing. Patent-driven exclusivity has given way to a multi-player competitive field, reimbursement pathways are stabilizing in core markets, and supply networks are expanding into higher-growth regions. In this environment, organizations need more than a market size figure; they need a framework for interpreting where value will accrue and what levers will determine outcomes. The Worldwide Dienogest Market study is built to provide that framework. It equips teams to evaluate pipeline and portfolio decisions against realistic share trajectories, to assess pricing and market-access strategies in light of reimbursement and generic pressure, and to align supply and distribution plans with the geographies and channels that will shape demand over the forecast period.
For commercial leaders, the research clarifies where brand equity still commands premium positioning and where generic competition will compress margins and accelerate switching. For market-access and policy teams, it provides the context needed to understand how approval status, reimbursement design, and health-system procurement interact to create or constrain commercial opportunity. For supply chain and manufacturing strategy, it connects API sourcing patterns and export flows to the practical requirements of multi-market launch execution. Taken together, these insights support a more disciplined approach to budgeting, launch sequencing, and partnership selection in a market where decisive timing can separate durable positioning from reactive catch-up.
What Remains Inside the Full Study
The analysis presented here is intended as a professional preview: a demonstration of the strategic depth, structural clarity, and operational relevance that define the full report. The complete study goes further. It breaks down regional demand architecture, product-type value distribution, and application-level commercial logic with the precision required for planning, forecasting, and negotiation. It also maps the competitive field in greater detail, integrating company profiles, recent development timelines, and market-concentration signals into a coherent view of where incumbents, generic challengers, and regional suppliers are positioned to win or lose share.
Readers who need the underlying segmentation values, regional revenue architecture, and formulation-level demand splits will find them inside the full report, along with the interpretive frameworks that translate those figures into decision-ready intelligence. The goal of this preview is not to replace that depth but to show why it matters and how it connects to the strategic questions that 2026 planning teams must answer now. For organizations that treat dienogest as a therapeutic category, a market opportunity, or a competitive battleground, the full Worldwide Dienogest Market research provides the structured intelligence required to move from awareness to action.
For detailed analysis of this topic, please visit the official page: Worldwide Dienogest Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com