

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: System Kitchen Market Hits $38.5B in 2025, Projected to Reach $55.8B by 2032 at 5.45% CAGR
By pmarketresearch, 2026-09-16
2026 Global System Kitchen Market: Navigating Growth, Disruption, and Strategic Positioning
The global system kitchen market stands at a critical inflection point as we move deeper into 2026. Shaped by accelerating urbanization, shifting consumer expectations around modularity and sustainability, and a complex regulatory environment marked by evolving trade policies, the sector presents both substantial growth opportunities and pressing strategic questions for manufacturers, distributors, component suppliers, and real estate developers. Our latest comprehensive market research delivers a rigorously structured view of this landscape, designed not merely to report historical trends but to equip decision-makers with actionable intelligence for the years ahead. Grounded in a robust analytical framework spanning historical performance through 2025 and a forward-looking forecast extending to 2032, this study translates macro shifts into granular operational insights that matter at the boardroom and planning table.
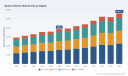
At the macro level, the system kitchen sector has demonstrated consistent expansion over the past half-decade, with total revenue scaling steadily from its 2020 baseline to a projected 38.5 billion USD in 2025. This trajectory reflects durable demand drivers, including residential modernization cycles, the growing preference for pre-configured and customizable kitchen ecosystems, and the ongoing integration of functional design with logistical efficiency. Looking ahead, the forecast period positions the market for continued growth, with a compound annual growth rate of approximately 5.45 percent. By the close of the forecasting horizon in 2032, overall market revenue is expected to reach approximately 55.8 billion USD. These figures are not simply retrospective markers; they represent a structural expansion that demands strategic recalibration across supply chains, product development pipelines, channel strategies, and competitive positioning.
The Strategic Imperative for 2026 Decision-Making
2026 is shaping up to be a defining year for the system kitchen industry. Macroeconomic pressures, trade policy recalibrations, and evolving consumer preferences are converging in ways that reward early movers while penalizing reactive players. For executives and strategy teams, the critical question is no longer whether the market is expanding, but how to allocate resources, prioritize product portfolios, and optimize distribution in a landscape that rewards agility and precision. This research is built to answer that question. Rather than offering generic market commentary, the study dissects the operational, commercial, and competitive dynamics that will determine performance over the next several years. It provides decision-makers with a structured lens to evaluate market entry timing, regional prioritization, component-level investment, and channel mix optimization.
One of the core strategic themes emerging from our analysis is the intersection of sustainability, logistics efficiency, and consumer demand for compact, highly functional kitchen systems. In key geographies, particularly Japan and parts of Europe, buyers are increasingly prioritizing designs that maximize utility within limited footprints while minimizing environmental impact. Manufacturers are responding with innovations that reduce packaging volumes, lower transportation emissions, and streamline assembly and installation. These shifts are not merely product design decisions; they are supply chain, cost structure, and brand positioning decisions that ripple across procurement, manufacturing, and channel relationships. Understanding how these dynamics play out across different market segments is essential for any organization seeking to build a resilient and differentiated positioning strategy.
Core Dimensions of the Study
This market research is structured to provide a full-spectrum view of the system kitchen sector, blending quantitative forecasting with qualitative strategic analysis. The study is organized to support both high-level strategic planning and granular commercial execution. Key dimensions include:
- Market Sizing and Forecast Architecture: A comprehensive revenue model that tracks historical performance from 2020 through 2025 and projects forward through 2032, enabling scenario planning, capacity forecasting, and investment prioritization.
- Segment-Level Diagnostics: A detailed breakdown of market structure across product components and distribution pathways, revealing where value creation is concentrated, where growth is accelerating, and where competitive intensity is reshaping margins.
- Regional Performance Mapping: An analytical overview of geographic demand patterns and structural characteristics, providing the context needed to align go-to-market strategies with regional realities without relying on simplistic one-size-fits-all assumptions.
- Competitive Landscape Assessment: Profiles of leading manufacturers, component suppliers, and value-chain participants, alongside recent product launches, partnership activity, and trade-show-driven innovation showcases that signal where the industry is heading.
- Regulatory and Trade Context: An examination of tariff adjustments, material cost pressures, and policy developments that are reshaping cost structures, sourcing decisions, and competitive dynamics across key export and import markets.
- Consumer and Design Trend Integration: Analysis of how demand for compact functionality, modularity, natural material palettes, and sustainability features is influencing product roadmaps and channel expectations.
Throughout the study, the emphasis is on operational relevance. Readers will find structured insight into how different components contribute to overall market value, how distribution channels shape customer acquisition and pricing dynamics, and how leading firms are adapting their offerings to meet evolving expectations around customization, durability, and environmental responsibility. The research is designed to support product planning, channel strategy refinement, competitive benchmarking, and regional expansion decisions.
Competitive Landscape: Leaders, Innovators, and Structural Shifts
The system kitchen market is characterized by a mix of established manufacturers with deep regional roots, global players with broad modular portfolios, and specialized component suppliers that enable the broader ecosystem. Market concentration remains relatively fragmented, with the top three participants accounting for roughly 18.5 percent of total revenue and the top five holding approximately 26.8 percent. This structure suggests that scale alone is not the sole determinant of advantage; differentiation through design, logistics efficiency, customization capability, and channel relationships continues to play a decisive role.
Several companies illustrate the strategic directions currently shaping the sector. In Japan, LIXIL Corporation has reinforced its leadership in system kitchens by expanding integrated solutions that emphasize functionality, compact design, and logistics efficiency. Its recent introduction of the UL Kitchen system reflects a focused response to labor shortages and distribution challenges, delivering meaningful reductions in packaging volume and associated distribution emissions. This kind of innovation underscores how product architecture and supply chain design are increasingly intertwined in competitive strategy. TOYO KITCHEN STYLE similarly demonstrates the value of lifestyle-oriented design paired with showroom-supported layouts, reinforcing the importance of experiential retail and visual merchandising in driving residential adoption.
In Europe, the competitive picture is defined by both scale and premium positioning. nobilia, recognized as Europe’s largest kitchen manufacturer, continues to leverage high-volume modular production while expanding customization options. Its 2026 collection launch reflects a clear strategic emphasis on natural materials, expanded decors, side panels, handles, and niche panelling options, signaling a broader industry move toward material authenticity and personalized expression. Häcker Kitchens maintains a premium German manufacturing footprint with high daily output, emphasizing quality, sustainability, and international project capabilities. SieMatic occupies a distinct high-end segment, using design-week platforms and external collaborations to reinforce its premium brand identity and demonstrate innovation beyond conventional kitchen manufacturing.
Beyond finished kitchen systems, the competitive ecosystem also includes major component and hardware suppliers such as Hettich, whose fittings and component solutions support manufacturers globally and help shape the functional capabilities of modular and system kitchens. Meanwhile, IKEA continues to exert significant influence as a global leader in affordable modular kitchens, with customizable flat-pack system solutions that have broadened access to structured kitchen design in residential markets. In emerging markets, Godrej Interio illustrates how local manufacturing and partnership-driven premium offerings can align system kitchen solutions with regional space constraints, affordability expectations, and design preferences.
These competitive dynamics are not static. Recent activity, from product collection refreshes and trade-show showcases to logistics-focused system launches, indicates that firms are actively using innovation and brand signaling to differentiate in a market where concentration remains moderate and regional specialization matters. Understanding where each major participant is placing its bets, and how those bets align with broader demand trends, is essential for benchmarking and strategic positioning.
Structural Dynamics Shaping the Market
Several interrelated forces are reshaping the system kitchen market as it moves through 2026 and beyond. One of the most consequential is the evolution of trade policy and tariff structures. Recent adjustments to U.S. tariff levels on imported kitchen cabinets and vanities, including a significant increase effective in early 2026, have introduced new cost and sourcing considerations for manufacturers and distributors operating across borders. Additional country-specific rates affecting major export markets have further complicated trade planning. Alongside these developments, tariffs on softwood lumber and timber imports have added pressure to input costs for kitchen cabinet and modular system production. These shifts are not isolated regulatory events; they are strategic variables that influence sourcing decisions, pricing architecture, margin management, and regional manufacturing footprints.
At the same time, consumer preferences continue to reward design and production strategies that align with sustainability and spatial efficiency. In markets where compact, efficient kitchen designs are in strong demand, manufacturers are increasingly expected to deliver solutions that reduce material waste, lower distribution emissions, and streamline installation without sacrificing aesthetic quality or functional performance. This expectation is reshaping product development priorities and encouraging innovation in packaging, component standardization, and material selection. The result is a market environment in which sustainability and efficiency are no longer peripheral concerns but core elements of competitive differentiation.
Kitchen Sinks Market
Distribution channels also remain a critical strategic axis. The way customers discover, evaluate, and purchase system kitchens continues to vary by region and by buyer profile. Showrooms and specialty dealers remain central to high-consideration purchases, while home centers, retailers, direct sales to real estate developers, and online channels each play distinct roles in broadening access and shaping purchasing behavior. Navigating this multi-channel environment requires a clear understanding of how value is communicated, how customization is supported, and how logistics and service expectations differ across pathways. The strategic challenge is not simply to be present across channels, but to align channel mix with product positioning, margin targets, and customer expectations in a way that reinforces brand integrity and operational efficiency.
Why This Research Matters for 2026 and Beyond
For executives, strategy leaders, and commercial teams operating in the system kitchen sector, the challenge is to move beyond headline growth figures and understand the structural drivers that will determine competitive outcomes. Total market size and forward projections provide essential context, but the real strategic value lies in the deeper analysis of how demand is distributed across components, how channels shape purchase behavior, how trade and material cost dynamics affect profitability, and how leading firms are positioning themselves for the next wave of innovation and regional expansion.
System Kitchen Market
This study is designed to support that deeper understanding. It offers a structured foundation for evaluating where to invest, how to differentiate, and which competitive risks and opportunities deserve the most attention in 2026 planning cycles. By combining forecast discipline with competitive and regulatory context, it helps organizations translate market momentum into practical strategy rather than assuming that growth alone will generate favorable outcomes.
The full research contains detailed segmentation analysis, regional breakdowns, competitive profiles, and forward-looking scenario data that are essential for precise strategic execution. To access the complete intelligence set, including all forecast detail and operational insights, please visit the source webpage for the full System Kitchen Market report and explore the complete dataset, analysis, and strategic recommendations.
For detailed analysis of this topic, please visit the official page: System Kitchen Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Semiconductor Magnetic Sensor Market to Hit $5,995.97M by 2032, 9.0% CAGR
By pmarketresearch, 2026-09-16
Navigating the Magnetic North: Strategic Imperatives in the Global Semiconductor Sensor Landscape
The semiconductor industry stands at a critical inflection point, where the convergence of electrification, automation, and advanced sensing technologies is redefining value chains across the globe. For enterprise leaders and strategic planners, understanding the trajectory of semiconductor magnetic sensors is no longer optional—it is a prerequisite for capital allocation, supply chain resilience, and product roadmap justification. Our latest comprehensive study, the Worldwide Semiconductor Magnetic Sensor Market analysis, provides the granular intelligence required to navigate this complex environment through 2032.
This report serves as a definitive guide for stakeholders aiming to capitalize on the projected expansion of this vital sector. As industries increasingly rely on precise magnetic field detection for everything from electric vehicle powertrains to industrial robotics, the demand for robust, high-sensitivity sensor solutions is accelerating. The following insights outline the macro-environmental drivers, competitive dynamics, and regulatory headwinds that will shape decision-making in 2026 and beyond.
Macro Market Trajectory and Growth Vectors
The historical data from 2020 through 2025 sets a robust foundation for future projections. Over this period, the market has demonstrated resilient growth, moving from a base of approximately $2.15 billion in 2020 to an estimated $3.28 billion by 2025. This upward trajectory reflects the deepening integration of magnetic sensing technologies into core industrial and consumer processes. However, the forecast period from 2026 to 2032 suggests an acceleration in value creation that outpaces recent historical trends.
Our analysis projects the market to reach significant milestones by the end of the decade, driven by a compound annual growth rate (CAGR) of 9.0%. This growth rate indicates a healthy expansion environment, though it is not without volatility. The forecast values indicate a steady climb, suggesting that demand drivers are structural rather than cyclical. For strategic planners, this implies that investments made in 2026 will likely yield compounding returns as the market matures toward 2032. The revenue projections, denominated in USD millions, highlight a market capable of sustaining high-volume production while accommodating premium pricing for advanced technologies such as Tunnel Magnetoresistance (TMR) and Giant Magnetoresistance (GMR).
It is crucial for stakeholders to recognize that this growth is not uniform across all vectors. The momentum is concentrated in specific technological and application domains that are undergoing rapid transformation. Understanding where this growth concentrates allows organizations to prioritize R&D spending and capacity expansion in high-yield areas while mitigating exposure to slower-growing segments.
Segmentation Dynamics: Technology and Application Convergence
The market structure is defined by a diverse array of sensor technologies, each serving distinct performance requirements. Hall Effect sensors continue to hold a substantial share of the value proposition, particularly in applications requiring cost-effective and reliable detection. However, the landscape is shifting toward higher-sensitivity technologies. Magnetoresistive solutions, including AMR, GMR, and TMR, are gaining traction in scenarios demanding greater precision and stability under varying environmental conditions.
Worldwide Semiconductor Magnetic Sensor Market
Magnetic Field Sensors Market
From an application perspective, the automotive sector remains the dominant force driving revenue. The ongoing transition toward electric vehicles and the integration of advanced driver-assistance systems (ADAS) are creating sustained demand for position, speed, and current sensing. Industrial automation constitutes another significant pillar, where the push for smart manufacturing and predictive maintenance is increasing the deployment of magnetic sensors in robotics and motor control systems. Consumer electronics and medical healthcare sectors represent growing niches, where miniaturization and low-power consumption are key differentiators.
Strategic decisions in 2026 must account for the interplay between these segments. For instance, a technology chosen for automotive safety-critical applications may not be suitable for consumer goods due to cost constraints, yet the underlying IP might be leveraged across both. Our report details these cross-segment opportunities without exposing the specific revenue splits that constitute proprietary intelligence within the full dataset.
Competitive Landscape and Strategic Positioning
The market is characterized by a consolidated competitive environment where established players leverage deep portfolios and vertical integration. The top three companies command a significant portion of the market revenue, indicating high barriers to entry for new competitors. The top five firms further extend this influence, controlling over two-thirds of the market share. This concentration suggests that partnership, acquisition, or licensing strategies may be more viable for smaller entities than direct competition on scale.
Leading entities such as Allegro MicroSystems, Infineon Technologies, and NXP Semiconductors are central to this ecosystem. Allegro has been aggressive in expanding its portfolio, particularly following strategic acquisitions that broadened its TMR and current sensing capabilities. Infineon continues to leverage its XENSIV brand to cover a wide spectrum of sensing technologies for automotive and industrial use. NXP remains focused on automotive-specific solutions, emphasizing ultra-low power and reliability.
In the Asia-Pacific region, Japanese manufacturers like Asahi Kasei Microdevices (AKM) and TDK Corporation are pivotal. TDK's recent introduction of compact TMR angle sensors highlights the industry's move toward higher performance in safety-critical contexts. Similarly, STMicroelectronics and Melexis are pushing the boundaries with 3D magnetic position sensors and multi-sensor reference designs. American giants like Honeywell and Texas Instruments maintain strong positions in industrial and aerospace applications, while specialized players like ABLIC and Tower Semiconductor offer niche capabilities ranging from ZCL detection to GaN-based foundry services.
Recent product launches underscore the pace of innovation. STMicroelectronics launched a new industrial multi-sensor reference design featuring ultra-low-power 3-axis magnetic sensors in late 2025. TDK followed with the TAS8240, a compact TMR angle sensor for safety-critical applications. Allegro MicroSystems made significant waves with the ACS37100, the first commercial 10 MHz TMR magnetic current sensor designed for high-speed wide-bandgap power electronics. These launches indicate a clear trend toward higher frequency response, lower power consumption, and enhanced integration.
Geopolitical and Supply Chain Risk Factors
While demand drivers are strong, supply chain resilience remains a paramount concern for 2026 planning. The geopolitical landscape has introduced new complexities, particularly regarding raw materials essential for high-performance magnetic systems. China's dominance in the refining of heavy rare earth elements, holding over 85% of global capacity and approximately 90% of processed dysprosium and terbium supply, creates a potential bottleneck. These materials are critical for the magnets and systems associated with advanced sensor technologies.
Regulatory actions have further tightened the environment. In late 2024 and early 2025, restrictions were imposed on the export of gallium, germanium, antimony, and certain heavy rare earth elements to the United States. These measures were followed by a foreign direct product rule-style measure in late 2025, requiring licenses for foreign-produced rare earth magnets or semiconductor materials containing significant Chinese-origin heavy rare earth elements. Such regulations necessitate a thorough review of tier-2 and tier-3 supply chain dependencies.
Furthermore, trade policy shifts in the United States, including tariffs on certain advanced computing chips and semiconductor imports implemented in early 2026, add another layer of cost and compliance complexity. Organizations must evaluate whether their sourcing strategies are robust against these regulatory fluctuations. Conversely, there are mitigating factors; global battery pack prices fell significantly in 2024, driven by declines in critical minerals prices. This volatility in input costs can ripple through the sensor supply chain, affecting margins and pricing strategies.
For decision-makers, the implication is clear: strategic sourcing and diversification are no longer just operational tasks but competitive advantages. Reliance on single-source geographies for critical materials poses a tangible risk to production continuity and cost stability. The full report provides a risk matrix that maps these regulatory and material constraints against specific market segments, enabling leaders to model contingency plans.
Proprietary Intelligence and Decision Support
The value of this market research extends beyond high-level trends. The complete study offers actionable granularity that is essential for nuanced strategy formulation. While this overview highlights the macro landscape, the full document contains detailed segmentation analysis that breaks down revenue potential by specific technology types and application verticals without aggregating them into broad categories.
Stakeholders will find detailed profiles of key competitors, including their headquarters, strategic focus areas, and recent developmental milestones. This information allows for benchmarking against peers and identifying potential partnership opportunities. The report also includes a comprehensive examination of regulatory impacts by region, helping organizations anticipate compliance requirements in key markets across Asia Pacific, North America, Europe, Latin America, and the Middle East and Africa.
By accessing the full intelligence package, enterprises can quantify the market opportunity with precision, validate internal forecasts against independent data, and identify white spaces for innovation. The data is structured to support financial modeling, inventory planning, and long-term capacity strategy.
Conclusion: Strategic Readiness for 2026 and Beyond
The Worldwide Semiconductor Magnetic Sensor Market is poised for substantial growth, driven by technological advancement and expanding application bases. However, the path to capturing this value is fraught with competitive intensity and supply chain complexities. Success in 2026 will depend on the ability to interpret macro trends through the lens of specific operational realities.
This report provides the foundational intelligence required to make those interpretations with confidence. By understanding the concentration of market power, the trajectory of technological adoption, and the impact of geopolitical regulations, leaders can position their organizations to not only withstand volatility but to leverage it. We invite you to explore the complete findings to unlock the detailed data necessary for securing your strategic advantage in this evolving landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Semiconductor Magnetic Sensor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Used Cooking Oil for SAF Market Hits $2.87B in 2025, Projected 20.31% CAGR to $10.45B by 2032
By pmarketresearch, 2026-09-16
The UCO-to-SAF Imperative: Navigating a $10 Billion Transition by 2032
The aviation industry stands at a critical decarbonization inflection point, and used cooking oil has emerged as one of the most strategically vital feedstock vectors in the sustainable aviation fuel value chain. Our latest market research on the Used Cooking Oil for Sustainable Aviation Fuel market translates a rapidly compounding revenue trajectory into an actionable decision framework for executives, procurement leaders, and energy investors. Drawing on historical performance from 2020 through 2025 and a forward-looking forecast extending to 2032, the analysis captures how feedstock logistics, regulatory mandates, and refining pathway economics are converging to reshape competitive positioning across the global SAF ecosystem.
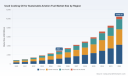
The headline trajectory is unmistakable. Revenue associated with UCO directed toward sustainable aviation fuel applications expanded from roughly $840 million in 2020 to approximately $2.87 billion in 2025, and the forecast arc accelerates sharply thereafter, reaching an estimated $3.49 billion in 2026 and climbing toward $10.45 billion by 2032. This expansion is anchored by a projected compound annual growth rate of 20.31 percent across the 2026–2032 forecast period. For strategy teams, the implication is straightforward: UCO is no longer a peripheral waste-stream story. It is becoming a structurally constrained, policy-driven commodity whose availability, pricing power, and geographic routing will determine which refiners, aggregators, and airline-affiliated fuel buyers can reliably meet blending obligations without incurring margin erosion.
Executing in this environment requires more than top-line forecasting. It demands a clear line of sight into collection-channel economics, conversion-pathway competitiveness, regional supply-chain resilience, and the contractual architectures that major processors are already locking in. The research is designed to deliver that precision without overwhelming decision-makers with undifferentiated data density. Instead, it surfaces the operational and strategic variables that actually move the needle when boards are allocating capital, negotiating offtake terms, or evaluating entry into the HEFA and co-processing value chains.
Why This Research Matters for 2026 Decision-Making
2026 is a pivot year for sustainable aviation fuel procurement and feedstock strategy. Regulatory clocks have already started ticking in key markets, and the earliest compliance cycles are exposing the operational realities of scaling UCO-dependent production. The European Union’s ReFuelEU Aviation mandate requires a 2 percent SAF blending baseline from January 2025, climbing toward 6 percent by 2030, with UCO-based HEFA positioned as the dominant compliant pathway in the near term. In the United Kingdom, the SAF mandate took effect in January 2025 with a 2 percent target, and provisional data from the first ten months of 2025 indicated that 1.63 percent was achieved, entirely from UCO feedstock. These early compliance readings matter because they reveal both the speed at which demand can materialize and the dependency that emerges when a single feedstock category carries the bulk of early blending requirements.
On the incentive side, the United States Section 45Z clean fuel production credit provides up to $1 per gallon for SAF through 2029 under updated legislation, with eligibility restricted to North American feedstocks. That restriction changes the strategic calculus for anyone modelling U.S. production economics or planning feedstock sourcing across borders. Meanwhile, trade dynamics are reshaping physical supply routes: U.S. imports of UCO from China declined significantly in 2025 due to tariff pressure, pushing sourcing activity toward Australia, South Korea, and Malaysia even as total import volumes remained robust at approximately 2 million metric tons through November 2025. These are exactly the kinds of structural shifts that can undermine a supply plan if they are treated as background noise rather than core inputs to scenario design.
Used Cooking Oil for Sustainable Aviation Fuel Market
The research therefore treats feedstock availability as a strategic risk variable, not a static assumption. It maps how collection infrastructure, pre-processing capacity, and long-term supply commitments interact with policy timelines, so that executives can stress-test their SAF sourcing strategies against realistic constraints instead of optimistic averages.
What the Report Covers: An Operational Roadmap, Not Just a Forecast
The study is built around practical decision support. Beyond the macro revenue trajectory and multi-year forecast, the report examines the structural segmentation that determines where value accrues and where bottlenecks form. It analyzes collection and supply channels including food service collection, industrial food processing, and household collection, with attention to how each channel’s logistics profile affects scalability, contamination risk, and feedstock consistency. It also evaluates application pathways, particularly the HEFA production pathway and refinery co-processing, explaining how capital intensity, conversion yields, and integration with existing refining assets shape competitiveness across different operator profiles.
Worldwide Kenaf Seed Oil Market
Regional analysis is presented to help teams understand where supply depth, processing infrastructure, and policy momentum are most aligned. Rather than forcing a single narrative, the research disaggregates market behavior so that strategy leaders can identify which geographies offer the most reliable feedstock aggregation, where co-processing assets are best positioned to absorb waste oils, and where import dependency may create vulnerability under shifting trade or tariff regimes.
Equally important, the report connects quantitative structure to real-world industry movement. It incorporates recent developments that illustrate how the market is actually behaving as procurement contracts, production ramp-ups, and partnership agreements begin to lock in supply for the 2026–2030 window. These activity signals are essential for interpreting whether observed price behavior reflects temporary tightness or a more durable re-rating of UCO as a premium SAF feedstock.
Competitive Positioning in a Concentrated but Fragmented Value Chain
The competitive landscape reveals a market that is consolidated at the top yet highly dependent on a broad network of collectors, processors, and integrators. Market concentration data indicates a CR3 of approximately 38.4 percent and a CR5 of about 52.15 percent, suggesting that while leading players hold meaningful share, a substantial portion of supply and conversion capacity remains distributed across specialized operators. For entrants and incumbents alike, the strategic question is less about aggregate share than about securing dependable feedstock flow, differentiating by conversion route, and building long-term contractual insulation against price volatility.
Among the most prominent players, Neste stands out as a global leader in renewable fuels with extensive UCO collection and processing networks, including assets acquired in the United States, feeding HEFA-based SAF production across multiple refineries through dedicated UCO-to-SAF pathways. Darling Ingredients operates through its Diamond Green Diesel joint venture, supplying UCO and other waste feedstocks and delivering neat SAF produced from UCO, animal fats, and other renewables. Greenergy International functions as a major collector and supplier of UCO for biofuel and SAF production, supported by established European and international aggregation networks that reinforce HEFA pathway supply. In the UK, Olleco specializes in UCO collection and pre-processing for conversion into biodiesel and SAF feedstocks, while Brocklesby Ltd collects and processes UCO into refined feedstock specifically for sustainable aviation fuel production. Argent Energy focuses on waste-based feedstocks including UCO for advanced biofuels and SAF.
Across the Atlantic, Baker Commodities Inc. provides UCO collection and recycling services that supply feedstock for renewable diesel and SAF facilities, and Mahoney Environmental Inc. operates as a UCO collection specialist delivering feedstock directly into Neste’s SAF production. Quatra supplies large volumes of European UCO under long-term agreements for processing into SAF at biorefineries. Sanimax collects and processes animal fats and UCO for renewable fuel and SAF applications across Canada and the United States. Münzer Bioindustrie GmbH processes UCO and waste oils into biofuels with SAF feedstock capabilities. World Energy operates biorefineries converting UCO into high volumes of SAF. EcoCeres converts UCO and agricultural waste into SAF and other fuels using proprietary technology. In Asia, PT Pertamina has completed its first SAF shipment from UCO and is developing co-processing capabilities for UCO-based SAF, while Sinopec operates UCO-based bio-aviation fuel plants using proprietary SRJET technology. TotalEnergies receives UCO supplies for biorefineries producing SAF and operates co-processing units using waste oils. XCF Global Inc., through its New Rise Renewables operations, runs HEFA SAF facilities using waste- and residue-based feedstocks including UCO.
What makes this competitive set strategically interesting is not simply the roster of names, but the pattern of recent commitments and operational milestones. In August 2025, PT Pertamina completed its first shipment of aviation fuel produced from used cooking oil, signaling state-backed momentum in UCO-based SAF adoption. In July 2025, Quatra signed a 15-year agreement to supply TotalEnergies with 60,000 tons of European used cooking oil annually starting in 2026 for biodiesel and SAF processing, illustrating how long-duration contracts are being used to stabilize feedstock access. In December 2024, Darling Ingredients delivered its first batch of neat SAF produced using UCO and other renewable feedstocks via Diamond Green Diesel to Avfuel Corporation, marking a concrete step in distributed neat-SAF supply. In February 2025, XCF Global’s New Rise Reno facility began ramp-up with HEFA technology using waste feedstocks, with SAF production expected to resume in early 2026. In March 2025, Cosmo Oil partnered with SAFFAIRE SKY ENERGY, Suita City, JGC Holdings, and REVO International to promote domestic UCO collection for Japan’s first large-scale locally-made SAF production targeting 30,000 kiloliters per year.
These moves matter because they show the market hardening around long-term supply architecture. A collector secures a 15-year off-take commitment; a refiner brings a HEFA line back into ramp-up; a state-owned energy company executes its first UCO-based SAF shipment; a domestic consortium organizes around localized collection to reduce import dependency. Each event is a data point in a broader pattern: the companies that can combine reliable collection, credible processing credentials, and policy-aligned conversion pathways are positioning themselves to capture the most durable margins as mandates intensify.
Feedstock Economics, Regulatory Tailwinds, and the 2026–2032 Window
Pricing behavior in the UCO market has become an integral part of SAF project economics. Indicative bulk UCO prices in 2025–2026 reached the $750–$1,250 per ton range in Europe and North America, with spikes above $1,400 per ton in tight markets, driven by rising SAF and biodiesel demand. For procurement and finance teams, this range is not just a commodity note; it is a margin sensitivity variable that interacts directly with blending mandates, incentive eligibility, and the competitiveness of alternative feedstocks. When UCO prices spike, the economic advantage of co-processing configurations, regional sourcing diversification, and long-term fixed-price or indexed contracts becomes more pronounced.
Regulatory alignment is amplifying that sensitivity. The EU ReFuelEU Aviation mandate’s progressive ramp from 2 percent to 6 percent by 2030 establishes a multi-year demand floor that favors feedstocks capable of meeting compliance requirements at scale. UCO-based HEFA has emerged as the dominant compliant pathway in the early years, which means that near-term policy implementation is disproportionately channeling demand toward the very feedstock category this research analyzes. In parallel, the UK mandate’s early attainment figures, entirely from UCO feedstock, underscore how quickly a market can become concentrated around a single supply base when compliance timelines are immediate and alternatives are limited.
In the United States, the Section 45Z credit creates a different kind of strategic filter. Because eligibility is restricted to North American feedstocks, the incentive architecture favors domestic and regionally sourced supply chains over imported alternatives, reinforcing the importance of collection networks, preprocessing capacity, and feedstock traceability within the eligible geography. This is one of the reasons the report pays close attention to how trade flow changes, such as the 2025 decline in U.S. UCO imports from China and the corresponding pivot toward Australia, South Korea, and Malaysia, can alter both cost structures and compliance positioning.
From Intelligence to Action
The broader takeaway for 2026 planning is that UCO for sustainable aviation fuel is evolving from an opportunistic sustainability narrative into a tightly contested supply-chain business. The revenue outlook suggests a market moving toward the $10.45 billion range by 2032, but the strategic prize will not go to organizations that simply recognize the growth trend. It will go to those who can map their feedstock access, conversion strategy, and regulatory exposure onto a coherent plan before mandates, incentives, and competitor contracts reshape the landscape.
This research is designed to support that planning with granular segmentation, competitive profiling, and market-dynamic analysis that can be translated directly into sourcing strategy, capacity evaluation, and risk management. The full study provides the detailed regional and segment breakouts, company-level analysis, and scenario-ready context that executives need to move from awareness to execution. For teams responsible for SAF procurement, renewable fuel investment, or feedstock portfolio strategy, the complete report offers the depth required to make 2026 decisions with confidence rather than conjecture.
For detailed analysis of this topic, please visit the official page: Used Cooking Oil for Sustainable Aviation Fuel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive ISOFIX Mounts Reach $1.05B in 2025, Expanding to $1.6B by 2032 at 6.25% CAGR
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Automotive ISOFIX Mounts Market: Navigating Growth and Compliance Through 2032
The automotive safety ecosystem is undergoing a fundamental transformation, driven by rigorous regulatory frameworks and an increasing consumer demand for child passenger safety. At the heart of this evolution lies the ISOFIX mounting system, a standardized attachment mechanism that has become critical for securing child restraint systems within vehicles. For industry stakeholders, understanding the trajectory of the Automotive ISOFIX Mounts Market is not merely an exercise in data analysis; it is a strategic necessity for capital allocation, product development, and supply chain resilience.
Our latest comprehensive study, the Worldwide Automotive ISOFIX Mounts Market research, offers a granular view of this sector. This article serves as a strategic briefing, highlighting the macro-economic drivers and regulatory currents shaping the landscape from 2026 through 2032. While we outline the broad contours of opportunity here, the full depth of segmentation, competitive intelligence, and quantitative forecasts is reserved for our detailed report, designed to equip decision-makers with actionable intelligence.
Market Trajectory and Financial Outlook
The financial narrative of the ISOFIX mounts market reflects a steady upward trend, underpinned by vehicle production growth and mandatory safety installations. Analyzing historical data from 2020 to 2025 provides a baseline for understanding market maturity. In 2020, the global market revenue stood at approximately 785.4 million USD. Over the subsequent five years, the market experienced consistent expansion, reaching 1050.0 million USD by the base year of 2025.
Looking forward, the forecast period from 2026 to 2032 suggests continued momentum, albeit with varying rates of acceleration across different phases. The market is projected to surpass the 1.6 billion USD mark by 2032. This growth trajectory is supported by a Compound Annual Growth Rate (CAGR) of 6.25 percent during the forecast period. Such figures indicate a mature yet expanding market where volume growth is often tied to regulatory mandates in emerging automotive hubs and the replacement cycle in established markets.
It is crucial for strategic planners to note that while the aggregate numbers paint a picture of health, the distribution of this value is heavily influenced by regional manufacturing capabilities and vehicle type segmentation. The shift from historical stability to future expansion requires companies to align their capacity planning with these projected revenue milestones, ensuring that infrastructure investments match the anticipated demand surge in the latter half of the decade.
Regulatory Landscape as a Growth Catalyst
Regulations are the primary engine driving standardization and, consequently, market demand for ISOFIX components. The industry is currently navigating a complex web of international safety standards that dictate design specifications and installation protocols.
UNECE Standards and i-Size Mandates
In Europe and many other jurisdictions, the United Nations Economic Commission for Europe (UNECE) regulations hold significant sway. Within UNECE R129, commonly known as i-Size, ISOFIX is mandatory for the i-Size category. This regulation aims to ensure universal vehicle compatibility and significantly reduce incorrect installations, which have historically been a major safety risk. The mandate creates a compliance-driven demand where vehicle manufacturers must equip cars with standardized anchor points, and child seat producers must design around these fixed points.
Furthermore, the evolution of these standards is ongoing. During the GRSP-77 session in May 2025, there was discussion on the potential evolution of ISOFIX 3.0. Building on 30 years of the standardized attachment system, these discussions signal that the technology is not static. Companies must remain agile to adapt to potential iteration in mounting mechanisms or strength requirements that could arise from these standardization bodies.
NHTSA and Side-Impact Protection
In the United States, the National Highway Traffic Safety Administration (NHTSA) continues to tighten safety requirements. Ongoing implementation preparations for FMVSS 213a, focusing on side-impact protection standards, are affecting child restraint systems that utilize ISOFIX mounts. This standard requires enhanced side-impact testing for child car seats under 40 pounds. The compliance date has been extended to December 5, 2026, which impacts the design and validation of ISOFIX-compatible restraints.
This regulatory update creates a specific pressure point for manufacturers. It is not enough to simply meet anchorage strength requirements; the interaction between the mount and the restraint system must withstand higher lateral forces. Anchorage strength and positioning must meet specific ECE R44/ECE R129 and FMVSS requirements to prevent anchorage failure or seat damage during use. For component suppliers, this means material science and structural integrity testing are becoming more critical than ever before.
Competitive Landscape and Key Players
The market structure is characterized by a moderate level of concentration, with key players holding significant sway over supply chains and technological standards. Our analysis indicates a CR3 of 42.5 percent and a CR5 of 58.8 percent, suggesting that while there are dominant entities, there is still room for specialized manufacturers and regional players to capture value.
The competitive environment is defined by companies that specialize in the precision engineering of safety components. Leading entities include:
- Holmbergs (Sweden): This company specializes in ISOFIX/LATCH connectors, arms, straps, tethers, and adjusters. They supply global child car seat manufacturers, focusing on the secure vehicle anchoring ecosystem. Their strategic position lies in their integration with child seat producers who require high-reliability connectors.
- Ningbo Welldon Infant and Child Safety Technology Co., Ltd. (China): As a manufacturer of ISOFIX mounting points, anchors, and related child safety seat components, Welldon represents the significant manufacturing capacity located in Asia. Their focus on automotive applications makes them a key supplier for vehicle OEMs and tier-one safety component integrators.
- IMMI (United States): IMMI produces ISOFIX anchorages, LATCH attachments, snap hooks, and child seating components. They are notable for their compliance with global safety standards including FMVSS and ECE. Their location in the US positions them strategically to navigate North American regulatory changes such as FMVSS 213a.
- Quanzhou Kwok Shing Automotive Subassembly Co., Ltd. (China): This firm supplies ISOFIX systems and rigid baby car seat components as automotive subassemblies. Their role highlights the trend towards modular subassemblies that can be integrated directly into vehicle production lines or child seat manufacturing processes.
These companies are not merely competing on price; they are competing on certification, reliability, and the ability to adapt to evolving regulatory standards. The interplay between Swedish design specialization, American regulatory compliance expertise, and Chinese manufacturing scale defines the current competitive dynamics. Strategic partnerships between vehicle manufacturers and these component suppliers are essential to ensure that the final assembly meets the rigorous crash load requirements.
Technical Dynamics and Material Considerations
The engineering behind ISOFIX mounts is driven by the need for structural integrity under crash loads. ISOFIX mounts and anchors are primarily constructed from high-strength steel or alloy steel. This material choice is non-negotiable, as the components must withstand significant force without deformation or failure during an accident.
The technical specifications are tightly linked to the regulatory environment. ISOFIX anchorage strength and positioning must meet specific ECE R44/ECE R129 and FMVSS requirements. Any deviation can lead to anchorage failure or seat damage during use, posing severe liability risks for automakers and component suppliers. As vehicle designs evolve towards lighter materials and different chassis structures, the integration of these steel mounts becomes a challenge in itself. Engineers must ensure that the mounting points do not compromise the structural integrity of the vehicle floor or seat rails while still providing the rigid connection required for child safety.
Moreover, the supply chain for these high-strength materials is subject to global commodity fluctuations. Strategic procurement strategies are required to mitigate cost volatility without compromising the quality standards mandated by safety regulations.
Strategic Focus for OEMs and Aftermarket
The market is broadly divided by sales channel, with distinct implications for different business models. The Original Equipment Manufacturer (OEM) channel represents the larger portion of the market revenue. This segment is driven by vehicle production volumes and the mandatory inclusion of ISOFIX points in new car models. For suppliers targeting this segment, long-term contracts and qualification processes with automotive OEMs are critical. The revenue flow here is stable but subject to the cycles of the automotive industry.
Conversely, the Aftermarket segment serves a different need. While smaller in total revenue compared to OEM, it represents a vital channel for retrofitting older vehicles or replacing damaged components. As the fleet of vehicles equipped with ISOFIX grows, the aftermarket demand evolves from installation assistance to replacement parts for wear and tear or post-accident repair. Companies operating in this space must maintain broad compatibility across various vehicle models and generations.
Understanding the split between these channels is vital for revenue forecasting. While the OEM channel drives volume through new car sales, the aftermarket offers recurrent revenue opportunities and niche customization possibilities. A balanced portfolio strategy often involves servicing both streams to mitigate the risk of production slowdowns in the automotive sector.
Regional Growth Vectors
Geographically, the market exhibits distinct characteristics based on vehicle ownership rates and regulatory adoption. Asia Pacific remains a critical region, driven by high vehicle production volumes and increasing awareness of child safety standards. Europe continues to be a mature market where regulations like i-Size drive consistent demand for compliant mounts. North America presents a specific regulatory environment focused on FMVSS compliance and side-impact enhancements.
Latin America and the Middle East and Africa represent emerging vectors where vehicle fleet modernization and the import of safety-standard-compliant vehicles are gradually increasing the uptake of ISOFIX systems. However, the pace of adoption in these regions is influenced by economic factors and the penetration of standardized child restraint systems. Strategic expansion into these regions requires a nuanced understanding of local regulatory enforcement and consumer behavior regarding child safety.
Conclusion: The Value of Detailed Intelligence
The Automotive ISOFIX Mounts Market is at a intersection of regulatory pressure, technological evolution, and steady market growth. The projected increase to over 1.6 billion USD by 2032 offers significant opportunity, but realizing this value requires navigating complex compliance landscapes and supply chain dynamics. The upcoming changes in FMVSS 213a and potential evolutions in UNECE standards mean that static strategies will fail.
Engine Mounts Market
For executives and strategy teams, the high-level trends are clear, but the path to capturing market share lies in the details. Which specific vehicle segments are driving the highest growth rates? How do supply chain vulnerabilities in specific regions impact lead times? What are the precise design constraints imposed by the new side-impact regulations?
Worldwide Automotive ISOFIX Mounts Market
Our full Worldwide Automotive ISOFIX Mounts Market research report delves into these specifics. It provides the segmented data, the competitive profiles, and the granular forecast models necessary to build a robust strategic plan. We invite you to access the complete study to unlock the full depth of this intelligence and ensure your organization is positioned to lead in the next era of automotive safety.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive ISOFIX Mounts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Copaiba Oil Market Hits $148.5M in 2025, Projects 7.2% CAGR to $241.6M by 2032
By pmarketresearch, 2026-09-16
Strategic Horizons: Navigating the Global Copaiba Essential Oil Market Through 2032
The global essential oils sector stands at a critical inflection point, where botanical versatility meets escalating demand for clean, sustainable ingredients across wellness, cosmetic, and pharmaceutical verticals. Within this complex landscape, Copaiba essential oil has emerged as a compelling asset class, driven by its unique chemical profile, traditional therapeutic applications, and growing integration into modern consumer products. As industry participants prepare for the next cycle of growth, understanding the macroeconomic trajectory, competitive architecture, and regulatory undercurrents of this niche market is no longer optional—it is a strategic imperative.
Our latest Worldwide Copaiba Essential Oil Market research provides a rigorous, data-driven framework for stakeholders aiming to capitalize on the projected expansion through 2032. This overview outlines the market's historical momentum, near-term catalyst landscape, competitive positioning, and the analytical depth embedded in our full report. The objective is to equip executives, procurement leaders, and product developers with the contextual intelligence required to make informed, forward-looking decisions in an increasingly fragmented and sustainability-centric value chain.
Worldwide Copaiba Essential Oil Market
Historical Trajectory and Forecasted Growth Dynamics
Between 2020 and 2025, the global Copaiba essential oil market established a firm foundation through expanding consumer awareness, innovative extraction methodologies, and the formalization of sustainable sourcing protocols across key origin regions. The base year assessment reflects a market that has matured beyond early-stage experimentation into a structured commercial ecosystem. Steady year-over-year valuation increases during this historical window underscore the product's successful migration from niche herbal applications into mainstream cosmetic formulations, wellness supplements, and specialty fragrance compounds.
Moving into the forecast horizon of 2026 through 2032, the market is projected to sustain a compound annual growth rate of 7.2%. This trajectory signals more than incremental expansion; it indicates structural demand acceleration driven by formulation innovation, cross-industry adoption, and the premiumization of botanical ingredients. The valuation progression from the 2026 baseline through to the terminal forecast year reflects a compounding effect of new market entrants, geographic diversification, and the monetization of clinically backed or sustainably certified product variants. Stakeholders who align their supply chain resilience, brand positioning, and R&D investments with this forecasted cadence are positioned to capture disproportionate share during the growth window.
The underlying demand architecture continues to be shaped by an interplay of end-use breadth and quality differentiation. As manufacturers seek ingredients that simultaneously satisfy sensory expectations, stability requirements, and clean-label mandates, Copaiba's dual utility as both a functional botanical and an aromatic carrier positions it advantageously. The market's evolution will increasingly reward players who can articulate clear value propositions across therapeutic, cosmetic, and industrial gradations while maintaining supply integrity and regulatory compliance.
Value Chain Architecture and Segmentation Intelligence
A nuanced understanding of the Copaiba essential oil market requires dissecting how revenue distributes across geographic territories, quality specifications, and application channels. Our analysis maps these dimensions not as isolated silos, but as interconnected nodes that dictate pricing power, sourcing strategy, and go-to-market execution. The regional landscape reveals a market where established consumer maturity and robust distribution infrastructure coexist alongside emerging demand centers that are actively building local processing capacity and import dependencies.
Demand is not evenly distributed across end-use categories. The application matrix demonstrates how cosmetic and personal care formulations currently anchor the largest share of commercial activity, capitalizing on Copaiba's emollient properties, natural aroma profile, and compatibility with clean beauty trends. Pharmaceutical and nutraceutical applications represent a secondary but rapidly evolving vector, where standardized extracts, softgel formulations, and bioactive research are opening premium pathways. Simultaneously, aromatherapy, wellness blending, and specialty flavor or fragrance uses continue to expand, supported by direct-to-consumer education and influencer-driven discovery cycles.
Cypress Essential Oil Market
Grade differentiation further modulates market behavior. Therapeutic-grade material commands heightened scrutiny around purity, traceability, and clinical or traditional efficacy claims, while food-grade and industrial-grade variants serve distinct regulatory and formulation requirements. The relative weighting of these categories influences procurement strategies, from bulk commodity hedging to specialized small-batch sourcing. Understanding how each grade interacts with regional supply availability and end-market price elasticity is essential for companies optimizing inventory allocation, contract negotiation, and product line extension.
From a supply-side perspective, the origin ecosystem remains anchored by producers operating within the Amazon biome, where oleoresin extraction from Copaifera species underpins the raw material pipeline. The integration of agroextractivist partnerships, cooperative models, and fair-trade frameworks has shifted sourcing from a purely extractive paradigm to one emphasizing sociobiodiversity preservation and community economic security. These practices are increasingly viewed not only as ethical imperatives but also as risk-mitigation instruments that stabilize long-term supply continuity amid environmental and regulatory pressures. Recent corporate disclosures reinforce this shift, highlighting collaborative sourcing journeys and low-impact harvesting protocols designed to maintain product quality while safeguarding collector livelihoods and ecosystem integrity.
Competitive Landscape: Strategic Positioning and Differentiation Vectors
The Copaiba essential oil market features a heterogeneous mix of multinational ingredient groups, regional Latin American producers, and specialized Western distributors, each competing through distinct lenses of scale, authenticity, certification, and application expertise. Competitive advantage in this space rarely stems from price alone; it emerges from the ability to reliably deliver consistent chemotype profiles, validate sustainability claims, and provide technical support tailored to downstream formulation needs.
Leading global wellness and essential oils enterprises have built expansive brand ecosystems that pair direct-to-consumer marketing with rigorous internal research initiatives. One prominent player has emphasized Co-Impact Sourcing networks that connect Brazilian Amazon communities with structured procurement pathways, translating socioenvironmental commitments into branded product lines spanning pure oils and encapsulated softgel formats. Concurrently, this company has advanced its scientific credibility by publishing detailed human clinical investigations examining cellular, molecular, and microbiome-level interactions, reinforcing a positioning rooted in evidence-informed wellness.
On the industrial and ingredients side, integrated chemical and specialty groups have leveraged local sourcing relationships to secure steady access to Amazonian raw materials while embedding sociobiodiversity and fair-trade principles into their operating models. Partnerships with cooperatives illustrate a supply chain philosophy that prioritizes transparent compensation structures and low-impact harvesting, aligning commercial output with biodiversity protection standards. These initiatives are increasingly cited in corporate sustainability communications, signaling to buyers that ethical provenance is becoming a procurement criterion rather than an optional accessory.
Specialty bulk suppliers and fragrance-focused producers occupy another strategic layer, often competing on consistency, origin transparency, certification portfolios, and technical service. Companies with established relationships across multiple origin points can buffer against seasonal or logistical variability, offering downstream formulators greater predictability. Meanwhile, organic-certified distributors and herbal-focused retailers continue to build loyalty through curated quality standards, educational content, and niche application expertise in aromatherapy and personal care. The resulting ecosystem is characterized by overlapping yet distinct value propositions, where scale, traceability, clinical or traditional validation, and format adaptability collectively determine share dynamics.
Recent corporate activity illustrates the breadth of strategic maneuvering shaping the market. High-profile sustainability partnerships have brought Amazon cooperative sourcing into sharper focus, while clinical research publications have sought to substantiate functional benefit narratives at a physiological level. For competitors and new entrants alike, these signals carry strategic weight: they demonstrate that credibility is increasingly constructed through visible supply chain ethics and scientifically grounded communication, not merely through product availability.
Regulatory, Sustainability, and Sourcing Dynamics
Market evolution in Copaiba essential oil is tightly coupled to regulatory expectations and sustainability mandates that are becoming more explicit across buyer organizations and origin jurisdictions. As end-users and brand owners incorporate biodiversity protection, ethical procurement, and traceability into vendor qualification criteria, suppliers who can document compliant harvesting practices, fair economic impact, and low ecological disturbance gain preferential access to premium contracts. This trend is especially pronounced in cosmetic and personal care segments, where clean-label narratives and responsible sourcing claims are subject to heightened consumer scrutiny and internal compliance review.
Forestry and biodiversity regulations governing the Amazon biome further influence how raw materials are harvested, transported, and certified. Producers reliant on conventional vs. cooperative or certified models face different cost structures, administrative burdens, and reputational exposure. As a result, sourcing strategy has evolved into a multidimensional challenge that balances yield stability, quality consistency, audit readiness, and community impact. Companies that invest early in supplier mapping, documentation infrastructure, and partnership transparency are better equipped to navigate volatility and demonstrate resilience to institutional buyers.
What the Full Research Delivers: Analytical Depth for Decision-Makers
Our complete market study extends far beyond high-level growth narratives. It is structured to support operational planning, competitive benchmarking, and investment prioritization across multiple functional teams. The report integrates historical baselines, forecast modeling, and segmentation intelligence into an actionable format that enables readers to assess market entry suitability, channel expansion opportunities, and supply chain optimization pathways.
Inside the full publication, stakeholders will find detailed analysis covering regional demand profiles, grade-specific commercial behaviors, and application-level adoption trends, along with quantitative estimates that clarify revenue distribution without exposing proprietary granular breakdowns in this summary. The competitive section profiles key companies by headquarters, sourcing philosophy, product formats, and strategic focus, supplemented by recent corporate developments that illuminate where incumbents are directing attention. Additional components examine raw material origins, extraction methodologies, certification landscapes, and regulatory considerations that shape procurement risk and formulation compatibility.
The research is designed for multiple use cases. Product developers can align ingredient selection with grade availability and application performance expectations. Procurement leaders can benchmark supplier types and assess sourcing model trade-offs. Commercial strategists can evaluate where differentiation through sustainability claims, clinical narratives, or format innovation is likely to yield stronger positioning. Investors and analysts can use the structural overview to frame portfolio exposure and identify segments where growth is most concentrated.
Strategic Imperatives for 2026 and Beyond
As the forecast period unfolds, several strategic priorities will distinguish adaptable organizations from those caught reacting to market shifts. First, supply chain resilience must be treated as a competitive asset. Diversifying origin relationships, verifying certification integrity, and maintaining contingency pathways can mitigate the impact of environmental, logistical, or regulatory disruptions. Second, communication credibility matters. Claims around sustainability, ethical compensation, and functional benefits increasingly require substantiation through documented sourcing practices, research integration, or certification frameworks. Third, application breadth should be approached with discipline. While cosmetic and personal care channels currently anchor volume, pharmaceutical, aromatherapy, and specialty flavor or fragrance segments offer differentiated margin profiles and require tailored technical alignment.
Companies that treat Copaiba essential oil as a dynamic ingredient platform—rather than a static commodity—will be better positioned to respond to evolving consumer expectations, formulation trends, and procurement standards. The intersection of projected growth, sustainability-driven sourcing, and application expansion creates a period where informed strategic action can yield durable advantage.
To access the complete dataset, segmentation estimates, company profiles, regional demand breakdowns, and forecast modeling that underpin this analysis, we invite decision-makers to explore the full Worldwide Copaiba Essential Oil Market research. The full report delivers the operational precision and contextual depth required to convert market intelligence into executable strategy across the 2026 to 2032 horizon.
For detailed analysis of this topic, please visit the official page: Worldwide Copaiba Essential Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Managed Office Market Hits $48.5B in 2025, Poised to $117.2B by 2032
By pmarketresearch, 2026-09-16
Navigating the Future of Work: Strategic Imperatives in the Global Managed Office Market
The global workplace is undergoing a structural metamorphosis. No longer viewed merely as a cost center or a static asset, the office has evolved into a strategic instrument for talent retention, operational agility, and brand expression. As organizations grapple with the enduring legacy of hybrid work models and shifting real estate economics, the managed office sector has emerged as a critical pivot point for corporate real estate strategy. Our latest Worldwide Managed Office Market research provides a comprehensive roadmap for navigating this complex landscape through 2032.
This report is not merely a collection of statistics; it is a strategic asset designed to empower C-suite executives, real estate occupiers, and investment stakeholders with the foresight necessary to make informed decisions in 2026 and beyond. By dissecting the market dynamics, competitive contours, and operational challenges, we offer clarity amidst the noise of a rapidly evolving industry.
Macro Trajectory and Market Magnitude
The managed office industry has demonstrated remarkable resilience and growth, outperforming traditional commercial real estate segments in recent years. Our analysis tracks a robust historical trajectory from 2020 through 2025, setting the stage for an aggressive forecast period extending to 2032. The market has expanded significantly from its baseline in the early 2020s, reflecting the accelerated adoption of flexible work solutions driven by technological enablement and changing workforce expectations.
Looking forward, the growth momentum is expected to sustain a strong compound annual growth rate (CAGR) over the forecast period. This expansion is underpinned by a fundamental shift in how enterprises approach space utilization. Rather than committing to long-term leases for fixed capacity, organizations are increasingly leveraging managed office solutions to align physical footprints with fluctuating headcount and project-based needs. This shift transforms office space from a liability on the balance sheet into a variable operational expense that scales with business activity.
The valuation of the market in the coming years underscores the liquidity and investor confidence in this sector. However, understanding the aggregate number is only the first step. The true strategic value lies in understanding the velocity of this growth and the specific drivers that will differentiate high-performing markets from laggards. Our research delves into these velocity drivers, offering a nuanced view of where capital and operational focus should be directed to maximize return on occupancy.
Operational Dynamics and External Pressures
The managed office ecosystem does not operate in a vacuum. It is subject to a complex web of external pressures that influence pricing, availability, and service delivery models. A primary constraint is the global office vacancy rate, which reached significant levels in late 2023. This surplus of traditional space exerts downward pressure on lease terms, forcing managed office providers to innovate their value propositions. Providers must now justify premium pricing through superior service integration, technology infrastructure, and community amenities that vacant traditional buildings cannot offer.
Labor costs represent another critical variable. The median hourly wage for facilities support services has seen upward pressure, reflecting broader inflationary trends and labor shortages in the support sector. For managed office operators, this translates to increased operational expenditures that must be managed without eroding margins or service quality. Our analysis examines how leading firms are mitigating these costs through automation and optimized staffing models while maintaining the hospitality-grade service that defines the premium managed office experience.
Regulatory environments are also tightening, particularly regarding sustainability. Emerging directives, such as those mandating minimum energy efficiency standards for non-residential buildings, will necessitate significant capital expenditure for operators managing older assets. Compliance is no longer optional; it is a prerequisite for market access in key jurisdictions. Furthermore, geopolitical factors, including export controls on IT hardware, have introduced volatility into the cost structures for technology setups within these spaces. These factors collectively shape the risk profile of entering new regions or scaling existing operations.
On the demand side, the permanence of hybrid work models cannot be overstated. A majority of global companies have institutionalized hybrid arrangements, creating a sustained demand for flexible managed offices that support distributed teams. The office is no longer the default location for every workday; it is becoming a destination for collaboration, culture building, and specialized work. Managed offices that facilitate this shift—by offering bookable collaboration zones, high-quality meeting infrastructure, and seamless technology integration—are best positioned to capture this demand.
Competitive Landscape and Strategic Positioning
The market is characterized by a diverse mix of global giants, regional specialists, and niche hospitality-driven operators. Market concentration remains relatively fragmented, meaning there is ample room for strategic differentiation and consolidation. Understanding the competitive tactics of key players is essential for both occupiers seeking partners and investors evaluating market entry opportunities.
IWG plc stands as a dominant force, operating thousands of locations under recognized brands like Regus and Spaces. Their strategy emphasizes volume and global consistency, providing fully serviced flexible workspaces that integrate IT, reception, and facilities management. Their recent financial performance highlights sustained revenue growth and continued physical expansion, reinforcing their position as a benchmark for scale in the industry.
WeWork, despite recent financial turbulence, remains a significant player in the cultural narrative of flexible work. Their restructuring efforts have focused on debt reduction and operational continuity, allowing them to maintain a presence in over 120 cities. Their emphasis on community amenities and enterprise-grade services continues to attract startups and established enterprises alike, though their financial stabilization remains a key watchpoint for partners.
Worldwide Managed Office Market
In the premium segment, companies like Servcorp and The Executive Centre focus on high-quality, furnished spaces with global IT infrastructure and concierge-level support. Servcorp's recent launch of a dedicated managed office tower in Sydney CBD exemplifies the strategy of investing in flagship assets to capture high-value tenants. Similarly, The Executive Centre leverages a strong presence across Asia-Pacific, Europe, and the Middle East to serve clients requiring luxury executive offices and day offices with robust tech services.
A newer wave of competitors includes hospitality-driven operators like Industrious and Fora. Industrious manages premium flexible workspaces tailored for enterprise teams, emphasizing hospitality-grade managed services and recent expansion into key US markets. Fora operates managed workspaces with a focus on SMBs and enterprises, offering hospitality-driven office services across numerous US locations with ambitions for global expansion. These players challenge traditional providers by elevating the user experience to match consumer hospitality standards.
Additionally, the convergence of real estate services and flexible office solutions is evident with firms like JLL Flex and CBRE FlexWork. Leveraging massive occupier relationships and provider alliances, these organizations offer managed flexible office solutions that integrate workplace strategy with on-demand management. Their approach appeals to corporate occupiers seeking scalability without the administrative burden of managing multiple providers, highlighting a trend where traditional real estate brokers are becoming active operators in the flex space.
Segmentation Nuances and Growth Vectors
A deep dive into the market reveals distinct growth vectors across space types and end-user industries. Understanding these nuances allows organizations to tailor their strategies to specific demand pockets rather than treating the market as a monolith.
In terms of space type, fully managed offices command the largest share of value. This segment appeals to enterprises seeking a turnkey solution where the provider assumes responsibility for design, fit-out, operations, and maintenance. Serviced offices represent another significant pillar, offering furnished spaces with varying levels of support. Co-working spaces, while sometimes perceived as a subset, maintain a distinct identity focused on community and ad-hoc usage. Each segment serves different risk profiles and operational requirements, and our report details the specific value drivers for each.
Smart Office Market
Demand is also unevenly distributed across end-user industries. The IT and telecommunications sector remains a primary driver, reflecting the talent-intensive nature of the industry and its early adoption of flexible work policies. Financial services and BFSI sectors follow, often utilizing managed offices for project teams, satellite offices, or cost optimization initiatives. Retail and consumer goods, healthcare, and other sectors contribute to the diversified demand base. Each industry vertical brings unique compliance, security, and service requirements that shape the offerings of managed office providers.
Geographically, the market exhibits varying maturity levels. Established markets in North America and Europe offer stability and deep provider networks, while Asia Pacific presents high-growth potential driven by urbanization and digital transformation. Emerging regions in Latin America and the Middle East and Africa are also developing, though at different scales and paces. Navigating these regional differences requires an understanding of local regulatory frameworks, labor markets, and cultural attitudes toward flexible work.
Strategic Roadmap for 2026 Decision-Makers
The insights contained in this research are designed to translate into actionable strategy. For corporate occupiers, the report provides a framework for evaluating managed office partners based on total cost of occupancy, service level agreements, technology integration, and sustainability credentials. It helps organizations decide whether to consolidate their workspace portfolio through managed solutions or to adopt a hybrid approach that blends owned assets with flexible managed spaces.
For investors and property owners, the analysis identifies which segments and regions offer the most attractive risk-adjusted returns. It highlights the importance of asset quality, location strategy, and the ability to adapt to regulatory changes such as energy efficiency mandates. The competitive intelligence section offers a detailed look at how key players are positioning themselves, allowing stakeholders to anticipate market shifts and potential consolidation events.
Furthermore, the report addresses the operational tactics required to thrive in this environment. From managing labor cost inflation to integrating technology stacks that support seamless user experiences, the findings provide a checklist for operational excellence. The impact of macroeconomic factors, including currency fluctuations and supply chain constraints on IT hardware, is also factored into the strategic recommendations.
Conclusion and Call to Action
The Worldwide Managed Office Market is at an inflection point. The convergence of hybrid work adoption, real estate cost pressures, and technological advancement is reshaping the value proposition of flexible workspaces. Organizations that proactively understand these dynamics will secure a competitive advantage in talent attraction, operational efficiency, and financial resilience.
Our comprehensive study goes beyond high-level trends to provide the granular intelligence necessary for precise decision-making. We invite you to explore the full depth of our analysis to uncover the specific regional opportunities, competitive benchmarks, and financial forecasts that will define your strategy for 2026 and the decade ahead. Access the complete report to gain the full spectrum of intelligence required to navigate the future of work with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Managed Office Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Global Meropenem Injection Market to Reach $2.87B by 2032 at 4.21% CAGR
By pmarketresearch, 2026-09-16
Navigating the Global Meropenem Injection Market: Strategic Imperatives for 2026 and Beyond
The global landscape for critical care antibiotics is undergoing a profound transformation, driven by the convergence of patent expirations, supply chain reconfigurations, and shifting epidemiological demands. As enterprises operating within the pharmaceutical and healthcare sectors plan their strategies for 2026, access to precise, forward-looking intelligence is not merely advantageous—it is essential. Our latest research offering, the Worldwide Meropenem Injection Market study, provides a comprehensive roadmap for stakeholders aiming to navigate this complex environment. This article serves as a strategic preview, outlining the macroscopic trends, competitive dynamics, and operational realities that define the market, while illustrating why this specific analysis is a critical asset for decision-makers in the coming year.
Market Trajectory and Growth Dynamics
To understand where the market is heading, one must first appreciate the trajectory it has established over the past half-decade. Our analysis covers historical performance from 2020 through 2025, establishing a robust baseline before projecting forward into the forecast period extending to 2032. The data indicates a steady expansion in market value, reflecting the enduring necessity of carbapenem antibiotics in treating severe bacterial infections.
Starting from a baseline in the early 2020s, the market has demonstrated resilience despite global supply chain disruptions and varying regulatory environments. By 2025, the market had reached a significant milestone, positioning itself for continued growth into the forecast horizon. Looking ahead, the market is expected to expand at a Compound Annual Growth Rate (CAGR) of approximately 4.21 percent. This growth is not linear; it is punctuated by specific inflection points related to product approvals, generic entries, and regional healthcare access improvements. For instance, the valuation in the immediate forecast year of 2026 reflects continued adoption, while long-term projections suggest accelerating value creation as newer manufacturing capacities come online and healthcare infrastructure in emerging economies matures.
However, growth alone does not tell the whole story. The market structure is evolving. Concentration metrics suggest that while a core group of players maintains significant influence—indicated by a top three concentration ratio exceeding 40 percent—the barrier to entry has lowered substantially following the expiration of key original patents. This shift from a branded-dominated landscape to a generic-rich ecosystem creates both opportunities for cost-efficient suppliers and risks for those reliant on fragile supply chains.
Operational Landscape: Distribution and Indication
The commercial realization of meropenem products is heavily dependent on how these injections reach the patient and the specific clinical scenarios driving their prescription. Our research dissect the market across critical operational dimensions, providing clarity on where volume and value are generated.
Worldwide Sulbactam Acid Market
Distribution channels play a pivotal role in market accessibility. Hospital pharmacies remain the dominant conduit for meropenem injections, reflecting the nature of the drug's administration which often requires supervised intravenous delivery in acute care settings. This channel captures the largest share of market activity, underscoring the importance of strong institutional relationships and reliable bulk supply mechanisms. Retail pharmacies and online pharmacies represent additional avenues, though their relative contribution varies by region and healthcare system structure. Understanding the nuances of these channels is vital for companies optimizing their sales networks and logistics partnerships.
On the demand side, the clinical indications driving consumption are diverse but concentrated around specific high-burden infections. Intra-abdominal infections represent a substantial portion of the clinical need, followed by complicated skin and structure infections. The treatment of bacterial meningitis also remains a critical use case, particularly given recent regulatory approvals expanding the utility of certain formulations for pediatric populations. By analyzing these indication segments, stakeholders can identify where therapeutic demand is most stable and where clinical guidelines might shift consumption patterns.
Competitive Dynamics and Recent Industry Shifts
The competitive arena for meropenem injections has become increasingly crowded since the original patents expired. This has enabled widespread generic manufacturing and the entry of multiple suppliers, altering the power dynamics within the industry. Our report provides a granular analysis of the key companies shaping this landscape, from established global giants to specialized generic manufacturers.
Worldwide Meropenem Injection Market
Several recent developments highlight the velocity of change in this sector. In early 2025, a major pharmaceutical company launched meropenem for injection in the United States in specific dosage strengths, manufactured through strategic partnerships with production facilities in Asia. This move underscores the trend of leveraging global supply chains to access high-value markets. Similarly, in mid-2025, another manufacturer received FDA approval for a higher-strength 2g formulation, marking a first for this specific strength in the US market and expanding options for treating severe infections including pediatric bacterial meningitis. These events illustrate how regulatory milestones can rapidly reshape market share potential.
Other key players continue to strengthen their positions through various strategies. Some focus on supplying the active pharmaceutical ingredient (API) while others concentrate on finished dosage forms. Major manufacturers based in Italy and India maintain significant roles as suppliers of both API and finished products, with multiple FDA listings supporting global distribution. Companies headquartered in Europe and North America continue to market generic versions, often relying on outsourced manufacturing networks to maintain competitiveness. The presence of suppliers from South Korea, China, and Taiwan further diversifies the supply base, though it also introduces complexities regarding quality assurance and geopolitical supply risks.
It is noteworthy that the original branded formulations in the US have been discontinued, leaving the market entirely to generic competitors. This shift places a premium on manufacturing efficiency, regulatory compliance, and supply chain reliability. Companies that can secure consistent API sourcing while maintaining strict quality standards are best positioned to capture value in this generic-dominated landscape.
Supply Chain Vulnerabilities and Regulatory Considerations
While the market offers growth opportunities, it is not without significant structural risks. Our analysis delves deep into the supply chain dynamics that underpin the availability of meropenem injections. A critical finding is the concentration of API production among a limited number of manufacturers, many of which are based in China and India. This concentration creates potential vulnerabilities, as over 80 percent of global intermediates for antibiotic APIs originate from a small number of production clusters. For procurement leaders and supply chain strategists, this represents a key area for risk mitigation and diversification.
Regulatory factors also continue to influence market operations. Recent updates to FDA labeling for certain meropenem for injection products have revised warnings and precautions, requiring manufacturers to ensure compliance and clear communication with healthcare providers. Furthermore, the discontinuation of original brand formulations in key markets like the US has consolidated the landscape around generic options, making regulatory approvals such as ANDAs critical gateways to market entry. Our report examines how these regulatory currents affect market timing and competitive positioning.
For strategic planners, understanding these dynamics is crucial. The interaction between raw material sourcing, manufacturing capacity, and regulatory approval timelines creates a complex web of dependencies. Companies must balance the cost advantages of sourcing from concentrated manufacturing hubs with the risks of supply disruption. The report provides frameworks for evaluating these trade-offs, helping organizations build more resilient procurement strategies.
Why This Research Matters for 2026 Decision-Making
As we move into 2026, the decisions made today regarding market entry, partnership selection, capacity investment, and risk management will determine competitive success in the years ahead. The Worldwide Meropenem Injection Market study is designed to support these high-stakes decisions with data-backed insights.
This research does more than report market size and growth rates. It offers a detailed examination of the forces shaping the industry. For product managers, it clarifies the competitive set and identifies gaps in formulation coverage. For supply chain directors, it maps the concentration risks and highlights the key nodes in the global API network. For investors and strategists, it provides a view on which indication segments and distribution channels offer the most stable returns.
The macroeconomic environment also adds urgency to having accurate forecasts. With market valuations projected to evolve through 2032, organizations need to know not just where the market is, but where it is going. The projected growth trajectory suggests that while the immediate forecast year shows steady progress, the longer-term outlook indicates potential acceleration as healthcare systems expand and treatment protocols evolve. Understanding the timing of these shifts allows companies to align their resource allocation with market opportunities.
Moreover, the report addresses the operational realities of the market. It explores how regional differences influence demand patterns and how distribution channel preferences vary across geographies. This level of detail is essential for companies planning market expansion or seeking to optimize their existing footprint. Generic competition is intense, and success often depends on subtle advantages in logistics, regulatory speed, or clinical support rather than price alone.
Conclusion
The global meropenem injection market stands at a pivotal juncture. The expiration of original patents has democratized access but also intensified competition. Supply chain concentration introduces fragility into an otherwise growing market. Regulatory updates continue to refine the boundaries of safe and effective use. In this environment, generic intelligence is insufficient. Leaders need a deep, structured understanding of the interplay between clinical demand, manufacturing realities, and competitive maneuvers.
Our forthcoming publication, the Worldwide Meropenem Injection Market study, delivers this depth. It integrates historical data, forward-looking projections, and a detailed analysis of the key players and dynamics that define the industry. For executives, analysts, and strategists preparing for 2026 and beyond, this report offers the clarity needed to make informed, confident decisions. We invite you to explore the full research for comprehensive data, detailed segmentation analysis, and the strategic frameworks necessary to navigate this critical segment of the pharmaceutical market.
For detailed analysis of this topic, please visit the official page: Worldwide Meropenem Injection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Packaging Reel Market Hits $1,450M in 2025, Forecasts 5.18% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Packaging Reel Market: Navigating Growth and Compliance in 2026
The global packaging landscape is undergoing a structural transformation, driven by intensifying sustainability mandates, volatile raw material economics, and shifting supply chain geographies. For executive leaders and strategy teams, understanding the trajectory of the Worldwide Packaging Reel Market is no longer optional. It is a critical input for capital allocation, product development roadmaps, and risk mitigation strategies heading into 2026.
This article serves as a strategic precursor to our comprehensive Worldwide Packaging Reel Market research report. The following analysis outlines the macro-economic forces, competitive pressures, and regulatory inflection points defining the sector. While we highlight the market's direction and the depth of our upcoming intelligence, specific segment valuations and granular forecasts are reserved for the full study. Leaders who secure access to the complete dataset will gain a distinct advantage in positioning their organizations for the forecast period.
Packaging Market
Market Trajectory and Macro-Economic Foundations
The packaging reel market has demonstrated resilience and steady expansion over the past half-decade. Historical analysis from 2020 through the base year of 2025 reveals a market that has successfully navigated supply chain disruptions and material cost fluctuations. The sector has matured, moving from reactive recovery to proactive growth strategies centered on efficiency and material innovation.
Looking forward, the forecast period from 2026 to 2032 indicates sustained momentum. Our analysis projects a Compound Annual Growth Rate (CAGR) of 5.18 percent across the forecast horizon. This growth trajectory suggests that the market will expand from its 2026 baseline of approximately 1,497 million USD to reach over 2,064 million USD by 2032. For strategic planners, this represents a significant total addressable market expansion, albeit one that will be unevenly distributed across regions and applications based on local regulatory adoption and industrial output.
The market size data underscores a critical narrative: value is accumulating, but the composition of that value is shifting. Early historical periods saw volatility, with contractions and expansions reflecting global economic conditions. However, the trend from 2023 onward shows a clear upward vector. This stabilization provides a reliable foundation for long-term investment decisions, provided companies account for the regulatory and material dynamics that will shape future revenue streams.
Regulatory and Operational Dynamics Shaping 2026
No strategic assessment of the packaging reel market is complete without addressing the regulatory environment. The years ahead will be defined by compliance costs, material substitution pressures, and cross-border trade friction. Three key regulatory themes dominate the landscape for 2026 planning.
- Sustainability Mandates and Reusability Targets. The European Union's Packaging and Packaging Waste Regulation introduces strict requirements, including a mandate for 10 percent reusable packaging share by 2030. This directly impacts reel formats used in industrial and logistics applications, pushing manufacturers and converters to evaluate returnable and durable reel systems. Companies operating in or exporting to Europe must model the operational implications of this shift, including reverse logistics costs and reel lifecycle management.
- Recycled Content and Tax Incentives. Taxation policies are rapidly aligning with circularity goals. In the United Kingdom, the Plastic Packaging Tax rate is set at £217.85 per tonne for items containing less than 30 percent recycled content. This creates a clear financial incentive to integrate recycled resin into reel production or to source reels that meet the threshold. Similarly, California SB 1013 requires all single-use plastic packaging to be recyclable by 2032, a mandate that encompasses films and reels derived from film stock. These requirements are reshaping procurement criteria and forcing material innovation.
- Trade and Tariff Pressures. Geopolitical factors continue to influence cost structures. US Section 301 tariffs impose 25 percent duties on Chinese-origin plastic packaging films and reels. For North American buyers and importers, this alters the cost-benefit analysis of offshore sourcing versus domestic or near-shore production. Strategic sourcing decisions in 2026 must factor in tariff exposure, lead time variability, and the potential for supply chain reconfiguration.
These dynamics are not isolated. They interact with raw material economics, such as the recent decline in HDPE resin prices for packaging films to $0.92 per pound in North America during Q1 2024. While lower resin costs can improve margins, they also invite scrutiny from regulators and consumers regarding the environmental profile of plastic-based solutions. The strategic imperative is to balance cost efficiency with compliance and brand positioning, a balance that requires precise data on material substitution pathways and cost modeling.
Competitive Landscape and Strategic Positioning
The market is characterized by a mix of global multinationals and specialized regional players, with concentration metrics indicating a moderately consolidated environment. The CR3 stands at 38.45 percent and the CR5 at 52.1 percent, suggesting that while leading firms hold significant share, a substantial portion of the market remains distributed among mid-tier and niche suppliers. This structure creates opportunities for both consolidation and differentiation, depending on a company's capabilities in material science, geographic reach, and customer intimacy.
Worldwide Packaging Reel Market
Leading organizations are actively reshaping their portfolios to address the trends outlined above. Several recent developments illustrate the strategic directions being taken by key participants:
- Material Innovation and Circular Design. Amcor exhibited recyclable mono-material film reels at PACK EXPO International in October 2024, signaling a shift toward formats that simplify recovery and recycling. Mondi launched the Advantage Reel Wrapper, a recyclable paper-based reel cover, in September 2023, showcasing paper-plastic hybrid and mono-material approaches for sustainable flexible packaging. Berry Global introduced NatureWorks-based bio-resin film reels in May 2023, expanding the use of bio-based feedstocks in flexible applications.
- Performance and Application-Specific Engineering. Uflex showcased a new generation of BOPP reels with enhanced printability at PlastIndia in February 2024, reflecting ongoing investment in surface performance and converter usability. Huhtamäki continues to offer high-barrier EVOH and PA co-extruded film reels for extended shelf-life food packaging, addressing the demand for preservation and waste reduction. Constantia Flexibles provides aluminum-laminated and plastic film reels for premium consumer and medical packaging, while Coveris specializes in fresh food flexible film reels with high puncture resistance.
- Diversified Regional Footprints. Companies such as Sealed Air supply Cryovac multilayer shrink and barrier film reels for protein packaging, leveraging scale and technical expertise. Sonoco delivers flexible packaging reel stock including stand-up pouch precursors, supporting a broad range of end-use formats. Winpak manufactures medical-grade and food-safe barrier film reels, while Inteplast supplies PE stretch and shrink film reels for industrial packaging. In the Asia-Pacific region, Uflex exports BOPET, BOPP, and metalized film jumbo reels to global converters, and Cosmo Films produces thermally laminatable BOPP and BOPET reels for overwrap and label applications. These regional capabilities are increasingly relevant as buyers seek to mitigate tariff risk and shorten supply chains.
The competitive game is shifting from pure price competition to value-based differentiation. Suppliers that can demonstrate compliance with recycled content thresholds, offer mono-material or recyclable formats, and provide application-specific performance will capture premium positioning. Conversely, undifferentiated commodity reel products face margin compression and heightened exposure to regulatory and tariff headwinds. Our full report provides a detailed competitive profiling framework, including capability mapping and strategic group analysis, to help leadership teams benchmark their position and identify partnership or acquisition targets.
Segmentation Themes and Growth Vectors
While the aggregate market growth is compelling, the real strategic insight lies in understanding how value is distributed across materials, regions, and end-use applications. The full study deconstructs these dimensions to reveal where growth is concentrated and which segments face structural headwinds or tailwinds.
On the material axis, plastic reels continue to represent the largest share of market value, driven by their versatility, barrier properties, and integration with high-speed converting equipment. However, paper and fiberboard reels are gaining attention as brands seek to reduce plastic intensity and improve recyclability profiles. Metal reels maintain a specialized role in high-durability and precision applications. The interplay between these material categories is being reshaped by regulation, consumer preference, and total cost of ownership calculations that include waste management and compliance costs.
Regionally, the market exhibits distinct characteristics. Asia Pacific remains a central hub for both production and consumption, with strong industrial output and growing domestic demand. North America and Europe are characterized by mature markets where growth is increasingly driven by innovation, premiumization, and regulatory compliance rather than volume expansion alone. Latin America and the Middle East and Africa present emerging opportunities, though they vary significantly in terms of infrastructure readiness, regulatory frameworks, and foreign exchange exposure. The complete report provides a nuanced view of these regional dynamics without over-simplifying the heterogeneous nature of local markets.
End-use segmentation further refines the growth picture. Electronics and semiconductors represent a high-performance segment where reel quality, cleanliness, and consistency are paramount. Automotive components demand durable and traceable packaging solutions that align with stringent quality standards. Telecommunications, medical devices, and consumer goods each impose unique requirements on reel format, handling, and material properties. The medical devices segment, for example, involves higher barriers to entry and stricter validation processes, while consumer goods are more sensitive to sustainability messaging and cost pressures. Understanding the relative attractiveness of each end-use vertical is essential for prioritizing sales investments, R&D bandwidth, and capacity planning.
The Strategic Value of Granular Intelligence in 2026
For decision-makers, the difference between a directional market view and a precise, actionable intelligence package can determine the success of a product launch, the timing of a capacity investment, or the outcome of a supplier negotiation. The Worldwide Packaging Reel Market research report is designed to bridge that gap. It goes beyond top-line figures to deliver the operational detail required for strategic execution.
The report's core components include:
- Historical Reconstruction and Forecast Modeling. A rigorous reconstruction of market performance from 2020 to 2025, integrated with a bottom-up forecast model spanning 2026 to 2032. This enables scenario planning around base, upside, and downside cases, with clear drivers identified for each.
- Segmentation Deep-Dives. Detailed breakdowns by region, material, and end-use, with analysis of volume and value trends, substitution patterns, and segment-specific regulatory impacts. This allows teams to target the most attractive sub-markets and avoid over-indexed exposure to declining segments.
- Competitive Benchmarking. Profiles of key companies, including headquarters, product focus, and recent strategic moves. The report includes a structured competitive analysis that maps capabilities, geographic coverage, and strategic positioning, supporting M&A screening, partnership evaluation, and competitive response planning.
- Regulatory and Trade Impact Assessment. A synthesis of the most material regulations, taxes, mandates, and tariffs affecting reel formats, with practical guidance on compliance pathways and cost implications. This section is updated to reflect the latest policy developments and is designed to feed directly into risk registers and procurement strategies.
- Market Concentration and Structure Analysis. Metrics on concentration, alongside qualitative assessment of barriers to entry, capacity dynamics, and the role of converters and integrators in the value chain. This helps leadership teams understand where power sits in the supply chain and how to negotiate from a position of informed strength.
This depth of analysis is particularly valuable as organizations prepare for 2026. The combination of moderate market growth, regulatory complexity, and evolving competitive dynamics means that generic market narratives are insufficient. Executives need to know which subsegments offer the best risk-adjusted returns, how material substitution will affect cost structures, and where competitors are likely to pivot. The full report delivers this level of specificity, enabling data-driven decisions rather than assumption-based planning.
Conclusion: Turning Market Insight into Strategic Advantage
The Worldwide Packaging Reel Market is entering a phase where growth and complexity are intertwined. A 5.18 percent CAGR over the forecast period signals continued expansion, but the value of that growth will accrue to organizations that can navigate material transitions, regulatory requirements, and regional asymmetries with precision. The macro trajectory is favorable; the micro execution is where competitive advantage will be won or lost.
This article has outlined the strategic context and the breadth of analysis available in our upcoming study. To move from awareness to action, leaders need the full dataset: segment-level valuations, regional growth decompositions, end-use performance comparisons, and detailed competitive profiles. These insights are essential for building resilient sourcing strategies, prioritizing innovation investments, and aligning commercial plans with the realities of 2026 and beyond.
We invite strategy, procurement, and commercial leaders to access the complete Worldwide Packaging Reel Market research for a comprehensive view of the market's architecture and trajectory. The full report translates the directional signals discussed here into the granular intelligence required to make confident, forward-looking decisions in a market that rewards clarity and preparation.
For detailed analysis of this topic, please visit the official page: Worldwide Packaging Reel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com