

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Used Cooking Oil for SAF Market Hits $2.87B in 2025, Projected 20.31% CAGR to $10.45B by 2032

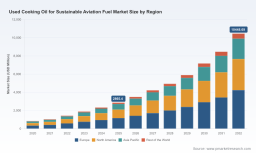
The UCO-to-SAF Imperative: Navigating a $10 Billion Transition by 2032
The aviation industry stands at a critical decarbonization inflection point, and used cooking oil has emerged as one of the most strategically vital feedstock vectors in the sustainable aviation fuel value chain. Our latest market research on the Used Cooking Oil for Sustainable Aviation Fuel market translates a rapidly compounding revenue trajectory into an actionable decision framework for executives, procurement leaders, and energy investors. Drawing on historical performance from 2020 through 2025 and a forward-looking forecast extending to 2032, the analysis captures how feedstock logistics, regulatory mandates, and refining pathway economics are converging to reshape competitive positioning across the global SAF ecosystem.
The headline trajectory is unmistakable. Revenue associated with UCO directed toward sustainable aviation fuel applications expanded from roughly $840 million in 2020 to approximately $2.87 billion in 2025, and the forecast arc accelerates sharply thereafter, reaching an estimated $3.49 billion in 2026 and climbing toward $10.45 billion by 2032. This expansion is anchored by a projected compound annual growth rate of 20.31 percent across the 2026–2032 forecast period. For strategy teams, the implication is straightforward: UCO is no longer a peripheral waste-stream story. It is becoming a structurally constrained, policy-driven commodity whose availability, pricing power, and geographic routing will determine which refiners, aggregators, and airline-affiliated fuel buyers can reliably meet blending obligations without incurring margin erosion.
Executing in this environment requires more than top-line forecasting. It demands a clear line of sight into collection-channel economics, conversion-pathway competitiveness, regional supply-chain resilience, and the contractual architectures that major processors are already locking in. The research is designed to deliver that precision without overwhelming decision-makers with undifferentiated data density. Instead, it surfaces the operational and strategic variables that actually move the needle when boards are allocating capital, negotiating offtake terms, or evaluating entry into the HEFA and co-processing value chains.
Why This Research Matters for 2026 Decision-Making
2026 is a pivot year for sustainable aviation fuel procurement and feedstock strategy. Regulatory clocks have already started ticking in key markets, and the earliest compliance cycles are exposing the operational realities of scaling UCO-dependent production. The European Union’s ReFuelEU Aviation mandate requires a 2 percent SAF blending baseline from January 2025, climbing toward 6 percent by 2030, with UCO-based HEFA positioned as the dominant compliant pathway in the near term. In the United Kingdom, the SAF mandate took effect in January 2025 with a 2 percent target, and provisional data from the first ten months of 2025 indicated that 1.63 percent was achieved, entirely from UCO feedstock. These early compliance readings matter because they reveal both the speed at which demand can materialize and the dependency that emerges when a single feedstock category carries the bulk of early blending requirements.
On the incentive side, the United States Section 45Z clean fuel production credit provides up to $1 per gallon for SAF through 2029 under updated legislation, with eligibility restricted to North American feedstocks. That restriction changes the strategic calculus for anyone modelling U.S. production economics or planning feedstock sourcing across borders. Meanwhile, trade dynamics are reshaping physical supply routes: U.S. imports of UCO from China declined significantly in 2025 due to tariff pressure, pushing sourcing activity toward Australia, South Korea, and Malaysia even as total import volumes remained robust at approximately 2 million metric tons through November 2025. These are exactly the kinds of structural shifts that can undermine a supply plan if they are treated as background noise rather than core inputs to scenario design.
Used Cooking Oil for Sustainable Aviation Fuel Market
The research therefore treats feedstock availability as a strategic risk variable, not a static assumption. It maps how collection infrastructure, pre-processing capacity, and long-term supply commitments interact with policy timelines, so that executives can stress-test their SAF sourcing strategies against realistic constraints instead of optimistic averages.
What the Report Covers: An Operational Roadmap, Not Just a Forecast
The study is built around practical decision support. Beyond the macro revenue trajectory and multi-year forecast, the report examines the structural segmentation that determines where value accrues and where bottlenecks form. It analyzes collection and supply channels including food service collection, industrial food processing, and household collection, with attention to how each channel’s logistics profile affects scalability, contamination risk, and feedstock consistency. It also evaluates application pathways, particularly the HEFA production pathway and refinery co-processing, explaining how capital intensity, conversion yields, and integration with existing refining assets shape competitiveness across different operator profiles.
Worldwide Kenaf Seed Oil Market
Regional analysis is presented to help teams understand where supply depth, processing infrastructure, and policy momentum are most aligned. Rather than forcing a single narrative, the research disaggregates market behavior so that strategy leaders can identify which geographies offer the most reliable feedstock aggregation, where co-processing assets are best positioned to absorb waste oils, and where import dependency may create vulnerability under shifting trade or tariff regimes.
Equally important, the report connects quantitative structure to real-world industry movement. It incorporates recent developments that illustrate how the market is actually behaving as procurement contracts, production ramp-ups, and partnership agreements begin to lock in supply for the 2026–2030 window. These activity signals are essential for interpreting whether observed price behavior reflects temporary tightness or a more durable re-rating of UCO as a premium SAF feedstock.
Competitive Positioning in a Concentrated but Fragmented Value Chain
The competitive landscape reveals a market that is consolidated at the top yet highly dependent on a broad network of collectors, processors, and integrators. Market concentration data indicates a CR3 of approximately 38.4 percent and a CR5 of about 52.15 percent, suggesting that while leading players hold meaningful share, a substantial portion of supply and conversion capacity remains distributed across specialized operators. For entrants and incumbents alike, the strategic question is less about aggregate share than about securing dependable feedstock flow, differentiating by conversion route, and building long-term contractual insulation against price volatility.
Among the most prominent players, Neste stands out as a global leader in renewable fuels with extensive UCO collection and processing networks, including assets acquired in the United States, feeding HEFA-based SAF production across multiple refineries through dedicated UCO-to-SAF pathways. Darling Ingredients operates through its Diamond Green Diesel joint venture, supplying UCO and other waste feedstocks and delivering neat SAF produced from UCO, animal fats, and other renewables. Greenergy International functions as a major collector and supplier of UCO for biofuel and SAF production, supported by established European and international aggregation networks that reinforce HEFA pathway supply. In the UK, Olleco specializes in UCO collection and pre-processing for conversion into biodiesel and SAF feedstocks, while Brocklesby Ltd collects and processes UCO into refined feedstock specifically for sustainable aviation fuel production. Argent Energy focuses on waste-based feedstocks including UCO for advanced biofuels and SAF.
Across the Atlantic, Baker Commodities Inc. provides UCO collection and recycling services that supply feedstock for renewable diesel and SAF facilities, and Mahoney Environmental Inc. operates as a UCO collection specialist delivering feedstock directly into Neste’s SAF production. Quatra supplies large volumes of European UCO under long-term agreements for processing into SAF at biorefineries. Sanimax collects and processes animal fats and UCO for renewable fuel and SAF applications across Canada and the United States. Münzer Bioindustrie GmbH processes UCO and waste oils into biofuels with SAF feedstock capabilities. World Energy operates biorefineries converting UCO into high volumes of SAF. EcoCeres converts UCO and agricultural waste into SAF and other fuels using proprietary technology. In Asia, PT Pertamina has completed its first SAF shipment from UCO and is developing co-processing capabilities for UCO-based SAF, while Sinopec operates UCO-based bio-aviation fuel plants using proprietary SRJET technology. TotalEnergies receives UCO supplies for biorefineries producing SAF and operates co-processing units using waste oils. XCF Global Inc., through its New Rise Renewables operations, runs HEFA SAF facilities using waste- and residue-based feedstocks including UCO.
What makes this competitive set strategically interesting is not simply the roster of names, but the pattern of recent commitments and operational milestones. In August 2025, PT Pertamina completed its first shipment of aviation fuel produced from used cooking oil, signaling state-backed momentum in UCO-based SAF adoption. In July 2025, Quatra signed a 15-year agreement to supply TotalEnergies with 60,000 tons of European used cooking oil annually starting in 2026 for biodiesel and SAF processing, illustrating how long-duration contracts are being used to stabilize feedstock access. In December 2024, Darling Ingredients delivered its first batch of neat SAF produced using UCO and other renewable feedstocks via Diamond Green Diesel to Avfuel Corporation, marking a concrete step in distributed neat-SAF supply. In February 2025, XCF Global’s New Rise Reno facility began ramp-up with HEFA technology using waste feedstocks, with SAF production expected to resume in early 2026. In March 2025, Cosmo Oil partnered with SAFFAIRE SKY ENERGY, Suita City, JGC Holdings, and REVO International to promote domestic UCO collection for Japan’s first large-scale locally-made SAF production targeting 30,000 kiloliters per year.
These moves matter because they show the market hardening around long-term supply architecture. A collector secures a 15-year off-take commitment; a refiner brings a HEFA line back into ramp-up; a state-owned energy company executes its first UCO-based SAF shipment; a domestic consortium organizes around localized collection to reduce import dependency. Each event is a data point in a broader pattern: the companies that can combine reliable collection, credible processing credentials, and policy-aligned conversion pathways are positioning themselves to capture the most durable margins as mandates intensify.
Feedstock Economics, Regulatory Tailwinds, and the 2026–2032 Window
Pricing behavior in the UCO market has become an integral part of SAF project economics. Indicative bulk UCO prices in 2025–2026 reached the $750–$1,250 per ton range in Europe and North America, with spikes above $1,400 per ton in tight markets, driven by rising SAF and biodiesel demand. For procurement and finance teams, this range is not just a commodity note; it is a margin sensitivity variable that interacts directly with blending mandates, incentive eligibility, and the competitiveness of alternative feedstocks. When UCO prices spike, the economic advantage of co-processing configurations, regional sourcing diversification, and long-term fixed-price or indexed contracts becomes more pronounced.
Regulatory alignment is amplifying that sensitivity. The EU ReFuelEU Aviation mandate’s progressive ramp from 2 percent to 6 percent by 2030 establishes a multi-year demand floor that favors feedstocks capable of meeting compliance requirements at scale. UCO-based HEFA has emerged as the dominant compliant pathway in the early years, which means that near-term policy implementation is disproportionately channeling demand toward the very feedstock category this research analyzes. In parallel, the UK mandate’s early attainment figures, entirely from UCO feedstock, underscore how quickly a market can become concentrated around a single supply base when compliance timelines are immediate and alternatives are limited.
In the United States, the Section 45Z credit creates a different kind of strategic filter. Because eligibility is restricted to North American feedstocks, the incentive architecture favors domestic and regionally sourced supply chains over imported alternatives, reinforcing the importance of collection networks, preprocessing capacity, and feedstock traceability within the eligible geography. This is one of the reasons the report pays close attention to how trade flow changes, such as the 2025 decline in U.S. UCO imports from China and the corresponding pivot toward Australia, South Korea, and Malaysia, can alter both cost structures and compliance positioning.
From Intelligence to Action
The broader takeaway for 2026 planning is that UCO for sustainable aviation fuel is evolving from an opportunistic sustainability narrative into a tightly contested supply-chain business. The revenue outlook suggests a market moving toward the $10.45 billion range by 2032, but the strategic prize will not go to organizations that simply recognize the growth trend. It will go to those who can map their feedstock access, conversion strategy, and regulatory exposure onto a coherent plan before mandates, incentives, and competitor contracts reshape the landscape.
This research is designed to support that planning with granular segmentation, competitive profiling, and market-dynamic analysis that can be translated directly into sourcing strategy, capacity evaluation, and risk management. The full study provides the detailed regional and segment breakouts, company-level analysis, and scenario-ready context that executives need to move from awareness to execution. For teams responsible for SAF procurement, renewable fuel investment, or feedstock portfolio strategy, the complete report offers the depth required to make 2026 decisions with confidence rather than conjecture.
For detailed analysis of this topic, please visit the official page: Used Cooking Oil for Sustainable Aviation Fuel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com