

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Global Meropenem Injection Market to Reach $2.87B by 2032 at 4.21% CAGR

Navigating the Global Meropenem Injection Market: Strategic Imperatives for 2026 and Beyond
The global landscape for critical care antibiotics is undergoing a profound transformation, driven by the convergence of patent expirations, supply chain reconfigurations, and shifting epidemiological demands. As enterprises operating within the pharmaceutical and healthcare sectors plan their strategies for 2026, access to precise, forward-looking intelligence is not merely advantageous—it is essential. Our latest research offering, the Worldwide Meropenem Injection Market study, provides a comprehensive roadmap for stakeholders aiming to navigate this complex environment. This article serves as a strategic preview, outlining the macroscopic trends, competitive dynamics, and operational realities that define the market, while illustrating why this specific analysis is a critical asset for decision-makers in the coming year.
Market Trajectory and Growth Dynamics
To understand where the market is heading, one must first appreciate the trajectory it has established over the past half-decade. Our analysis covers historical performance from 2020 through 2025, establishing a robust baseline before projecting forward into the forecast period extending to 2032. The data indicates a steady expansion in market value, reflecting the enduring necessity of carbapenem antibiotics in treating severe bacterial infections.
Starting from a baseline in the early 2020s, the market has demonstrated resilience despite global supply chain disruptions and varying regulatory environments. By 2025, the market had reached a significant milestone, positioning itself for continued growth into the forecast horizon. Looking ahead, the market is expected to expand at a Compound Annual Growth Rate (CAGR) of approximately 4.21 percent. This growth is not linear; it is punctuated by specific inflection points related to product approvals, generic entries, and regional healthcare access improvements. For instance, the valuation in the immediate forecast year of 2026 reflects continued adoption, while long-term projections suggest accelerating value creation as newer manufacturing capacities come online and healthcare infrastructure in emerging economies matures.
However, growth alone does not tell the whole story. The market structure is evolving. Concentration metrics suggest that while a core group of players maintains significant influence—indicated by a top three concentration ratio exceeding 40 percent—the barrier to entry has lowered substantially following the expiration of key original patents. This shift from a branded-dominated landscape to a generic-rich ecosystem creates both opportunities for cost-efficient suppliers and risks for those reliant on fragile supply chains.
Operational Landscape: Distribution and Indication
The commercial realization of meropenem products is heavily dependent on how these injections reach the patient and the specific clinical scenarios driving their prescription. Our research dissect the market across critical operational dimensions, providing clarity on where volume and value are generated.
Worldwide Sulbactam Acid Market
Distribution channels play a pivotal role in market accessibility. Hospital pharmacies remain the dominant conduit for meropenem injections, reflecting the nature of the drug's administration which often requires supervised intravenous delivery in acute care settings. This channel captures the largest share of market activity, underscoring the importance of strong institutional relationships and reliable bulk supply mechanisms. Retail pharmacies and online pharmacies represent additional avenues, though their relative contribution varies by region and healthcare system structure. Understanding the nuances of these channels is vital for companies optimizing their sales networks and logistics partnerships.
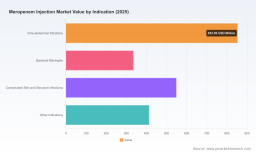
On the demand side, the clinical indications driving consumption are diverse but concentrated around specific high-burden infections. Intra-abdominal infections represent a substantial portion of the clinical need, followed by complicated skin and structure infections. The treatment of bacterial meningitis also remains a critical use case, particularly given recent regulatory approvals expanding the utility of certain formulations for pediatric populations. By analyzing these indication segments, stakeholders can identify where therapeutic demand is most stable and where clinical guidelines might shift consumption patterns.
Competitive Dynamics and Recent Industry Shifts
The competitive arena for meropenem injections has become increasingly crowded since the original patents expired. This has enabled widespread generic manufacturing and the entry of multiple suppliers, altering the power dynamics within the industry. Our report provides a granular analysis of the key companies shaping this landscape, from established global giants to specialized generic manufacturers.
Worldwide Meropenem Injection Market
Several recent developments highlight the velocity of change in this sector. In early 2025, a major pharmaceutical company launched meropenem for injection in the United States in specific dosage strengths, manufactured through strategic partnerships with production facilities in Asia. This move underscores the trend of leveraging global supply chains to access high-value markets. Similarly, in mid-2025, another manufacturer received FDA approval for a higher-strength 2g formulation, marking a first for this specific strength in the US market and expanding options for treating severe infections including pediatric bacterial meningitis. These events illustrate how regulatory milestones can rapidly reshape market share potential.
Other key players continue to strengthen their positions through various strategies. Some focus on supplying the active pharmaceutical ingredient (API) while others concentrate on finished dosage forms. Major manufacturers based in Italy and India maintain significant roles as suppliers of both API and finished products, with multiple FDA listings supporting global distribution. Companies headquartered in Europe and North America continue to market generic versions, often relying on outsourced manufacturing networks to maintain competitiveness. The presence of suppliers from South Korea, China, and Taiwan further diversifies the supply base, though it also introduces complexities regarding quality assurance and geopolitical supply risks.
It is noteworthy that the original branded formulations in the US have been discontinued, leaving the market entirely to generic competitors. This shift places a premium on manufacturing efficiency, regulatory compliance, and supply chain reliability. Companies that can secure consistent API sourcing while maintaining strict quality standards are best positioned to capture value in this generic-dominated landscape.
Supply Chain Vulnerabilities and Regulatory Considerations
While the market offers growth opportunities, it is not without significant structural risks. Our analysis delves deep into the supply chain dynamics that underpin the availability of meropenem injections. A critical finding is the concentration of API production among a limited number of manufacturers, many of which are based in China and India. This concentration creates potential vulnerabilities, as over 80 percent of global intermediates for antibiotic APIs originate from a small number of production clusters. For procurement leaders and supply chain strategists, this represents a key area for risk mitigation and diversification.
Regulatory factors also continue to influence market operations. Recent updates to FDA labeling for certain meropenem for injection products have revised warnings and precautions, requiring manufacturers to ensure compliance and clear communication with healthcare providers. Furthermore, the discontinuation of original brand formulations in key markets like the US has consolidated the landscape around generic options, making regulatory approvals such as ANDAs critical gateways to market entry. Our report examines how these regulatory currents affect market timing and competitive positioning.
For strategic planners, understanding these dynamics is crucial. The interaction between raw material sourcing, manufacturing capacity, and regulatory approval timelines creates a complex web of dependencies. Companies must balance the cost advantages of sourcing from concentrated manufacturing hubs with the risks of supply disruption. The report provides frameworks for evaluating these trade-offs, helping organizations build more resilient procurement strategies.
Why This Research Matters for 2026 Decision-Making
As we move into 2026, the decisions made today regarding market entry, partnership selection, capacity investment, and risk management will determine competitive success in the years ahead. The Worldwide Meropenem Injection Market study is designed to support these high-stakes decisions with data-backed insights.
This research does more than report market size and growth rates. It offers a detailed examination of the forces shaping the industry. For product managers, it clarifies the competitive set and identifies gaps in formulation coverage. For supply chain directors, it maps the concentration risks and highlights the key nodes in the global API network. For investors and strategists, it provides a view on which indication segments and distribution channels offer the most stable returns.
The macroeconomic environment also adds urgency to having accurate forecasts. With market valuations projected to evolve through 2032, organizations need to know not just where the market is, but where it is going. The projected growth trajectory suggests that while the immediate forecast year shows steady progress, the longer-term outlook indicates potential acceleration as healthcare systems expand and treatment protocols evolve. Understanding the timing of these shifts allows companies to align their resource allocation with market opportunities.
Moreover, the report addresses the operational realities of the market. It explores how regional differences influence demand patterns and how distribution channel preferences vary across geographies. This level of detail is essential for companies planning market expansion or seeking to optimize their existing footprint. Generic competition is intense, and success often depends on subtle advantages in logistics, regulatory speed, or clinical support rather than price alone.
Conclusion
The global meropenem injection market stands at a pivotal juncture. The expiration of original patents has democratized access but also intensified competition. Supply chain concentration introduces fragility into an otherwise growing market. Regulatory updates continue to refine the boundaries of safe and effective use. In this environment, generic intelligence is insufficient. Leaders need a deep, structured understanding of the interplay between clinical demand, manufacturing realities, and competitive maneuvers.
Our forthcoming publication, the Worldwide Meropenem Injection Market study, delivers this depth. It integrates historical data, forward-looking projections, and a detailed analysis of the key players and dynamics that define the industry. For executives, analysts, and strategists preparing for 2026 and beyond, this report offers the clarity needed to make informed, confident decisions. We invite you to explore the full research for comprehensive data, detailed segmentation analysis, and the strategic frameworks necessary to navigate this critical segment of the pharmaceutical market.
For detailed analysis of this topic, please visit the official page: Worldwide Meropenem Injection Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com