

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Packaging Reel Market Hits $1,450M in 2025, Forecasts 5.18% CAGR to 2032

Strategic Intelligence for the Packaging Reel Market: Navigating Growth and Compliance in 2026
The global packaging landscape is undergoing a structural transformation, driven by intensifying sustainability mandates, volatile raw material economics, and shifting supply chain geographies. For executive leaders and strategy teams, understanding the trajectory of the Worldwide Packaging Reel Market is no longer optional. It is a critical input for capital allocation, product development roadmaps, and risk mitigation strategies heading into 2026.
This article serves as a strategic precursor to our comprehensive Worldwide Packaging Reel Market research report. The following analysis outlines the macro-economic forces, competitive pressures, and regulatory inflection points defining the sector. While we highlight the market's direction and the depth of our upcoming intelligence, specific segment valuations and granular forecasts are reserved for the full study. Leaders who secure access to the complete dataset will gain a distinct advantage in positioning their organizations for the forecast period.
Packaging Market
Market Trajectory and Macro-Economic Foundations
The packaging reel market has demonstrated resilience and steady expansion over the past half-decade. Historical analysis from 2020 through the base year of 2025 reveals a market that has successfully navigated supply chain disruptions and material cost fluctuations. The sector has matured, moving from reactive recovery to proactive growth strategies centered on efficiency and material innovation.
Looking forward, the forecast period from 2026 to 2032 indicates sustained momentum. Our analysis projects a Compound Annual Growth Rate (CAGR) of 5.18 percent across the forecast horizon. This growth trajectory suggests that the market will expand from its 2026 baseline of approximately 1,497 million USD to reach over 2,064 million USD by 2032. For strategic planners, this represents a significant total addressable market expansion, albeit one that will be unevenly distributed across regions and applications based on local regulatory adoption and industrial output.
The market size data underscores a critical narrative: value is accumulating, but the composition of that value is shifting. Early historical periods saw volatility, with contractions and expansions reflecting global economic conditions. However, the trend from 2023 onward shows a clear upward vector. This stabilization provides a reliable foundation for long-term investment decisions, provided companies account for the regulatory and material dynamics that will shape future revenue streams.
Regulatory and Operational Dynamics Shaping 2026
No strategic assessment of the packaging reel market is complete without addressing the regulatory environment. The years ahead will be defined by compliance costs, material substitution pressures, and cross-border trade friction. Three key regulatory themes dominate the landscape for 2026 planning.
- Sustainability Mandates and Reusability Targets. The European Union's Packaging and Packaging Waste Regulation introduces strict requirements, including a mandate for 10 percent reusable packaging share by 2030. This directly impacts reel formats used in industrial and logistics applications, pushing manufacturers and converters to evaluate returnable and durable reel systems. Companies operating in or exporting to Europe must model the operational implications of this shift, including reverse logistics costs and reel lifecycle management.
- Recycled Content and Tax Incentives. Taxation policies are rapidly aligning with circularity goals. In the United Kingdom, the Plastic Packaging Tax rate is set at £217.85 per tonne for items containing less than 30 percent recycled content. This creates a clear financial incentive to integrate recycled resin into reel production or to source reels that meet the threshold. Similarly, California SB 1013 requires all single-use plastic packaging to be recyclable by 2032, a mandate that encompasses films and reels derived from film stock. These requirements are reshaping procurement criteria and forcing material innovation.
- Trade and Tariff Pressures. Geopolitical factors continue to influence cost structures. US Section 301 tariffs impose 25 percent duties on Chinese-origin plastic packaging films and reels. For North American buyers and importers, this alters the cost-benefit analysis of offshore sourcing versus domestic or near-shore production. Strategic sourcing decisions in 2026 must factor in tariff exposure, lead time variability, and the potential for supply chain reconfiguration.
These dynamics are not isolated. They interact with raw material economics, such as the recent decline in HDPE resin prices for packaging films to $0.92 per pound in North America during Q1 2024. While lower resin costs can improve margins, they also invite scrutiny from regulators and consumers regarding the environmental profile of plastic-based solutions. The strategic imperative is to balance cost efficiency with compliance and brand positioning, a balance that requires precise data on material substitution pathways and cost modeling.
Competitive Landscape and Strategic Positioning
The market is characterized by a mix of global multinationals and specialized regional players, with concentration metrics indicating a moderately consolidated environment. The CR3 stands at 38.45 percent and the CR5 at 52.1 percent, suggesting that while leading firms hold significant share, a substantial portion of the market remains distributed among mid-tier and niche suppliers. This structure creates opportunities for both consolidation and differentiation, depending on a company's capabilities in material science, geographic reach, and customer intimacy.
Worldwide Packaging Reel Market
Leading organizations are actively reshaping their portfolios to address the trends outlined above. Several recent developments illustrate the strategic directions being taken by key participants:
- Material Innovation and Circular Design. Amcor exhibited recyclable mono-material film reels at PACK EXPO International in October 2024, signaling a shift toward formats that simplify recovery and recycling. Mondi launched the Advantage Reel Wrapper, a recyclable paper-based reel cover, in September 2023, showcasing paper-plastic hybrid and mono-material approaches for sustainable flexible packaging. Berry Global introduced NatureWorks-based bio-resin film reels in May 2023, expanding the use of bio-based feedstocks in flexible applications.
- Performance and Application-Specific Engineering. Uflex showcased a new generation of BOPP reels with enhanced printability at PlastIndia in February 2024, reflecting ongoing investment in surface performance and converter usability. Huhtamäki continues to offer high-barrier EVOH and PA co-extruded film reels for extended shelf-life food packaging, addressing the demand for preservation and waste reduction. Constantia Flexibles provides aluminum-laminated and plastic film reels for premium consumer and medical packaging, while Coveris specializes in fresh food flexible film reels with high puncture resistance.
- Diversified Regional Footprints. Companies such as Sealed Air supply Cryovac multilayer shrink and barrier film reels for protein packaging, leveraging scale and technical expertise. Sonoco delivers flexible packaging reel stock including stand-up pouch precursors, supporting a broad range of end-use formats. Winpak manufactures medical-grade and food-safe barrier film reels, while Inteplast supplies PE stretch and shrink film reels for industrial packaging. In the Asia-Pacific region, Uflex exports BOPET, BOPP, and metalized film jumbo reels to global converters, and Cosmo Films produces thermally laminatable BOPP and BOPET reels for overwrap and label applications. These regional capabilities are increasingly relevant as buyers seek to mitigate tariff risk and shorten supply chains.
The competitive game is shifting from pure price competition to value-based differentiation. Suppliers that can demonstrate compliance with recycled content thresholds, offer mono-material or recyclable formats, and provide application-specific performance will capture premium positioning. Conversely, undifferentiated commodity reel products face margin compression and heightened exposure to regulatory and tariff headwinds. Our full report provides a detailed competitive profiling framework, including capability mapping and strategic group analysis, to help leadership teams benchmark their position and identify partnership or acquisition targets.
Segmentation Themes and Growth Vectors
While the aggregate market growth is compelling, the real strategic insight lies in understanding how value is distributed across materials, regions, and end-use applications. The full study deconstructs these dimensions to reveal where growth is concentrated and which segments face structural headwinds or tailwinds.
On the material axis, plastic reels continue to represent the largest share of market value, driven by their versatility, barrier properties, and integration with high-speed converting equipment. However, paper and fiberboard reels are gaining attention as brands seek to reduce plastic intensity and improve recyclability profiles. Metal reels maintain a specialized role in high-durability and precision applications. The interplay between these material categories is being reshaped by regulation, consumer preference, and total cost of ownership calculations that include waste management and compliance costs.
Regionally, the market exhibits distinct characteristics. Asia Pacific remains a central hub for both production and consumption, with strong industrial output and growing domestic demand. North America and Europe are characterized by mature markets where growth is increasingly driven by innovation, premiumization, and regulatory compliance rather than volume expansion alone. Latin America and the Middle East and Africa present emerging opportunities, though they vary significantly in terms of infrastructure readiness, regulatory frameworks, and foreign exchange exposure. The complete report provides a nuanced view of these regional dynamics without over-simplifying the heterogeneous nature of local markets.
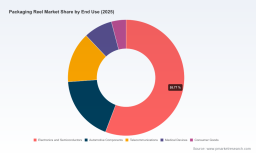
End-use segmentation further refines the growth picture. Electronics and semiconductors represent a high-performance segment where reel quality, cleanliness, and consistency are paramount. Automotive components demand durable and traceable packaging solutions that align with stringent quality standards. Telecommunications, medical devices, and consumer goods each impose unique requirements on reel format, handling, and material properties. The medical devices segment, for example, involves higher barriers to entry and stricter validation processes, while consumer goods are more sensitive to sustainability messaging and cost pressures. Understanding the relative attractiveness of each end-use vertical is essential for prioritizing sales investments, R&D bandwidth, and capacity planning.
The Strategic Value of Granular Intelligence in 2026
For decision-makers, the difference between a directional market view and a precise, actionable intelligence package can determine the success of a product launch, the timing of a capacity investment, or the outcome of a supplier negotiation. The Worldwide Packaging Reel Market research report is designed to bridge that gap. It goes beyond top-line figures to deliver the operational detail required for strategic execution.
The report's core components include:
- Historical Reconstruction and Forecast Modeling. A rigorous reconstruction of market performance from 2020 to 2025, integrated with a bottom-up forecast model spanning 2026 to 2032. This enables scenario planning around base, upside, and downside cases, with clear drivers identified for each.
- Segmentation Deep-Dives. Detailed breakdowns by region, material, and end-use, with analysis of volume and value trends, substitution patterns, and segment-specific regulatory impacts. This allows teams to target the most attractive sub-markets and avoid over-indexed exposure to declining segments.
- Competitive Benchmarking. Profiles of key companies, including headquarters, product focus, and recent strategic moves. The report includes a structured competitive analysis that maps capabilities, geographic coverage, and strategic positioning, supporting M&A screening, partnership evaluation, and competitive response planning.
- Regulatory and Trade Impact Assessment. A synthesis of the most material regulations, taxes, mandates, and tariffs affecting reel formats, with practical guidance on compliance pathways and cost implications. This section is updated to reflect the latest policy developments and is designed to feed directly into risk registers and procurement strategies.
- Market Concentration and Structure Analysis. Metrics on concentration, alongside qualitative assessment of barriers to entry, capacity dynamics, and the role of converters and integrators in the value chain. This helps leadership teams understand where power sits in the supply chain and how to negotiate from a position of informed strength.
This depth of analysis is particularly valuable as organizations prepare for 2026. The combination of moderate market growth, regulatory complexity, and evolving competitive dynamics means that generic market narratives are insufficient. Executives need to know which subsegments offer the best risk-adjusted returns, how material substitution will affect cost structures, and where competitors are likely to pivot. The full report delivers this level of specificity, enabling data-driven decisions rather than assumption-based planning.
Conclusion: Turning Market Insight into Strategic Advantage
The Worldwide Packaging Reel Market is entering a phase where growth and complexity are intertwined. A 5.18 percent CAGR over the forecast period signals continued expansion, but the value of that growth will accrue to organizations that can navigate material transitions, regulatory requirements, and regional asymmetries with precision. The macro trajectory is favorable; the micro execution is where competitive advantage will be won or lost.
This article has outlined the strategic context and the breadth of analysis available in our upcoming study. To move from awareness to action, leaders need the full dataset: segment-level valuations, regional growth decompositions, end-use performance comparisons, and detailed competitive profiles. These insights are essential for building resilient sourcing strategies, prioritizing innovation investments, and aligning commercial plans with the realities of 2026 and beyond.
We invite strategy, procurement, and commercial leaders to access the complete Worldwide Packaging Reel Market research for a comprehensive view of the market's architecture and trajectory. The full report translates the directional signals discussed here into the granular intelligence required to make confident, forward-looking decisions in a market that rewards clarity and preparation.
For detailed analysis of this topic, please visit the official page: Worldwide Packaging Reel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com