

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Blog
PW Consulting: Global Skin Care Tubes to Reach $18.5B in 2025, Growing at 5.45% CAGR to 2032
By pmarketresearch, 2026-09-16
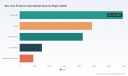
Strategic Horizons in the Global Skin Care Products Tubes Market: Navigating Growth and Sustainability Through 2032
Executive Summary: The Imperative for Precision Intelligence
The packaging sector for skin care products stands at a critical inflection point. As consumer preferences shift rapidly toward sustainability and regulatory frameworks tighten across major economies, manufacturers and brands alike face a complex landscape defined by both opportunity and constraint. Our latest comprehensive study on the Worldwide Skin Care Products Tubes Market provides a detailed roadmap for navigating this environment from 2026 through 2032. This article serves as a strategic primer, outlining the market's trajectory, competitive intensity, and the actionable intelligence embedded within our full report. For stakeholders aiming to secure market share or optimize supply chains, understanding the macro trends is only the first step; accessing granular, segment-specific data is essential for precise execution.
Market Trajectory and Historical Performance
The global market for skin care tubes has demonstrated robust resilience and steady expansion over the past half-decade. Historical data indicates a consistent upward trend in revenue, reflecting the enduring demand for convenient and protective packaging solutions in the personal care industry. Building on this momentum, the market is projected to achieve significant valuation milestones in the forecast period. The overall revenue trajectory suggests a Compound Annual Growth Rate (CAGR) of 5.45 percent, signaling stable growth driven by both volume expansion and value innovation.
This growth is not merely a reflection of population increases but is intricately linked to product formulation advancements and packaging technology. As brands differentiate themselves through premium offerings and specialized delivery systems, the tube segment continues to capture a substantial portion of total packaging expenditure. The forecast period from 2026 to 2032 anticipates continued capitalization on these trends, though stakeholders must remain vigilant regarding input cost volatility and regional regulatory disparities that could impact margin structures.
Segmentation Dynamics: Material and Application Perspectives
A nuanced understanding of market segmentation is crucial for identifying high-potential niches. The market is primarily categorized by material type, encompassing plastic, laminated, and aluminum tubes. Each material category serves distinct functional requirements and consumer perceptions. Plastic tubes remain a dominant force due to their versatility and cost-effectiveness, while laminated options are gaining traction for their ability to combine barrier properties with lightweight design. Aluminum tubes continue to hold relevance in specific premium segments where product integrity and recyclability are paramount.
In terms of application, the demand is distributed across various personal care categories. Face care products represent a significant portion of consumption, driven by the high frequency of use and the need for hygienic dispensing. Body care and hand care segments also contribute substantially, reflecting broader wellness trends. Additionally, the sun care category, while smaller in volume compared to daily care products, presents unique challenges regarding UV protection and packaging durability. Our full analysis delves into the specific revenue contributions and growth rates of each segment, providing the data necessary to prioritize resource allocation.
Key segmentation areas covered in depth include:
- Material Preferences: Analysis of plastic, laminated, and aluminum trends including recyclability metrics and barrier performance.
- Application Verticals: Detailed breakdowns for face care, body care, hand care, and sun care formulations.
- Regional Performance: Evaluation of market strength across Asia Pacific, Europe, North America, Latin America, and the Middle East and Africa.
Competitive Landscape and Strategic Positioning
The competitive environment is characterized by a mix of global packaging giants and specialized manufacturers. Market concentration metrics indicate that while the top players hold a significant share, the market remains fragmented enough to allow for strategic entry and niche domination. The CR3 ratio stands at 28.45 percent, and the CR5 ratio is 39.12 percent, suggesting that consolidation is present but not absolute. This structure allows agile companies to compete through innovation rather than scale alone.
Several key companies define the current competitive boundaries. Albéa Group, headquartered in France, remains a global leader in manufacturing laminated, plastic, and aluminum tubes, recently emphasizing sustainable options like mono-material tubes. Silgan Holdings Inc. in the United States provides dispensing systems and plastic tubes specialized for skincare packaging through its dedicated division. AptarGroup Inc. offers beauty and personal care packaging including airless and pump tubes, catering to formulations that require advanced preservation. Amcor plc, based in Switzerland, produces flexible packaging solutions with a focus on recyclable and high-barrier materials.
Worldwide Skin Care Products Tubes Market
Further adding to the competitive depth are Berry Global Group Inc., known for lightweight and sustainable rigid and flexible tubes; Huhtamäki Oyj from Finland, supplying laminate tubes with mono-material recyclability; Virospack S.A. in Spain, specializing in premium airless systems; and Intrapac International Pty Ltd in Australia, providing custom tubes and dispensers across global markets. Recent activities highlight the pace of innovation. For instance, Albéa Group launched a recyclable snap-top tube at Cosmoprof North America in late 2024. AptarGroup exhibited new airless tubes for clean beauty at in-cosmetics Global earlier that year. Berry Global also achieved significant sustainability certification in spring 2024. These moves underscore the industry's pivot toward ecological responsibility and functional superiority.
Industry Dynamics: Regulations, Materials, and Trade Barriers
External factors are reshaping the operational landscape for tube manufacturers and brand owners. Regulatory compliance is becoming increasingly complex. The European Union's Packaging and Packaging Waste Regulation mandates 30 percent recycled content in plastic packaging by 2030. This requirement forces supply chain adjustments and potentially higher material costs, necessitating proactive sourcing strategies. Simultaneously, the US FDA requires child-resistant closures on certain skincare tubes exceeding 125ml volume, adding a layer of design consideration for products targeting specific demographics or regions.
Worldwide Push-up Paperboard Tube Market
Raw material costs remain a volatile element. HDPE resin prices in Europe averaged €1,450 per metric ton in the fourth quarter of 2025, impacting tube production costs globally. Such fluctuations require sophisticated hedging strategies and efficient manufacturing processes to maintain profitability. On the trade front, US Section 301 tariffs on Chinese plastic packaging imports remain at 25 percent as of 2026. This tariff structure influences sourcing decisions, encouraging companies to diversify supply chains or localize production where feasible.
Macro trends also play a pivotal role. Global demand for sustainable tubes grew 12 percent year-over-year, driven by clean beauty preferences. This shift is not merely a consumer preference but a strategic imperative for brands seeking to align with Environmental, Social, and Governance (ESG) goals. Companies that fail to adapt to these sustainability expectations risk losing shelf space and consumer loyalty. Our report analyzes how these dynamics interact with regional market sizes and segment growth to identify vulnerable and opportunity-rich zones.
Strategic Recommendations for 2026 and Beyond
To capitalize on the projected market expansion, stakeholders should consider several strategic pillars. First, sustainability integration must move beyond marketing claims to verifiable supply chain actions. Investing in mono-material solutions and recyclable designs will mitigate regulatory risks and align with consumer demand. Second, supply chain resilience is critical given the tariff environment and raw material volatility. Diversifying sourcing locations and securing long-term contracts for key resins can buffer against cost spikes. Third, innovation in dispensing mechanisms offers a pathway to premiumization. Airless and pump technologies not only protect sensitive formulations but also enhance user experience, justifying higher price points.
For investors and market entrants, understanding the regional nuances is vital. While Asia Pacific represents a vast volume opportunity, maturity levels and regulatory maturity vary significantly within the region. Europe presents high regulatory hurdles but also high willingness to pay for sustainable solutions. North America remains a strong market for premium innovation but is sensitive to trade policy changes. A one-size-fits-all strategy is unlikely to succeed; tailored approaches based on granular market data are required.
Conclusion: Accessing Granular Intelligence
The Worldwide Skin Care Products Tubes Market offers substantial growth potential, but realizing this value requires more than high-level trends. It demands precise data on regional revenue splits, segment-specific CAGRs, and detailed competitive profiling. The insights outlined here provide a foundational understanding of the market's direction, yet the full spectrum of opportunities and risks is detailed in our comprehensive report. For decision-makers ready to deepen their market intelligence, accessing the complete dataset is the next logical step. The detailed segmentation, historical data tables, and forward-looking analysis contained within the full study are designed to support concrete strategic decisions in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Skin Care Products Tubes Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Automotive Optoelectronic Market to Reach $15.5B by 2032 at 13.85% CAGR
By pmarketresearch, 2026-09-16
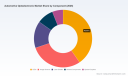
Navigating the Light-Driven Era: Strategic Intelligence for the Worldwide Automotive Optoelectronic Market Through 2032
The automotive industry is undergoing a fundamental recalibration of how vehicles perceive, communicate, and illuminate their surroundings. At the center of this transformation lies the optoelectronic subsystem, a critical enabler of advanced driver assistance, adaptive illumination, and next-generation human-machine interfaces. As automakers and tier-one suppliers navigate tightening safety mandates, semiconductor capacity realignments, and rapidly evolving LiDAR and camera architectures, access to granular, forward-looking market intelligence is no longer optional. It is a prerequisite for capital allocation, supplier selection, and technology roadmapping.
PW Consulting’s latest Worldwide Automotive Optoelectronic Market study provides a structured, data-backed framework for decision-makers operating across the automotive value chain. Drawing on a multi-year historical baseline spanning 2020 through 2025 and a comprehensive forecast window extending to 2032, this report maps the trajectory of a market that has consistently outpaced traditional automotive component growth cycles. For executive teams planning product portfolios, securing supply agreements, or evaluating partnership opportunities in 2026, the study delivers the analytical rigor required to separate structural trends from short-term volatility.
A Decade of Acceleration: What the Numbers Reveal About Market Scale and Trajectory
The macroeconomic arc of the automotive optoelectronic sector tells a clear story of compounding demand. From a baseline of approximately 3,450 million USD in 2020, the market expanded through successive growth phases to reach roughly 6,250 million USD by 2025. This progression reflects the accelerating integration of optical sensing, LED-based illumination, and laser-driven ranging technologies into mainstream vehicle architectures. Looking ahead, the forecast period from 2026 through 2032 projects continued expansion at a compound annual growth rate of 13.85 percent, with market valuation climbing steadily toward the mid-15,000 million USD range by the end of the outlook window.
These figures are not merely historical footnotes. They represent the quantitative foundation for capacity planning, R&D prioritization, and regional investment decisions. A sustained double-digit growth trajectory of this magnitude signals that optoelectronic components are transitioning from peripheral accessories to core architectural elements. For automotive OEMs, tier-one integrators, and semiconductor manufacturers, the implication is straightforward: timing, product differentiation, and supply chain resilience will determine competitive positioning in the years ahead. The report contextualizes these macro trends within component-level adoption curves, application-driven demand cycles, and regional deployment patterns, giving strategists the scaffolding needed to model revenue scenarios and assess market entry or expansion opportunities.
Inside the Research: How the Report Translates Data Into Actionable Intelligence
Market studies are only as valuable as their ability to inform real-world decisions. This report is structured around operational utility, combining quantitative forecasting with qualitative analysis of technology adoption, regulatory impact, and competitive positioning. The analytical framework covers component segmentation, application-driven demand mapping, geographic deployment dynamics, and concentration metrics that reveal where value is accumulating across the supply chain. Rather than presenting isolated statistics, the study weaves together cross-referencing layers that allow readers to trace how shifts in one segment—such as safety regulation or sensor architecture—ripple through adjacent markets and supplier ecosystems.
Readers will find detailed assessments of how lighting systems, advanced driver assistance platforms, infotainment and telematics architectures, and powertrain-related optical applications are reshaping procurement priorities. The report also examines the structural forces compressing or expanding margins, including raw material price stabilization, fab capacity constraints, and the certification requirements that govern safety-critical deployments. By aligning historical performance with forward-looking indicators, the study equips teams with the benchmarks needed to evaluate supplier competitiveness, forecast component availability, and stress-test product launch timelines against emerging technological and regulatory milestones.
Worldwide Automotive Optoelectronic Market
Worldwide LNOI Optoelectronic Chip Market
Competitive Dynamics: Where Leaders Are Positioning for the Next Wave
The automotive optoelectronic landscape is defined by a concentrated yet highly active supplier base. Top-tier players account for a meaningful share of total market revenue, with the leading three firms collectively representing approximately 38.5 percent of industry output and the top five capturing just over half of total revenue. This concentration underscores the strategic importance of supplier relationships, technology partnerships, and continuous product innovation. Companies that can align component performance with automotive-grade reliability, cost efficiency, and program scalability are increasingly becoming gatekeepers for next-generation vehicle platforms.
Several foundational players anchor this ecosystem through differentiated technology portfolios. European and Austrian-based innovators have deepened their focus on automotive LEDs, VCSEL arrays, photodiodes, and ambient light sensing solutions tailored for headlights, ADAS modules, and interior lighting environments. German semiconductor manufacturers continue to supply optoelectronic components spanning LEDs, infrared emitters, and detectors that support both sensing and illumination functions. Swiss-headquartered firms have expanded their automotive-qualified CMOS image sensor and time-of-flight offerings, including specialized sensor families designed for ADAS and gesture recognition. Japanese technology leaders remain pivotal in high-power blue LEDs, laser diodes, and UV LED architectures that enable advanced headlight systems and LiDAR applications, while South Korean manufacturers have introduced wafer-level chip-on-plate and next-generation LED platforms targeting exterior lighting, smart headlights, and display integration.
Meanwhile, Dutch specialists have scaled high-power LED architectures for forward lighting, matrix beam systems, and adaptive illumination. American-based sensor developers are pushing ultra-low-light CMOS image sensor performance for ADAS cameras and surround-view applications. Japanese semiconductor solution providers continue to supply stacked CMOS image sensors engineered for automotive vision systems and ADAS workloads. Additional U.S.-based suppliers have broadened their portfolios with image sensor arrays, ambient light sensing, and VCSEL driver technologies. Swiss connectivity experts contribute fiber optic connectors, optical sensors, and encoders for data transmission and sensing applications, while Taiwanese manufacturers round out the ecosystem with surface-mount LEDs and photointerrupter solutions for interior, exterior, and sensor-related deployments.
Recent product activity illustrates how quickly this competitive field is evolving. In early 2024, one European technology group unveiled a multi-pixel matrix laser light source designed for dynamic high-beam automotive lighting, signaling a shift toward highly programmable illumination architectures. Around the same period, a South Korean LED manufacturer showcased a platform integrating digital micro-mirror devices for smart adaptive headlights, highlighting the convergence of optical components and display technologies. In late 2023, a Swiss semiconductor firm introduced a QVGA global shutter image sensor qualified for automotive ADAS applications, reinforcing the industry’s emphasis on latency-sensitive vision systems. At a major mobility trade show that same year, a Japanese company presented a high-lumen laser diode targeting short- and mid-range LiDAR use cases, while a U.S. sensor supplier had previously launched a global shutter image sensor optimized for automotive machine vision and robotics-related applications. These developments are not isolated product launches; they are indicators of where R&D capital is flowing and which technology pathways are gaining commercial traction.
Market Forces Shaping the 2026–2032 Horizon
The growth trajectory of automotive optoelectronics cannot be understood in isolation from the regulatory, geopolitical, and supply-side forces that surround it. Safety regulations are increasingly dictating sensor and camera deployment. The EU General Safety Regulation mandates camera-based systems for emergency braking and intelligent speed assistance beginning in mid-2024, directly accelerating demand for vision components and associated optical subsystems. At the same time, functional safety standards require automotive optoelectronic sensors operating in safety-critical ADAS functions to meet ASIL-B through ASIL-D certification thresholds, raising the bar for qualification, testing, and long-term reliability.
Geopolitical and industrial policy dynamics are also reshaping manufacturing and sourcing strategies. Major semiconductor subsidy frameworks, including the U.S. CHIPS and Science Act’s substantial funding pool for domestic production, are influencing where automotive-grade optoelectronic components are designed, fabricated, and assembled. These incentives are encouraging regional capacity investments, but they also introduce new considerations around supply continuity, qualification lead times, and multi-source strategies.
Supply chain volatility remains a persistent variable. Disruptions such as the April 2024 seismic event in Taiwan, which temporarily halted production at major fabrication facilities and delayed automotive CMOS image sensor deliveries, serve as reminders that concentration risk in advanced semiconductor manufacturing can quickly translate into program delays and inventory pressure. On the materials front, price dynamics for key enablers such as GaN-on-Si epiwafers have shown stabilization after earlier upward pressure, reflecting capacity expansions in Japan and Europe. These cost and availability signals matter deeply for margin modeling and for decisions about long-term supply agreements.
Why This Study Matters for 2026 Decision-Making
As organizations enter 2026, the strategic questions facing automotive and semiconductor teams are becoming more specific and more urgent. Which component categories will capture the steepest adoption curves? How will regional demand patterns shift as safety mandates take effect and local semiconductor ecosystems mature? Where are suppliers gaining structural advantages through technology differentiation, and where is consolidation likely to intensify? The Worldwide Automotive Optoelectronic Market report is designed to answer these questions with the precision required for executive planning.
The study provides a complete analytical foundation for evaluating market entry, portfolio expansion, supplier qualification, and technology investment. It aligns historical performance with forward forecasts, embeds regulatory and supply-side context into segment-level analysis, and maps competitive positioning across a globally distributed supplier base. For organizations that need to move beyond high-level industry narratives and into detail-grade market intelligence, this report offers the structure, data depth, and strategic context necessary to make informed decisions with confidence.
To access the full segmentation breakdowns, regional demand mappings, competitive benchmarking details, and complete forecast tables, we invite you to explore the complete report on our website. The insights outlined here represent a strategic preview; the full study delivers the comprehensive intelligence needed to shape your 2026 roadmap and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Optoelectronic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: L7 and L6 Quadricycles Market Projected to Hit $3,887 Million by 2032
By pmarketresearch, 2026-09-16
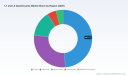
Strategic Horizons: Navigating the 2026-2032 Evolution of the L7 and L6 Quadricycles Market
The light quadricycle sector is standing at a definitive inflection point. As urban congestion intensifies across major metropolitan regions and regulatory frameworks tighten around low-emission zones, the demand for L6 and L7 quadricycles has transitioned from a niche alternative to a core component of modern mobility strategies. For industry stakeholders, understanding the trajectory of this market is no longer optional. It is a strategic imperative.
PW Consulting's latest comprehensive study on the L7 and L6 Quadricycles Market provides a granular roadmap of this transformation. Spanning historical analysis from 2020 through base year 2025 and extending forecasts to 2032, this research is designed to equip decision-makers with the foresight required to navigate a landscape defined by electrification, regulatory shifts, and evolving consumption patterns. This article outlines the strategic value of the report, highlighting the macro-economic currents and competitive dynamics that will define the next cycle of growth.
Macro-Economic Trajectory and Growth Vectors
The financial scale of the quadricycles market underscores its increasing relevance. Valued at approximately 1,425.5 million USD in 2020, the market has demonstrated consistent resilience and expansion, reaching an estimated 2,350.0 million USD by 2025. This trajectory signals more than cyclical recovery; it reflects a structural shift in how light mobility is perceived and utilized in urban and semi-urban environments.
Looking forward, the forecast period from 2026 to 2032 projects robust continued expansion. The analysis anticipates the market will surpass 2,827.95 million USD by 2027, eventually climbing toward 3,887.0 million USD by the end of the forecast horizon. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 7.45 percent. For corporate strategy teams, this figure suggests a stable investment environment with clear avenues for revenue generation, provided that product portfolios align with shifting consumer preferences and regulatory mandates.
It is critical to note that this growth is not uniform across all vectors. The transition from internal combustion engine (ICE) models to electric alternatives is reshaping the value chain. By the first half of 2025, over 82 percent of new quadricycles sold in key European markets were fully electric, a statistic that highlights the velocity of this technological pivot. Strategic planning that relies on legacy ICE frameworks risks obsolescence in this rapidly electrifying ecosystem.
The Competitive Landscape: Consolidation and Innovation
The market structure is characterized by a mix of specialized heritage manufacturers and agile electric mobility newcomers. Our detailed analysis indicates a moderately concentrated environment, with the top three companies holding a significant share of the market and the top five managing over half of the total revenue. This concentration suggests that while opportunities exist for smaller players, the path to scale increasingly requires strong partnerships, proprietary technology, or aggressive expansion into underserved segments.
Ligier Group (France) remains a dominant force, particularly with its JS50 internal combustion models and the expanding Myli electric lineup. Their strategic direction was highlighted in late 2024 with the debut of redesigned JS50 and Myli 2025 electric models at the Paris Motor Show. Moving into 2025, the group deepened its technological moat through a strategic partnership with Niu Technologies in January, aimed at co-developing a new electric L6/L7 quadricycle platform integrating advanced battery and motor systems. This collaboration positions Ligier to leverage external expertise to accelerate electrification without compromising its core manufacturing capabilities.
Aixam (Polaris) (France) continues to lead in the license-free passenger and commercial space under its Aixam and Mega brands. Their focus on both electric and ICE variants allows them to cover a broad spectrum of user needs, from restricted-license drivers to commercial fleets seeking cost-effective utility solutions.
In the utility and commercial domain, Goupil Industrie (France), also part of the Polaris group, has carved out a specialized niche. In March 2025, the company secured a major contract to supply 1,000 electric quadricycles to the City of Paris for municipal fleet use. This win validates the commercial viability of electric L7e vehicles for municipal logistics and points toward a growing public-sector demand driver.
Tazzari EV (Italy) represents the agility of the EV specialist. Offering models like the ZEROMAX 45 (L6e) and ZEROMAX 80 and Zero 4 (L7e), Tazzari targets urban commuting and adventure variants, appealing to consumers seeking personalization and off-road capability within the light quadricycle classification.
Stellantis (France/Italy), through its Citroën, Fiat, and Opel brands, has brought significant mainstream attention to the L6e segment with urban micro-mobility icons like the Citroën Ami and Fiat Topolino. These mass-market offerings help normalize electric quadricycles for broader consumer adoption. Similarly, Renault (Mobilize) is pushing the L7e boundary with models like the Mobilize Duo and Bento, designed explicitly for shared and commercial urban use, aligning with the growing shared mobility infrastructure.
Piaggio (Italy) has shown aggressive intent to expand its footprint. In May 2025, the company completed the acquisition of Quadro Vehicles' European operations to expand its L6/L7 electrification portfolio. This acquisition signals a consolidation trend among larger industrial groups seeking to secure proprietary technology and market access in the light vehicle segment.
Other notable players such as Automobiles Chatenet (France) with its high-end CH46 and electric CH46E variants, Casalini Srl (Italy) with its established Sulky and M10 series, and Piaggio 's broader L-category involvement, contribute to a diverse ecosystem where differentiation is driven by brand prestige, utility focus, and electrification strategy.
Regulatory and Structural Dynamics
The operating environment for L6 and L7 quadricycles is heavily defined by European regulatory frameworks. EU Regulation (EU) No 168/2013 establishes the technical boundaries for these vehicles. L6e quadricycles are capped at a maximum unladen mass of 425 kg (excluding batteries), a speed limit of 45 km/h, and a power output of 6 kW. L7e heavy quadricycles allow for a higher mass limit (up to 450 kg or 600 kg depending on configuration), a power cap of 15 kW, and speeds up to 90 km/h.
L7 and L6 Quadricycles Market
These technical definitions directly influence market segmentation and user adoption. Licensing regulations further shape the consumer base. In many EU countries, L6e quadricycles can typically be driven with an AM license or a standard Category B car license from ages 14 to 16. L7e vehicles often require a B1 license. This regulatory accessibility makes L6 models particularly attractive for younger demographics or those seeking license-free mobility, while L7 models appeal to users requiring higher performance or cargo capacity who meet the necessary licensing criteria.
The regulatory push toward electrification is also a critical dynamic. As low-emission zones expand and urban access restrictions tighten, the operational flexibility of zero-emission quadricycles becomes a significant competitive advantage. The surge in electric registrations, such as the +34 percent growth in L6 registrations in Italy in 2024, demonstrates how regulatory tailwinds and consumer environmental awareness are converging to drive adoption.
Segmentation and Application Nuances
Understanding where value is generated requires a nuanced look at segmentation. The market is divided into L6 light quadricycles and L7 heavy quadricycles. Current analysis shows that L6 models account for a substantial portion of the revenue mix, valued at approximately 1,408.76 million USD, while L7 models contribute around 941.24 million USD. However, the relative weight of these segments can shift rapidly based on electrification trends, as L7 platforms are often favored for commercial utility applications that require greater payload and range.
Application-wise, the market splits between Personal Use and Commercial Use. Personal use currently represents a significant share of the market, valued at 1,508.71 million USD, driven by individual commuters, second-car households, and recreational users. Commercial use, valued at 841.29 million USD, is a high-growth area fueled by last-mile delivery, municipal fleets, and industrial site mobility. The commercial segment is particularly sensitive to total cost of ownership (TCO) calculations, where electric quadricycles often offer compelling advantages in operating costs and maintenance over ICE equivalents.
Geographic distribution also plays a role in shaping strategy. Europe remains the dominant revenue generator for this market, reflecting the deep cultural integration of quadricycles and the supportive regulatory environment. Asia Pacific and North America present distinct opportunities and challenges, ranging from different regulatory classifications to varying consumer acceptance of micro-mobility. Our report delves into these regional nuances, analyzing how market maturity and local dynamics influence entry strategies and growth potential.
Operational Intelligence Within the Report
PW Consulting's L7 and L6 Quadricycles Market research is structured to move beyond high-level statistics and provide actionable intelligence for strategic planning. The report includes a detailed examination of the following components:
- Historical and Forecast Volume Analysis: A comprehensive review of market performance from 2020 to 2032, allowing stakeholders to benchmark internal performance against broader industry trends and anticipate future demand cycles with greater accuracy.
- Deep-Dive Segmentation: Detailed breakdowns of the L6 and L7 categories, as well as personal versus commercial applications, to identify niche opportunities, assess market saturation, and prioritize R&D or production focus areas.
- Competitive Positioning and Benchmarking: Profiles of key companies including Ligier, Aixam, Tazzari, Goupil, Chatenet, Casalini, Stellantis, Renault, and Piaggio, analyzing their product portfolios, recent strategic moves, and competitive advantages. This section helps identify white space for new entrants or partnership opportunities for incumbents.
- Recent Developments Tracking: A chronology of critical events, such as Ligier's partnership with Niu, Goupil's Paris municipal contract, and Piaggio's acquisition of Quadro Vehicles, providing context on how strategic actions are reshaping the competitive landscape in real-time.
- Regulatory Impact Assessment: An evaluation of how EU regulations and licensing frameworks affect vehicle design, market access, and consumer adoption, enabling compliance planning and risk mitigation.
- Electrification Transition Analysis: Insights into the shift toward electric powertrains, including adoption rates, infrastructure considerations, and the strategic implications for manufacturers transitioning from ICE to EV platforms.
By integrating these elements, the report serves as a decision-support tool for product managers, market strategists, investors, and policy advisors. It answers critical questions about where the market is going, which players are leading the charge, and how regulatory and technological forces will reshape the value chain over the coming years.
Strategic Imperatives for 2026 and Beyond
As the market approaches 2026, stakeholders must align their strategies with the converging forces of electrification, regulatory compliance, and application diversification. The data points to a market that is growing steadily but changing rapidly in composition.
Motorized Quadricycles Market
For manufacturers, the priority is to accelerate the transition to electric platforms while managing the cost and complexity of the shift. Partnerships, such as the one between Ligier and Niu, illustrate one path to mitigating development risks. For commercial fleet operators and urban mobility providers, the focus should be on total cost of ownership and suitability for specific use cases, leveraging the growing body of evidence that electric quadricycles can deliver efficient, compliant urban logistics.
For investors and analysts, the concentration dynamics and recent M&A activity, like Piaggio's acquisition, suggest that value is consolidating around players with strong electrification capabilities, robust distribution networks, and clear alignment with municipal or shared mobility trends. Understanding the nuances of each segment and the strategic moves of key competitors is essential for capitalizing on the market's expansion toward the projected 3,887.0 million USD by 2032.
The L7 and L6 Quadricycles Market is no longer a peripheral curiosity; it is a dynamic sector at the heart of the urban mobility revolution. This latest PW Consulting research provides the depth, context, and foresight necessary to navigate this evolution with confidence. We invite you to explore the full report to access the comprehensive data, detailed segmentation analysis, and strategic recommendations that will inform your decisions in this pivotal market.
For detailed analysis of this topic, please visit the official page: L7 and L6 Quadricycles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Atmospheric Water Generator Market Hits $3.46B in 2025, Growing at 17.15% CAGR
By pmarketresearch, 2026-09-16
The Strategic Imperative of Atmospheric Water Generation: Navigating Market Dynamics and Growth Trajectories Through 2032
Introduction: The Convergence of Scarcity and Innovation
The global atmospheric water generator market is no longer a niche technological curiosity; it is rapidly evolving into a critical pillar of decentralized water infrastructure. As water stress intensifies across multiple geographies and industrial supply chains face mounting environmental compliance pressures, organizations are seeking alternative, resilient sources of potable and process water. Our latest Worldwide Atmospheric Water Generator Market research is designed to equip executives, investors, and strategic planners with the analytical rigor needed to make informed decisions in 2026 and beyond. This publication does not merely track historical performance; it maps the compounding forces that will shape procurement strategies, product development roadmaps, and competitive positioning through the end of the decade.
For decision-makers, the urgency is clear. Water infrastructure is being redefined by climate volatility, urban expansion, and the rise of off-grid and hybrid energy systems. Atmospheric water generation sits at the intersection of these trends, offering a distributed alternative to conventional extraction, treatment, and transport models. Understanding how this market scales, where value concentrates, and which competitive strategies will dominate requires more than headline figures. It demands a structured assessment of technological pathways, regional adoption drivers, application-specific demand profiles, and the regulatory and partnership dynamics that accelerate or constrain deployment.
Market Trajectory: Compounding Growth from 2020 to 2032
The macro arc of atmospheric water generation reflects a market in the early-to-mid stages of a sustained expansion cycle. Historical revenue data from 2020 through 2025 reveals a consistent upward progression, driven by incremental commercialization, improving system efficiency, and early adoption across industrial and commercial end-use environments. That momentum is projected to intensify over the forecast horizon, with revenue scaling toward a multi-billion-dollar annual footprint by the early 2030s. The compound annual growth rate anticipated across the 2026 to 2032 period underscores a structural shift rather than a cyclical uptick: adoption is broadening, unit economics are improving, and new use cases are emerging as the technology matures.
For corporate planners, this trajectory carries several strategic implications. First, the growth rate suggests that atmospheric water generation is transitioning from pilot-scale experimentation to repeatable commercial deployment. Second, the revenue acceleration indicates that product differentiation, reliability, and integration with renewable energy or building management systems are becoming decisive value drivers. Third, the widening gap between earlier historical baselines and later forecast years signals that the window for market definition is narrowing. Organizations that establish supply relationships, validation credentials, and regional partnerships now will be better positioned to capture share as the addressable base expands. The detailed revenue pathways, milestone inflection points, and scenario analyses are presented in full within the published report, enabling readers to benchmark internal projections against a rigorously constructed market baseline.
What the Report Delivers: A Practitioner's Toolkit for 2026 Decision-Making
This study is structured around actionable intelligence rather than abstract commentary. It translates market data into operational guidance across multiple dimensions that matter to procurement, R&D, sales strategy, and corporate development teams.
- Comprehensive historical reconstruction supporting the base year, alongside transparent trajectory mapping into the 2026 to 2032 window, so leadership can align budget assumptions and capacity planning with externally validated demand signals.
- Technology and product-type evaluation that distinguishes between cooling condensation-based systems and wet desiccation approaches, clarifying where performance characteristics, energy profiles, and operating cost structures diverge.
- Application-level analysis spanning industrial, commercial, and residential deployments, highlighting the distinct procurement criteria, certification requirements, and scale economics that shape each segment.
- Regional demand context that maps where atmospheric water generation is gaining traction and why, without reducing complex adoption drivers to oversimplified rankings, helping strategists prioritize market entry or partnership efforts.
- Competitive landscape profiling that examines leading participants, their geographic footprints, technological orientations, and strategic alliances, enabling benchmarking across innovation, capacity, and market presence.
- Qualitative dynamics covering regulatory incentives, off-grid sustainability trends, vehicle and infrastructure integration experiments, and product-launch cadences that indicate where the market is accelerating.
- Practical compliance and quality considerations relevant to potable use, including the role of local standards and certification pathways in shaping commercial viability for water-from-air systems.
Each section is designed to support a specific decision function. Executives can use the consolidated synthesis for portfolio and investment framing. Product managers can align development priorities with segments showing the strongest uptake signals. Sales and channel leaders can identify where regional narratives, incentive structures, and end-user pain points converge. The report intentionally withholds raw sub-segment figures in this overview to preserve analytical exclusivity; the full dataset, interactive segmentation depth, and supporting exhibits are available through the published market research.
Competitive Landscape: Benchmarking the Field and Reading Strategic Signals
The atmospheric water generation sector is characterized by a blend of specialized innovators, regionally focused manufacturers, and diversified players expanding into decentralized water production. Competitive advantage is increasingly defined not only by hardware capability but also by integration readiness, certification credibility, and the ability to tailor systems to local climate conditions and end-use requirements.
Worldwide Atmospheric Water Generator Market
Several companies have built distinct market identities. Watergen Ltd., based in Israel, has extended its atmospheric water generation footprint across residential, commercial, military, and vehicle-integration applications, relying on proprietary technology to produce potable water from ambient air. GENAQ Technologies S.L. in Spain has emphasized industrial and commercial systems derived from HVAC-derived engineering, focusing on efficient, certified solutions for off-grid and sustainable water production. In India, Akvo Atmospheric Water Systems and WaterMaker India Pvt. Ltd. have targeted water-stressed environments with cost-effective condensation-based offerings aligned to residential and commercial demand. Across the United States, multiple firms such as EcoloBlue, Drinkable Air Technologies, Atlantis Solar, Dew Point Manufacturing, Water Technologies International, SOURCE Global, Ray Agua-partners, Quench Innovations, Hendrx Water, Energy and Water Development Corp., Air 2 Water Solutions, PlanetsWater, and Fujian Wanjuan Technology have each carved out positions spanning solar-integrated units, high-capacity industrial systems, IoT-enabled monitoring, point-of-use integration, and advanced filtration for drinking water output. International participation also includes SkyWater Air Water Machines in South Africa, where variable humidity conditions create distinct operational requirements.
The concentration profile of the market indicates that established players hold meaningful share, but the landscape remains open enough for targeted entrants and product innovation to influence segment leadership. This balance matters strategically. For incumbents, it reinforces the value of execution excellence, brand trust, and ecosystem partnerships. For challengers, it highlights opportunities to win on efficiency, modularity, serviceability, or application-specific customization. The report examines these competitive positions in detail, including how participants are shaping product roadmaps, expanding capacities, and aligning with sustainability narratives. Rather than presenting static company bios, the analysis connects strategic behavior to market outcomes so readers can assess where differentiation is durable and where it is likely to erode under competitive pressure.
Industry Dynamics and Catalysts: Policy, Partnerships, and Product Momentum
Market momentum in atmospheric water generation is being reinforced by a web of operational developments, institutional projects, and policy signals. These catalysts differ by geography and application, but collectively they are expanding the relevance of water-from-air systems beyond early adopters.
Recent product and installation activity points to a broadening of use cases. In early 2026, an atmospheric water generation system was installed by the University of North Florida for research into water and infrastructure resilience, underscoring the role of institutional pilots in generating performance data and validating sustainability initiatives. Earlier, in late 2025, Beyond Water introduced atmospheric water generation technology into the U.S. market with advanced condensation and purification designed for industrial and commercial sustainable water alternatives. In the same year, Aeronero unveiled its Series 2.0 atmospheric water generators with scalable capacities reaching up to 5,000 liters per day, incorporating thermodynamic condensation, custom evaporator coils, intelligent mineralization, and IoT monitoring. Residential-oriented launches have also advanced, such as a compact kitchen-focused unit introduced in California in early 2025 and the debut of a consumer-grade atmospheric water generator at a major consumer technology event in early 2024.
Partnerships and institutional collaborations are equally important. A notable vehicle-integration initiative paired an automotive company with an atmospheric water generation specialist to explore in-vehicle fresh water production within electric vehicle portfolios. In India, partnerships have accelerated both commercial expansion and community-facing deployments, including plans for manufacturing scale-up and school-based installations that bring pure drinking water to water-stressed locations. These collaborations illustrate a broader pattern: atmospheric water generation is being embedded into existing organizational ecosystems rather than sold solely as standalone hardware.
Regulatory and policy developments are beginning to shape adoption economics as well. In early 2025, Indian authorities announced policy initiatives offering subsidies and tax incentives for atmospheric water generator installations in rural areas to promote decentralized water access. Such measures can materially influence payback periods, procurement willingness, and rollout pace in targeted geographies. At the same time, the sector continues to operate within established drinking water quality standards and certification frameworks, with active commercial models generally navigating compliance without widespread recall activity. The report consolidates these dynamics and explains how they interact with demand formation, procurement cycles, and competitive positioning.
Strategic Takeaways for 2026: Positioning for a Decade of Expansion
As organizations plan for 2026, the atmospheric water generation market presents both opportunity and complexity. The growth trajectory is strong, but capturing value will depend on how effectively companies interpret regional variation, application-level economics, and the shifting basis of competition. Several strategic themes emerge.
Atmospheric Water Generator (AWG) Market
First, differentiation is moving toward integration and reliability. Systems that can align with renewable energy sources, building operations, remote monitoring, and local water quality requirements are likely to command greater commercial relevance than units competing on output alone. Second, application selection will increasingly determine returns. Industrial and commercial deployments often prioritize continuity, capacity, and operational cost control, while residential and community-facing use cases emphasize ease of use, footprint, and perceived health or sustainability benefits. Third, partnerships and local presence will be decisive in scaling. The most effective market entry and expansion strategies are likely to combine technology credibility with distribution, service capacity, and policy awareness.
Finally, the strategic window is narrowing. With sustained growth projected and an expanding set of participants, the emphasis is shifting from proving that atmospheric water generation can work to proving where, how, and for whom it creates durable economic value. Our Worldwide Atmospheric Water Generator Market research is built to support that transition. It provides the analytical scaffolding needed to test assumptions, prioritize segments, and evaluate competitive moves with confidence.
To access the full market sizing pathways, segmentation depth, regional demand interpretations, competitive benchmarking, and scenario-driven guidance underpinning this overview, readers are invited to consult the complete published report. The detailed intelligence contained within is designed to help leadership teams convert market momentum into concrete strategic action throughout 2026 and across the remainder of the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Atmospheric Water Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Hernia Mesh Market Hits $4.8B in 2025, Projected 4.8% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Next Growth Cycle: Inside the Worldwide Inguinal Hernia Repair Mesh Market 2026–2032
The global surgical landscape is entering a decisive growth phase, driven by aging demographics, rising surgical volumes, and continuous innovation in soft-tissue reinforcement technologies. For medtech executives, procurement leaders, and strategic planners, navigating the worldwide inguinal hernia repair mesh market requires more than surface-level demand forecasts. It demands a rigorous, data-backed view of how clinical workflows, regulatory shifts, material economics, and competitive positioning will intersect over the coming years. Our newly released Worldwide Inguinal Hernia Repair Mesh Market research delivers precisely that intelligence, offering a structured, decision-ready foundation for enterprise strategy in 2026 and beyond.
Built on a comprehensive historical baseline spanning 2020–2025 and extending through a detailed forecast period from 2026 to 2032, this report translates complex market signals into actionable insight. It is engineered for leadership teams that need to align product portfolios, evaluate market entry or expansion opportunities, and anticipate structural changes before they become pricing or volume pressure points. The analysis places particular emphasis on how evolving surgical preferences, reimbursement frameworks, and material cost dynamics will shape enterprise performance across the forecast horizon.
Worldwide Hernia Mesh Devices Market
Market Trajectory and Growth Architecture
The worldwide inguinal hernia repair mesh market has demonstrated consistent expansion over the past half-decade, supported by steady surgical volume growth, broader adoption of tension-free repair techniques, and increasing procedural standardization across both mature and emerging healthcare systems. Historical revenue progression from 2020 through 2025 reflects a market that has matured yet retained clear upward momentum, with annual performance indicating resilience against macroeconomic volatility and supply chain friction. This established trajectory provides a credible foundation for forward-looking planning, allowing organizations to model realistic growth scenarios rather than relying on speculative assumptions.
The forecast window maps a sustained growth path, anchored by a projected compound annual growth rate of 4.8% across the 2026–2032 period. This growth rate is neither hyper-accelerated nor stagnant; it reflects a market that is scaling through surgical adoption, clinician preference evolution, and procedural mix shifts, while remaining sensitive to cost containment pressures and regulatory oversight. For strategists, this environment rewards disciplined portfolio positioning, differentiated clinical value propositions, and surgical-site-specific commercial execution. The consistency of the forecast curve also enables scenario modeling around volume, pricing, and mix, giving enterprise teams a reliable framework for resource allocation, capacity planning, and market prioritization.
Importantly, the market’s size and momentum do not imply uniform opportunity across all segments or geographies. The revenue dispersion across product architectures, procedural approaches, end-user settings, and regional ecosystems reveals where competitive intensity concentrates and where differentiated positioning can unlock disproportionate share gains. The report unpacks these dispersion patterns without reducing them to simplistic headline figures, enabling clients to understand the structural drivers that underpin growth variance and to calibrate investment accordingly.
Segment Architecture That Shapes Commercial Strategy
Product architecture remains one of the most decisive dimensions of competitive positioning in the inguinal hernia repair mesh category. The market comprises synthetic, biological, and composite mesh solutions, each aligned with distinct surgical philosophies, patient-risk profiles, and clinical adoption patterns. Synthetic meshes continue to anchor mainstream procedural volume, supported by established clinician familiarity, reproducible outcomes, and broad institutional procurement familiarity. Biological and composite alternatives occupy more specialized roles, often tied to specific patient cohorts, contamination risk considerations, or surgeon preference for enhanced tissue integration and reduced foreign-body response. Understanding how these product families interact with surgical indication patterns and procurement decision-making is essential for companies calibrating R&D priorities, manufacturing capacity, and marketing messages.
Surgical approach further defines the competitive field. Open surgery and laparoscopic surgery represent two major procedural pathways, each with unique mesh requirements, handling characteristics, and fixation considerations. Laparoscopic techniques have continued to gain relevance where surgical training, infrastructure, and reimbursement alignment support minimally invasive adoption. At the same time, open repair remains a durable volume base, particularly in settings where operational throughput, surgical expertise distribution, and case complexity favor established techniques. The balance between these approaches is not static, and the report examines the dynamics that will influence procedural mix evolution, including surgeon training pipelines, OR efficiency priorities, and the growing emphasis on standardization in inguinal hernia repair.
End-user configuration adds another layer of strategic nuance. Hospitals, ambulatory surgical centers, and specialty clinics each operate with different purchasing rhythms, cost sensitivity profiles, and surgical volume thresholds. Hospital systems typically concentrate high-acuity and high-volume procedures, often influencing standardization decisions across multiple service lines. Ambulatory surgical centers increasingly shape procedural throughput for selected hernia repair pathways, where efficiency, instrument turnover, and predictable case scheduling matter. Specialty clinics represent a more focused segment, often tied to concentrated surgical expertise or regional referral patterns. The report evaluates how these end-user environments influence product selection, tendering behavior, and value communication, giving commercial teams a clearer picture of where and how demand is formed.
Geographic distribution of demand introduces further strategic complexity. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each exhibit different healthcare infrastructure maturity, surgical training ecosystems, reimbursement environments, and import or distribution dynamics. Rather than treating these regions as interchangeable growth pools, the analysis distinguishes the operational realities that determine how mesh products are adopted, priced, and sustained in local markets. This regional granularity supports more precise opportunity sizing, market entry sequencing, and partnership evaluation for organizations expanding beyond their core territories.
Competitive Landscape and Strategic Positioning
The competitive environment in this market is defined by established multinational players with deep surgical portfolios, strong regulatory footprints, and long-standing relationships with clinical communities. Market concentration reflects a structure in which a relatively small group of leading participants commands a significant share of revenue, reinforcing the importance of differentiation, lifecycle management, and surgical-value storytelling. For entrants and incumbent challengers alike, successful positioning depends on how well a company can align product performance, surgical workflow compatibility, and commercial execution with the priorities of procurement committees and operating-room decision-makers.
Becton Dickinson continues to leverage its Bard mesh heritage alongside next-generation bioresorbable options such as Phasix Mesh, which is built on P4HB technology and positioned as an alternative for soft-tissue reinforcement. The company’s recent activity underscores both product expansion and clinical indication development, including CE-mark-related prophylactic use expansion and broader European availability. These moves highlight a strategy oriented toward extending the clinical relevance of mesh technologies beyond standard repair into prevention-oriented and high-risk surgical contexts. For competitors, such indication expansion can reshape reference points in surgical conversations and influence procurement considerations around long-term tissue outcomes and procedural versatility.
Medtronic, through its Covidien heritage, maintains a strong alignment with laparoscopic inguinal hernia repair, offering anatomical and self-fixating mesh solutions designed for TAPP and TEP approaches. Its portfolio emphasizes reinforcement of abdominal wall soft tissue with designs intended to support minimally invasive surgical workflows. In a market where procedural approach mix and surgeon training habits influence adoption curves, this laparoscopic orientation gives Medtronic a distinct positioning lever. The company’s product narratives often resonate in environments where OR efficiency, standardized mesh handling, and laparoscopic technique maturity are priorities for surgical programs.
Ethicon, as part of Johnson & Johnson MedTech, brings a widely recognized presence in hernia repair through established nonabsorbable mesh platforms and partially absorbable macroporous options for inguinal procedures. Its commercial strength is reinforced by broad surgical brand recognition and integration within larger medtech ecosystems. For strategists, Ethicon’s portfolio breadth and institutional footprint illustrate how product reliability, clinician familiarity, and cross-product surgical support can sustain competitive relevance even as technologies and surgical preferences evolve.
B. Braun Melsungen AG, operating through its Aesculap platform, offers mesh ranges designed for inguinal hernia repair and connective tissue reinforcement, with product attributes that emphasize handling characteristics and indication-specific use. This positioning supports surgical programs seeking predictable performance across defined repair scenarios. Similarly, W. L. Gore & Associates contributes biomaterials and dual-surface mesh solutions suited to reconstruction contexts, including applications that aim to manage adhesion risk while supporting inguinal and soft-tissue repair objectives. Getinge, through its Atrium Medical heritage, maintains a historical presence in synthetic hernia mesh products used in inguinal and abdominal wall repair, reflecting the broader reality that product lineage, manufacturing scale, and market reputation continue to matter in procurement decisions.
Together, these players illustrate a market where product engineering, surgical-method alignment, and commercial execution intersect. The report maps how these competitive profiles relate to demand formation and market share distribution, giving clients a practical lens for anticipating competitive responses, identifying whitespace, and shaping differentiation strategies that are not dependent solely on price competition.
Regulatory, Reimbursement, and Supply Chain Dynamics
Market performance in hernia mesh is increasingly shaped by forces that extend beyond surgical volume alone. Regulatory communication standards, reimbursement coding updates, and raw-material cost structures all influence how products are positioned, procured, and sustained across healthcare systems. In mid-2025, the U.S. FDA issued draft guidance recommending standardized package labeling for hernia mesh devices intended for hernia repair, including inguinal procedures. This guidance is designed to improve the consistency of clinically relevant information available to providers and to support safer and more effective use. For manufacturers, labeling clarity and documentation rigor are becoming more than compliance tasks; they are elements of commercial trust that can affect surgeon confidence, procurement review, and downstream adoption.
Reimbursement environments also exert direct influence on procedural economics. Updated Medicare coding and reimbursement guidance for hernia repair procedures, including inguinal repair with mesh, reflects revised CPT/HCPCS structures and national average payment rates effective at the start of 2026. These updates matter because reimbursement clarity can affect case economics, surgical program planning, and the willingness of institutions to standardize particular mesh solutions. Strategists should view reimbursement changes not as isolated administrative updates, but as factors that can either reinforce or disrupt adoption trajectories depending on how they interact with procedure mix, site of care, and product selection.
On the cost side, the materials environment has introduced meaningful pressure into manufacturing and sourcing strategies. Medical-grade polypropylene, the primary material base for most synthetic inguinal hernia repair meshes, has experienced price increases exceeding 35% since 2021, reaching approximately $1,700 per metric tonne in 2024. This trajectory affects cost structures, margin planning, and procurement negotiations, particularly for companies with high exposure to synthetic mesh production. In response, organizations are increasingly focused on supply resilience, formulation efficiency, and value communication that justifies pricing within institutional budget constraints. The report integrates these dynamics into the broader market narrative, helping clients assess how material economics and regulatory/reimbursement shifts combine to influence competitive behavior and demand patterns.
What the Report Delivers for Decision-Makers
This research is designed to serve as a working strategic resource rather than a static market summary. It provides a structured base-year viewpoint anchored in 2025, supported by historical performance data from 2020 through 2025, and extended by a forward forecast through 2032. By bridging historical validation with near- and mid-term projection, the report enables teams to test assumptions, benchmark expectations, and align planning cycles with a coherent market timeline. The analytical framework is built to support product strategy, market prioritization, competitive assessment, and commercial execution planning within a single coherent reference point.
Beyond top-line growth figures, the report examines the structural dimensions that determine how market value is created and captured. That includes the interplay of product type, surgical approach, end-user environment, and regional demand conditions, presented in a way that supports segmentation strategy without reducing the market to generic category statements. Clients gain insight into where demand concentration is strongest, how procedural and purchasing behavior varies across settings, and which structural factors are most likely to influence growth dispersion over the forecast period.
The competitive analysis component translates company activity into strategic implication. Rather than cataloguing product names for their own sake, the report evaluates how leading participants are shaping the market through portfolio emphasis, surgical-method alignment, indication expansion, and regulatory or reimbursement responsiveness. It also incorporates recent market-moving developments, including BD’s prophylactic indication milestone and product expansion activity, as well as the broader FDA labeling guidance and updated reimbursement coding context. These elements help clients understand not only who leads today, but how the competitive field is being reshaped in real time.
For enterprises operating in or entering this space, the report supports several practical use cases. It can inform product roadmap decisions by clarifying where clinical and commercial demand signals are most consistent. It can guide market-entry sequencing by distinguishing regions and end-user settings with different adoption dynamics. It can assist pricing and value-proposition development by connecting material cost pressures, reimbursement context, and surgical value narratives. It can also strengthen investor, management, and partnership communications by grounding strategic claims in a clear market trajectory and competitive structure.
Why This Research Matters for 2026 Strategy
The 2026 decision environment will reward organizations that can integrate clinical, regulatory, reimbursement, and cost realities into a single strategic view. The worldwide inguinal hernia repair mesh market is large enough to support meaningful growth, yet structured in ways that make undifferentiated approaches vulnerable to competitive compression. Companies that understand the forces shaping procedural mix, product preferences, and purchasing behavior will be better positioned to allocate resources, defend share, and pursue expansion with greater precision.
This report is intended to provide that strategic clarity. It offers a validated market baseline, a forward-looking growth framework, and a detailed look at the structural dynamics that matter most to enterprise decision-makers. By aligning historical evidence with forecast logic and competitive context, it helps organizations move from general market awareness to informed strategic action.
For a complete view of the segmentation architecture, regional demand interpretation, competitive mapping, and forward forecast detail, the full Worldwide Inguinal Hernia Repair Mesh Market research is available through the PW Consulting source page. The complete study provides the operational depth required to translate these high-level insights into targeted commercial and strategic decisions for 2026 and the years ahead.
Worldwide Inguinal Hernia Repair Mesh Market
For detailed analysis of this topic, please visit the official page: Worldwide Inguinal Hernia Repair Mesh Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Device Charging Kiosk Revenue Hits $570M in 2025, Poised for 11.02% CAGR Through 2032
By pmarketresearch, 2026-09-16
Powering the Connected World: Strategic Intelligence for the Portable Device Charging Kiosks Market 2026–2032
In an era where mobile connectivity is non-negotiable, the infrastructure supporting it has quietly become a critical battleground for retail operators, venue managers, transportation authorities, and public facility planners. The Worldwide Portable Device Charging Kiosks Market has evolved from a niche convenience amenity into a measurable revenue channel and a strategic touchpoint for customer experience, dwell time optimization, and smart-space monetization. Our latest research release is designed for decision-makers who need to separate signal from noise in a rapidly consolidating landscape. This introduction previews the analytical depth, operational frameworks, and competitive intelligence contained in the full report, while anchoring the discussion in the macro trajectory that will define investment and deployment decisions through 2032.
For strategy teams, the central question is no longer whether charging infrastructure matters, but how to position for the next phase of commercialization. The market’s recent trajectory illustrates a structural shift rather than a cyclical fluctuation. Historical performance from 2020 through 2025 shows a market that expanded from 348.12 million USD to 570.0 million USD, reflecting sustained adoption across commercial and public environments. The forecast horizon extends that momentum into a compound annual growth rate of 11.02 percent, with projected revenue reaching 1,184.9 million USD by 2032. These are not abstract growth figures; they are indicators of expanding use cases, maturing business models, and increasing integration of charging kiosks into broader experiential and operational strategies.
Worldwide Portable Device Charging Kiosks Market
What makes this period especially consequential is the transition from ad hoc deployments to deliberate infrastructure planning. Early adoption was often driven by one-off events, pop-up activations, or incremental customer service additions. The next wave is defined by persistent placement logic, recurring revenue models, and operational standardization. That evolution changes the decision calculus for procurement, real estate allocation, branding, and service-level commitments. It also raises the stakes for vendors and buyers alike, because deployment decisions increasingly interact with labor planning, maintenance economics, and regulatory environments that differ by jurisdiction.
Why 2026 Is a Strategic Inflection Point
The 2026–2032 forecast period matters because it captures the market after the initial wave of trial-and-error has been filtered through commercial discipline. By this stage, successful operators and venue owners are no longer asking whether a charging kiosk can attract attention. They are evaluating total cost of ownership, utilization-driven ROI, branding leverage, and the operational burden that accompanies hardware placed in high-traffic environments. That shift elevates the importance of data-backed segmentation analysis, because the value of a kiosk is not uniform across locations, form factors, or customer journeys.
In the pages that follow, the full report translates this inflection point into a working framework. It maps the divergence between floor-standing, wall-mounted, and tabletop configurations as they align with space constraints, throughput expectations, and branding objectives. It also examines how application contexts shape deployment priorities, comparing the commercial dynamics of retail and shopping centers, airports and transportation hubs, hospitality and restaurants, healthcare facilities, and other specialized environments. Each segment carries its own demand drivers, operational constraints, and monetization pathways, and the analysis is built to help leaders match the right solution to the right environment rather than defaulting to a one-size-fits-all procurement decision.
From Amenities to Managed Infrastructure
One of the most operationally important themes in the market is the growing complexity beneath the surface of what appears to be a simple customer service addition. Charging kiosks may look straightforward from a distance, but real-world performance depends on access control, payment logic, device compatibility, hygiene considerations, branding integration, and ongoing maintenance. The industry context increasingly reflects that complexity. For example, average annual maintenance costs for charging stations, including labor elements, are estimated to reach up to 400 USD per charger. That figure is not just an operational footnote; it is a signal that hardware selection and service design must be evaluated alongside utilization forecasts and contract structures.
At the same time, the regulatory backdrop is evolving in ways that can affect pricing models, operational classification, and tax treatment. In the United States, multiple states have moved toward frameworks that allow kWh-based pricing for public charging contexts by excluding operators from certain public utility definitions. In parallel, certain states impose kWh-based charges on charging station operators, with rules that vary by capacity thresholds and location. While much of this regulatory discussion is associated with electric vehicle infrastructure, it carries broader relevance for device charging ecosystems because it shapes how operators think about energy pricing, compliance, and jurisdictional risk. Combined with the realities of hardware installationcosts and power-related infrastructure requirements, these factors underscore why a strategic assessment must go beyond sticker price and consider lifecycle economics.
Reading the Competitive Landscape
The vendor ecosystem in this market is diverse, and competition is shaping up along more than one axis. Some players compete on volume deployment and network reach; others differentiate through hardware durability, customization, security, solar-powered options, or software-enabled remote management. The full report profiles a wide set of leading participants, including goCharge Networks, InCharged, Veloxity, ChargeBar, Chargetech, ChargerGoGo, chargeFUZE, Winnsen Industry Co., Ltd., HonestWaves, and The Power Stop, among others. Rather than treating these companies as a static list, the analysis examines how their operating models, product portfolios, and recent moves reflect broader market forces.
That competitive reading is especially relevant given the level of fragmentation still visible in the market. Concentration remains moderate, with the top three firms accounting for approximately 32.4 percent of the market and the top five firms accounting for roughly 48.7 percent. This structure implies both opportunity and risk. On one hand, there is still room for capable entrants and regional expansion strategies. On the other hand, the mid-to-large players are increasingly defining expectations around reliability, branding, remote oversight, and service support, which raises the bar for any organization seeking to compete on more than price alone.
Recent activity highlights the kinds of moves that matter. In March 2025, ChargeBar published analysis on phone battery longevity, reinforcing the role that operator education and user support play in sustaining kiosk engagement. In September 2025, HeyCharge emphasized turnkey mobile charging vending machines and power bank rental stations designed for businesses and high-traffic areas, pointing toward a more integrated product narrative. Most recently, in March 2026, ChargerGoGo announced the official launch of its Northeast Ohio presence with new charging kiosk deployments, illustrating how regional expansion continues to be a viable growth lever even as the market matures. These examples are not isolated announcements; they are indicators of how product framing, service visibility, and geographic rollout are being used to strengthen position in a competitive field.
What the Full Report Delivers
This research is built for practitioners who need to move from broad market awareness to specific action. The complete study goes beyond headline revenue figures to provide a structured basis for procurement strategy, channel selection, venue planning, and competitive positioning. It is organized to support both top-down portfolio planning and granular operational evaluation.
- A full historical and forecast view that connects the 2020–2025 baseline to the 2026–2032 outlook, enabling teams to test growth assumptions against observed trends and forward projections.
- Segment-level interpretation across region, type, and application, with analysis focused on deployment suitability, demand drivers, and commercial logic rather than isolated statistics.
- Competitive profiling of key companies, including their operating models, product emphasis, geographic footprints, and recent developments that may affect procurement or partnership decisions.
- Operational and regulatory context that brings maintenance burden, installation complexity, energy pricing structures, and state-level frameworks into the decision process.
- Strategic implications for revenue models, branding integration, remote management, and service design, with an emphasis on how these elements interact in real deployment environments.
The report is especially useful for organizations evaluating whether to buy, lease, partner, or expand an existing charging program. It helps clarify where customization matters, where standardization reduces risk, and where the value of a kiosk depends more on placement strategy than on hardware features alone. For vendors and investors, it provides a basis for understanding where consolidation pressure is strongest, where regional growth is most plausible, and where product differentiation must be supported by operational credibility.
Where the Market Is Heading
The path to 2032 is unlikely to be defined by a single breakthrough product. Instead, it will be shaped by the cumulative effect of better placement logic, more disciplined operating economics, and more sophisticated integration of charging kiosks into broader venue and business strategies. As utilization becomes a more important measure of success, the winners in this market will be those who can align form factor, service model, and commercial framing with the realities of the environment they serve. That means thinking about throughput in a shopping center differently from throughput in an airport lounge, and thinking about lock-and-walk convenience differently from passive plug-and-charge models.
It also means acknowledging that the market’s next phase will reward organizations that can manage complexity without overcomplicating the customer experience. Security, hygiene, payment flexibility, remote monitoring, branding, and battery management are all part of the same operational stack. Companies that treat these as afterthoughts may win short-term placement deals but will face pressure as expectations rise. Companies that design for them from the outset will be better positioned to defend margins, sustain utilization, and support repeat deployments across sites.
For enterprise decision-makers, the practical implication is clear: the market is large enough and dynamic enough to merit dedicated strategic attention, but it is also nuanced enough that generic assumptions can lead to costly misalignment. A disciplined review of segment fit, total operating cost, competitive alternatives, and regional dynamics is the difference between adding another amenity and building a durable infrastructure asset.
What Comes Next
The Worldwide Portable Device Charging Kiosks Market is entering a phase in which growth and operational rigor must advance together. The 11.02 percent forecast CAGR and the rise toward 1,184.9 million USD by 2032 describe a market with real momentum, but momentum alone does not create advantage. Advantage comes from understanding where value is created in each segment, how competitors are positioning themselves, and which operational and regulatory factors will shape long-term viability.
Portable Power Bank Market
The complete report expands every layer introduced here. It develops the segment interpretation in detail, unpacks the company profiles with current product and expansion context, and situates the market within the broader operational and regulatory environment that procurement and operations teams must navigate. For leaders planning 2026 decisions and preparing for the 2026–2032 horizon, the full study is intended to serve as a working reference rather than a high-level summary.
The market is changing fast enough that the most valuable intelligence is not just what is happening, but why it matters and what to do about it. The full report is built for that purpose.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Device Charging Kiosks Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Industrial Epoxy Glass Market to Reach $4.2B by 2032 Growing at 5.82% CAGR
By pmarketresearch, 2026-09-16
Global Industrial Epoxy Glass Market Outlook 2026: Strategic Intelligence for Boards and Composite Leaders
The industrial epoxy glass sector stands at a pivotal juncture as organizations navigate post-pandemic supply normalization, intensifying electrification mandates, and the recalibration of global manufacturing footprints. Our latest Worldwide Industrial Epoxy Glass Market research delivers a forward-looking intelligence framework designed specifically for executive teams, procurement directors, and R&D strategists who must align capital allocation with durable material demand. Spanning historical performance from 2020 through 2025 and a rigorous forecast window from 2026 to 2032, this study translates macro trajectories into actionable decision architecture. The base year of 2025 anchors our analytical baseline at USD 2,842.6 million, while the projected jump to USD 3,008.61 million in 2026 confirms that underlying demand drivers remain structurally intact even as pricing volatility and capacity reallocation test margin resilience.
Readers approaching this report for 2026 boardroom planning will find more than retrospective summaries. The study is engineered to answer the strategic questions that keep industry leaders awake: which grade families will continue to absorb the largest value pools, how regional manufacturing shifts are reshaping competitive positioning, and where the next phase of capacity investment will generate the highest risk-adjusted returns. The narrative consistently bridges top-down market architecture with bottom-up operational realities, ensuring that strategic forecasts remain tethered to engineering specifications, certification requirements, and raw material economics rather than abstract growth curves.
Why 2026 Decision-Makers Need a Structured Epoxy Glass Intelligence Map
Industrial epoxy glass is no longer a commoditized insulation substrate. It is a performance-critical material embedded in high-reliability printed circuit boards, aerospace structural laminates, automotive electronic assemblies, and heavy industrial machinery. That embeddedness means demand is increasingly tied to downstream technology roadmaps rather than standalone material cycles. Our research framework treats the market as a system of interdependent choices: grade selection influences downstream validation timelines; regional sourcing decisions affect lead-time reliability and regulatory exposure; and raw material price movements can compress or expand the viability of specific processing routes. By mapping these interdependencies, the report gives leaders a shared reference point for cross-functional alignment between engineering, procurement, and commercial strategy.
The 2026-2032 forecast period is particularly consequential because it captures the maturation of several long-cycle programs in aerospace and defense alongside the scaling of automotive electronics content. Historical momentum from 2020-2025 demonstrates a market that has already absorbed multiple demand shocks and emerged with a stronger consolidated base. That resilience is not accidental; it reflects the sector's ability to sustain deployment even when upstream chemical pricing fluctuates and when regional manufacturing networks are rewired. For executives evaluating 2026 investment theses, the study offers a disciplined way to separate temporary price pacing from structural volume growth, allowing teams to plan around durable consumption patterns rather than headline noise.
Industrial Epoxy Glass Market Trajectory: Scaling Demand and Forecast Architecture
Market sizing in this study is constructed from a multi-layered triangulation of historical shipments, production disclosures, capacity signals, and downstream content forecasts. The resulting trajectory shows a market expanding from USD 2,145.3 million in 2020 to USD 2,842.6 million in 2025, with the forecast pathway extending toward USD 4,218.88 million by 2032. The compound annual growth rate across the 2026-2032 horizon is assessed at 5.82%, a pace that signals steady expansion rather than cyclical spikes. For strategy teams, this matters because it implies that competitive advantage will come less from timing a sudden surge and more from positioning reliably within a long-duration growth envelope.
Revenue units are expressed in millions of USD to maintain consistency across historical and forecast years, and the base year of 2025 acts as the calibration point for forward modeling. This structure allows the report to isolate how much of the 2026 opening position to USD 3,008.61 million is inherited from 2025 demand carry-over versus newly accelerated program activations. Decision-makers can use this framing to test internal forecasts against an externally validated baseline, pressure-testing whether their own order books, capacity plans, and pricing strategies are aligned with the sector's observed trajectory. The forecast does not rely on simplistic linear extrapolation; instead, it integrates grade-level substitution dynamics and application-level content changes so that leadership can see where volume growth is likely to concentrate and where pricing discipline will become the dominant value lever.
Segmentation Architecture: Grades, Applications, and Demand Drivers
The study's segmentation design is built to help executives move beyond broad category language and into the operational specifics that actually drive procurement and product strategy. Epoxy glass demand is structured around grade families that differ in dielectric performance, mechanical stability, flame-retardant behavior, and machining compatibility. The report examines how these grade distinctions influence end-market fit, particularly where electrical and electronics platforms require standardized high-volume laminates and where aerospace or industrial applications call for more specialized tolerance and certification profiles. By presenting each grade family within its functional context, the analysis clarifies why certain substrate classes maintain persistent demand even when overall market growth appears moderate.
LED Glass Market
Application segmentation is treated with equal rigor. Electrical and electronics use cases anchor a large share of consumption because epoxy glass laminates remain integral to board construction, insulation, and structural support in high-reliability assemblies. Aerospace and defense applications create a different demand signature: lower volume, higher specification, and stronger sensitivity to certification, traceability, and material consistency. Automotive electronics contribute a rapidly evolving demand layer tied to vehicle electrification, sensor proliferation, and power management content. Industrial machinery applications reinforce the market's base through durable requirements for insulating structural components and composite-format laminates that support heavy-duty operating environments. Rather than presenting these segments as isolated slices, the report maps the overlap between them so strategists can identify where multi-application grade families generate the most stable revenue streams and where application-specific specialization commands premium positioning.
Regional analysis is equally central to the strategic narrative. The report evaluates how manufacturing density, logistics architecture, and engineering support networks shape regional demand patterns without reducing the discussion to a static split of market share. Asia Pacific's scale advantages, North America's high-reliability supply requirements, Europe's specification-driven industrial base, and the broader international footprint each create distinct purchasing behaviors and risk profiles. Executives using this research can better anticipate where supplier diversification, local content expectations, or certification alignment will become decisive factors in sourcing strategy. The report intentionally avoids reducing these dynamics to simple percentage rankings; instead, it explains why regional positioning matters operationally and how it interacts with grade availability, lead times, and technical service expectations.
Competitive Landscape: Strategy, Scale, and Regional Positioning
The industrial epoxy glass market is shaped by a mix of global specialty material leaders, North American laminate manufacturers with deep machining and fabrication capabilities, and large-scale Asian producers expanding throughput to capture both domestic and export demand. Our competitive analysis focuses on how these players differentiate across product breadth, application engineering, capacity strategy, and certification readiness.
Ventec International Group operates from a strong global position in high-performance copper clad laminates and prepregs, including epoxy glass-based materials for PCB and industrial insulation applications. Its relevance in this market stems from the way high-reliability electronic material expertise overlaps with industrial insulation requirements, giving it a credible platform in segments where electrical performance and mechanical stability must be balanced. Isola Group follows a similar strategic logic, specializing in copper-clad laminates and prepreg materials, including epoxy glass systems for high-reliability PCB and industrial electronic applications. For buyers and competitors alike, these companies illustrate how electronic-grade laminate expertise can translate into industrial epoxy glass demand when specifications and validation paths align.
Worldwide Industrial Epoxy Glass Market
In North America, a second competitive tier emphasizes sheet, rod, tube, and fabricated-part capabilities. Atlas Fibre stands out as a North American manufacturer and supplier of thermoset composite laminates including extensive G-10, FR-4, and G-11 epoxy glass sheets, rods, and tubes with in-house machining. Franklin Fibre-Lamitex Corp. reinforces this profile by manufacturing high-quality Lamitex G-10, FR-4, G-11, and FR-5 glass-reinforced epoxy laminates in sheet and tube forms meeting MIL and NEMA specifications. Current Inc. adds further depth as a US manufacturer of G-10/FR-4 glass epoxy laminates in sheets, tubes, rods, and fabricated parts for electrical and structural industrial uses. Iten Industries complements this landscape as a producer of NEMA-grade G-10 and G-10/FR4 epoxy glass laminates with over 100 years of experience in advanced composite materials. This cohort demonstrates that competitive advantage in certain market pockets comes from specification familiarity, machining readiness, and the ability to convert standard laminates into application-ready forms.
On the other side of the competitive equation, large-scale Chinese production capacity has become a defining feature of global supply dynamics. SIDA operates as a large-scale Chinese producer of FR-4, G-10, G-11, and 3240 epoxy glass laminates in sheets, tubes, and rods with capacity over 45,000 tons annually. Its scale signals the growing importance of volume throughput, standardized grade availability, and cost-competitive supply in global procurement planning. Hony Engineering Plastics Limited further illustrates this trajectory as a manufacturer of FR4, G10, G11 epoxy glass fiber laminate sheets and EPGC series materials for electrical insulation. Alongside these, Hexcel Corporation develops and supplies epoxy-based composite materials, including glass-reinforced systems for aerospace and industrial structural applications, while Park Aerospace Corp. manufactures advanced composite materials including epoxy glass laminates and prepregs for high-performance industrial and aerospace uses. Together, these players show that the market's competitive map is not simply about who produces the most volume, but about who can reliably serve the most demanding specification environments while maintaining cost and delivery credibility.
Strategic Dynamics: Raw Material Economics, Certifications, and Market Concentration
No epoxy glass strategy can be built without confronting upstream economics. Epoxy resin serves as the primary upstream chemical feedstock for epoxy glass laminates, with prices directly influencing production costs of G-10/FR-4 materials. Recent pricing signals reinforce the need for structured cost monitoring. Northeast Asia epoxy resin prices reached USD 2.62/KG in April 2026, while China epoxy resin prices were reported at USD 2031/MT in February 2026. These movements matter because they alter the cost backdrop for manufacturers and buyers simultaneously, affecting margin planning, inventory timing, and make-versus-buy judgments. The report integrates these price dynamics into a broader cost-structure discussion so that leaders can evaluate exposure not just at the laminate level, but across the resin-to-glass value chain.
Regulatory and certification expectations remain equally important. Epoxy glass laminates such as FR-4 from major suppliers maintain UL 94 V-0 flame retardancy and RoHS/REACH compliance as standard certifications. For procurement and engineering teams, this is not a footnote; it is a baseline requirement that determines supplier eligibility, validation speed, and downstream acceptance. The report emphasizes how certification readiness shapes competitive positioning, particularly in segments where qualification cycles are long and where switching costs are high. In such environments, suppliers that can demonstrate consistent compliance and documentation control gain durable access to demand even when price competition intensifies.
Market concentration data provides another strategic lens. The CR3 level sits at 32.4%, while CR5 reaches 48.7%. This structure indicates a market with meaningful scale players and established specialists, but not one dominated by a single overwhelming incumbency. For 2026 strategists, that matters because it suggests room for differentiation through service, grade specialization, regional capability, and fabrication value-add, rather than relying solely on volume dominance. The report uses these concentration signals to frame questions about partnership strategy, supplier diversification, and the potential for consolidation or capacity expansion to reshape competitive access over the forecast period.
Recent Developments and Forward Indicators
Momentum from late 2025 and early 2026 underscores that product innovation and capacity signaling remain active across the value chain. In April 2026, SHD Composites launched MTC521FR flame-retardant clear epoxy prepreg for visually critical applications, extending capabilities in epoxy-based composites. This kind of development matters because it shows how epoxy glass-adjacent material systems continue to expand into applications where appearance, flame performance, and processing precision must be balanced. It also signals that competitive differentiation is increasingly tied to specialty prepreg and laminate variants rather than only standard commodity grades.
At the end of 2025, Hony Engineering Plastics updated offerings and specifications for EPGC series epoxy glass fabric laminate sheets spanning EPGC201 to EPGC308, meeting IEC and GB standards. This move reinforces the importance of standards alignment in electrical insulation markets and suggests that suppliers are actively broadening specification coverage to support broader customer qualification pathways. At the same time, SIDA signaled ongoing expansion projects supporting annual manufacturing capacity exceeding 45,000 tons of epoxy glass laminates including FR-4, G-10, and G-11 grades. Capacity signaling of this type is a critical forward indicator because it shapes future supply availability, competitive pricing tension, and regional sourcing flexibility. The report weaves these developments into a forward-looking discussion so that leaders can interpret them not as isolated news items, but as evidence of how product structure and supply scale are evolving in parallel.
Inside the Report: What Decision-Makers Will Find
This study is built for direct operational use. Beyond the macro trajectory and segmentation structure, the report provides a practical toolkit for teams responsible for sourcing strategy, capacity planning, product roadmap alignment, and competitive monitoring. The content is organized to support both high-level strategic review and detailed cross-functional discussion, with clear linkages between market structure, grade economics, application demand, and supplier behavior. Readers will find a framework that helps answer questions such as where demand durability is strongest, how certification and specification requirements influence supplier access, and which structural factors are likely to determine margin outcomes over the 2026-2032 period.
The analysis also treats raw material exposure, regional supply dynamics, and capacity signals as living variables rather than static assumptions. By integrating recent pricing movements, product launches, specification updates, and capacity expansion narratives into one strategic view, the report enables decision-makers to test internal assumptions against market-consistent evidence. For boards and senior management teams, this means the research can support investment prioritization, risk mapping, and sourcing architecture discussions without requiring teams to reconstruct the underlying logic from fragmented sources.
How to Use This Research for 2026 Planning
The strongest value of this study lies in its ability to turn complex material-market dynamics into a disciplined decision frame. Executives can use the report to validate demand expectations, expose hidden sensitivities in cost and certification pathways, and identify where supplier positioning is likely to shift as capacity and product specialization evolve. Procurement teams can build sourcing strategies around a clearer understanding of grade families, application fit, and regional capability. Engineering and product leaders can better anticipate where material selection will influence downstream validation timelines and how epoxy glass systems fit within broader composite and electronics roadmaps.
Because the full report contains the detailed segment architecture, comparative supplier assessment, and forward-looking scenario framework required for implementation, this preview is designed to establish the strategic direction and analytical rigor behind the work. The complete intelligence set enables teams to move from directional confidence to specific, defensible action plans.
Key Takeaways for Strategic Action
- The market is expanding from a 2025 base of USD 2,842.6 million toward a 2026 opening of USD 3,008.61 million and a 2032 trajectory of USD 4,218.88 million, with a 5.82% CAGR across the forecast window.
- Grade families such as FR-4, G-10, G-11, and other specialty grades anchor distinct demand profiles across electrical, aerospace, automotive, and industrial applications, making grade-level strategy essential rather than optional.
- Competitive advantage increasingly depends on specification readiness, certification consistency, machining and fabrication capability, and capacity scale rather than volume alone.
- Upstream epoxy resin pricing directly shapes production economics, so cost planning must integrate resin-to-laminate exposure instead of treating laminate pricing in isolation.
- Market concentration is moderate, leaving meaningful room for differentiation through service, specialization, regional reach, and application engineering.
- Recent product launches, specification updates, and capacity expansion signals indicate that product structure and supply scale are evolving together, requiring continuous monitoring rather than one-time assessment.
Get the Full Market Intelligence
This preview outlines the strategic structure and analytical discipline behind our Worldwide Industrial Epoxy Glass Market research, but the complete report contains the detailed segment maps, supplier positioning frameworks, regional dynamics, and forward scenarios needed to act with confidence in 2026. If your team is preparing sourcing decisions, capacity evaluations, specification roadmaps, or competitive response plans, the full study provides the granular intelligence required to convert market direction into executable strategy. Access the complete report to unlock the full dataset, segmentation detail, and implementation-ready analysis built for enterprise decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Epoxy Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Gelling Agent Market Hits $9.13B in 2025, Poised for 6.42% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Imperatives in the Global Natural Gelling Agent Market: Navigating Growth Through 2032
Executive Introduction: Why This Market Matters in 2026
The global natural gelling agent market stands at a critical inflection point. As formulation scientists, procurement leaders, and corporate strategists alike navigate an increasingly complex landscape defined by clean-label mandates, supply chain volatility, and shifting regulatory frameworks, the ability to anticipate structural shifts across hydrocolloid markets has transitioned from a tactical advantage to an operational necessity. Our latest Worldwide Natural Gelling Agent Market research delivers precisely that foresight, grounding strategic decision-making in rigorous historical analysis and forward-looking projections spanning 2026 to 2032.
Built upon a comprehensive six-year historical dataset covering 2020 through 2025, this analysis traces a clear trajectory of sustained commercial expansion. The market has consistently demonstrated resilience and incremental growth, with total revenue climbing from approximately 6.71 billion USD in 2020 to 8.09 billion USD by 2023, accelerating further to 8.59 billion USD in 2024. The most recent historical baseline places the market at roughly 9.13 billion USD in 2025, setting a robust platform for the forecast horizon. Looking ahead, the research outlines a steady, compounding growth pathway, with total market value projected to surpass 9.7 billion USD in 2026 and continue its upward march through the decade, ultimately reaching a valuation approaching 14.1 billion USD by 2032. This evolution is underpinned by a compound annual growth rate of 6.42 percent, a figure that encapsulates both underlying demand momentum and the structural maturation of global supply networks.
For enterprise decision-makers, these numbers are not merely retrospective scorecards. They represent the foundational architecture upon which procurement strategies, capital allocation decisions, product development roadmaps, and competitive positioning must be built. In an environment where ingredient availability, geographic sourcing dynamics, and raw material pricing can shift within quarters, relying on static or fragmented market intelligence introduces measurable strategic risk. This research was designed specifically to eliminate that blind spot.
The Architecture of the Analysis: What the Research Delivers
A market of this scale and complexity cannot be understood through aggregate revenue figures alone. Effective strategy requires granular visibility into how demand is distributed across end-use sectors, how formulation preferences are evolving by product type, and where geographic concentrations of production and consumption create both opportunities and vulnerabilities. The Worldwide Natural Gelling Agent Market report is structured to translate raw market data into actionable strategic intelligence across multiple dimensions.
Segment-Level Demand Mapping
The analysis dissects market composition across three primary structural lenses. The first examines product-type dynamics, revealing how traditional staples and emerging specialty hydrocolloids compete for formulation share across diverse industrial and consumer applications. The second dimension evaluates end-use application segmentation, tracing how food and beverage formulations, pharmaceutical-grade excipients, cosmetics and personal care formulations, and broader industrial uses each drive distinct volume and value requirements. The third dimension provides a regional breakdown, identifying which geographic markets are absorbing the largest shares of production, where localized supply ecosystems are maturing, and how cross-border trade flows are shaping competitive accessibility. Rather than presenting isolated percentage allocations or standalone revenue pockets, the report contextualizes each segment within broader formulation trends, regulatory developments, and supply chain realities, enabling leaders to assess where incremental growth is structurally supported versus where it depends on short-term cyclical factors.
Worldwide Natural Gelling Agent Market
Competitive Positional Intelligence
Beyond segmentation, the research delivers a rigorous competitive landscape assessment. Spanning a broad roster of established multinational ingredient suppliers and specialized hydrocolloid manufacturers, the company profiles map out strategic capabilities, product portfolio strengths, geographic manufacturing footprints, and recent corporate developments that signal shifting market leverage. The analysis explicitly tracks high-impact corporate actions, including the landmark acquisition that consolidated major pectin and specialty gum assets under a single global food ingredients platform, alongside targeted capacity expansions in key production regions aimed at securing supply for high-demand natural gelling inputs. These moves are not treated as isolated news items; instead, they are evaluated for their downstream implications on pricing power, supply reliability, and formulation access across customer sectors.
Operational and Supply-Side Dynamics
Market value is ultimately governed by physical realities: raw material availability, agricultural and marine harvest cycles, processing capacity, and logistical friction. The report integrates current supply-side intelligence that directly affects formulation economics. Recent quarters have illustrated how tightly coupled the natural gelling supply chain is to external environmental and sourcing variables. Fluctuations in red seaweed availability have placed upward pressure on specific hydrocolloid input pricing, while brown seaweed supply variability has similarly influenced alginate cost structures in key sourcing regions. Conversely, other input streams benefit from more stabilized byproduct supply chains, supporting consistent formulation availability. The research also captures how tariff policy adjustments and trade environment shifts are altering the cost calculus for imported and domestically sourced hydrocolloid materials, providing procurement teams with essential context for contract structuring and inventory planning.
Why This Research Is Structurally Vital for 2026 Decision-Making
The transition from 2025 historical baselines into the 2026-2032 forecast window coincides with a period of intensified reformulation activity across food, pharmaceutical, and personal care categories. Clean-label expectations continue to reshape ingredient acceptable-use lists, while sustainability commitments are pushing buyers to scrutinize sourcing provenance and processing footprints. In parallel, the competitive landscape is consolidating around larger, better-capitalized players who can invest in capacity, streamline global distribution, and offer integrated formulation support. Against this backdrop, strategic planning requires more than top-line growth projections.
Procurement and Supply Chain Resilience
For procurement and supply chain leadership, the forecast horizon offers a structured framework for anticipating where supply constraints may emerge and where diversification pathways should be prioritized. Understanding how regional production concentrations intersect with raw material harvest cycles allows organizations to model inventory strategies, evaluate dual-sourcing feasibility, and negotiate contracts with a clearer view of medium-term cost trajectories. The research does not simply identify vulnerable nodes in the supply chain; it contextualizes them within broader market concentration metrics, giving buyers a realistic assessment of supplier dependency risks and negotiating leverage.
R&D and Formulation Strategy
Product development teams face an equally complex environment. As manufacturers seek to replace synthetic or less-desirable texturizing inputs with natural alternatives, the choice of gelling agent affects not only sensory performance and stability but also regulatory compliance and consumer perception. The segmentation analysis within the report enables R&D leadership to align ingredient selection with end-market demand patterns, anticipate where certain product types are gaining or losing formulation share, and identify whitespaces where specialized gelling solutions may command premium positioning. By mapping application-level demand against product-type evolution, formulation strategists can prioritize development efforts toward segments where natural gelling adoption is structurally accelerating rather than temporarily opportunistic.
Capital Allocation and Market Entry Evaluation
For investors, business development teams, and executive leadership evaluating capacity investments or market entry, the forward-looking trajectory provides essential guardrails. The sustained compound growth rate reflects a market that is expanding in step with broader consumer and industrial demand rather than experiencing a speculative surge. However, the distribution of that growth across regions, applications, and product categories is uneven, and success depends on identifying where capacity additions will be absorbed efficiently versus where oversupply or margin compression may emerge. The report's integrated view of competitive moves, capacity investments, and regional demand balances equips decision-makers with the context needed to evaluate entry timing, partnership structures, and asset deployment strategies with greater precision.
The Competitive Field: Structure, Consolidation, and Strategic Signals
The natural gelling agent market is defined by a diverse yet increasingly concentrated set of participants. Global food ingredient conglomerates bring scale, integrated supply chains, and broad formulation service capabilities, while specialized hydrocolloid manufacturers compete on technical performance, niche application expertise, and regional supply reliability. The competitive analysis within the report maps these dynamics across a comprehensive set of leading organizations, detailing how their respective portfolios span key product categories such as gelatin, pectin, carrageenan, xanthan gum, agar-agar, and other hydrocolloids, and how those portfolios align with demand across food and beverage, pharmaceutical, personal care, and industrial applications.
Strategic Moves Reshaping Market Leverage
Recent corporate activity underscores a clear pattern: consolidation and capacity investment are being deployed to strengthen supply security and broaden technical service capabilities. The acquisition of a major specialty hydrocolloid supplier by a global food ingredients platform for approximately 1.8 billion USD represents a decisive consolidation of pectin and specialty gum assets, enhancing scale and formulation reach across food and beverage markets. Separately, substantial capital commitments are flowing into new manufacturing capacity, including multi-hundred-million-dollar investments aimed at establishing localized production of fermentation-derived gelling inputs in key Western markets, alongside expanded pectin capacity in Latin American production hubs. These developments signal a broader industry shift toward securing regional supply nodes, reducing exposure to cross-continental logistics risks, and aligning production footprint with end-market demand centers.
Specialization and Technical Differentiation
While consolidation provides scale advantages, differentiation remains a critical competitive lever. Leading gelatin manufacturers continue to emphasize high-purity grades tailored for pharmaceutical and nutraceutical applications, while pectin specialists focus on consistency, sustainability credentials, and citrus- and apple-derived supply reliability. Seaweed-derived hydrocolloid producers navigate the technical and sourcing complexities of marine raw material supply, balancing formulation performance with exposure to regional harvest variability. Fermentation-based and cellulose-derived gelling inputs add further technical diversity, enabling formulators to match specific rheological and stability requirements. The research evaluates how these distinct strategic postures influence market positioning, pricing resilience, and customer lock-in across application segments.
Navigating Structural Risks and Emerging Opportunities
No market trajectory unfolds in a vacuum. The research explicitly integrates dynamic risk factors and opportunity drivers that will shape how growth materializes across the forecast period. On the raw material front, the natural gelling supply chain remains sensitive to agricultural and marine sourcing conditions. Regional concentration of seaweed harvesting for carrageenan and alginate production introduces weather-related and harvest-cycle vulnerabilities that can ripple through input pricing and availability. At the same time, byproduct-driven supply streams offer more stable feedstock pathways, supporting consistent production for certain product types. Understanding these asymmetries is essential for building robust sourcing strategies and for anticipating where pricing volatility may create margin pressure or, conversely, open windows for advantageous procurement.
Regulatory and trade environments add another layer of strategic complexity. Recent adjustments to tariff frameworks have altered the cost landscape for certain imported hydrocolloid materials, with exemptions and reciprocal tariff structures influencing the relative attractiveness of domestic versus imported sourcing. These policy shifts interact with broader sustainability and clean-label expectations, shaping not only cost but also formulation compliance and consumer-facing positioning. The report contextualizes these dynamics so that strategy teams can separate transient policy effects from longer-term structural cost reassignments.
Ultimately, the strategic value of this research lies in its capacity to translate market complexity into decision-ready clarity. By aligning historical performance, forward-looking growth projections, segment-level demand mapping, competitive intelligence, and supply-side dynamics within a single analytical framework, the Worldwide Natural Gelling Agent Market study equips organizations to move beyond reactive problem-solving and toward proactive strategy execution. The numbers tell a story of steady expansion, but the real insight lies in understanding how that expansion is distributed, who is positioned to capture it, and where structural risks and opportunities will emerge as the market advances through the remainder of the decade.
Gellan Gum Market
For leadership teams preparing for 2026 and beyond, the difference between speculation and informed strategy is access to complete, structured, and current market intelligence. The full research provides the detailed segmentation breakdowns, regional and application-level revenue distributions, competitive benchmarking, and forward-looking scenario context necessary to operationalize the insights outlined here. We invite strategic decision-makers to explore the complete analysis and integrate its findings into their planning processes, ensuring that growth ambitions are grounded in precise, actionable market intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Natural Gelling Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com