

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Automotive Optoelectronic Market to Reach $15.5B by 2032 at 13.85% CAGR

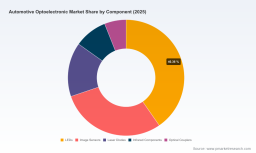
Navigating the Light-Driven Era: Strategic Intelligence for the Worldwide Automotive Optoelectronic Market Through 2032
The automotive industry is undergoing a fundamental recalibration of how vehicles perceive, communicate, and illuminate their surroundings. At the center of this transformation lies the optoelectronic subsystem, a critical enabler of advanced driver assistance, adaptive illumination, and next-generation human-machine interfaces. As automakers and tier-one suppliers navigate tightening safety mandates, semiconductor capacity realignments, and rapidly evolving LiDAR and camera architectures, access to granular, forward-looking market intelligence is no longer optional. It is a prerequisite for capital allocation, supplier selection, and technology roadmapping.
PW Consulting’s latest Worldwide Automotive Optoelectronic Market study provides a structured, data-backed framework for decision-makers operating across the automotive value chain. Drawing on a multi-year historical baseline spanning 2020 through 2025 and a comprehensive forecast window extending to 2032, this report maps the trajectory of a market that has consistently outpaced traditional automotive component growth cycles. For executive teams planning product portfolios, securing supply agreements, or evaluating partnership opportunities in 2026, the study delivers the analytical rigor required to separate structural trends from short-term volatility.
A Decade of Acceleration: What the Numbers Reveal About Market Scale and Trajectory
The macroeconomic arc of the automotive optoelectronic sector tells a clear story of compounding demand. From a baseline of approximately 3,450 million USD in 2020, the market expanded through successive growth phases to reach roughly 6,250 million USD by 2025. This progression reflects the accelerating integration of optical sensing, LED-based illumination, and laser-driven ranging technologies into mainstream vehicle architectures. Looking ahead, the forecast period from 2026 through 2032 projects continued expansion at a compound annual growth rate of 13.85 percent, with market valuation climbing steadily toward the mid-15,000 million USD range by the end of the outlook window.
These figures are not merely historical footnotes. They represent the quantitative foundation for capacity planning, R&D prioritization, and regional investment decisions. A sustained double-digit growth trajectory of this magnitude signals that optoelectronic components are transitioning from peripheral accessories to core architectural elements. For automotive OEMs, tier-one integrators, and semiconductor manufacturers, the implication is straightforward: timing, product differentiation, and supply chain resilience will determine competitive positioning in the years ahead. The report contextualizes these macro trends within component-level adoption curves, application-driven demand cycles, and regional deployment patterns, giving strategists the scaffolding needed to model revenue scenarios and assess market entry or expansion opportunities.
Inside the Research: How the Report Translates Data Into Actionable Intelligence
Market studies are only as valuable as their ability to inform real-world decisions. This report is structured around operational utility, combining quantitative forecasting with qualitative analysis of technology adoption, regulatory impact, and competitive positioning. The analytical framework covers component segmentation, application-driven demand mapping, geographic deployment dynamics, and concentration metrics that reveal where value is accumulating across the supply chain. Rather than presenting isolated statistics, the study weaves together cross-referencing layers that allow readers to trace how shifts in one segment—such as safety regulation or sensor architecture—ripple through adjacent markets and supplier ecosystems.
Readers will find detailed assessments of how lighting systems, advanced driver assistance platforms, infotainment and telematics architectures, and powertrain-related optical applications are reshaping procurement priorities. The report also examines the structural forces compressing or expanding margins, including raw material price stabilization, fab capacity constraints, and the certification requirements that govern safety-critical deployments. By aligning historical performance with forward-looking indicators, the study equips teams with the benchmarks needed to evaluate supplier competitiveness, forecast component availability, and stress-test product launch timelines against emerging technological and regulatory milestones.
Worldwide Automotive Optoelectronic Market
Worldwide LNOI Optoelectronic Chip Market
Competitive Dynamics: Where Leaders Are Positioning for the Next Wave
The automotive optoelectronic landscape is defined by a concentrated yet highly active supplier base. Top-tier players account for a meaningful share of total market revenue, with the leading three firms collectively representing approximately 38.5 percent of industry output and the top five capturing just over half of total revenue. This concentration underscores the strategic importance of supplier relationships, technology partnerships, and continuous product innovation. Companies that can align component performance with automotive-grade reliability, cost efficiency, and program scalability are increasingly becoming gatekeepers for next-generation vehicle platforms.
Several foundational players anchor this ecosystem through differentiated technology portfolios. European and Austrian-based innovators have deepened their focus on automotive LEDs, VCSEL arrays, photodiodes, and ambient light sensing solutions tailored for headlights, ADAS modules, and interior lighting environments. German semiconductor manufacturers continue to supply optoelectronic components spanning LEDs, infrared emitters, and detectors that support both sensing and illumination functions. Swiss-headquartered firms have expanded their automotive-qualified CMOS image sensor and time-of-flight offerings, including specialized sensor families designed for ADAS and gesture recognition. Japanese technology leaders remain pivotal in high-power blue LEDs, laser diodes, and UV LED architectures that enable advanced headlight systems and LiDAR applications, while South Korean manufacturers have introduced wafer-level chip-on-plate and next-generation LED platforms targeting exterior lighting, smart headlights, and display integration.
Meanwhile, Dutch specialists have scaled high-power LED architectures for forward lighting, matrix beam systems, and adaptive illumination. American-based sensor developers are pushing ultra-low-light CMOS image sensor performance for ADAS cameras and surround-view applications. Japanese semiconductor solution providers continue to supply stacked CMOS image sensors engineered for automotive vision systems and ADAS workloads. Additional U.S.-based suppliers have broadened their portfolios with image sensor arrays, ambient light sensing, and VCSEL driver technologies. Swiss connectivity experts contribute fiber optic connectors, optical sensors, and encoders for data transmission and sensing applications, while Taiwanese manufacturers round out the ecosystem with surface-mount LEDs and photointerrupter solutions for interior, exterior, and sensor-related deployments.
Recent product activity illustrates how quickly this competitive field is evolving. In early 2024, one European technology group unveiled a multi-pixel matrix laser light source designed for dynamic high-beam automotive lighting, signaling a shift toward highly programmable illumination architectures. Around the same period, a South Korean LED manufacturer showcased a platform integrating digital micro-mirror devices for smart adaptive headlights, highlighting the convergence of optical components and display technologies. In late 2023, a Swiss semiconductor firm introduced a QVGA global shutter image sensor qualified for automotive ADAS applications, reinforcing the industry’s emphasis on latency-sensitive vision systems. At a major mobility trade show that same year, a Japanese company presented a high-lumen laser diode targeting short- and mid-range LiDAR use cases, while a U.S. sensor supplier had previously launched a global shutter image sensor optimized for automotive machine vision and robotics-related applications. These developments are not isolated product launches; they are indicators of where R&D capital is flowing and which technology pathways are gaining commercial traction.
Market Forces Shaping the 2026–2032 Horizon
The growth trajectory of automotive optoelectronics cannot be understood in isolation from the regulatory, geopolitical, and supply-side forces that surround it. Safety regulations are increasingly dictating sensor and camera deployment. The EU General Safety Regulation mandates camera-based systems for emergency braking and intelligent speed assistance beginning in mid-2024, directly accelerating demand for vision components and associated optical subsystems. At the same time, functional safety standards require automotive optoelectronic sensors operating in safety-critical ADAS functions to meet ASIL-B through ASIL-D certification thresholds, raising the bar for qualification, testing, and long-term reliability.
Geopolitical and industrial policy dynamics are also reshaping manufacturing and sourcing strategies. Major semiconductor subsidy frameworks, including the U.S. CHIPS and Science Act’s substantial funding pool for domestic production, are influencing where automotive-grade optoelectronic components are designed, fabricated, and assembled. These incentives are encouraging regional capacity investments, but they also introduce new considerations around supply continuity, qualification lead times, and multi-source strategies.
Supply chain volatility remains a persistent variable. Disruptions such as the April 2024 seismic event in Taiwan, which temporarily halted production at major fabrication facilities and delayed automotive CMOS image sensor deliveries, serve as reminders that concentration risk in advanced semiconductor manufacturing can quickly translate into program delays and inventory pressure. On the materials front, price dynamics for key enablers such as GaN-on-Si epiwafers have shown stabilization after earlier upward pressure, reflecting capacity expansions in Japan and Europe. These cost and availability signals matter deeply for margin modeling and for decisions about long-term supply agreements.
Why This Study Matters for 2026 Decision-Making
As organizations enter 2026, the strategic questions facing automotive and semiconductor teams are becoming more specific and more urgent. Which component categories will capture the steepest adoption curves? How will regional demand patterns shift as safety mandates take effect and local semiconductor ecosystems mature? Where are suppliers gaining structural advantages through technology differentiation, and where is consolidation likely to intensify? The Worldwide Automotive Optoelectronic Market report is designed to answer these questions with the precision required for executive planning.
The study provides a complete analytical foundation for evaluating market entry, portfolio expansion, supplier qualification, and technology investment. It aligns historical performance with forward forecasts, embeds regulatory and supply-side context into segment-level analysis, and maps competitive positioning across a globally distributed supplier base. For organizations that need to move beyond high-level industry narratives and into detail-grade market intelligence, this report offers the structure, data depth, and strategic context necessary to make informed decisions with confidence.
To access the full segmentation breakdowns, regional demand mappings, competitive benchmarking details, and complete forecast tables, we invite you to explore the complete report on our website. The insights outlined here represent a strategic preview; the full study delivers the comprehensive intelligence needed to shape your 2026 roadmap and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Automotive Optoelectronic Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com