

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Hernia Mesh Market Hits $4.8B in 2025, Projected 4.8% CAGR Through 2032

Strategic Intelligence for the Next Growth Cycle: Inside the Worldwide Inguinal Hernia Repair Mesh Market 2026–2032
The global surgical landscape is entering a decisive growth phase, driven by aging demographics, rising surgical volumes, and continuous innovation in soft-tissue reinforcement technologies. For medtech executives, procurement leaders, and strategic planners, navigating the worldwide inguinal hernia repair mesh market requires more than surface-level demand forecasts. It demands a rigorous, data-backed view of how clinical workflows, regulatory shifts, material economics, and competitive positioning will intersect over the coming years. Our newly released Worldwide Inguinal Hernia Repair Mesh Market research delivers precisely that intelligence, offering a structured, decision-ready foundation for enterprise strategy in 2026 and beyond.
Built on a comprehensive historical baseline spanning 2020–2025 and extending through a detailed forecast period from 2026 to 2032, this report translates complex market signals into actionable insight. It is engineered for leadership teams that need to align product portfolios, evaluate market entry or expansion opportunities, and anticipate structural changes before they become pricing or volume pressure points. The analysis places particular emphasis on how evolving surgical preferences, reimbursement frameworks, and material cost dynamics will shape enterprise performance across the forecast horizon.
Worldwide Hernia Mesh Devices Market
Market Trajectory and Growth Architecture
The worldwide inguinal hernia repair mesh market has demonstrated consistent expansion over the past half-decade, supported by steady surgical volume growth, broader adoption of tension-free repair techniques, and increasing procedural standardization across both mature and emerging healthcare systems. Historical revenue progression from 2020 through 2025 reflects a market that has matured yet retained clear upward momentum, with annual performance indicating resilience against macroeconomic volatility and supply chain friction. This established trajectory provides a credible foundation for forward-looking planning, allowing organizations to model realistic growth scenarios rather than relying on speculative assumptions.
The forecast window maps a sustained growth path, anchored by a projected compound annual growth rate of 4.8% across the 2026–2032 period. This growth rate is neither hyper-accelerated nor stagnant; it reflects a market that is scaling through surgical adoption, clinician preference evolution, and procedural mix shifts, while remaining sensitive to cost containment pressures and regulatory oversight. For strategists, this environment rewards disciplined portfolio positioning, differentiated clinical value propositions, and surgical-site-specific commercial execution. The consistency of the forecast curve also enables scenario modeling around volume, pricing, and mix, giving enterprise teams a reliable framework for resource allocation, capacity planning, and market prioritization.
Importantly, the market’s size and momentum do not imply uniform opportunity across all segments or geographies. The revenue dispersion across product architectures, procedural approaches, end-user settings, and regional ecosystems reveals where competitive intensity concentrates and where differentiated positioning can unlock disproportionate share gains. The report unpacks these dispersion patterns without reducing them to simplistic headline figures, enabling clients to understand the structural drivers that underpin growth variance and to calibrate investment accordingly.
Segment Architecture That Shapes Commercial Strategy
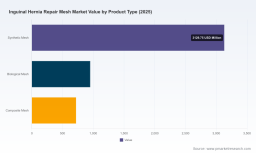
Product architecture remains one of the most decisive dimensions of competitive positioning in the inguinal hernia repair mesh category. The market comprises synthetic, biological, and composite mesh solutions, each aligned with distinct surgical philosophies, patient-risk profiles, and clinical adoption patterns. Synthetic meshes continue to anchor mainstream procedural volume, supported by established clinician familiarity, reproducible outcomes, and broad institutional procurement familiarity. Biological and composite alternatives occupy more specialized roles, often tied to specific patient cohorts, contamination risk considerations, or surgeon preference for enhanced tissue integration and reduced foreign-body response. Understanding how these product families interact with surgical indication patterns and procurement decision-making is essential for companies calibrating R&D priorities, manufacturing capacity, and marketing messages.
Surgical approach further defines the competitive field. Open surgery and laparoscopic surgery represent two major procedural pathways, each with unique mesh requirements, handling characteristics, and fixation considerations. Laparoscopic techniques have continued to gain relevance where surgical training, infrastructure, and reimbursement alignment support minimally invasive adoption. At the same time, open repair remains a durable volume base, particularly in settings where operational throughput, surgical expertise distribution, and case complexity favor established techniques. The balance between these approaches is not static, and the report examines the dynamics that will influence procedural mix evolution, including surgeon training pipelines, OR efficiency priorities, and the growing emphasis on standardization in inguinal hernia repair.
End-user configuration adds another layer of strategic nuance. Hospitals, ambulatory surgical centers, and specialty clinics each operate with different purchasing rhythms, cost sensitivity profiles, and surgical volume thresholds. Hospital systems typically concentrate high-acuity and high-volume procedures, often influencing standardization decisions across multiple service lines. Ambulatory surgical centers increasingly shape procedural throughput for selected hernia repair pathways, where efficiency, instrument turnover, and predictable case scheduling matter. Specialty clinics represent a more focused segment, often tied to concentrated surgical expertise or regional referral patterns. The report evaluates how these end-user environments influence product selection, tendering behavior, and value communication, giving commercial teams a clearer picture of where and how demand is formed.
Geographic distribution of demand introduces further strategic complexity. North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa each exhibit different healthcare infrastructure maturity, surgical training ecosystems, reimbursement environments, and import or distribution dynamics. Rather than treating these regions as interchangeable growth pools, the analysis distinguishes the operational realities that determine how mesh products are adopted, priced, and sustained in local markets. This regional granularity supports more precise opportunity sizing, market entry sequencing, and partnership evaluation for organizations expanding beyond their core territories.
Competitive Landscape and Strategic Positioning
The competitive environment in this market is defined by established multinational players with deep surgical portfolios, strong regulatory footprints, and long-standing relationships with clinical communities. Market concentration reflects a structure in which a relatively small group of leading participants commands a significant share of revenue, reinforcing the importance of differentiation, lifecycle management, and surgical-value storytelling. For entrants and incumbent challengers alike, successful positioning depends on how well a company can align product performance, surgical workflow compatibility, and commercial execution with the priorities of procurement committees and operating-room decision-makers.
Becton Dickinson continues to leverage its Bard mesh heritage alongside next-generation bioresorbable options such as Phasix Mesh, which is built on P4HB technology and positioned as an alternative for soft-tissue reinforcement. The company’s recent activity underscores both product expansion and clinical indication development, including CE-mark-related prophylactic use expansion and broader European availability. These moves highlight a strategy oriented toward extending the clinical relevance of mesh technologies beyond standard repair into prevention-oriented and high-risk surgical contexts. For competitors, such indication expansion can reshape reference points in surgical conversations and influence procurement considerations around long-term tissue outcomes and procedural versatility.
Medtronic, through its Covidien heritage, maintains a strong alignment with laparoscopic inguinal hernia repair, offering anatomical and self-fixating mesh solutions designed for TAPP and TEP approaches. Its portfolio emphasizes reinforcement of abdominal wall soft tissue with designs intended to support minimally invasive surgical workflows. In a market where procedural approach mix and surgeon training habits influence adoption curves, this laparoscopic orientation gives Medtronic a distinct positioning lever. The company’s product narratives often resonate in environments where OR efficiency, standardized mesh handling, and laparoscopic technique maturity are priorities for surgical programs.
Ethicon, as part of Johnson & Johnson MedTech, brings a widely recognized presence in hernia repair through established nonabsorbable mesh platforms and partially absorbable macroporous options for inguinal procedures. Its commercial strength is reinforced by broad surgical brand recognition and integration within larger medtech ecosystems. For strategists, Ethicon’s portfolio breadth and institutional footprint illustrate how product reliability, clinician familiarity, and cross-product surgical support can sustain competitive relevance even as technologies and surgical preferences evolve.
B. Braun Melsungen AG, operating through its Aesculap platform, offers mesh ranges designed for inguinal hernia repair and connective tissue reinforcement, with product attributes that emphasize handling characteristics and indication-specific use. This positioning supports surgical programs seeking predictable performance across defined repair scenarios. Similarly, W. L. Gore & Associates contributes biomaterials and dual-surface mesh solutions suited to reconstruction contexts, including applications that aim to manage adhesion risk while supporting inguinal and soft-tissue repair objectives. Getinge, through its Atrium Medical heritage, maintains a historical presence in synthetic hernia mesh products used in inguinal and abdominal wall repair, reflecting the broader reality that product lineage, manufacturing scale, and market reputation continue to matter in procurement decisions.
Together, these players illustrate a market where product engineering, surgical-method alignment, and commercial execution intersect. The report maps how these competitive profiles relate to demand formation and market share distribution, giving clients a practical lens for anticipating competitive responses, identifying whitespace, and shaping differentiation strategies that are not dependent solely on price competition.
Regulatory, Reimbursement, and Supply Chain Dynamics
Market performance in hernia mesh is increasingly shaped by forces that extend beyond surgical volume alone. Regulatory communication standards, reimbursement coding updates, and raw-material cost structures all influence how products are positioned, procured, and sustained across healthcare systems. In mid-2025, the U.S. FDA issued draft guidance recommending standardized package labeling for hernia mesh devices intended for hernia repair, including inguinal procedures. This guidance is designed to improve the consistency of clinically relevant information available to providers and to support safer and more effective use. For manufacturers, labeling clarity and documentation rigor are becoming more than compliance tasks; they are elements of commercial trust that can affect surgeon confidence, procurement review, and downstream adoption.
Reimbursement environments also exert direct influence on procedural economics. Updated Medicare coding and reimbursement guidance for hernia repair procedures, including inguinal repair with mesh, reflects revised CPT/HCPCS structures and national average payment rates effective at the start of 2026. These updates matter because reimbursement clarity can affect case economics, surgical program planning, and the willingness of institutions to standardize particular mesh solutions. Strategists should view reimbursement changes not as isolated administrative updates, but as factors that can either reinforce or disrupt adoption trajectories depending on how they interact with procedure mix, site of care, and product selection.
On the cost side, the materials environment has introduced meaningful pressure into manufacturing and sourcing strategies. Medical-grade polypropylene, the primary material base for most synthetic inguinal hernia repair meshes, has experienced price increases exceeding 35% since 2021, reaching approximately $1,700 per metric tonne in 2024. This trajectory affects cost structures, margin planning, and procurement negotiations, particularly for companies with high exposure to synthetic mesh production. In response, organizations are increasingly focused on supply resilience, formulation efficiency, and value communication that justifies pricing within institutional budget constraints. The report integrates these dynamics into the broader market narrative, helping clients assess how material economics and regulatory/reimbursement shifts combine to influence competitive behavior and demand patterns.
What the Report Delivers for Decision-Makers
This research is designed to serve as a working strategic resource rather than a static market summary. It provides a structured base-year viewpoint anchored in 2025, supported by historical performance data from 2020 through 2025, and extended by a forward forecast through 2032. By bridging historical validation with near- and mid-term projection, the report enables teams to test assumptions, benchmark expectations, and align planning cycles with a coherent market timeline. The analytical framework is built to support product strategy, market prioritization, competitive assessment, and commercial execution planning within a single coherent reference point.
Beyond top-line growth figures, the report examines the structural dimensions that determine how market value is created and captured. That includes the interplay of product type, surgical approach, end-user environment, and regional demand conditions, presented in a way that supports segmentation strategy without reducing the market to generic category statements. Clients gain insight into where demand concentration is strongest, how procedural and purchasing behavior varies across settings, and which structural factors are most likely to influence growth dispersion over the forecast period.
The competitive analysis component translates company activity into strategic implication. Rather than cataloguing product names for their own sake, the report evaluates how leading participants are shaping the market through portfolio emphasis, surgical-method alignment, indication expansion, and regulatory or reimbursement responsiveness. It also incorporates recent market-moving developments, including BD’s prophylactic indication milestone and product expansion activity, as well as the broader FDA labeling guidance and updated reimbursement coding context. These elements help clients understand not only who leads today, but how the competitive field is being reshaped in real time.
For enterprises operating in or entering this space, the report supports several practical use cases. It can inform product roadmap decisions by clarifying where clinical and commercial demand signals are most consistent. It can guide market-entry sequencing by distinguishing regions and end-user settings with different adoption dynamics. It can assist pricing and value-proposition development by connecting material cost pressures, reimbursement context, and surgical value narratives. It can also strengthen investor, management, and partnership communications by grounding strategic claims in a clear market trajectory and competitive structure.
Why This Research Matters for 2026 Strategy
The 2026 decision environment will reward organizations that can integrate clinical, regulatory, reimbursement, and cost realities into a single strategic view. The worldwide inguinal hernia repair mesh market is large enough to support meaningful growth, yet structured in ways that make undifferentiated approaches vulnerable to competitive compression. Companies that understand the forces shaping procedural mix, product preferences, and purchasing behavior will be better positioned to allocate resources, defend share, and pursue expansion with greater precision.
This report is intended to provide that strategic clarity. It offers a validated market baseline, a forward-looking growth framework, and a detailed look at the structural dynamics that matter most to enterprise decision-makers. By aligning historical evidence with forecast logic and competitive context, it helps organizations move from general market awareness to informed strategic action.
For a complete view of the segmentation architecture, regional demand interpretation, competitive mapping, and forward forecast detail, the full Worldwide Inguinal Hernia Repair Mesh Market research is available through the PW Consulting source page. The complete study provides the operational depth required to translate these high-level insights into targeted commercial and strategic decisions for 2026 and the years ahead.
Worldwide Inguinal Hernia Repair Mesh Market
For detailed analysis of this topic, please visit the official page: Worldwide Inguinal Hernia Repair Mesh Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com