

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Industrial Epoxy Glass Market to Reach $4.2B by 2032 Growing at 5.82% CAGR

Global Industrial Epoxy Glass Market Outlook 2026: Strategic Intelligence for Boards and Composite Leaders
The industrial epoxy glass sector stands at a pivotal juncture as organizations navigate post-pandemic supply normalization, intensifying electrification mandates, and the recalibration of global manufacturing footprints. Our latest Worldwide Industrial Epoxy Glass Market research delivers a forward-looking intelligence framework designed specifically for executive teams, procurement directors, and R&D strategists who must align capital allocation with durable material demand. Spanning historical performance from 2020 through 2025 and a rigorous forecast window from 2026 to 2032, this study translates macro trajectories into actionable decision architecture. The base year of 2025 anchors our analytical baseline at USD 2,842.6 million, while the projected jump to USD 3,008.61 million in 2026 confirms that underlying demand drivers remain structurally intact even as pricing volatility and capacity reallocation test margin resilience.
Readers approaching this report for 2026 boardroom planning will find more than retrospective summaries. The study is engineered to answer the strategic questions that keep industry leaders awake: which grade families will continue to absorb the largest value pools, how regional manufacturing shifts are reshaping competitive positioning, and where the next phase of capacity investment will generate the highest risk-adjusted returns. The narrative consistently bridges top-down market architecture with bottom-up operational realities, ensuring that strategic forecasts remain tethered to engineering specifications, certification requirements, and raw material economics rather than abstract growth curves.
Why 2026 Decision-Makers Need a Structured Epoxy Glass Intelligence Map
Industrial epoxy glass is no longer a commoditized insulation substrate. It is a performance-critical material embedded in high-reliability printed circuit boards, aerospace structural laminates, automotive electronic assemblies, and heavy industrial machinery. That embeddedness means demand is increasingly tied to downstream technology roadmaps rather than standalone material cycles. Our research framework treats the market as a system of interdependent choices: grade selection influences downstream validation timelines; regional sourcing decisions affect lead-time reliability and regulatory exposure; and raw material price movements can compress or expand the viability of specific processing routes. By mapping these interdependencies, the report gives leaders a shared reference point for cross-functional alignment between engineering, procurement, and commercial strategy.
The 2026-2032 forecast period is particularly consequential because it captures the maturation of several long-cycle programs in aerospace and defense alongside the scaling of automotive electronics content. Historical momentum from 2020-2025 demonstrates a market that has already absorbed multiple demand shocks and emerged with a stronger consolidated base. That resilience is not accidental; it reflects the sector's ability to sustain deployment even when upstream chemical pricing fluctuates and when regional manufacturing networks are rewired. For executives evaluating 2026 investment theses, the study offers a disciplined way to separate temporary price pacing from structural volume growth, allowing teams to plan around durable consumption patterns rather than headline noise.
Industrial Epoxy Glass Market Trajectory: Scaling Demand and Forecast Architecture
Market sizing in this study is constructed from a multi-layered triangulation of historical shipments, production disclosures, capacity signals, and downstream content forecasts. The resulting trajectory shows a market expanding from USD 2,145.3 million in 2020 to USD 2,842.6 million in 2025, with the forecast pathway extending toward USD 4,218.88 million by 2032. The compound annual growth rate across the 2026-2032 horizon is assessed at 5.82%, a pace that signals steady expansion rather than cyclical spikes. For strategy teams, this matters because it implies that competitive advantage will come less from timing a sudden surge and more from positioning reliably within a long-duration growth envelope.
Revenue units are expressed in millions of USD to maintain consistency across historical and forecast years, and the base year of 2025 acts as the calibration point for forward modeling. This structure allows the report to isolate how much of the 2026 opening position to USD 3,008.61 million is inherited from 2025 demand carry-over versus newly accelerated program activations. Decision-makers can use this framing to test internal forecasts against an externally validated baseline, pressure-testing whether their own order books, capacity plans, and pricing strategies are aligned with the sector's observed trajectory. The forecast does not rely on simplistic linear extrapolation; instead, it integrates grade-level substitution dynamics and application-level content changes so that leadership can see where volume growth is likely to concentrate and where pricing discipline will become the dominant value lever.
Segmentation Architecture: Grades, Applications, and Demand Drivers
The study's segmentation design is built to help executives move beyond broad category language and into the operational specifics that actually drive procurement and product strategy. Epoxy glass demand is structured around grade families that differ in dielectric performance, mechanical stability, flame-retardant behavior, and machining compatibility. The report examines how these grade distinctions influence end-market fit, particularly where electrical and electronics platforms require standardized high-volume laminates and where aerospace or industrial applications call for more specialized tolerance and certification profiles. By presenting each grade family within its functional context, the analysis clarifies why certain substrate classes maintain persistent demand even when overall market growth appears moderate.
LED Glass Market
Application segmentation is treated with equal rigor. Electrical and electronics use cases anchor a large share of consumption because epoxy glass laminates remain integral to board construction, insulation, and structural support in high-reliability assemblies. Aerospace and defense applications create a different demand signature: lower volume, higher specification, and stronger sensitivity to certification, traceability, and material consistency. Automotive electronics contribute a rapidly evolving demand layer tied to vehicle electrification, sensor proliferation, and power management content. Industrial machinery applications reinforce the market's base through durable requirements for insulating structural components and composite-format laminates that support heavy-duty operating environments. Rather than presenting these segments as isolated slices, the report maps the overlap between them so strategists can identify where multi-application grade families generate the most stable revenue streams and where application-specific specialization commands premium positioning.
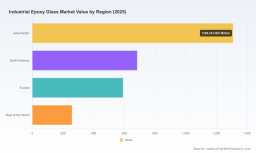
Regional analysis is equally central to the strategic narrative. The report evaluates how manufacturing density, logistics architecture, and engineering support networks shape regional demand patterns without reducing the discussion to a static split of market share. Asia Pacific's scale advantages, North America's high-reliability supply requirements, Europe's specification-driven industrial base, and the broader international footprint each create distinct purchasing behaviors and risk profiles. Executives using this research can better anticipate where supplier diversification, local content expectations, or certification alignment will become decisive factors in sourcing strategy. The report intentionally avoids reducing these dynamics to simple percentage rankings; instead, it explains why regional positioning matters operationally and how it interacts with grade availability, lead times, and technical service expectations.
Competitive Landscape: Strategy, Scale, and Regional Positioning
The industrial epoxy glass market is shaped by a mix of global specialty material leaders, North American laminate manufacturers with deep machining and fabrication capabilities, and large-scale Asian producers expanding throughput to capture both domestic and export demand. Our competitive analysis focuses on how these players differentiate across product breadth, application engineering, capacity strategy, and certification readiness.
Ventec International Group operates from a strong global position in high-performance copper clad laminates and prepregs, including epoxy glass-based materials for PCB and industrial insulation applications. Its relevance in this market stems from the way high-reliability electronic material expertise overlaps with industrial insulation requirements, giving it a credible platform in segments where electrical performance and mechanical stability must be balanced. Isola Group follows a similar strategic logic, specializing in copper-clad laminates and prepreg materials, including epoxy glass systems for high-reliability PCB and industrial electronic applications. For buyers and competitors alike, these companies illustrate how electronic-grade laminate expertise can translate into industrial epoxy glass demand when specifications and validation paths align.
Worldwide Industrial Epoxy Glass Market
In North America, a second competitive tier emphasizes sheet, rod, tube, and fabricated-part capabilities. Atlas Fibre stands out as a North American manufacturer and supplier of thermoset composite laminates including extensive G-10, FR-4, and G-11 epoxy glass sheets, rods, and tubes with in-house machining. Franklin Fibre-Lamitex Corp. reinforces this profile by manufacturing high-quality Lamitex G-10, FR-4, G-11, and FR-5 glass-reinforced epoxy laminates in sheet and tube forms meeting MIL and NEMA specifications. Current Inc. adds further depth as a US manufacturer of G-10/FR-4 glass epoxy laminates in sheets, tubes, rods, and fabricated parts for electrical and structural industrial uses. Iten Industries complements this landscape as a producer of NEMA-grade G-10 and G-10/FR4 epoxy glass laminates with over 100 years of experience in advanced composite materials. This cohort demonstrates that competitive advantage in certain market pockets comes from specification familiarity, machining readiness, and the ability to convert standard laminates into application-ready forms.
On the other side of the competitive equation, large-scale Chinese production capacity has become a defining feature of global supply dynamics. SIDA operates as a large-scale Chinese producer of FR-4, G-10, G-11, and 3240 epoxy glass laminates in sheets, tubes, and rods with capacity over 45,000 tons annually. Its scale signals the growing importance of volume throughput, standardized grade availability, and cost-competitive supply in global procurement planning. Hony Engineering Plastics Limited further illustrates this trajectory as a manufacturer of FR4, G10, G11 epoxy glass fiber laminate sheets and EPGC series materials for electrical insulation. Alongside these, Hexcel Corporation develops and supplies epoxy-based composite materials, including glass-reinforced systems for aerospace and industrial structural applications, while Park Aerospace Corp. manufactures advanced composite materials including epoxy glass laminates and prepregs for high-performance industrial and aerospace uses. Together, these players show that the market's competitive map is not simply about who produces the most volume, but about who can reliably serve the most demanding specification environments while maintaining cost and delivery credibility.
Strategic Dynamics: Raw Material Economics, Certifications, and Market Concentration
No epoxy glass strategy can be built without confronting upstream economics. Epoxy resin serves as the primary upstream chemical feedstock for epoxy glass laminates, with prices directly influencing production costs of G-10/FR-4 materials. Recent pricing signals reinforce the need for structured cost monitoring. Northeast Asia epoxy resin prices reached USD 2.62/KG in April 2026, while China epoxy resin prices were reported at USD 2031/MT in February 2026. These movements matter because they alter the cost backdrop for manufacturers and buyers simultaneously, affecting margin planning, inventory timing, and make-versus-buy judgments. The report integrates these price dynamics into a broader cost-structure discussion so that leaders can evaluate exposure not just at the laminate level, but across the resin-to-glass value chain.
Regulatory and certification expectations remain equally important. Epoxy glass laminates such as FR-4 from major suppliers maintain UL 94 V-0 flame retardancy and RoHS/REACH compliance as standard certifications. For procurement and engineering teams, this is not a footnote; it is a baseline requirement that determines supplier eligibility, validation speed, and downstream acceptance. The report emphasizes how certification readiness shapes competitive positioning, particularly in segments where qualification cycles are long and where switching costs are high. In such environments, suppliers that can demonstrate consistent compliance and documentation control gain durable access to demand even when price competition intensifies.
Market concentration data provides another strategic lens. The CR3 level sits at 32.4%, while CR5 reaches 48.7%. This structure indicates a market with meaningful scale players and established specialists, but not one dominated by a single overwhelming incumbency. For 2026 strategists, that matters because it suggests room for differentiation through service, grade specialization, regional capability, and fabrication value-add, rather than relying solely on volume dominance. The report uses these concentration signals to frame questions about partnership strategy, supplier diversification, and the potential for consolidation or capacity expansion to reshape competitive access over the forecast period.
Recent Developments and Forward Indicators
Momentum from late 2025 and early 2026 underscores that product innovation and capacity signaling remain active across the value chain. In April 2026, SHD Composites launched MTC521FR flame-retardant clear epoxy prepreg for visually critical applications, extending capabilities in epoxy-based composites. This kind of development matters because it shows how epoxy glass-adjacent material systems continue to expand into applications where appearance, flame performance, and processing precision must be balanced. It also signals that competitive differentiation is increasingly tied to specialty prepreg and laminate variants rather than only standard commodity grades.
At the end of 2025, Hony Engineering Plastics updated offerings and specifications for EPGC series epoxy glass fabric laminate sheets spanning EPGC201 to EPGC308, meeting IEC and GB standards. This move reinforces the importance of standards alignment in electrical insulation markets and suggests that suppliers are actively broadening specification coverage to support broader customer qualification pathways. At the same time, SIDA signaled ongoing expansion projects supporting annual manufacturing capacity exceeding 45,000 tons of epoxy glass laminates including FR-4, G-10, and G-11 grades. Capacity signaling of this type is a critical forward indicator because it shapes future supply availability, competitive pricing tension, and regional sourcing flexibility. The report weaves these developments into a forward-looking discussion so that leaders can interpret them not as isolated news items, but as evidence of how product structure and supply scale are evolving in parallel.
Inside the Report: What Decision-Makers Will Find
This study is built for direct operational use. Beyond the macro trajectory and segmentation structure, the report provides a practical toolkit for teams responsible for sourcing strategy, capacity planning, product roadmap alignment, and competitive monitoring. The content is organized to support both high-level strategic review and detailed cross-functional discussion, with clear linkages between market structure, grade economics, application demand, and supplier behavior. Readers will find a framework that helps answer questions such as where demand durability is strongest, how certification and specification requirements influence supplier access, and which structural factors are likely to determine margin outcomes over the 2026-2032 period.
The analysis also treats raw material exposure, regional supply dynamics, and capacity signals as living variables rather than static assumptions. By integrating recent pricing movements, product launches, specification updates, and capacity expansion narratives into one strategic view, the report enables decision-makers to test internal assumptions against market-consistent evidence. For boards and senior management teams, this means the research can support investment prioritization, risk mapping, and sourcing architecture discussions without requiring teams to reconstruct the underlying logic from fragmented sources.
How to Use This Research for 2026 Planning
The strongest value of this study lies in its ability to turn complex material-market dynamics into a disciplined decision frame. Executives can use the report to validate demand expectations, expose hidden sensitivities in cost and certification pathways, and identify where supplier positioning is likely to shift as capacity and product specialization evolve. Procurement teams can build sourcing strategies around a clearer understanding of grade families, application fit, and regional capability. Engineering and product leaders can better anticipate where material selection will influence downstream validation timelines and how epoxy glass systems fit within broader composite and electronics roadmaps.
Because the full report contains the detailed segment architecture, comparative supplier assessment, and forward-looking scenario framework required for implementation, this preview is designed to establish the strategic direction and analytical rigor behind the work. The complete intelligence set enables teams to move from directional confidence to specific, defensible action plans.
Key Takeaways for Strategic Action
- The market is expanding from a 2025 base of USD 2,842.6 million toward a 2026 opening of USD 3,008.61 million and a 2032 trajectory of USD 4,218.88 million, with a 5.82% CAGR across the forecast window.
- Grade families such as FR-4, G-10, G-11, and other specialty grades anchor distinct demand profiles across electrical, aerospace, automotive, and industrial applications, making grade-level strategy essential rather than optional.
- Competitive advantage increasingly depends on specification readiness, certification consistency, machining and fabrication capability, and capacity scale rather than volume alone.
- Upstream epoxy resin pricing directly shapes production economics, so cost planning must integrate resin-to-laminate exposure instead of treating laminate pricing in isolation.
- Market concentration is moderate, leaving meaningful room for differentiation through service, specialization, regional reach, and application engineering.
- Recent product launches, specification updates, and capacity expansion signals indicate that product structure and supply scale are evolving together, requiring continuous monitoring rather than one-time assessment.
Get the Full Market Intelligence
This preview outlines the strategic structure and analytical discipline behind our Worldwide Industrial Epoxy Glass Market research, but the complete report contains the detailed segment maps, supplier positioning frameworks, regional dynamics, and forward scenarios needed to act with confidence in 2026. If your team is preparing sourcing decisions, capacity evaluations, specification roadmaps, or competitive response plans, the full study provides the granular intelligence required to convert market direction into executable strategy. Access the complete report to unlock the full dataset, segmentation detail, and implementation-ready analysis built for enterprise decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Epoxy Glass Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com