

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Gelling Agent Market Hits $9.13B in 2025, Poised for 6.42% CAGR Through 2032

Strategic Imperatives in the Global Natural Gelling Agent Market: Navigating Growth Through 2032
Executive Introduction: Why This Market Matters in 2026
The global natural gelling agent market stands at a critical inflection point. As formulation scientists, procurement leaders, and corporate strategists alike navigate an increasingly complex landscape defined by clean-label mandates, supply chain volatility, and shifting regulatory frameworks, the ability to anticipate structural shifts across hydrocolloid markets has transitioned from a tactical advantage to an operational necessity. Our latest Worldwide Natural Gelling Agent Market research delivers precisely that foresight, grounding strategic decision-making in rigorous historical analysis and forward-looking projections spanning 2026 to 2032.
Built upon a comprehensive six-year historical dataset covering 2020 through 2025, this analysis traces a clear trajectory of sustained commercial expansion. The market has consistently demonstrated resilience and incremental growth, with total revenue climbing from approximately 6.71 billion USD in 2020 to 8.09 billion USD by 2023, accelerating further to 8.59 billion USD in 2024. The most recent historical baseline places the market at roughly 9.13 billion USD in 2025, setting a robust platform for the forecast horizon. Looking ahead, the research outlines a steady, compounding growth pathway, with total market value projected to surpass 9.7 billion USD in 2026 and continue its upward march through the decade, ultimately reaching a valuation approaching 14.1 billion USD by 2032. This evolution is underpinned by a compound annual growth rate of 6.42 percent, a figure that encapsulates both underlying demand momentum and the structural maturation of global supply networks.
For enterprise decision-makers, these numbers are not merely retrospective scorecards. They represent the foundational architecture upon which procurement strategies, capital allocation decisions, product development roadmaps, and competitive positioning must be built. In an environment where ingredient availability, geographic sourcing dynamics, and raw material pricing can shift within quarters, relying on static or fragmented market intelligence introduces measurable strategic risk. This research was designed specifically to eliminate that blind spot.
The Architecture of the Analysis: What the Research Delivers
A market of this scale and complexity cannot be understood through aggregate revenue figures alone. Effective strategy requires granular visibility into how demand is distributed across end-use sectors, how formulation preferences are evolving by product type, and where geographic concentrations of production and consumption create both opportunities and vulnerabilities. The Worldwide Natural Gelling Agent Market report is structured to translate raw market data into actionable strategic intelligence across multiple dimensions.
Segment-Level Demand Mapping
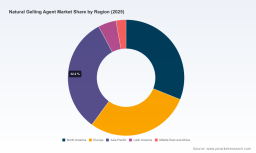
The analysis dissects market composition across three primary structural lenses. The first examines product-type dynamics, revealing how traditional staples and emerging specialty hydrocolloids compete for formulation share across diverse industrial and consumer applications. The second dimension evaluates end-use application segmentation, tracing how food and beverage formulations, pharmaceutical-grade excipients, cosmetics and personal care formulations, and broader industrial uses each drive distinct volume and value requirements. The third dimension provides a regional breakdown, identifying which geographic markets are absorbing the largest shares of production, where localized supply ecosystems are maturing, and how cross-border trade flows are shaping competitive accessibility. Rather than presenting isolated percentage allocations or standalone revenue pockets, the report contextualizes each segment within broader formulation trends, regulatory developments, and supply chain realities, enabling leaders to assess where incremental growth is structurally supported versus where it depends on short-term cyclical factors.
Worldwide Natural Gelling Agent Market
Competitive Positional Intelligence
Beyond segmentation, the research delivers a rigorous competitive landscape assessment. Spanning a broad roster of established multinational ingredient suppliers and specialized hydrocolloid manufacturers, the company profiles map out strategic capabilities, product portfolio strengths, geographic manufacturing footprints, and recent corporate developments that signal shifting market leverage. The analysis explicitly tracks high-impact corporate actions, including the landmark acquisition that consolidated major pectin and specialty gum assets under a single global food ingredients platform, alongside targeted capacity expansions in key production regions aimed at securing supply for high-demand natural gelling inputs. These moves are not treated as isolated news items; instead, they are evaluated for their downstream implications on pricing power, supply reliability, and formulation access across customer sectors.
Operational and Supply-Side Dynamics
Market value is ultimately governed by physical realities: raw material availability, agricultural and marine harvest cycles, processing capacity, and logistical friction. The report integrates current supply-side intelligence that directly affects formulation economics. Recent quarters have illustrated how tightly coupled the natural gelling supply chain is to external environmental and sourcing variables. Fluctuations in red seaweed availability have placed upward pressure on specific hydrocolloid input pricing, while brown seaweed supply variability has similarly influenced alginate cost structures in key sourcing regions. Conversely, other input streams benefit from more stabilized byproduct supply chains, supporting consistent formulation availability. The research also captures how tariff policy adjustments and trade environment shifts are altering the cost calculus for imported and domestically sourced hydrocolloid materials, providing procurement teams with essential context for contract structuring and inventory planning.
Why This Research Is Structurally Vital for 2026 Decision-Making
The transition from 2025 historical baselines into the 2026-2032 forecast window coincides with a period of intensified reformulation activity across food, pharmaceutical, and personal care categories. Clean-label expectations continue to reshape ingredient acceptable-use lists, while sustainability commitments are pushing buyers to scrutinize sourcing provenance and processing footprints. In parallel, the competitive landscape is consolidating around larger, better-capitalized players who can invest in capacity, streamline global distribution, and offer integrated formulation support. Against this backdrop, strategic planning requires more than top-line growth projections.
Procurement and Supply Chain Resilience
For procurement and supply chain leadership, the forecast horizon offers a structured framework for anticipating where supply constraints may emerge and where diversification pathways should be prioritized. Understanding how regional production concentrations intersect with raw material harvest cycles allows organizations to model inventory strategies, evaluate dual-sourcing feasibility, and negotiate contracts with a clearer view of medium-term cost trajectories. The research does not simply identify vulnerable nodes in the supply chain; it contextualizes them within broader market concentration metrics, giving buyers a realistic assessment of supplier dependency risks and negotiating leverage.
R&D and Formulation Strategy
Product development teams face an equally complex environment. As manufacturers seek to replace synthetic or less-desirable texturizing inputs with natural alternatives, the choice of gelling agent affects not only sensory performance and stability but also regulatory compliance and consumer perception. The segmentation analysis within the report enables R&D leadership to align ingredient selection with end-market demand patterns, anticipate where certain product types are gaining or losing formulation share, and identify whitespaces where specialized gelling solutions may command premium positioning. By mapping application-level demand against product-type evolution, formulation strategists can prioritize development efforts toward segments where natural gelling adoption is structurally accelerating rather than temporarily opportunistic.
Capital Allocation and Market Entry Evaluation
For investors, business development teams, and executive leadership evaluating capacity investments or market entry, the forward-looking trajectory provides essential guardrails. The sustained compound growth rate reflects a market that is expanding in step with broader consumer and industrial demand rather than experiencing a speculative surge. However, the distribution of that growth across regions, applications, and product categories is uneven, and success depends on identifying where capacity additions will be absorbed efficiently versus where oversupply or margin compression may emerge. The report's integrated view of competitive moves, capacity investments, and regional demand balances equips decision-makers with the context needed to evaluate entry timing, partnership structures, and asset deployment strategies with greater precision.
The Competitive Field: Structure, Consolidation, and Strategic Signals
The natural gelling agent market is defined by a diverse yet increasingly concentrated set of participants. Global food ingredient conglomerates bring scale, integrated supply chains, and broad formulation service capabilities, while specialized hydrocolloid manufacturers compete on technical performance, niche application expertise, and regional supply reliability. The competitive analysis within the report maps these dynamics across a comprehensive set of leading organizations, detailing how their respective portfolios span key product categories such as gelatin, pectin, carrageenan, xanthan gum, agar-agar, and other hydrocolloids, and how those portfolios align with demand across food and beverage, pharmaceutical, personal care, and industrial applications.
Strategic Moves Reshaping Market Leverage
Recent corporate activity underscores a clear pattern: consolidation and capacity investment are being deployed to strengthen supply security and broaden technical service capabilities. The acquisition of a major specialty hydrocolloid supplier by a global food ingredients platform for approximately 1.8 billion USD represents a decisive consolidation of pectin and specialty gum assets, enhancing scale and formulation reach across food and beverage markets. Separately, substantial capital commitments are flowing into new manufacturing capacity, including multi-hundred-million-dollar investments aimed at establishing localized production of fermentation-derived gelling inputs in key Western markets, alongside expanded pectin capacity in Latin American production hubs. These developments signal a broader industry shift toward securing regional supply nodes, reducing exposure to cross-continental logistics risks, and aligning production footprint with end-market demand centers.
Specialization and Technical Differentiation
While consolidation provides scale advantages, differentiation remains a critical competitive lever. Leading gelatin manufacturers continue to emphasize high-purity grades tailored for pharmaceutical and nutraceutical applications, while pectin specialists focus on consistency, sustainability credentials, and citrus- and apple-derived supply reliability. Seaweed-derived hydrocolloid producers navigate the technical and sourcing complexities of marine raw material supply, balancing formulation performance with exposure to regional harvest variability. Fermentation-based and cellulose-derived gelling inputs add further technical diversity, enabling formulators to match specific rheological and stability requirements. The research evaluates how these distinct strategic postures influence market positioning, pricing resilience, and customer lock-in across application segments.
Navigating Structural Risks and Emerging Opportunities
No market trajectory unfolds in a vacuum. The research explicitly integrates dynamic risk factors and opportunity drivers that will shape how growth materializes across the forecast period. On the raw material front, the natural gelling supply chain remains sensitive to agricultural and marine sourcing conditions. Regional concentration of seaweed harvesting for carrageenan and alginate production introduces weather-related and harvest-cycle vulnerabilities that can ripple through input pricing and availability. At the same time, byproduct-driven supply streams offer more stable feedstock pathways, supporting consistent production for certain product types. Understanding these asymmetries is essential for building robust sourcing strategies and for anticipating where pricing volatility may create margin pressure or, conversely, open windows for advantageous procurement.
Regulatory and trade environments add another layer of strategic complexity. Recent adjustments to tariff frameworks have altered the cost landscape for certain imported hydrocolloid materials, with exemptions and reciprocal tariff structures influencing the relative attractiveness of domestic versus imported sourcing. These policy shifts interact with broader sustainability and clean-label expectations, shaping not only cost but also formulation compliance and consumer-facing positioning. The report contextualizes these dynamics so that strategy teams can separate transient policy effects from longer-term structural cost reassignments.
Ultimately, the strategic value of this research lies in its capacity to translate market complexity into decision-ready clarity. By aligning historical performance, forward-looking growth projections, segment-level demand mapping, competitive intelligence, and supply-side dynamics within a single analytical framework, the Worldwide Natural Gelling Agent Market study equips organizations to move beyond reactive problem-solving and toward proactive strategy execution. The numbers tell a story of steady expansion, but the real insight lies in understanding how that expansion is distributed, who is positioned to capture it, and where structural risks and opportunities will emerge as the market advances through the remainder of the decade.
Gellan Gum Market
For leadership teams preparing for 2026 and beyond, the difference between speculation and informed strategy is access to complete, structured, and current market intelligence. The full research provides the detailed segmentation breakdowns, regional and application-level revenue distributions, competitive benchmarking, and forward-looking scenario context necessary to operationalize the insights outlined here. We invite strategic decision-makers to explore the complete analysis and integrate its findings into their planning processes, ensuring that growth ambitions are grounded in precise, actionable market intelligence.
For detailed analysis of this topic, please visit the official page: Worldwide Natural Gelling Agent Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com