

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: L7 and L6 Quadricycles Market Projected to Hit $3,887 Million by 2032

Strategic Horizons: Navigating the 2026-2032 Evolution of the L7 and L6 Quadricycles Market
The light quadricycle sector is standing at a definitive inflection point. As urban congestion intensifies across major metropolitan regions and regulatory frameworks tighten around low-emission zones, the demand for L6 and L7 quadricycles has transitioned from a niche alternative to a core component of modern mobility strategies. For industry stakeholders, understanding the trajectory of this market is no longer optional. It is a strategic imperative.
PW Consulting's latest comprehensive study on the L7 and L6 Quadricycles Market provides a granular roadmap of this transformation. Spanning historical analysis from 2020 through base year 2025 and extending forecasts to 2032, this research is designed to equip decision-makers with the foresight required to navigate a landscape defined by electrification, regulatory shifts, and evolving consumption patterns. This article outlines the strategic value of the report, highlighting the macro-economic currents and competitive dynamics that will define the next cycle of growth.
Macro-Economic Trajectory and Growth Vectors
The financial scale of the quadricycles market underscores its increasing relevance. Valued at approximately 1,425.5 million USD in 2020, the market has demonstrated consistent resilience and expansion, reaching an estimated 2,350.0 million USD by 2025. This trajectory signals more than cyclical recovery; it reflects a structural shift in how light mobility is perceived and utilized in urban and semi-urban environments.
Looking forward, the forecast period from 2026 to 2032 projects robust continued expansion. The analysis anticipates the market will surpass 2,827.95 million USD by 2027, eventually climbing toward 3,887.0 million USD by the end of the forecast horizon. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 7.45 percent. For corporate strategy teams, this figure suggests a stable investment environment with clear avenues for revenue generation, provided that product portfolios align with shifting consumer preferences and regulatory mandates.
It is critical to note that this growth is not uniform across all vectors. The transition from internal combustion engine (ICE) models to electric alternatives is reshaping the value chain. By the first half of 2025, over 82 percent of new quadricycles sold in key European markets were fully electric, a statistic that highlights the velocity of this technological pivot. Strategic planning that relies on legacy ICE frameworks risks obsolescence in this rapidly electrifying ecosystem.
The Competitive Landscape: Consolidation and Innovation
The market structure is characterized by a mix of specialized heritage manufacturers and agile electric mobility newcomers. Our detailed analysis indicates a moderately concentrated environment, with the top three companies holding a significant share of the market and the top five managing over half of the total revenue. This concentration suggests that while opportunities exist for smaller players, the path to scale increasingly requires strong partnerships, proprietary technology, or aggressive expansion into underserved segments.
Ligier Group (France) remains a dominant force, particularly with its JS50 internal combustion models and the expanding Myli electric lineup. Their strategic direction was highlighted in late 2024 with the debut of redesigned JS50 and Myli 2025 electric models at the Paris Motor Show. Moving into 2025, the group deepened its technological moat through a strategic partnership with Niu Technologies in January, aimed at co-developing a new electric L6/L7 quadricycle platform integrating advanced battery and motor systems. This collaboration positions Ligier to leverage external expertise to accelerate electrification without compromising its core manufacturing capabilities.
Aixam (Polaris) (France) continues to lead in the license-free passenger and commercial space under its Aixam and Mega brands. Their focus on both electric and ICE variants allows them to cover a broad spectrum of user needs, from restricted-license drivers to commercial fleets seeking cost-effective utility solutions.
In the utility and commercial domain, Goupil Industrie (France), also part of the Polaris group, has carved out a specialized niche. In March 2025, the company secured a major contract to supply 1,000 electric quadricycles to the City of Paris for municipal fleet use. This win validates the commercial viability of electric L7e vehicles for municipal logistics and points toward a growing public-sector demand driver.
Tazzari EV (Italy) represents the agility of the EV specialist. Offering models like the ZEROMAX 45 (L6e) and ZEROMAX 80 and Zero 4 (L7e), Tazzari targets urban commuting and adventure variants, appealing to consumers seeking personalization and off-road capability within the light quadricycle classification.
Stellantis (France/Italy), through its Citroën, Fiat, and Opel brands, has brought significant mainstream attention to the L6e segment with urban micro-mobility icons like the Citroën Ami and Fiat Topolino. These mass-market offerings help normalize electric quadricycles for broader consumer adoption. Similarly, Renault (Mobilize) is pushing the L7e boundary with models like the Mobilize Duo and Bento, designed explicitly for shared and commercial urban use, aligning with the growing shared mobility infrastructure.
Piaggio (Italy) has shown aggressive intent to expand its footprint. In May 2025, the company completed the acquisition of Quadro Vehicles' European operations to expand its L6/L7 electrification portfolio. This acquisition signals a consolidation trend among larger industrial groups seeking to secure proprietary technology and market access in the light vehicle segment.
Other notable players such as Automobiles Chatenet (France) with its high-end CH46 and electric CH46E variants, Casalini Srl (Italy) with its established Sulky and M10 series, and Piaggio 's broader L-category involvement, contribute to a diverse ecosystem where differentiation is driven by brand prestige, utility focus, and electrification strategy.
Regulatory and Structural Dynamics
The operating environment for L6 and L7 quadricycles is heavily defined by European regulatory frameworks. EU Regulation (EU) No 168/2013 establishes the technical boundaries for these vehicles. L6e quadricycles are capped at a maximum unladen mass of 425 kg (excluding batteries), a speed limit of 45 km/h, and a power output of 6 kW. L7e heavy quadricycles allow for a higher mass limit (up to 450 kg or 600 kg depending on configuration), a power cap of 15 kW, and speeds up to 90 km/h.
L7 and L6 Quadricycles Market
These technical definitions directly influence market segmentation and user adoption. Licensing regulations further shape the consumer base. In many EU countries, L6e quadricycles can typically be driven with an AM license or a standard Category B car license from ages 14 to 16. L7e vehicles often require a B1 license. This regulatory accessibility makes L6 models particularly attractive for younger demographics or those seeking license-free mobility, while L7 models appeal to users requiring higher performance or cargo capacity who meet the necessary licensing criteria.
The regulatory push toward electrification is also a critical dynamic. As low-emission zones expand and urban access restrictions tighten, the operational flexibility of zero-emission quadricycles becomes a significant competitive advantage. The surge in electric registrations, such as the +34 percent growth in L6 registrations in Italy in 2024, demonstrates how regulatory tailwinds and consumer environmental awareness are converging to drive adoption.
Segmentation and Application Nuances
Understanding where value is generated requires a nuanced look at segmentation. The market is divided into L6 light quadricycles and L7 heavy quadricycles. Current analysis shows that L6 models account for a substantial portion of the revenue mix, valued at approximately 1,408.76 million USD, while L7 models contribute around 941.24 million USD. However, the relative weight of these segments can shift rapidly based on electrification trends, as L7 platforms are often favored for commercial utility applications that require greater payload and range.
Application-wise, the market splits between Personal Use and Commercial Use. Personal use currently represents a significant share of the market, valued at 1,508.71 million USD, driven by individual commuters, second-car households, and recreational users. Commercial use, valued at 841.29 million USD, is a high-growth area fueled by last-mile delivery, municipal fleets, and industrial site mobility. The commercial segment is particularly sensitive to total cost of ownership (TCO) calculations, where electric quadricycles often offer compelling advantages in operating costs and maintenance over ICE equivalents.
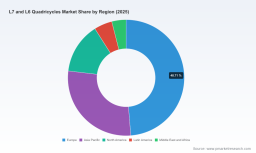
Geographic distribution also plays a role in shaping strategy. Europe remains the dominant revenue generator for this market, reflecting the deep cultural integration of quadricycles and the supportive regulatory environment. Asia Pacific and North America present distinct opportunities and challenges, ranging from different regulatory classifications to varying consumer acceptance of micro-mobility. Our report delves into these regional nuances, analyzing how market maturity and local dynamics influence entry strategies and growth potential.
Operational Intelligence Within the Report
PW Consulting's L7 and L6 Quadricycles Market research is structured to move beyond high-level statistics and provide actionable intelligence for strategic planning. The report includes a detailed examination of the following components:
- Historical and Forecast Volume Analysis: A comprehensive review of market performance from 2020 to 2032, allowing stakeholders to benchmark internal performance against broader industry trends and anticipate future demand cycles with greater accuracy.
- Deep-Dive Segmentation: Detailed breakdowns of the L6 and L7 categories, as well as personal versus commercial applications, to identify niche opportunities, assess market saturation, and prioritize R&D or production focus areas.
- Competitive Positioning and Benchmarking: Profiles of key companies including Ligier, Aixam, Tazzari, Goupil, Chatenet, Casalini, Stellantis, Renault, and Piaggio, analyzing their product portfolios, recent strategic moves, and competitive advantages. This section helps identify white space for new entrants or partnership opportunities for incumbents.
- Recent Developments Tracking: A chronology of critical events, such as Ligier's partnership with Niu, Goupil's Paris municipal contract, and Piaggio's acquisition of Quadro Vehicles, providing context on how strategic actions are reshaping the competitive landscape in real-time.
- Regulatory Impact Assessment: An evaluation of how EU regulations and licensing frameworks affect vehicle design, market access, and consumer adoption, enabling compliance planning and risk mitigation.
- Electrification Transition Analysis: Insights into the shift toward electric powertrains, including adoption rates, infrastructure considerations, and the strategic implications for manufacturers transitioning from ICE to EV platforms.
By integrating these elements, the report serves as a decision-support tool for product managers, market strategists, investors, and policy advisors. It answers critical questions about where the market is going, which players are leading the charge, and how regulatory and technological forces will reshape the value chain over the coming years.
Strategic Imperatives for 2026 and Beyond
As the market approaches 2026, stakeholders must align their strategies with the converging forces of electrification, regulatory compliance, and application diversification. The data points to a market that is growing steadily but changing rapidly in composition.
Motorized Quadricycles Market
For manufacturers, the priority is to accelerate the transition to electric platforms while managing the cost and complexity of the shift. Partnerships, such as the one between Ligier and Niu, illustrate one path to mitigating development risks. For commercial fleet operators and urban mobility providers, the focus should be on total cost of ownership and suitability for specific use cases, leveraging the growing body of evidence that electric quadricycles can deliver efficient, compliant urban logistics.
For investors and analysts, the concentration dynamics and recent M&A activity, like Piaggio's acquisition, suggest that value is consolidating around players with strong electrification capabilities, robust distribution networks, and clear alignment with municipal or shared mobility trends. Understanding the nuances of each segment and the strategic moves of key competitors is essential for capitalizing on the market's expansion toward the projected 3,887.0 million USD by 2032.
The L7 and L6 Quadricycles Market is no longer a peripheral curiosity; it is a dynamic sector at the heart of the urban mobility revolution. This latest PW Consulting research provides the depth, context, and foresight necessary to navigate this evolution with confidence. We invite you to explore the full report to access the comprehensive data, detailed segmentation analysis, and strategic recommendations that will inform your decisions in this pivotal market.
For detailed analysis of this topic, please visit the official page: L7 and L6 Quadricycles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com