

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Smart Parcel Lockers Hit $1.2B in 2025, Forecast 12.5% CAGR to $2.7B by 2032
By pmarketresearch, 2026-09-15
Intelligent Parcel Locker Market: Strategic Imperatives for the 2026 Decision-Maker
The global logistics landscape is undergoing a structural recalibration. As e-commerce penetration deepens across commercial and residential verticals, the final mile has emerged as the most cost-intensive and operationally fragile segment of the supply chain. In this environment, intelligent parcel lockers have transitioned from a peripheral convenience to a core infrastructure asset. PW Consulting's latest market research on the Intelligent Parcel Locker Market is engineered to equip executives, investors, and logistics strategists with the analytical rigor required to navigate the 2026-2032 horizon with confidence.
This report is not a static snapshot of historical numbers. It is a forward-looking strategic instrument designed to decode purchasing behavior, competitive maneuvering, regulatory friction, and technology adoption curves. The following analysis outlines the report's architectural logic, previews the macro-economic trajectory, and demonstrates why institutional decision-makers must treat intelligent locker networks as a board-level priority.
Macro Trajectory: Sizing the Inflection Point
Our methodology constructs a granular baseline that traces the market's evolution from 2020 through 2025, followed by a disciplined forecast window extending to 2032. Over the historical observation period, the global market has progressed from approximately 800 million USD in 2020 to a 2025 baseline of 1.2 billion USD. This 50 percent cumulative expansion reflects sustained capital deployment by postal operators, third-party logistics providers, property developers, and retail integrators seeking to offload delivery friction from human handlers to automated, contactless nodes.
The forward-looking projection indicates that the addressable revenue pool will expand to roughly 1.38 billion USD in 2026 and continue compounding at a rate of 12.5 percent annually. By 2032, the market is positioned to exceed 2.7 billion USD. These figures are anchored in observable adoption signals, including carrier-neutral network growth, real estate integration mandates, and the acceleration of self-service pickup models across urban and suburban geographies. The sustained double-digit trajectory underscores a structural shift rather than a cyclical bump. Enterprises that internalize this growth vector early will secure first-mover advantages in site leasing, carrier partnerships, and software-driven locker fleet orchestration.
Strategic Report Architecture: What Decision-Makers Will Find Inside
Market intelligence loses its value when it cannot be translated into action. PW Consulting's research is organized around operational deployment rather than abstract theorization. The report dissects the intelligent locker ecosystem across multiple analytical dimensions, providing readers with a replicable framework for capital allocation, vendor selection, and geographic prioritization.
The segmentation architecture maps the installed base and revenue attribution across product typologies that reflect distinct use cases and buyer profiles. Modular locker configurations, postal-grade automated nodes, temperature-controlled units engineered for fresh food and specialized logistics, and multi-function laundry or extended-service lockers each present unique total-cost-of-ownership profiles, site requirements, and user-experience considerations. The report isolates the demand characteristics, operational trade-offs, and growth catalysts for each category, enabling category managers to align procurement with specific delivery pain points rather than adopting a one-size-fits-all hardware posture.
Application-level analysis grounds the hardware discussion in real-world deployment environments. High-traffic commercial buildings, residential condos and apartment complexes, retail buy-online-pick-up-in-store augmented ecosystems, academic campuses, and specialty or emerging use cases all exhibit divergent throughput requirements, access-control protocols, and integration complexity. By separating these verticals, the research equips stakeholders with application-specific benchmarks for utilization rates, peak-load management, and return on infrastructure spend.
Geographic coverage is structured to illuminate regional market maturity, regulatory climates, and infrastructure readiness without reducing the narrative to superficial regional summaries. Readers will encounter a comparative lens that connects urban density, last-mile labor economics, carrier network topology, and municipal permitting environments to localized deployment feasibility. This regional framing is critical for multinational operators evaluating where to concentrate capital or how to sequence market entry across diverse regulatory jurisdictions.
Beyond segmentation, the report delivers an actionable competitive intelligence module, a dynamics and regulatory environment scan, and an industry-context synthesis that directly informs operational strategy. These components are described in detail below.
Competitive Landscape: The Players Shaping the Next Phase
The intelligent parcel locker market is characterized by a measured degree of concentration, with the top three participants collectively accounting for approximately a quarter of industry revenue and the top five firms representing roughly thirty-five percent. This structure signals a market in which scale advantages, carrier relationships, and software interoperability differentiate credible platforms from commoditized hardware suppliers. The competitive analysis within the report profiles organizations whose strategic moves define the market's trajectory.
Quadient has established itself as a significant force through its carrier-agnostic Parcel Pending network, an extensive footprint of more than eighteen thousand locations, and a management software layer designed to serve residential, retail, and commercial deployments. Its strategic partnerships, including the activation of additional smart locker capacity across the United Kingdom with Evri and the integration of smart locker points into Scotland's rail network with ScotRail for comprehensive commuter access, illustrate how established operators expand reach by embedding locker nodes into mobility infrastructure and alternative pickup ecosystems.
In Europe, OMNIC contributes to the competitive fabric with indoor and outdoor smart locker series engineered for logistics and e-commerce use cases, including IP-rated protection and solar off-grid configurations. These features reflect an industry-wide emphasis on deployment flexibility and resilience in locations where grid power or fixed connectivity may be constrained. KEBA continues to reinforce its position through partnerships with major postal and parcel operators such as bpost and GLS, supplying automated locker infrastructure that aligns with national and cross-border delivery workflows.
ZHILAI operates with a strong product-development orientation, offering smart locker solutions that span solar-powered, Bluetooth-enabled, and refrigerated models tailored to last-mile delivery and self-service pickup. Such diversification indicates a market trend in which hardware differentiation increasingly hinges on energy independence, connectivity protocols, and specialized climate control for perishable or sensitive goods. Postal Source, positioned in the United States, brings intelligent locker solutions focused on secure package management and streamlined operational workflows, reinforcing the demand for integrated security, inventory visibility, and staff efficiency in institutional and commercial settings.
Beyond profiling incumbents, the report tracks the most consequential recent developments that alter competitive dynamics. Acquisition activity, such as the expansion of smart locker network coverage through the consolidation of courier assets, signals an industry in which geographic density and carrier relationships are actively being bought, built, or partnered. Partnership announcements indicate the acceleration of large-scale deployments across national borders, including multi-thousand-unit rollouts in Canada and sustained capacity expansion in European rail and retail contexts. These events are examined not as isolated press releases but as indicators of consolidation strategy, partnership economics, and the pace at which network effects are being monetized.
Dynamics, Regulatory Environment, and Operational Realities
Technology adoption rarely unfolds in a regulatory vacuum. The intelligent parcel locker market is being shaped by intersecting forces that influence cost structures, deployment timelines, data governance, and operational design. The report synthesizes these forces into a coherent dynamics framework so that executives can anticipate friction and align their strategies accordingly.
Cost pressure on last-mile labor remains a persistent catalyst. Automated self-service access reduces dependency on manual handoffs and repetitive residential drop-off attempts, enabling postal and courier providers to reallocate workforce capacity toward higher-value routing and exception handling. The report evaluates how this labor arbitrage intersects with site economics, carrier co-opetition, and shared-network models, helping operators determine whether to build proprietary locker assets, lease neutral space, or participate in multi-carrier common-pool networks.
Regulatory considerations are equally decisive. Across Europe, universal service providers have expanded parcel locker networks in contexts shaped by net neutrality rules and associated policy objectives aimed at lowering delivery costs and improving consumer convenience. At the same time, data sovereignty requirements mandate secure locker-based data handling for parcel tracking and access, creating compliance obligations that affect software architecture, data residency choices, and vendor selection. Spectrum and wireless regulations further enable real-time IoT notifications, supporting contactless operations and remote monitoring at scale. These regulatory threads are mapped to practical implications for system design, localization, and risk management.
Sustainability and infrastructure efficiency provide a third dynamic pillar. Deploying smart parcel lockers supports sustainable urban logistics by reducing the number of physical delivery trips required in high-density cities. This operational efficiency carries implications for carbon accounting, municipal partnerships, and site-selection logic. The report frames sustainability not as a peripheral narrative but as a cost and reputation lever that can tip the calculus in congested urban markets where delivery density and dwell time directly influence profitability.
How the Intelligence Converts Into Decisions
A market study earns its place on an executive dashboard when it clarifies choices. PW Consulting's research translates structural data into decision paths across several common corporate scenarios.
Worldwide Luggage Storage Locker Market
For logistics and delivery operators, the report clarifies where locker networks can compress cost per parcel, reduce failed-delivery penalty cycles, and extend pickup windows without expanding headcount. It outlines how carrier-agnostic and carrier-specific models differ in monetization, utilization, and partnership leverage, allowing operators to evaluate build-versus-partner trade-offs with greater precision.
For real estate owners and property managers, the analysis defines how smart locker installations can enhance tenant retention, support residential and commercial amenities, and generate ancillary revenue or service-differentiation value. Application-level benchmarks help decision-makers estimate throughput, access control integration, and hardware selection aligned with occupancy profiles and delivery volumes.
For retail and omnichannel operators, the report examines how locker infrastructure can reinforce buy-online-pick-up-in-store strategies by offloading counter congestion, extending retrieval windows, and improving the consistency of order fulfillment handoffs. It situates locker deployment within broader omnichannel cost structures and customer-experience expectations, making it possible to compare locker-based pickup against in-store and curbside alternatives on total operating economics.
For investors and technology vendors, the competitive concentration profile and recent partnership and acquisition activity provide signals about where scale is being accumulated, which geographies are attracting deployment momentum, and what product features are becoming table stakes versus differentiators. This perspective supports portfolio decisions, partnership targeting, and product-roadmap prioritization.
Why 2026 Is a Defining Year for Intelligent Locker Strategy
The convergence of sustained double-digit growth, evolving regulatory frameworks, carrier network experimentation, and application-specific hardware diversification places 2026 at a strategic inflection point. Enterprises that continue to treat parcel lockers as ad hoc hardware purchases risk underutilizing assets, misaligning with carrier expectations, and missing opportunities to embed locker nodes into broader mobility and retail ecosystems. Organizations that approach intelligent lockers as managed infrastructure can convert them into demand-smoothing assets, labor-efficiency tools, and customer-experience differentiators.
PW Consulting's Intelligent Parcel Locker Market research is designed to support that shift from intuition-led deployment to evidence-led strategy. The full study provides the deep segmentation detail, competitive event analysis, regulatory mapping, and forward scenarios required to translate macro momentum into operational plans. Readers seeking complete regional revenue distributions, application-level breakdowns, and company-specific investment signals will find the full dataset and interpretive commentary essential to precise planning.
Intelligent Parcel Locker Market
To access the complete report and integrate its findings into your 2026 planning cycle, visit the PW Consulting report page for the Intelligent Parcel Locker Market. The full research package delivers the comprehensive segmentation, competitive intelligence, and scenario analysis necessary to inform capital allocation, vendor selection, and deployment sequencing with confidence.
For detailed analysis of this topic, please visit the official page: Intelligent Parcel Locker Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Superconductor Market Hits $7.65B in 2025, Projects 9.5% CAGR to 2032
By pmarketresearch, 2026-09-15
Unlocking the Next Electrification Frontier: Strategic Intelligence for the 2026 Superconductor Market
The global superconductor market has evolved from a specialized niche of scientific inquiry into a foundational pillar of advanced industrial and medical infrastructure. As we navigate 2026, enterprise leaders across energy, healthcare, transportation, and advanced manufacturing must confront a rapidly shifting landscape where material science breakthroughs intersect with supply chain complexity, regulatory recalibration, and accelerating capital deployment. To address this inflection point, PW Consulting has prepared a comprehensive market intelligence study designed to translate macroeconomic signals into actionable strategic guidance.
Our analysis establishes that the superconductor market reached an estimated value of 7.65 billion USD in 2025, expanding from 4.65 billion USD at the beginning of the last decade. The historical trajectory from 2020 through 2025 reflects resilient accumulation across mature application verticals and early-stage commercialization of next-generation materials. Looking forward, the forecast period from 2026 through 2032 projects a sustained compound annual growth rate of 9.5 percent, positioning the sector to surpass 14 billion USD by the close of the forecast window. This expansion is not merely a function of incremental demand; it represents a structural reorientation of how critical infrastructure manages power density, magnetic field generation, and transmission efficiency. For executive teams, the implication is clear: superconductor technologies are transitioning from optional innovations to strategic necessities.
The purpose of this market study is to equip decision-makers with a rigorous, operationally grounded understanding of where capital should be allocated, which partnership models will mitigate execution risk, and how regulatory shifts will reshape competitive positioning. We have deliberately structured the report as a leadership instrument rather than a static data compilation. While high-level valuation trajectories and aggregate growth parameters provide essential context, the true strategic advantage lies in understanding the mechanics behind the numbers. This preview outlines the analytical architecture of our full publication and demonstrates why access to the complete dossier is critical for evidence-based planning in 2026 and beyond.
Macro Trajectory and the 2026 Decision Window
The decade-long progression from 4.65 billion USD to a projected 8.29 billion USD in 2026 illustrates a market that has successfully navigated early adoption challenges and is now scaling through demonstrable value propositions. Historical data reveals a compound trajectory shaped by incremental commercialization in medical diagnostics, steady modernization of power transmission infrastructure, and the emergence of high-temperature architectures capable of reducing cryogenic dependency. Yet the most consequential period for strategic positioning begins now. The 2026 to 2032 forecast window captures an acceleration phase where material supply chains mature, standard-setting bodies codify performance benchmarks, and large-scale demonstration projects convert technological promise into operational reality.
Forward-looking allocation decisions require more than awareness of aggregate valuation figures. Enterprise leaders must evaluate how regional deployment patterns intersect with localized regulatory frameworks, how type-specific material availability influences project timelines, and which application verticals will capture disproportionate value as cooling infrastructure and manufacturing capacity expand. Our full report dissects these interdependencies without exposing premature sensitivity to noise, allowing strategy teams to calibrate investment horizons against realistic commercialization curves. The aggregate growth perspective is intentionally presented here as a directional signal; the granular mapping of capacity utilization, regional absorption rates, and application-specific margin structures is reserved for the complete intelligence package, ensuring that only stakeholders with direct access can operationalize the findings.
Segmentation Architecture and Hidden Value Drivers
Technology Pathways and Application Synergies
The commercial landscape is broadly organized around two material paradigms, each carrying distinct performance characteristics, cost structures, and deployment considerations. Low-temperature architectures continue to anchor established diagnostic and experimental platforms where cryogenic infrastructure is already institutionalized. High-temperature variants are increasingly favored in grid modernization, advanced magnet systems, and emerging fusion-related applications, where reductions in cooling burden translate directly into operational flexibility and total cost of ownership advantages. Understanding the interplay between these material classes is essential for procurement strategy, capital planning, and technology roadmap alignment.
High Temperature Superconductor Market
- Medical imaging applications remain a central driver of demand, leveraging stable magnetic field generation for diagnostic platforms that are increasingly optimized for patient accessibility and workflow efficiency.
- Energy power grid applications are attracting sustained engineering attention, with superconducting cables, fault current limiters, and busbar systems being evaluated for high-density urban corridors and industrial electrolysis environments.
- Transportation and research applications continue to expand the functional envelope, supporting magnetic confinement concepts, high-field experimental setups, and next-generation mobility prototypes that depend on reliable high-current conduction.
Rather than offering isolated percentage breakdowns, our full study presents a sequenced assessment of how each application vertical interacts with underlying material availability, regional engineering talent, and standards compliance timelines. This integrated view enables technology leaders to anticipate substitution dynamics, identify procurement bottlenecks, and prioritize pilot deployments where early-mover advantages are most defensible.
Geographic and Competitive Concentration Patterns
The market exhibits a moderate degree of supplier concentration, with the top three participants accounting for approximately 35 percent of aggregate revenue and the top five entities representing roughly 45 percent. This concentration profile suggests a landscape where scale advantages in tape manufacturing, specialized winding capabilities, and application-specific system integration create meaningful barriers to entry. At the same time, the remaining market share is distributed across a diverse set of specialized producers, regional fabricators, and application-focused integrators, indicating that partnership ecosystems and supply diversification strategies remain viable pathways for organizations seeking to reduce dependency risk.
Regional revenue distribution, when viewed in aggregate, reflects the imprint of established industrial bases, research infrastructure density, and policy support environments. However, strategic value is rarely captured through regional averages alone. The complete report maps how local permitting cycles, cooling infrastructure readiness, and domestic content expectations influence the effective velocity of project execution. By holding back precise geographic splits and application-level dollar allocations within this preview, we reinforce the necessity of accessing the full dossier to inform location-specific capex decisions, sourcing commitments, and localized partnership negotiations.
Competitive Landscape and Strategic Positioning
Leadership in the superconductor sector is not defined solely by manufacturing footprint; it is increasingly determined by the ability to secure long-lead material supply, align product roadmaps with emerging application requirements, and respond rapidly to shifting regulatory and standards environments. The competitive field includes organizations that have built specialized capabilities across wire production, magnet assembly, cable integration, and system-level deployment. American Superconductor Corporation continues to advance HTS wire and power system solutions tailored for energy applications. ASG Superconductors S.p.A. has expanded its portfolio around superconducting cables, wires, and magnets, with recent momentum in open MRI platforms and commercial distribution agreements that extend its regional reach. Faraday Factory Japan remains a central figure in high-temperature superconductor tape production, supporting both magnet coil and power system applications at industrial scale. Cutting Edge Superconductors, Inc. has focused on MgB2-based conductors and alternative materials targeting cryogen-free imaging and specialized ambient-temperature conductor concepts. MetOx International operates a major North American HTS wire production facility and supplies superconducting tapes for grid and cable deployments. Advanced Conductor Technologies has developed CORC HTS wire and cable architectures designed for demanding magnet and power applications.
Superconductor Market
Recent execution signals illustrate how competitive advantage is being forged through supply chain reliability and application-specific commercialization. In 2025 and 2026, Faraday Factory Japan moved high-temperature superconductor tape into fusion prototype magnet coils and into large-scale industrial busbar projects, demonstrating the transition from laboratory-scale promise to utility-grade deployment. ASG Superconductors S.p.A. advanced its medical imaging presence through a new open MRI system launch and subsequent distribution agreements that extend commercial availability into additional territories. These developments underscore a broader market reality: winning strategies will depend on the ability to synchronize material throughput with defined project pipelines, rather than relying on speculative demand narratives.
Our full competitive analysis goes beyond corporate profiling. It evaluates partnership readiness, manufacturing scalability constraints, intellectual property positioning, and the strategic implications of recent supply announcements for future procurement calendars. The objective is to help enterprise buyers and investors distinguish between temporary capacity tightness and durable competitive moats.
Regulatory, Standards, and Supply Chain Dynamics
Policy and Standards Inflection Points
The 2026 operating environment is being reshaped by a cluster of policy and standardization actions that carry direct implications for superconductor market participants. In January 2026, the U.S. government imposed a 25 percent ad valorem duty on certain advanced computing chips and derivatives that do not support domestic manufacturing buildout. While this measure is focused on advanced computing components, its ripple effects extend into the broader advanced technology supply chain, particularly for organizations that rely on tightly integrated electronic control, simulation, and cryogenic management systems. In May 2026, the European Committee for Standardization published SIST EN IEC 61788-15:2026, establishing formal requirements for superconducting film properties and testing methods. This standardization milestone is likely to increase comparability across suppliers, accelerate qualification cycles for large infrastructure projects, and elevate the importance of documented process control within manufacturing operations.
On the support side, the Department of Commerce announced letters of intent with nine companies for two billion USD to accelerate U.S. leadership in quantum computing, with explicit support for superconducting qubit and magnet development. This funding signal reinforces a policy environment that views superconducting enabling technologies as strategic assets rather than purely commercial commodities. For enterprises operating across energy, medical, and scientific platforms, these dynamics create both opportunity and complexity: funding pathways and standards alignment can shorten time-to-value, while trade measures and qualification requirements can alter cost structures and sourcing geography preferences.
Supply Constraints and Execution Risk
Beyond policy, the most persistent operational challenge in the sector remains supply chain friction. Industry market data indicates that high-temperature superconductor adoption in fusion and grid projects is constrained by bottlenecks in REBCO tape production and helium-free cooling infrastructure. This constraint is not theoretical; it directly affects project sequencing, pilot scale-up timelines, and the economics of first-of-kind deployments. Organizations that fail to incorporate material throughput assumptions into their planning models risk underestimating lead times, overcommitting to demonstration schedules, or exposing themselves to single-source dependency.
- Tape production capacity remains a critical gating factor for large-scale grid and fusion-adjacent programs, requiring long-lead procurement commitments and close coordination between material suppliers and system integrators.
- Helium-free cooling infrastructure represents a parallel bottleneck, influencing the feasibility of cryogen-light deployments and shaping the commercial attractiveness of next-generation magnet and imaging platforms.
- Standards implementation, particularly around film property testing and performance verification, will likely increase supplier qualification burdens while also providing a clearer framework for risk allocation in multi-party projects.
Our full report translates these dynamics into scenario-based projections, helping strategy teams model how different supply expansion pathways, regulatory outcomes, and standards adoption curves could alter project economics. By withholding the precise scenario parameters and sensitivity ranges in this preview, we preserve the strategic exclusivity of the complete analysis for clients who require defensible, internally auditable planning frameworks.
How the Full Report Translates Intelligence into Execution
The PW Consulting Superconductor Market research study is built for decision-makers who need more than directional optimism. It is structured to provide a comprehensive, evidence-backed foundation for capital allocation, procurement strategy, partnership selection, and technology roadmap alignment. Key components of the full publication include:
- An integrated market sizing framework that connects historical performance with forecast drivers, enabling leadership to test assumptions against multiple commercialization pathways.
- Segment-level analysis that maps material types, application requirements, and deployment contexts to better understand where performance advantages translate into commercial advantage.
- Competitive profiling that evaluates manufacturer capabilities, supply commitments, product launch cadence, and distribution strategies, with emphasis on operational resilience rather than headline announcements alone.
- Regulatory and standards impact assessment that quantifies likely effects on qualification timelines, sourcing flexibility, and project cost structures across major markets.
- Supply chain and bottleneck analysis that identifies where capacity constraints, cooling infrastructure readiness, and material availability are most likely to influence execution risk.
- Strategic scenario guidance that supports internal planning discussions around investment pacing, vendor diversification, and go-to-market sequencing.
To maintain analytical rigor and protect client-sensitive insight, detailed regional revenue splits, application-level dollar allocations, and supplier-level capacity assumptions are presented in full only within the complete study. This deliberate design ensures that the report remains a practical internal tool for strategy formulation, procurement negotiation, and executive alignment, rather than a publicly diluted summary.
Conclusion: Strategic Imperatives for 2026 and Beyond
The superconductor market is entering a phase where scale, standardization, and supply chain maturity will determine which organizations capture durable advantage. The aggregate growth trajectory toward a 9.5 percent CAGR through 2032 signals a sector with substantial momentum, but momentum alone does not guarantee execution success. Enterprise teams must navigate concentration dynamics, evolving trade measures, new testing standards, and persistent material supply bottlenecks while simultaneously aligning investment decisions with the application verticals most likely to deliver near-term commercial returns.
This preview has outlined the strategic contours of our full market study and demonstrated why high-level figures are only the starting point for serious planning. The complete PW Consulting Superconductor Market report delivers the depth, segmentation clarity, competitive intelligence, and scenario-based guidance required to turn market potential into executable strategy. For leaders seeking to position their organizations ahead of the next wave of infrastructure modernization, medical platform innovation, and advanced magnet deployment, the full dossier provides the intelligence architecture necessary to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Superconductor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Bone Cement Market Hits $1.23 Billion in 2025, 5.8% CAGR to 2032
By pmarketresearch, 2026-09-15
Navigating the Bone Cement Market: Strategic Imperatives for 2026 and Beyond
Executive Overview
The global bone cement market stands at a critical inflection point as the industry moves through 2026. Characterized by steady growth, evolving regulatory frameworks, and shifting supply chain dynamics, this sector demands precise strategic planning from medical device manufacturers, healthcare providers, and investors alike. Our latest comprehensive market research provides an authoritative guide to navigating these complexities, offering the actionable intelligence required to capitalize on emerging opportunities while mitigating inherent risks. With a projected revenue trajectory that underscores the enduring clinical reliance on cemented fixation techniques, understanding the nuanced dynamics of this landscape is no longer optional—it is essential for sustainable competitive advantage.
From 2020 through the base year of 2025, the market demonstrated consistent expansion, reflecting the aging global population and the rising prevalence of osteoporotic fractures and degenerative joint diseases. The upward trend has continued into the forecast period spanning 2026 to 2032. Market valuation is expected to grow from approximately 1.26 billion USD in 2026 to over 1.82 billion USD by 2032, reflecting a Compound Annual Growth Rate (CAGR) of 5.8 percent. This growth is not merely a function of volume but is driven by technological advancements, material science innovations, and the strategic adaptation of key industry players to regulatory shifts such as the European Union Medical Device Regulation and evolving reimbursement models in North America.
Market Context and Historical Trajectory
The historical data from 2020 to 2025 establishes a robust baseline for understanding current market momentum. Revenue figures over this period illustrate a resilient demand profile that has withstood broader macroeconomic fluctuations. The transition from the historical analysis into the 2026-2032 forecast period reveals a market that is maturing yet still capable of generating meaningful increments in value. For strategic decision-makers, this trajectory signals a stable environment for investment, provided that supply chain vulnerabilities and regional regulatory divergences are adequately addressed. The consistency in growth suggests that demand drivers are structural rather than cyclical, rooted in the fundamental clinical requirements of orthopedic and spinal procedures.
Looking forward, the forecast period through 2032 indicates sustained expansion. The market is projected to reach significant valuation milestones by the end of the decade, offering a clear horizon for capacity planning and product development roadmaps. Companies that align their R&D pipelines and commercial strategies with this growth curve will be best positioned to capture market share. However, realizing this growth requires navigating a landscape where supply chain reliability has recently become a focal point of concern, as evidenced by recent production disruptions that highlight the fragility of even well-established manufacturing networks.
Competitive Landscape and Strategic Positioning
The bone cement market is characterized by a concentrated yet competitive environment where major multinational corporations coexist with specialized niche players. The top three companies account for nearly 50 percent of the market share, while the top five firms hold over 68 percent. This concentration underscores the importance of brand recognition, regulatory compliance, and established distribution channels. Understanding the specific strengths and vulnerabilities of key competitors is vital for formulating effective market entry or expansion strategies.
Heraeus Medical remains a pivotal player, particularly known for its Palacos, COPAL, and Refobacin high-viscosity antibiotic-loaded PMMA bone cements used in orthopedic arthroplasty and trauma fixation. Their product suite is integral to infection management protocols. However, recent events have introduced volatility; a packaging fault at their main production site caused a temporary halt in pouch bone cement production in early 2026. While global releases resumed by the end of June 2026, this disruption rippled through supply chains, notably impacting NHS England operations where over 1,000 weekly procedures were at risk.
In response to such disruptions, competitors like Zimmer Biomet and DePuy Synthes have stepped in to secure alternative supplies. Zimmer Biomet, with its Biomet Bone Cement R and Refobacin Bone Cement R, and Johnson & Johnson's DePuy Synthes, offering SMARTSET and DePuy CMW bone cements for hip and knee arthroplasty, have leveraged such situations to reinforce their reliability as backup providers. Stryker continues to dominate specific segments with KYPHON and Simplex P bone cements, particularly in vertebroplasty and orthopedic fixation, while maintaining a strong presence in spinal augmentation through Medtronic Sofamor Danek's KYPHON HV-R and ACTIVOS offerings.
Regional specialists and niche innovators are also reshaping the landscape. Tecres S.p.A. strengthened its orthopedic infection control portfolio in September 2025 through the acquisition of majority assets from Next Science LTD, signaling a strategic push to consolidate technology around Cemex and other radiopaque PMMA bone cements. Similarly, Biocomposites accelerated the UK market launch of its SYNICEM high- and low-viscosity gentamicin-loaded bone cement variants in early 2026 to help alleviate national supply crises, demonstrating agile responsiveness to market needs. Companies like Arthrex, Inc., with their G3 40 and G3A 40 radiopaque and gentamicin-loaded PMMA bone cements, and Amber Implants, utilizing Teknimed F20 PMMA bone cement in combination with their VCFix Spinal System, illustrate the diversification occurring in the application space, particularly in joint and shoulder procedures and vertebral fracture treatment.
Regulatory milestones continue to dictate the pace of competition. For instance, the FDA 510(k) clearance for Teknimed F20 bone cement in May 2025 and the MDR certification for Heraeus Medical COPAL G+V Bone Cement in February 2025 highlight the rigorous compliance pathways that define market access. Furthermore, reimbursement policies are evolving to support advanced technologies; the CMS approval of CERAMENT G for New Technology Add-On Payment effective August 2025 provides up to 5,687.50 USD additional payment for open fractures, influencing procurement decisions and product adoption rates.
Bone Cement Market
Operational Deep Dive and Product Intelligence
To truly leverage the growth potential of the bone cement market, stakeholders require granular insights beyond top-line figures. Our report provides an exhaustive examination of product specifications, delivery systems, and viscosity classifications that differentiate offerings in the eyes of surgeons and procurement officers. The distinction between high-viscosity and low-viscosity formulations, for example, is not merely technical but impacts surgical workflow, cement penetration, and ultimately clinical outcomes. Companies must understand where their products sit within these categories and how competitor innovations are shifting the standard of care.
The research delves into the lifecycle management strategies employed by leading manufacturers, analyzing how portfolio expansions and acquisitions are used to secure intellectual property and broaden indication sets. The recent acquisition activity, such as Tecres's move to acquire Next Science LTD assets, exemplifies the industry's focus on strengthening infection control capabilities. Additionally, the report assesses the impact of delivery system innovations, which are increasingly bundled with bone cement products to enhance usability and reduce handling errors. Understanding these operational nuances is critical for companies aiming to differentiate themselves in a market where clinical efficacy is often assumed and service reliability becomes the key differentiator.
Supply chain resilience is another core component of the operational analysis. The Heraeus Medical production halt serves as a case study for the broader industry, emphasizing the need for diversified manufacturing sites and robust inventory management protocols. The report evaluates how major stakeholders are restructuring their supply networks to prevent similar disruptions, offering lessons on risk mitigation that are applicable across the orthopedic device sector. For procurement leaders in hospitals and health systems, this intelligence is vital for ensuring continuity of care during periods of market stress.
Strategic Imperatives for 2026 Decision-Making
As organizations plan their moves for the remainder of 2026 and the subsequent forecast period, several strategic imperatives emerge from the data. First, maintaining supply chain agility is paramount. The recent supply disruption involving Heraeus Medical and the subsequent pivot by NHS England to secure alternatives from Zimmer Biomet and others illustrates that reliability is as valuable as product performance. Companies must invest in redundancy and transparent communication channels to preserve trust with healthcare providers.
Second, regulatory compliance and reimbursement alignment must be integrated into product development from the outset. With the MDR certification processes in Europe and evolving FDA clearances in the United States, navigating the regulatory landscape requires specialized expertise. The positive reimbursement decision for CERAMENT G demonstrates that innovative products with clear clinical value propositions can secure favorable payment pathways, incentivizing investment in advanced antibiotic-loaded cements and bioactive materials.
Bone Cement for Spine Market
Third, strategic partnerships and acquisitions offer viable pathways for growth, particularly for players seeking to expand their technological capabilities without building them from scratch. The activity seen in late 2025 and early 2026 suggests a consolidation trend where larger entities absorb specialized technologies to enhance their portfolios. Smaller innovators may find opportunities in licensing agreements or targeted partnerships that allow them to scale their solutions while leveraging the distribution networks of established leaders.
Finally, regional expansion strategies must be data-driven. While North America and Europe remain dominant revenue centers, the Asia Pacific region presents significant growth potential driven by increasing healthcare expenditure and rising surgical volumes. However, entering these markets requires an understanding of local reimbursement environments, regulatory requirements, and competitive dynamics. Our report provides the localized context necessary to formulate entry strategies that avoid common pitfalls and maximize return on investment.
Conclusion and Call to Action
The bone cement market offers a compelling landscape for strategic engagement in 2026 and beyond. With a clear growth trajectory, established clinical demand, and evolving technological frontiers, the opportunities for value creation are substantial. However, realizing these opportunities requires more than general industry knowledge; it demands precise, actionable intelligence that accounts for the complexities of supply chains, regulatory environments, and competitive maneuvering. The insights provided in this research are designed to equip decision-makers with the clarity needed to navigate this dynamic market confidently.
To access the full depth of this analysis, including detailed segment forecasts, comprehensive competitive benchmarking, and proprietary supply chain assessments, we invite you to review the complete Bone Cement Market research report. The full document contains the specific data points and strategic frameworks necessary to finalize your 2026 planning and secure a competitive edge in the coming years.
For detailed analysis of this topic, please visit the official page: Bone Cement Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting VTS Report: Market Hits $267M in 2025, Projected $373M by 2032 at 4.9% CAGR
By pmarketresearch, 2026-09-15
Navigating the Currents: Strategic Intelligence for the Vessel Traffic Services Market 2026–2032
The global maritime ecosystem is undergoing a structural transformation. As vessel density increases in crowded waterways and environmental regulations tighten, the operational backbone of port safety and efficiency is being recalibrated around sophisticated digital oversight. Vessel Traffic Services (VTS) have evolved from optional advisory tools into critical infrastructure for maritime domain awareness. For executives operating in shipping, port authorities, defense logistics, and maritime technology, understanding the trajectory of this market is no longer a niche concern—it is a prerequisite for capital allocation and risk management.
Vessel Traffic Services (VTS) Market
PW Consulting’s latest deep-dive research into the Vessel Traffic Services market offers a comprehensive lens on this evolution. This report is designed not merely as a statistical archive, but as a decision-support instrument for the 2026 planning cycle. By synthesizing historical performance data with forward-looking demand indicators, the study provides a clear view of where value is being created and how competitive pressures are reshaping vendor landscapes.
Market Trajectory and Growth Dynamics
The economic footprint of the VTS sector reflects a steady, resilient expansion path. Between 2020 and 2025, global revenue climbed from approximately 205.0 million USD to 267.0 million USD, signaling a consistent demand curve even through periods of broader supply chain volatility. Looking ahead, the forecast period from 2026 to 2032 projects continued upward momentum, with market value anticipated to reach 373.0 million USD by the end of the decade. This growth translates to a compound annual growth rate of 4.9 percent, a figure that underscores the sector’s maturity while highlighting its capacity for incremental innovation-driven expansion.
For strategy teams, this trajectory carries several implications. First, it indicates that VTS procurement is increasingly tied to long-term infrastructure roadmaps rather than reactive safety upgrades. Second, the steady CAGR suggests that while the market is not experiencing speculative hyper-growth, it offers predictable revenue streams for established players and stable entry points for those looking to modernize legacy systems. The revenue progression also hints at shifting procurement cycles, where integration capabilities and interoperability are becoming as valuable as hardware performance.
Structural Segmentation and Demand Drivers
Beneath the aggregate numbers lies a nuanced demand architecture. The market is shaped by distinct operational contexts, ranging from high-density harbor environments to extended coastal surveillance corridors. Procurement decisions are increasingly influenced by the specific regulatory and operational pressures facing different maritime zones. In port-centric environments, the priority remains collision avoidance, berth scheduling optimization, and real-time situational awareness for inbound and outbound traffic. Coastal and open-water applications, meanwhile, demand broader coverage, radar integration, and the ability to coordinate across multiple jurisdictional boundaries.
The technology mix deployed to serve these needs continues to diversify. Solutions are generally categorized into integrated navigation and surveillance systems, traffic operation suites, and specialized adjunct platforms. Each category addresses different layers of the maritime oversight stack, from raw sensor data fusion to the decision-support interfaces used by VTS operators. As ports and coastal agencies modernize, we are seeing a clear preference for platforms that can ingest heterogeneous data sources—AIS, radar, meteorological feeds, and even drone or UAV inputs—into a unified operational picture. This integration requirement is reshaping vendor selection criteria and pushing traditional hardware suppliers to demonstrate software-defined agility.
Regional dynamics further complicate the demand picture. Mature maritime markets are characterized by legacy system upgrade cycles and stringent compliance mandates, while emerging hubs are often entering the VTS space as part of broader port expansion projects. This divergence means that solution providers must calibrate their go-to-market strategies to the specific lifecycle stage of infrastructure in each geography. The report dissects these regional nuances without relying on simplistic geographic splits, instead focusing on the operational triggers that drive procurement timing and budget allocation.
Competitive Landscape: Positioning and Strategic Moves
The VTS vendor ecosystem is defined by a mix of specialized maritime technology firms, large defense and industrial conglomerates, and systems integrators with deep port authority relationships. Market concentration remains moderate, with the top three and top five players holding specific portions of the revenue base, indicating that while brand recognition and installed base matter, there is room for differentiation through niche capabilities and regional partnerships.
Several leading organizations illustrate the diversity of strategic positioning in this space. Signalis, headquartered in Bezons, France, focuses on integrated VTS platforms tailored for harbor and naval base safety and security, emphasizing the intersection of commercial and defense-grade requirements. Kongsberg Gruppen, based in Norway, delivers VTS and coastal surveillance solutions through its Kongsberg Norcontrol division, serving ports and maritime authorities with a reputation for robust maritime automation. Indra Sistemas, from Spain, offers comprehensive VTS and maritime traffic management systems targeting port authorities and coastal administrations, with a strong footprint in government-linked procurement. Saab, in Sweden, provides advanced VTS and Vessel Traffic Management Information Systems for ports, waterways, and coastal regions, leveraging its broader defense and sensing heritage. Wärtsilä, based in Finland, supplies Navi-Harbour Web VTS and VTS simulation solutions that address both live traffic management and operator training scenarios. Tokyo Keiki, from Japan, manufactures VTS and coastal surveillance radar systems, including solid-state radar series, anchoring its strategy in detection hardware and sensor reliability. Frequentis, headquartered in Austria, delivers smartVTS and integrated vessel traffic management solutions for maritime authorities, with an emphasis on communication and command-center integration.
Maritime Intercom Market
Recent corporate developments signal an active consolidation and capability-building phase. In October 2025, Kongsberg announced plans to spin off its Maritime unit as an independent company, with a stock exchange listing targeted for the first half of 2026. This move may unlock focused investment in maritime technologies while allowing the parent organization to streamline its portfolio. Earlier in the year, in February 2025, Indra showcased advanced radar technology at IDEX 2025 and signed a partnership to bolster VTS capabilities, illustrating how sensor innovation and alliances are being used to strengthen competitive positioning. On the consultancy and systems integration side, Arup was appointed by the Hong Kong Marine Department in October 2025 for a comprehensive consultancy to modernize the city’s Vessel Traffic Services system. This engagement highlights the growing role of design and advisory firms in bridging operational requirements with large-scale technology upgrades, particularly in major Asian hub ports.
For procurement leaders and investors, these moves are not merely corporate news—they are indicators of where capability will concentrate in the near term. Spin-offs, partnerships, and major modernization contracts often precede shifts in pricing models, service-level expectations, and product roadmaps. The report tracks these signals and maps them against commercial implications, helping readers anticipate how vendor strategies may affect total cost of ownership and integration risk.
Regulatory and Operational Context
No analysis of the VTS market is complete without grounding it in the regulatory frameworks that shape procurement mandates. International guidelines continue to elevate the role of information services, including the provision of hydro-meteo data and route planning support for high-traffic and environmentally sensitive areas. These requirements drive demand for platforms that can not only monitor traffic but also provide proactive advisory functions.
Standardization efforts further influence market dynamics. The IALA VTS Manual provides recommendations for operator recruitment, qualifications, and training, ensuring a baseline of consistency across global operations. This has downstream effects on product design, as vendors must consider human-machine interface ergonomics, simulation-based training modules, and auditability features. In the United States, the USCG operates multiple Vessel Traffic Centers that implement mandatory reporting for vessel traffic in high-density waterways, creating a regulatory environment that favors systems capable of handling compulsory data exchange and enforcement workflows. Meanwhile, UNECE guidelines on inland vessel traffic services establish harmonized standards for inland waterways across member states, extending the VTS concept beyond coastal and port domains into river and canal networks. These regulatory threads collectively expand the addressable operational scope for VTS providers and reinforce the need for adaptable, standards-compliant architectures.
What This Research Delivers for 2026 Decision-Makers
This market study is structured to translate macroeconomic trends into actionable strategic intelligence. Beyond the headline growth figures, the report examines the operational and commercial factors that will shape procurement behavior over the next several years. It provides a detailed view of solution categories, deployment contexts, and the performance criteria that distinguish winning proposals in competitive tenders. The analysis also evaluates how vendor relationships, service models, and integration requirements affect lifecycle costs, an area often underappreciated in early-stage planning.
The research includes a rigorous competitive profiling section that goes beyond corporate descriptions to assess positioning, capability emphasis, and recent market activity. By connecting corporate developments—such as spin-offs, partnerships, and major consultancy awards—to potential shifts in product strategy and regional focus, the report helps readers anticipate supplier behavior rather than simply react to it. This is particularly valuable for organizations evaluating multi-year contracts, considering vendor diversification, or planning internal system upgrades in alignment with regulatory timelines.
In addition, the study contextualizes the market within the broader maritime technology landscape, highlighting where VTS intersects with port community systems, autonomous vessel preparation, cybersecurity requirements, and data-sharing initiatives. These adjacencies are increasingly relevant as maritime authorities seek to avoid fragmented deployments and instead build coherent digital infrastructures. The report identifies the integration pressure points that matter most and frames them in terms of risk mitigation and operational resilience.
Using the Intelligence: Strategic Imperatives for the Year Ahead
For executives preparing 2026 strategies, the VTS market presents both opportunity and complexity. The growth trajectory is solid, but the value capture is uneven. Success will depend on recognizing where demand is being driven by regulatory mandate versus operational efficiency, and where vendors are differentiating through integration, training, and lifecycle support rather than raw sensor performance alone. Organizations that align their procurement cycles with the modernization rhythm of key ports and coastal agencies will be better positioned to secure favorable terms and reduce deployment risk.
The report is designed to support that alignment. It offers a structured view of market size evolution, demand segmentation logic, competitive dynamics, and regulatory influence—without obscuring the practical considerations that determine project outcomes. By focusing on the factors that shape purchasing behavior and vendor strategy, the research equips stakeholders to make informed choices about technology selection, partnership structures, and investment timing.
To access the full segmentation detail, company profiles, regional demand analysis, and forward forecasts that underpin these insights, we invite you to explore the complete PW Consulting Vessel Traffic Services market research. The complete edition provides the granular intelligence needed to translate market direction into concrete planning decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Vessel Traffic Services (VTS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: ACF Market Hits $2,265M in 2025, Poised for $3,815.61M by 2032 (7.85% CAGR)
By pmarketresearch, 2026-09-15
Anisotropic Conductive Film Market: Strategic Intelligence for 2026 and Beyond
Decoding the Next Phase of Interconnection Technology
In the fast-evolving landscape of electronic materials, few sectors offer as much strategic nuance as the anisotropic conductive film (ACF) industry. As we navigate through 2026, supply chain leaders, procurement strategists, and R&D directors are facing a critical juncture where material selection directly impacts product reliability, cost structures, and long-term scalability. PW Consulting has just finalized a comprehensive market study designed to empower stakeholders with actionable intelligence.
This report is not merely a collection of historical figures. It is a forward-looking analytical tool built on rigorous primary research and validated with market modeling. The core objective is to illuminate the path ahead, helping enterprises allocate resources effectively amidst shifting technological paradigms.
Market Trajectory: From Recovery to Sustained Expansion
The macroeconomic backdrop for this sector reveals a robust upward trajectory. Following a period of consolidation during the early 2020s, the market has demonstrated resilient growth momentum. Between 2020 and 2025, the industry navigated supply chain disruptions and raw material volatility, ultimately stabilizing into a growth phase characterized by steady revenue expansion. Our analysis projects that this momentum will accelerate through the forecast period, driven by the widening adoption of high-density interconnects in advanced consumer electronics and automotive systems.
Looking at the broader picture, the global market revenue is expected to climb significantly from its recent base levels, reaching new milestones by the end of the decade. This expansion is underpinned by a compound annual growth rate that signals healthy demand absorption across multiple verticals. The data indicates that 2026 serves as a pivotal launchpad, setting the stage for substantial value generation as we approach 2032.
Core Drivers: The Impact of Micro-LED and Automotive Electronics
The narrative of growth in 2026 is heavily influenced by specific technological inflection points. The rise of micro-LED displays represents one of the most transformative forces reshaping the demand landscape for ACF products. As display manufacturers push for higher brightness, better energy efficiency, and miniature form factors, the requirement for precise, reliable interconnection solutions becomes non-negotiable. Particle-arrayed ACF technologies are increasingly recognized as essential enablers in these contexts, ensuring both stable electrical conductivity and robust insulation properties.
Simultaneously, the automotive sector continues to electrify and digitize, creating complex needs for film-on-board solutions that can withstand harsh operating environments. Compliance with stringent quality standards, such as IATF16949, is no longer optional but a baseline requirement for suppliers targeting this lucrative segment. Additionally, the ongoing miniaturization of semiconductor packages and the proliferation of flexible printed circuits are sustaining demand for high-performance adhesive interlayers that bridge the gap between components and substrates.
Supply Chain Dynamics and Material Considerations
Understanding the cost structure is vital for strategic planning. ACF manufacturing relies on a blend of conductive materials, including gold and nickel, which introduces sensitivity to commodity price fluctuations. Strategic procurement teams must monitor these input costs and assess how bulk purchasing agreements or alternative material formulations might mitigate risk. Furthermore, the industry is witnessing a push towards eco-friendly formulations, reflecting broader sustainability mandates and the expectations of downstream electronics manufacturers.
Anisotropic Conductive Film Market
Regulatory and quality compliance frameworks are tightening globally. Companies operating in this space must ensure their product architectures align with evolving standards for automotive, medical, and consumer electronics applications. The ability to navigate these regulatory landscapes effectively is becoming a key differentiator in securing long-term contracts with tier-one OEMs.
Competitive Landscape: Incumbents and Innovators
The market structure is characterized by moderate concentration, where established players leverage deep technical expertise and global distribution networks to maintain strong positions. Our analysis highlights a competitive environment where technology leadership and product certification often dictate market share rather than price alone.
Dexerials Corporation remains a focal point of industry attention. As a leading manufacturer based in Japan, the company has consistently demonstrated technological prowess, particularly in particle-arrayed variants tailored for micro-LED displays and specialized film-on-board applications for automobiles. Recent recognitions, including a major industry award for display components in early 2026, underscore the company's role in advancing the technological frontier. The firm's focus on film-on-glass solutions for touch panels further expands its addressable market within the consumer electronics ecosystem.
RESONAC Corporation stands out as a pioneer in thermosetting resin applications for the semiconductor backend process. Their ANISOLM series of ACF films addresses critical needs in fine-pitch connections and film substrates, catering to the precision requirements of modern semiconductor manufacturing. This specialization positions them uniquely within the high-value segment of the supply chain, where performance reliability outweighs cost sensitivity.
In the Western hemisphere, 3M Company continues to be a significant force, leveraging its broad material science heritage to serve flexible printed circuit bonding and electronics interconnects. Recent product launches in 2025 signaled the introduction of new lines aimed at advanced display technologies, reinforcing the commitment to innovation in this segment. Meanwhile, broader industry activity, such as product launches by major material conglomerates focusing on eco-friendly, high-conductivity polymer-based films, indicates that competitive pressure is increasing through diversification and sustainability-focused R&D.
Strategic Imperatives for Enterprise Decision-Making in 2026
For executives and strategy teams, the implications of these dynamics are clear. Decision-making in 2026 requires a multi-dimensional view that balances technical capability, supply chain resilience, and commercial opportunity. First, aligning procurement strategies with the specific application needs of display panels versus IC packaging is essential, as the performance requirements and margin profiles differ substantially. Second, monitoring the competitive moves of key incumbents and emerging innovators provides early warning signals regarding shifting technological standards and potential supply constraints.
Third, the trend toward high-density interconnects and fine-pitch connections demands close collaboration between material suppliers and product designers. Early engagement in the design phase can secure preferential access to next-generation ACF solutions and create barriers to entry for competitors relying on legacy standards. Finally, the evolving regulatory environment necessitates proactive compliance planning, particularly for firms expanding into automotive and medical markets where certification timelines can impact time-to-market.
Inside the PW Consulting Report: What You Will Discover
PW Consulting's latest study provides a granular, data-backed exploration of these themes, structured to support immediate strategic action. The report goes beyond high-level summaries to deliver operational insights that can be integrated into business plans immediately.
Worldwide Capacitive Touch Foil Film Market
- Detailed Market Sizing and Forecasting: Comprehensive revenue projections across the forecast horizon, segmented by key periods to facilitate budget allocation and revenue modeling. The report details the transition from historical baselines to forward-looking estimates, allowing for accurate scenario planning.
- Segmentation Analysis: In-depth breakdowns of the market by type, covering polymer films, metal films, and other variations. This section explores the technical advantages, cost structures, and adoption rates of each segment, helping you identify where your product portfolio aligns with market demand.
- Application-Specific Intelligence: A thorough examination of how ACF products are deployed across display panels, IC packaging, and other emerging applications. This analysis highlights growth pockets, adoption barriers, and the specific performance requirements driving volume in each segment.
- Competitive Benchmarking: Profiles of the core industry participants, including their headquarters, product portfolios, recent strategic moves, and market positioning. The report assesses how key players are responding to technological shifts and what their strategies imply for the broader competitive dynamics.
- Regulatory and Standards Landscape: A review of the compliance frameworks affecting production and distribution, including quality certifications and material standards. This section helps risk managers anticipate regulatory changes and ensure supply chain continuity.
- Strategic Recommendations: Actionable guidance for companies looking to enter, expand, or defend their position in the market. The recommendations cover sourcing strategies, partnership opportunities, R&D focus areas, and market entry considerations based on the current industry climate.
Why Access the Full Report Now?
While the insights presented here capture the essence of the current market landscape, the complete dataset and proprietary analysis within the PW Consulting report offer a depth of intelligence that is critical for mitigating risk and capturing opportunity. The full study includes detailed modeling tables, sensitivity analyses, and granular regional and segment data that are essential for building robust business cases and investment theses.
In a market where first-mover advantage and precision forecasting can determine profitability, relying on fragmented information is a strategic liability. The complete report equips you with the evidence base needed to negotiate with suppliers, validate product roadmaps, and align organizational resources with the highest-probability growth vectors.
Unlock the full intelligence behind this market. Visit the PW Consulting source page to download the complete Anisotropic Conductive Film Market report and empower your 2026 strategic decisions with data-driven clarity.
For detailed analysis of this topic, please visit the official page: Anisotropic Conductive Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Lab Glassware Market Hits USD 185M in 2025 Projected to Reach 253.28M by 2032 at 4.7 CAGR
By pmarketresearch, 2026-09-15
Navigating the Laboratory Glassware Market: Strategic Intelligence for 2026 and Beyond
The laboratory glassware sector stands at a critical inflection point as it moves through 2026. What was once considered a mature, commoditized market is undergoing a structural transformation driven by stringent regulatory updates, evolving end-user demands for precision and safety, and a competitive landscape that is consolidating around both premium innovation and cost-optimized manufacturing. For procurement leaders, strategy teams, and investors, navigating this environment requires more than top-line revenue projections. It demands a granular understanding of where growth is materializing, which product categories are gaining relative share, and how regional dynamics are reshaping supply chain strategies.
Our latest market research delivers exactly that intelligence. Built on a rigorous historical analysis spanning 2020 through 2025 and a forward-looking forecast extending to 2032, this report equips decision-makers with the analytical depth required to allocate capital, prioritize product portfolios, and anticipate competitive threats. The baseline year of 2025 anchors a trajectory that reveals a market demonstrating consistent resilience and measured expansion, even as macroeconomic volatility and raw material pricing fluctuations test the agility of manufacturers across the value chain.
The Strategic Imperative of 2026 Intelligence
Why does a comprehensive market assessment matter so acutely in 2026? The answer lies in the convergence of multiple forces that are simultaneously altering demand patterns, regulatory expectations, and competitive positioning. Laboratory glassware is no longer a static category of interchangeable consumables. It is becoming a strategically differentiated asset class, where material specifications, traceability features, and compliance certifications directly influence purchasing decisions in high-stakes environments such as pharmaceutical development, clinical diagnostics, and advanced academic research.
Companies that rely on outdated assumptions about regional demand or product-line growth risk misallocating resources in a market where marginal advantages in product quality, lead times, or certification readiness can translate into outsized market capture. Our research is designed to eliminate that uncertainty. By mapping historical revenue performance against forward-looking growth trajectories, we provide a clear view of how the market has evolved and where it is headed, enabling stakeholders to model scenarios with confidence rather than speculation.
Market Trajectory: A Macro View of Growth and Resilience
The overarching market narrative from 2020 through the forecast horizon is one of steady, compounding expansion. Over the past half-decade, the global laboratory glassware market has demonstrated remarkable consistency, with revenue growth compounding at a pace that reflects both the essential nature of the product category and the gradual scaling of scientific infrastructure across developed and emerging economies. The market has progressed from a baseline in the early 2020s to a position of meaningful scale by 2025, and the forward outlook suggests that this momentum will continue, albeit with year-to-year variation that rewards disciplined, data-informed planning.
The forecast period through 2032 paints a picture of sustained upward movement, with revenue projections pointing toward a substantially larger market than the one observed in the mid-2020s. The compound annual growth rate of 4.7 percent underscores a market that is neither explosive nor stagnant, but rather characterized by reliable, long-term expansion that favors organizations capable of executing consistently across procurement, manufacturing, and go-to-market functions. Currency-denominated revenue in USD millions provides a standardized lens for comparing performance across regions and product categories, ensuring that strategic comparisons are grounded in a common financial framework.
What makes this trajectory particularly relevant for 2026 is the way it interacts with operational realities. Year-over-year movement in the forecast reveals periods of acceleration and modest recalibration, reflecting the complex interplay between end-user investment cycles, raw material availability, and regional purchasing power. Organizations that internalize these patterns are better positioned to time capacity expansions, negotiate supplier contracts, and align product launches with windows of heightened demand.
Laboratory Glassware Market
Competitive Landscape: Where Consolidation Meets Innovation
The laboratory glassware market is defined by a competitive ecosystem that blends established multinational manufacturers with agile regional producers. Concentration metrics indicate that a relatively small group of leading players commands a meaningful portion of total market revenue, while a broader tier of specialized and regional suppliers competes on price, customization, and niche technical capabilities. This dual-layer structure creates both opportunities and risks: it allows buyers to source from a diverse supplier base, but it also places pressure on mid-tier manufacturers to differentiate through quality, compliance, or service agility.
Several companies exemplify the strategic directions shaping the industry today. DWK Life Sciences, headquartered in Germany, has built its reputation on premium laboratory glassware brands including DURAN, KIMBLE, and WHEATON, positioning itself at the intersection of scientific reliability and product innovation. Its recent participation in Analytica 2026 in Munich, where it highlighted new laboratory glassware innovations, signals a continued commitment to visibility and product leadership in a market that values demonstrated expertise. Earlier, in mid-2025, the company introduced DURAN protect+ coated laboratory bottles designed for enhanced shatter protection, an example of how engineered safety features are becoming a competitive differentiator rather than a secondary feature.
Across the Atlantic, Ace Glass Inc. in the United States has long been recognized as a leader in both custom and standard scientific laboratory glassware, spanning beakers, flasks, and reaction systems. Its product breadth appeals to customers who require flexible specifications without sacrificing consistency. This dual focus on customization and standardization reflects a broader industry dynamic: buyers increasingly want the reliability of catalog products alongside the option to adapt equipment to specialized workflows, particularly in complex research and pharmaceutical settings.
The Indian manufacturing base represents another critical pillar of the competitive landscape. Companies such as Borosil Scientific, Glassco Laboratory Equipments, Medilab Exports, Omsons Labs, and Hindustan Glass Works illustrate the breadth of capability present in the region. Borosil Scientific offers general laboratory glassware and consumables manufactured to USP Type 1 and ASTM standards, emphasizing compliance-driven quality. Glassco Laboratory Equipments focuses on interchangeable volumetric, filtration, and general laboratory glassware, while also engaging in targeted exhibitions to showcase premium equipment. Omsons Labs has moved toward greater traceability by updating its product offerings with QR-coded items, a practical response to the growing demand for supply chain visibility and lot-level accountability. Medilab Exports and Hindustan Glass Works round out a competitive field that serves both research and educational markets with borosilicate culture tubes, vials, test tubes, and broader laboratory supplies.
In the United States, Kimble Chase and Bellco Glass continue to reinforce the market's emphasis on specialty and integrated solutions. Kimble Chase's focus on volumetrics, chemistry glassware, and safety-coated products aligns with end-users who prioritize precision and operator protection. Bellco Glass contributes to this ecosystem as a supplier of integrated borosilicate glassware, media bottles, bioreactors, and lab equipment, appealing to customers who value a unified supply relationship across multiple equipment categories.
Glassware Market
Meanwhile, manufacturers in China such as Changde BKMAM Biotechnology and Huida Medical are expanding their footprint with laboratory glassware including flasks, cuvettes, sampling processing items, beakers, flasks, and cylinders. Their presence underscores the ongoing globalization of supply options and the importance of evaluating total cost, quality consistency, and lead-time reliability when integrating international suppliers into procurement strategies.
Standards, Compliance, and the New Operational Baseline
Regulatory and standards developments in 2026 are reshaping how manufacturers qualify products and how buyers validate performance. The emergence of prEN ISO 1042:2026, alongside DIN EN ISO 1042:2026-04, establishes updated international requirements for one-mark volumetric flasks. These standards reflect a broader push toward measurement consistency, documentation rigor, and cross-border comparability in laboratory equipment. For manufacturers, alignment with such specifications is becoming a prerequisite for credibility in markets where analytical precision is non-negotiable. For buyers, it introduces an additional dimension to supplier evaluation, one that intersects with procurement risk, inspection burden, and long-term compliance assurance.
In parallel, regional certification frameworks continue to influence market access. In India, BIS certification applies to laboratory glassware falling within its scope under Indian standards, reinforcing the need for manufacturers and importers to maintain documentation and conformity pathways that satisfy local regulatory expectations. These certification requirements are not merely administrative; they shape product roadmaps, cost structures, and time-to-market for companies seeking to serve regulated end-users in key geographies.
Clinical diagnostics adds another layer of complexity. Laboratory glassware used in clinical diagnostic tests generally falls under laboratory services reimbursement policies without specific CPT codes, meaning that the financial context for downstream use is embedded in broader service reimbursement frameworks rather than in device-level coding. This reality affects purchasing decisions in diagnostic and hospital settings by linking procurement choices to operational efficiency, throughput, and the broader economics of laboratory service delivery.
At the material level, borosilicate glass remains the primary raw material for laboratory glassware due to its thermal shock resistance, a property that continues to anchor product design and manufacturing decisions across a wide range of applications. The stability of this material foundation does not eliminate supply chain risk, but it does provide a predictable performance baseline around which manufacturers can engineer additional features, coatings, and traceability enhancements.
Inside the Report: Practical Intelligence for Execution
This market research is built to support action, not simply description. The report moves beyond headline figures to deliver the analytical architecture needed for strategic planning, commercial prioritization, and risk management. It provides a structured examination of market size and growth patterns across the historical and forecast periods, enabling readers to understand not only where the market has been but how the trajectory changes under different time horizons.
The analysis incorporates segmentation that clarifies which product types are generating meaningful revenue and how different application areas are contributing to overall demand. Rather than presenting these categories as static lists, the report frames them within the operational realities of procurement teams and product leaders, showing how shifts in relative emphasis can inform sourcing strategies, inventory planning, and new product development priorities.
Regional dynamics are examined with a similar emphasis on usability. The report contextualizes demand across major geographic areas, helping stakeholders assess where infrastructure growth, regulatory environments, and purchasing patterns are likely to influence opportunity and competition. This regional perspective is particularly valuable for organizations that must coordinate global supply strategies while remaining responsive to local market conditions.
Competitive analysis forms another essential layer. The report profiles the companies that are shaping market direction, including their strategic positioning, recent developments, and the ways in which product launches and trade presence signal deeper shifts in focus. Recent activities such as product catalog updates with traceability features, participation in major trade exhibitions, and the introduction of safety-oriented coatings are interpreted not as isolated events but as indicators of the capabilities and priorities that will influence competitive outcomes over the forecast period.
Just as importantly, the report integrates the regulatory and standards environment into a practical framework for decision-making. By connecting emerging requirements for volumetric flask specifications, certification obligations in key markets, and the reimbursement context for clinical-use glassware, the analysis helps organizations anticipate the operational impact of compliance changes before they become disruptive.
Why This Research Belongs in Your 2026 Planning Cycle
The laboratory glassware market is not defined by sudden disruption; it is defined by the accumulation of incremental advantages that separate resilient, growth-oriented organizations from those that react too late. A 4.7 percent compound growth trajectory over the forecast horizon may appear measured at first glance, but in a market with concentrated leadership, evolving standards, and divergent regional dynamics, the difference between average execution and disciplined strategy can be substantial.
This report gives strategy and procurement teams the evidence base required to make those distinctions clearly. It supports decisions about supplier portfolio design, product-line emphasis, geographic prioritization, and compliance readiness. It also provides the context needed to interpret competitor moves, such as safety-focused product launches or traceability enhancements, as signals of where the market is heading rather than as isolated updates.
The full depth of this analysis, including the detailed segmentation structure, regional breakdowns, and competitive assessment that ground these strategic conclusions, is available in the complete report. We invite you to explore the full research to access the precise data, company-level insights, and forward-looking scenarios that will inform your 2026 decisions and position your organization for the opportunities emerging through 2032.
For detailed analysis of this topic, please visit the official page: Laboratory Glassware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Robotic Polishing Machine Market Hits $215M in 2025, Poised for 12.6% CAGR Through 2032
By pmarketresearch, 2026-09-15
Strategic Horizons: Navigating the Robotic Polishing Machine Market from 2026 Onward
Executive Overview
The industrial surface finishing landscape is undergoing a structural transformation, driven by the convergence of advanced robotics, precision control systems, and escalating demands for repeatable quality across complex geometries. For manufacturing executives, capital allocators, and procurement strategists, understanding the trajectory of the robotic polishing machine market is no longer a peripheral analytical exercise—it is a core component of operational planning, capacity investment, and competitive positioning. PW Consulting’s latest market research release delivers a comprehensive, forward-looking assessment engineered specifically to inform 2026 decision-making. This introduction outlines the strategic architecture of the study, the analytical frameworks it employs, and the decisive intelligence it surfaces. Readers are invited to engage with the full report for granular segmentation, modeling outputs, and actionable implementation roadmaps.
Robotic Polishing Cells Market
The analysis rests on a rigorously validated historical track record and a carefully constructed multi-year projection window. It traces market evolution across a defined historical span and extends the analytical horizon to the medium-term forecast period. By anchoring projections in observable supply-chain shifts, automation adoption curves, and sector-level capital expenditure patterns, the publication provides a defensible baseline for stress-testing investment hypotheses and aligning operational roadmaps with emerging market realities.
The 2026 Decision Landscape: Why Timing Matters
Entering 2026, enterprises across precision manufacturing, automotive assembly, electronics production, and industrial tooling face a shared strategic imperative: convert automation investments into measurable throughput gains, quality consistency, and labor flexibility. Market momentum suggests that the next several years will be characterized by accelerated deployment cycles, technology maturation, and evolving compliance expectations. In this environment, strategic planners require more than directional signals. They need validated sizing, scenario-tested growth pathways, and clear visibility into where capital will flow and how competitive dynamics will reshape vendor selection.
The research publication is structured to serve as a decision-support instrument rather than a static market snapshot. It maps the trajectory from the most recent baseline year through the forecast window, enabling leadership teams to calibrate their investment cadence, evaluate entry or expansion timing, and anticipate shifts in vendor pricing, integration complexity, and service requirements. By aligning forecast outputs with practical planning horizons, the study allows decision-makers to translate macro-level movement into actionable procurement and capacity strategies.
Historical Trajectory and Forward Momentum
Market expansion over the historical observation window provides a clear reference point for evaluating the scale and pace of ongoing adoption. Revenue progression across the reviewed historical years reflects sustained demand for automated finishing solutions, underpinned by quality standardization requirements, throughput optimization goals, and the broader shift toward flexible automation in discrete manufacturing. The data series captures the steady climb in system uptake as organizations transition from experimental automation to production-critical deployment.
Robotic Polishing Machine Market
Forward-looking projections extend this trajectory into the forecast period, illustrating a sustained growth pathway. The compound annual growth rate positions the market in a high-velocity band relative to adjacent industrial automation segments, signaling continued investment appetite and broadening application relevance. Revenue estimates for the near-term forecast years indicate a market that will continue to scale materially, with later projection points suggesting meaningful expansion as technology costs normalize, integration pathways mature, and end-user confidence in robotic finishing systems deepens. The overall market sizing framework offers executives a reliable macro baseline, while intentionally preserving detailed regional, application, and type-level breakdowns for the full report, where they can be examined alongside supporting methodology and scenario notes.
Structural Dimensions of the Market Opportunity
A market of this scale and pace cannot be understood through a single lens. The research decomposes the landscape into several interlocking structural layers, each designed to support a different class of strategic question.
- Technology and configuration pathways are evaluated to clarify how different machine architectures align with production objectives, surface complexity requirements, and integration footprints.
- Application relevance is mapped across major end-use environments, helping stakeholders determine where automated polishing delivers the strongest return on quality, cycle-time, and labor flexibility objectives.
- Geographic distribution is analyzed to identify demand concentration patterns, regional growth pacing, and localized adoption drivers that influence sourcing, service coverage, and partnership strategy.
This layered structure ensures that the study can be used both for executive-level market sizing and for operational planning tasks such as product-line alignment, regional rollout sequencing, and vendor shortlisting. By maintaining analytical discipline across these dimensions, the publication avoids overgeneralization and equips readers with a structured way to interrogate the opportunity space from multiple vantage points.
Competitive Architecture and Strategic Positioning
The competitive field in robotic polishing reflects a blend of established automation specialists, tooling and system integrators, and technology-forward entrants emphasizing intelligent control and adaptive finishing. The study profiles key participants to illuminate how strategic positioning, product focus, and geographic footprint shape market influence.
Several organizations feature prominently in the competitive landscape. Acme Manufacturing is highlighted for its emphasis on robotic polishing machines built around advanced belt polishing heads, targeting high-volume producers that require repeatable finishes on complex shapes. Mirka Ltd is examined for its broader systems approach, offering complete robotic polishing and sanding solutions that combine tooling and automation integration for industrial surface finishing. GrayMatter Robotics enters the analysis through its AI-powered systems, which scan and automate polishing workflows with a focus on expanding manufacturing capacity while reinforcing quality consistency. Dinosaw Machine is profiled for its 6-axis robotic arm and system portfolio designed for stone grinding and polishing, with an emphasis on force control and precision tooling. American Siepmann Corporation rounds out the competitive set through its supply of automated CNC polishing machines and robotic systems oriented toward high-precision industrial finishing.
These profiles are not presented as isolated corporate snapshots. Instead, they are contextualized within broader competitive dynamics, including technology differentiation, integration readiness, service and support expectations, and the strategic logic behind recent product and event-level developments. Recent activity underscores how rapidly the field is evolving. In late 2025, Dinosaw Machine presented an in-depth industry event analysis centered on stone polishing robot technology, detailing 6-axis force control and safety integration considerations. Around the same period, Mirka Ltd released an updated brochure for its robotic solutions, reinforcing its focus on automated polishing, sanding, and grinding systems. Such developments point to a market in which product refinement, application specificity, and compliance-aware engineering are becoming central to competitive differentiation.
Regulatory Guardrails and Operational Realities
As robotic finishing systems move deeper into production-critical roles, compliance and safety architecture increasingly shape procurement decisions. The market’s leading technology demonstrations increasingly reference governing industrial robot safety requirements, including structured risk assessments and protective measures that align with established ISO 10218 expectations. Rather than treating compliance as a separate administrative checklist, the research integrates it into the broader assessment of deployment readiness, integration risk, and total cost of ownership.
For planning teams, this means that technology selection is inseparable from operational governance. Machines that deliver superior finish consistency must also satisfy safeguarding, interoperability, and validation expectations within the user’s facility. The study examines how safety-centric engineering and compliance alignment influence vendor evaluation, installation timelines, and long-term reliability, ensuring that strategic recommendations account for both performance and operational accountability.
What the Full Report Delivers
The publication is designed as a modular intelligence framework that can be deployed across multiple internal use cases, from strategic planning and investment review to procurement alignment and competitive benchmarking. While this introduction establishes the strategic rationale and high-level market structure, the full report extends far deeper into the analytical detail required for concrete decision-making.
- Market sizing and growth modeling that connect historical performance with forward projections, enabling scenario planning across different adoption and pricing assumptions.
- Multi-dimensional segmentation analysis that isolates demand patterns across technology types, application environments, and regional footprints, with supporting commentary on what each split implies for sourcing and rollout strategy.
- Competitive profiling and positioning maps that clarify how leading participants differentiate themselves, where capability gaps may exist, and how procurement teams can structure vendor evaluations.
- Recent development tracking that ties product launches, technical presentations, and system updates to market implications, helping readers gauge momentum in specific sub-areas of the value chain.
- Operational and compliance considerations that connect technology choices to safety requirements, integration complexity, and facility-level implementation realities.
The report is built to support both near-term tactical questions and longer-horizon strategic planning. It provides the evidentiary scaffolding needed to evaluate market entry, capacity expansion, supplier diversification, and technology investment timing with greater confidence.
Strategic Takeaways for 2026 Planning
As enterprises move into the 2026 planning cycle, the robotic polishing machine market presents both a scaling opportunity and a complexity challenge. Demand momentum, technology maturation, and competitive differentiation are converging to reshape how organizations evaluate automation investments. The companies best positioned to capture value will be those that align system selection with production objectives, anticipate integration and compliance demands, and base procurement decisions on rigorous, scenario-tested intelligence rather than directional assumptions alone.
PW Consulting’s market research is intended to function as a strategic compass for that process. It synthesizes historical evidence, forward projections, competitive dynamics, and operational realities into a coherent decision-support structure. To fully exploit the analytical depth, segmentation breakdowns, and competitor intelligence embedded in the study, stakeholders should engage with the complete report. The full publication provides the detailed market architecture necessary to convert high-level trends into precise, execution-ready strategy.
For detailed analysis of this topic, please visit the official page: Robotic Polishing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Steam Turbine Market to Grow at 2.8% CAGR to $31.79M by 2032, Asia Pacific Leads
By pmarketresearch, 2026-09-15
Powering the Future: Strategic Insights into the Global Steam Turbine Market 2026-2032
Executive Summary: Navigating a Transitional Decade
The global energy landscape is undergoing a profound transformation. As the world balances the urgent need for reliable baseload power with the accelerating demand for sustainable solutions, the steam turbine remains a critical asset in the infrastructure toolkit. Our latest comprehensive study, the Steam Turbine Market Analysis 2026-2032, offers a granular examination of this evolving sector. This report is not merely a numerical forecast; it is a strategic roadmap designed to guide stakeholders through a period of regulatory shifts, technological innovation, and geopolitical complexity.
Based on rigorous data modeling, the global steam turbine market is projected to reach a valuation of USD 27.39 Million in 2026, growing steadily to approximately USD 31.79 Million by 2032. This trajectory reflects a Compound Annual Growth Rate (CAGR) of 2.8% over the forecast period. While the growth rate may appear moderate, the underlying dynamics driving this expansion are complex, involving a mix of legacy fleet modernization, renewable integration, and emerging power demands. Understanding the nuances behind these figures is essential for capitalizing on market opportunities.
Market Trajectory and Macro Economic Context
The historical data from 2020 to 2025 establishes a baseline of resilience. The market demonstrated consistent recovery and growth, moving from USD 22.82 Million in 2020 to USD 26.2 Million in 2025. This five-year trend underscores the enduring demand for thermal power solutions, even as the grid decarbonizes. The forecast period from 2026 to 2032 anticipates a continuation of this upward trend, driven by specific macroeconomic and industrial forces.
However, interpreting these top-line numbers requires a deeper dive into the segmentation and regional drivers that constitute the whole. The aggregate figure masks significant variations across product types, applications, and geography. Our full report dissects these components, providing the specific revenue breakdowns and volume analysis necessary for precise market sizing and opportunity assessment. Without this detailed segmentation, investment decisions risk being based on incomplete intelligence.
Key Market Drivers: Technology and Demand Shifts
Several critical factors are converging to shape the market landscape in 2026 and beyond. The most prominent driver is the surging power demand from artificial intelligence and data centers. As digital infrastructure expands, the requirement for reliable, high-capacity power generation is accelerating combined-cycle projects that incorporate steam turbines. Industry data indicates that projects targeting online operation by 2028 are already in motion, creating a immediate pipeline for turbine manufacturers.
Additionally, regulatory frameworks are playing a pivotal role in dictating market flow. In the United States, the Environmental Protection Agency finalized New Source Performance Standards for stationary combustion turbines effective January 15, 2026. These standards impose efficiency subcategorization thresholds, requiring large low-utilization units to meet design efficiency levels of 38%. This regulation directly impacts turbine design specifications and compliance strategies. Simultaneously, the U.S. Department of Energy allocated USD 475 million in June 2025 to enhance steam turbine efficiency in clean energy infrastructure, signaling strong government support for technological upgrades.
Furthermore, the regulatory environment regarding existing coal-fired units remains stringent. EPA Section 111 standards require conversion to natural gas or Carbon Capture and Storage (CCS) retrofits by 2030-2039. This mandates a strategic pivot for utilities and investors, influencing the demand for specific turbine configurations capable of handling alternative fuels or adapted cycles. These regulatory pressures create both challenges and opportunities, necessitating a detailed understanding of compliance timelines and technical requirements.
Supply Chain and Material Considerations
The manufacturing landscape is not immune to external economic pressures. Recent industry data highlights that U.S.-China tariffs have driven up prices of nickel and chromium-based alloys essential for steam turbine components. These raw material cost fluctuations impact margins and project economics, requiring careful supply chain management and hedging strategies. Stakeholders must account for these cost variables when bidding on long-term contracts or projecting financial performance.
Our analysis delves into the supply chain vulnerabilities and cost structures associated with high-grade alloys, offering insights into how leading manufacturers are mitigating these risks. Understanding the interplay between geopolitical trade policies and material costs is crucial for accurate pricing strategies and contract negotiations.
Competitive Landscape: Leaders and Innovators
The market is characterized by a mix of established multinational corporations and agile regional players. Concentration remains significant, with the top three companies holding a CR3 of 48.0% and the top five holding a CR5 of 50.0%. This concentration suggests a market where scale, technological IP, and long-term service agreements are key differentiators.
Several key companies are defining the competitive frontier through strategic orders and technological advancements:
Gas Turbine Market
- Siemens Energy AG continues to lead with a broad portfolio spanning 90-1,900 MW for conventional, combined-cycle, and nuclear applications. Recent activity includes a significant contract with Oklo for the Aurora advanced reactor power plant and selection for Applied Digital's 1 GW AI data center power project. Their record backlog of €138 billion reflects strong market confidence.
- GE Vernova Inc. supplies over 30% of global installed steam capacity. Their STF-series, including the STF-A650 and STF-D600, are central to advanced combined-cycle reheat designs, maintaining their dominance in power plant solutions.
- Mitsubishi Heavy Industries, Ltd. focuses on high-efficiency turbines for gas turbine combined-cycle plants, with the M701F series offering hydrogen co-firing capabilities, aligning with decarbonization goals.
- Doosan Enerbility Co., Ltd. has secured recent North American orders, including a contract for two 370 MW-class steam turbines for a U.S. data center project, highlighting the shift towards digital infrastructure power needs.
- Dongfang Electric Corporation Ltd. and Shanghai Electric Group Co., Ltd. remain leading Chinese suppliers, driving volume in large-scale turbine production for utility and combined-cycle systems.
- Bharat Heavy Electricals Limited serves the Indian market with turbines and generators for power generation and cogeneration.
- Toshiba Energy Systems & Solutions Corporation and Ansaldo Energia S.p.A. provide specialized solutions for combined-cycle and cogeneration plants.
- Harbin Electric Corporation leverages strong domestic and export capabilities for power generation turbines.
The competitive dynamics are not static. Recent developments in 2025 and 2026 show a clear trend towards securing long-term backlogs and entering niche high-growth sectors like nuclear and AI data centers. Our report provides a detailed competitive profiling, analyzing market share, strategic positioning, and recent M&A or partnership activities that shape the industry hierarchy. Accessing the full report reveals the specific strategic moves that are defining market leadership in this cycle.
Segmentation Insights: Types and Applications
The market is bifurcated primarily by turbine type and application. The two main technological approaches are Impulse and Reaction steam turbines. Each type offers distinct advantages depending on the pressure stages and efficiency requirements of the plant. Similarly, applications range from traditional power generation to industrial oil and gas usage, and other specialized sectors.
Power generation remains the dominant application, but the proportion of revenue contributed by industrial sectors and the specific performance characteristics preferred in different regions vary significantly. The full study provides a deep dive into the performance metrics, efficiency ratings, and cost-benefit analysis of each segment. Knowing which segment is driving growth in specific timeframes allows for targeted product development and marketing strategies.
Regional Analysis and Growth Hotspots
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique set of drivers. For instance, Asia Pacific has historically shown substantial volume due to industrialization and energy access goals. North America and Europe are increasingly driven by efficiency upgrades and compliance with stringent environmental regulations.
However, the specific revenue contribution and growth rate for each region are subject to local policy changes, capacity additions, and retirement schedules of older plants. A superficial regional overview is insufficient for strategic planning. The detailed regional analysis in our full report breaks down country-specific regulatory environments, infrastructure projects, and demand forecasts, enabling clients to prioritize markets with the highest potential return on investment.
Steam Turbine Market
Strategic Value for 2026 Decision Makers
Why is this report essential for 2026? Because the margin for error is narrowing. With regulatory deadlines approaching for coal-fired units and rapid shifts in power demand profiles, decisions made today will determine operational viability and profitability over the next decade.
Our report is designed to answer critical strategic questions:
- How should capital be allocated between new builds and retrofits given the 2030-2039 compliance windows?
- Which turbine technologies are best positioned to meet the 38% efficiency thresholds for large units?
- How do raw material cost volatilities impact long-term contract pricing models?
- Which competitors are gaining ground in high-growth niches like nuclear micro-reactors and data center power?
The insights provided are not generic observations but data-backed revelations derived from extensive primary and secondary research. We isolate the signal from the noise, focusing on actionable intelligence that drives bottom-line results.
Conclusion: Accessing Complete Intelligence
The global steam turbine market is at an inflection point. While the top-line forecast indicates steady growth, the real value lies in understanding the mechanical levers driving that growth. From the impact of EPA standards on turbine design to the supply chain implications of alloy tariffs, and the competitive maneuvers of industry giants like Siemens and GE Vernova, the landscape is rich with complexity.
This article serves as a preview of the depth and breadth of our Steam Turbine Market Research. However, the strategic numbers, detailed segmentation splits, and comprehensive competitor matrices are reserved for our full publication. To secure a competitive advantage in 2026, you need more than general trends; you need precise data.
We invite you to access the full report to unlock the complete strategic intelligence required to navigate the 2026-2032 forecast period with confidence. The detailed breakdowns of region-specific values, application-specific revenue, and type-specific market shares are available exclusively through our comprehensive study. Make informed decisions with the full picture.
For detailed analysis of this topic, please visit the official page: Steam Turbine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Data Center Busway Market Reaches $215M in 2025, 9% CAGR Forecast to 2032
By pmarketresearch, 2026-09-15
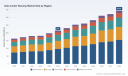
Strategic Intelligence for the AI Power Era: Inside the 2026 Data Center Busway Market Report
The global data center landscape is undergoing a structural transformation driven by the exponential power demands of artificial intelligence workloads. As hyperscale campuses expand and enterprise facilities retrofit for higher density, the infrastructure delivering power within the white space has become a critical bottleneck and a strategic differentiator. Our latest market research on the Data Center Busway Market provides the rigorous intelligence required to navigate this shift through 2032.
This document serves as a strategic preface to our comprehensive study. It outlines the macro trajectory, the competitive velocity, and the operational imperatives defining the sector. For executives responsible for capital allocation, infrastructure design, or supply chain resilience, the findings herein offer a decision-ready framework. However, the true depth of our analysis—down to granular segmentation drivers, regional procurement patterns, and proprietary risk matrices—is reserved for the full report, ensuring that organizational leaders possess the exclusive context needed to outperform the market curve.
The Macro Trajectory: Scaling from 215 Million to 344.8 Million
The market has demonstrated consistent upward momentum, evolving from a global revenue base of 163.15 million in 2020 to a projected 215.0 million in 2025. This growth reflects a sustained compound annual growth rate of 9.0 percent across the historical window, signaling that busway systems have transitioned from niche alternatives to mainstream power distribution standards.
Looking forward, our forecast model indicates that this momentum will sustain and accelerate. We project the market to reach 231.33 million in 2026, climbing to 253.41 million by 2027 and continuing toward 344.8 million by 2032. This trajectory is not merely a function of data center construction volume. It represents a fundamental shift in how power is routed within modern facilities. Traditional cabling architectures struggle to accommodate the spatial constraints and thermal profiles of high-density AI racks, making modular, plug-in busway systems the preferred engineering solution for scalable white-space optimization.
Busway-Bus Duct Market
For strategic planners, the implication is clear: the window for standardizing busway architectures at the design phase is narrowing. Organizations that delay infrastructure specification decisions risk higher retrofit costs and compatibility friction as facility density targets escalate. Our full report dissects the velocity of adoption across deployment stages, providing the sensitivity analysis required to model total cost of ownership under varying capacity expansion scenarios.
Operational Dynamics: Material Costs, Regulation, and AI Density
The market does not evolve in a vacuum. Three concurrent dynamics are reshaping procurement strategy and product selection criteria. Understanding their interplay is essential for accurate budgeting and risk mitigation.
-
Raw Material Volatility and Conductor Economics: Copper prices surged to 15-month highs in 2025, driven by supply chain disruptions and intensifying data center demand. This spike directly impacts the material cost structure of busway systems. In response, engineering teams are increasingly evaluating aluminum conductor options, which reduce weight and installation labor compared to copper in high-density deployments. The decision between copper and aluminum is no longer purely technical; it is a financial optimization problem tied to capacity planning cycles and local labor economics.
-
Regulatory Compliance and Infrastructure Upgrades: The EU Energy Efficiency Directive now requires data center operators to upgrade infrastructure, including busway replacement for compliance. This regulatory pressure transforms busway procurement from an operational upgrade into a compliance mandate in specific jurisdictions. Furthermore, UL listing requirements for specialized busway configurations ensure mission-critical reliability, adding a quality assurance layer that influences vendor selection and deployment timelines.
-
Hyperscale AI Construction and High-Ampacity Demands: The construction of hyperscale AI data centers is driving demand for high-ampacity busway systems exceeding 4000A. Traditional busway architectures rated for lower current thresholds are becoming obsolete in front-tier AI deployments. This shift pushes manufacturers to innovate in cross-sectional design, cooling integration, and tap-off modularity to support the power density profiles that AI training and inference clusters require.
These dynamics create a complex procurement environment. A decision that appears cost-effective on a per-meter basis may carry hidden integration risks or compliance gaps. Our report provides a structured evaluation matrix to assess these variables against your specific deployment profile, ensuring that procurement decisions align with both financial targets and operational resilience requirements.
Competitive Landscape: Innovation Velocity Among Market Leaders
The Data Center Busway Market operates with a measured concentration profile. The combined market share of the top three competitors stands at 24.6 percent, while the top five reach 26.2 percent. This relatively fragmented structure among leading players indicates that scale alone does not guarantee dominance. Instead, competitive advantage is increasingly derived from product-specific engineering, ecosystem integration, and speed of response to AI-driven specification changes.
Our analysis identifies a cohort of strategic players whose recent developments illustrate the direction of innovation:
-
Schneider Electric continues to advance the integration of power distribution with cooling and modular construction. The November 2025 launch of new EcoStruxure Pod Data Center solutions featuring high-power busway integrated with liquid cooling and prefabricated modules signals a shift toward turnkey AI cluster deployments. At Data Center World 2026, the company reinforced this trajectory with a booth showcasing NetShelter Power Shelf and busway integration for 48V AI systems, indicating an expansion into lower-voltage, high-efficiency architectures.
-
Vertiv has focused on scalable capacity within tight spatial footprints. The March 2026 announcement of a scalable high-capacity double-stack PowerBar Track busway system addresses growing AI data center demands while preserving white space. With PowerBar Track and double-stack busway systems supporting up to 2500A with copper and aluminum options and toolless tap-offs, Vertiv is positioning for rapid deployment cycles where installation efficiency matters as much as raw ampacity.
-
Eaton Corporation maintains a strong emphasis on modular flexibility. The Pow-R-Way III and PowerWave 2 track-style busway systems with modular tap-off enable scalable white-space and high-density power distribution. The company’s April 2026 presence at Data Center World 2026, showcasing modular data center solutions including busway power distribution, underscores a strategy aligned with facilities that require granular power zoning and future-proof expansion paths.
-
ABB Ltd offers the Lmax-T low-voltage busway systems with integrated protection, metering, and monitoring for data center server room distribution up to 86 kW per rack. This integrated approach appeals to operators seeking to reduce the number of discrete components in the power chain, streamlining maintenance and improving visibility at the rack level.
-
Siemens AG has pursued aluminum-based busway systems with smart monitoring for high-density AI data centers, complemented by strategic partnerships in power distribution. This playbook combines material efficiency with digital observability, enabling operators to monitor load profiles and thermal performance within the busway infrastructure itself.
-
LS Cable & System has introduced Data-way busway with modular plug-in taps and UL listing for high-capacity AI and energy-efficient data center power distribution. The UL listing provides a compliance anchor for mission-critical deployments, while the modular tap architecture supports rapid reconfiguration as rack densities evolve.
-
Legrand continues to provide data center busway solutions for modular power distribution in mission-critical facilities, emphasizing reliability and integration compatibility with broader facility management ecosystems.
-
nVent offers custom medium- and high-voltage bus systems for industrial and data center power applications, addressing operators whose power distribution needs extend beyond standard low-voltage architectures.
-
EAE Electric provides busway systems up to 6300A with data center-specific solutions for power distribution, targeting high-capacity deployments that demand robust current handling within a single busway run.
The competitive landscape is characterized by rapid product iteration and a clear focus on AI-specific requirements. Participation at events like Data Center World 2026 reflects a market where specification cycles are compressing and operators demand vendor responsiveness. Our report includes a comparative assessment of these players across product breadth, integration capabilities, and regional reach, enabling you to align vendor shortlists with your specific architectural and compliance requirements.
What Our Report Delivers: From Macro Trends to Actionable Intelligence
The full Data Center Busway Market research is structured to support decision-making at multiple organizational levels. Beyond the aggregate market sizing and growth projections, the study provides the operational granularity needed to translate market intelligence into procurement, design, and partnership strategies.
Key components of the analysis include:
-
Segmentation Architecture: A detailed breakdown of the market by system type, including three-phase five-wire configurations, three-phase four-wire variants, and other specialized formats. This segmentation reveals which architectures are gaining preference in specific deployment contexts and how design trade-offs influence adoption rates across different facility classes.
-
Application-Specific Demand Profiles: Analysis of demand patterns across hyperscale data centers, colocation facilities, and enterprise data centers. The study examines how power density targets, space constraints, and operational models differentiate the busway requirements of each segment, enabling you to benchmark your infrastructure plans against prevailing industry practices.
-
Regional Dynamics and Procurement Patterns: A geographic assessment that contextualizes demand drivers, regulatory environments, and supply chain maturity across major markets. This analysis supports multi-region expansion planning and helps identify regions where local content requirements or logistics considerations may influence vendor selection and lead-time expectations.
-
Competitive Benchmarking and Development Tracking: In addition to the profiles of the leading manufacturers, the report tracks recent product launches, trade show participations, and strategic moves that signal shifts in competitive positioning. This timeline of developments enables you to anticipate market evolution rather than react to it.
-
Risk and Cost Sensitivity Analysis: Structured evaluation of material price exposure, compliance timelines, and installation complexity factors. These insights help quantify the financial implications of different busway specification choices and support more accurate capital planning.
The report is designed to be actionable. Each section connects market data to operational implications, ensuring that technical leaders, procurement teams, and executive stakeholders can extract relevant insights without sifting through undifferentiated statistics.
Data Center Busway Market
Strategic Takeaways for 2026 Decision-Makers
As you evaluate your infrastructure roadmap for the remainder of 2026 and beyond, several priorities emerge from the market evidence:
-
Design for density, not just capacity. The shift toward AI workloads means that spatial efficiency and tap-off flexibility are as critical as raw ampacity. Busway architectures that support rapid reconfiguration and toolless connections will reduce deployment friction as rack layouts evolve.
-
Model material risk explicitly. Copper volatility and the availability of aluminum alternatives introduce cost variance into busway procurement. Incorporating conductor economics into your total cost of ownership models will improve budget accuracy and reveal scenarios where aluminum-based systems offer superior lifecycle value.
-
Align vendor evaluation with integration depth. The market leaders are increasingly competing on integrated monitoring, cooling compatibility, and modular shelf systems rather than busway conductors alone. Your vendor shortlist should reflect the degree to which you require ecosystem integration versus standalone power distribution.
-
Anticipate compliance-driven replacement cycles. In regions subject to energy efficiency mandates, busway replacement may transition from discretionary upgrade to regulatory requirement. Planning for compliance timelines now avoids rushed procurement and premium pricing later.
-
Access the full intelligence to de-risk capital decisions. While this overview establishes the market direction and competitive context, the complete report provides the segmented data, regional breakdowns, and scenario modeling necessary to finalize specifications, negotiate with vendors, and secure supply chain commitments.
The Data Center Busway Market is entering a phase where engineering precision, regulatory foresight, and vendor agility converge to define competitive advantage. Our report delivers the comprehensive intelligence required to navigate that convergence with confidence. To access the full analysis, including detailed segmentation insights, regional procurement patterns, and proprietary risk matrices, we invite you to explore the complete study on our platform.
For detailed analysis of this topic, please visit the official page: Data Center Busway Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Soy Sauce Market Hits $41.05B in 2025, Poised for 5.4% CAGR Through 2032
By pmarketresearch, 2026-09-15
Global Soy Sauce Market Strategic Outlook: Navigating Growth, Supply Chains, and Competitive Dynamics Through 2032
The global soy sauce market stands at a pivotal juncture. As consumer tastes diversify across culinary traditions, food manufacturers scale premiumization strategies, and raw material supply chains face renewed macroeconomic pressure, the category is evolving from a staple condiment into a structured, data-driven industry arena. For executives operating in food manufacturing, distribution, or ingredient procurement, understanding the trajectory of soy sauce demand is no longer a niche exercise. It is a strategic imperative.
Our latest market research initiative delivers a comprehensive, forward-looking analysis of this landscape. Designed for decision-makers who require actionable intelligence rather than superficial summaries, the study traces performance from historical baselines through a detailed forecast window, examining where value is created, how competitive advantages are shifting, and which structural forces will dictate profitability in the years ahead. This article offers a strategic preview of the report's analytical framework and explains why its findings are positioned to support high-stakes corporate planning throughout 2026.
Macro Trajectory and Strategic Implications
The market has demonstrated sustained expansion over the recent historical period, with revenue climbing steadily from approximately 29.95 billion USD in 2020 to 35.74 billion USD in 2023, before reaching an estimated 41.05 billion USD in 2025. This progression reflects more than nominal growth; it signals deepening penetration, rising unit values in premium categories, and sustained institutional demand across both household and commercial channels. The forecast horizon carries forward this momentum with a compound annual growth rate of 5.4 percent, positioning the market at 44.69 billion USD in 2026 and advancing toward the upper echelon of the high 50 billion USD range by the close of the projection window in 2032.
For corporate strategists, this trajectory carries several operational implications. A steady mid-single-digit growth profile suggests a maturing but still expandable category where incremental share gains require deliberate positioning rather than passive tailwinds. The sustained upward path also indicates that demand is not solely tethered to population growth in traditional markets; rather, it is being reinforced by product innovation, format diversification, and the continued globalization of Asian culinary influence. Officers tasked with capacity planning, brand portfolio management, or channel expansion should treat this overarching trend as a foundational input, while recognizing that underlying momentum varies meaningfully across segments and geographies. Our research isolates those variations so leadership can allocate resources where marginal returns are highest.
What the Report Delivers: Operational Intelligence for 2026 Decision-Making
This study was constructed to function as a working document for strategy, procurement, and commercial teams. Rather than stopping at headline numbers, the report breaks down the market architecture across multiple dimensions that matter directly to execution. Readers will find structured coverage of:
- Segment-Level Performance: Detailed assessments of product type categories, including light and dark soy sauce as well as other variants, with analysis of how each format's utility, flavor profile, and price positioning shape its respective demand curve. Household, food industry, and foodservice applications are examined separately, allowing executives to map consumption behavior to channel strategy and packaging decisions.
- Regional Dynamics: Geographic evaluation of how mature markets, high-growth regions, and emerging trade corridors contribute to total revenue. The analysis considers local culinary traditions, distribution maturity, import-export flows, and the interaction between regional purchasing power and product premiumization.
- Competitive Benchmarking: A focused examination of leading manufacturers and emerging innovators, covering operational scale, manufacturing footprints, export capabilities, and strategic moves that alter market positioning. This includes attention to facility expansion, brand architecture, and the competitive signaling evident in flagship product launches and trade presence.
- Cost and Input Environment: Assessment of the raw material backdrop, including soy commodity pricing trends and their implications for manufacturing cost structures, margin planning, and supplier negotiation timelines.
- Regulatory and Labeling Landscape: Comparative review of classification rules, GMO labeling obligations, and nutritional disclosure requirements across key jurisdictions, helping compliance and market-entry teams anticipate labeling burdens and consumer communication constraints.
- Strategic Scenarios and Forward Indicators: Synthesis of the data into decision-ready frameworks that translate market movement into potential strategic responses, including capacity timing, premiumization pacing, channel prioritization, and geographic expansion sequencing.
Each section is designed to connect directly to operational questions. Procurement leaders can reference the input-cost discussion to align hedging and sourcing windows. Commercial teams can use the segment and application breakdown to refine SKU strategy and packaging formats. Corporate development groups can leverage the competitive and regional analysis to identify where acquisition, partnership, or organic entry offers the most defensible positioning.
Competitive Landscape: Scale, Specialization, and Strategic Posture
The industry is shaped by a blend of large multinational producers, regionally dominant manufacturers, and specialized innovators pursuing differentiated flavor profiles. The concentration pattern reflects a market where scale advantages in brewing capacity, distribution reach, and brand recognition provide meaningful defensive moats, while differentiation in formulation, sourcing story, and premium positioning opens pockets of high-margin growth.
Among the most prominent players, Kikkoman Corporation continues to anchor its global footprint through a long-standing commitment to traditionally brewed production. With major facilities in the United States and a consistent export presence, the company's manufacturing expansion in its home region and overseas reflects a strategy of aligning supply capability with demand growth in key destination markets. Its planned first shipments from a new Wisconsin production facility in fall 2026 underscore the kind of capacity timing that can influence regional availability, cost competitiveness, and brand visibility well into the forecast period.
Foshan Haitian Flavouring and Food Co., Ltd. and Pearl River Bridge represent substantial production and distribution strength within China and broader Asian markets, with product portfolios extending across soy sauce and seasonings. Their scale in domestic channels and expanding international reach makes them central reference points for understanding how regional manufacturers compete on both volume and formulation variety. Lee Kum Kee Company Limited pursues a different strategic emphasis, concentrating on premium, naturally brewed varieties with worldwide distribution. This premium-oriented posture highlights the commercial opportunity that arises when brand narrative and product quality are aligned with global consumer curiosity about authentic condiment craftsmanship.
Yamasa Corporation and Shibanuma Soy Sauce Co., Ltd. further enrich the competitive picture by demonstrating the enduring relevance of specialized fermentation expertise. Their focus on naturally fermented products and established export channels illustrates how traditional production methods can be leveraged as differentiation assets in markets that reward authenticity and-consistency in flavor. At the opposite end of the scale spectrum, Bourbon Barrel Foods exemplifies a niche innovation pathway: microbrewed, barrel-aged soy sauce produced in repurposed bourbon barrels creates a distinct sensory profile that appeals to enthusiast buyers and specialty channels. While small relative to mass-market producers, such innovators signal an important structural truth about the category: differentiation in process and flavor story can command premium positioning even in a mature category.
These competitive postures do not exist in isolation. Recent activity illustrates how companies are using facility expansion, trade presence, and product visibility to reinforce market position. Kikkoman's U.S. facility milestone, with first shipments slated for fall 2026, represents a capacity event with implications for regional supply reliability and brand accessibility. Separately, broader trade activity in early 2026 highlighted the continued showcasing of leading Chinese soy sauce brands across light, dark, and standard varieties, reflecting the ongoing importance of trade platforms as both distribution touchpoints and competitive signaling arenas. Together, these movements suggest a landscape where incumbents defend share through scale and brand equity while challengers pursue differentiation through formulation, packaging, and channel specialization.
Soy Sauce Market
Market Dynamics and Structural Forces Shaping the Forecast Period
Several intersecting dynamics will influence how the projected growth materializes across segments and regions. Raw material economics sit at the center of cost planning. With USDA projections indicating a higher season-average farm price for soybeans ahead, manufacturers and private-label suppliers will need to monitor input-cost trajectories carefully as they set pricing, negotiate contracts, and evaluate margin protection strategies. The direction of soybean pricing can cascade into formulation cost planning, especially for producers operating on thinner margins or those dependent on domestic agricultural supply chains.
Regulatory variation across markets adds another layer of strategic complexity. Classification and labeling rules are not uniform, and the differences matter for product positioning, packaging design, and market-entry sequencing. In the United States, soy sauce is exempt from GM food labeling requirements, and nutritional labeling is not required for soy sauce products, creating a comparatively streamlined compliance environment for domestic production and imported goods sold into that market. By contrast, Taiwan classifies soy sauce as a deeply processed product and requires GMO food labeling, illustrating how the same category can face materially different disclosure obligations depending on jurisdiction. These contrasts matter for companies managing multi-market portfolios, because labeling burden, consumer communication norms, and supplier documentation expectations can differ even when the underlying product is identical.
Beyond input costs and regulation, demand-side shifts continue to reshape commercial strategy. The growing visibility of Asian cuisine in global foodservice and retail environments supports sustained interest in condiment authenticity, while premiumization trends encourage brand investment in brewing narratives, ingredient sourcing, and flavor complexity. At the same time, foodservice and industrial applications introduce volume-based demand that responds to menu innovation, institutional procurement cycles, and supply reliability. The interplay between household purchasing, food industry ingredient demand, and foodservice usage creates multiple pathways for growth, but those pathways are not equally attractive in every region. Our analysis separates these channels so that commercial leaders can match product formats, packaging sizes, and promotional strategies to the environment where they will perform best.
Soy Milk Market
Supply-side logistics also warrant attention. As production footprints expand and export flows intensify, distribution reliability, lead-time management, and regional inventory positioning become increasingly important determinants of market performance. The ability to align manufacturing capacity with demand concentration, while maintaining cost discipline amid variable input prices, will likely separate stronger operators from those that struggle to convert top-line growth into durable margin improvement.
Why This Research Matters for 2026 Strategy
Decision-makers entering 2026 need more than a retrospective snapshot. They need a structured view of where momentum is building, which competitive moves are reshaping positioning, and how external forces such as commodity pricing and regulatory variation will influence execution. This report is built to supply that view. It connects market-scale trajectory to the operational realities of segment differentiation, regional variation, input-cost exposure, and competitive behavior, enabling leadership teams to ground strategic choices in evidence rather than assumption.
For CEOs and division heads, the study offers a context for portfolio prioritization and geographic focus. For commercial and brand leaders, it provides a basis for SKU planning, premiumization pacing, and channel allocation. For procurement and supply chain executives, it frames input-cost planning and supplier strategy against a quantified demand backdrop. For corporate development teams, it highlights where scale, differentiation, and regional penetration create attractive points of entry or partnership.
The full report extends well beyond this overview. It contains the detailed segmentation data, regional assessments, competitive profiles, and scenario-level analysis that executives require to convert market intelligence into concrete action. Readers seeking the complete quantitative breakdown, granular segment evaluations, and the full set of strategic recommendations are encouraged to access the full publication through our official research portal, where the complete dataset and supporting analysis are available. In a market advancing steadily toward the high 50 billion USD range by 2032, the organizations that move earliest with informed, well-structured strategy will be best positioned to capture the value this growth creates.
For detailed analysis of this topic, please visit the official page: Soy Sauce Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com