

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Superconductor Market Hits $7.65B in 2025, Projects 9.5% CAGR to 2032

Unlocking the Next Electrification Frontier: Strategic Intelligence for the 2026 Superconductor Market
The global superconductor market has evolved from a specialized niche of scientific inquiry into a foundational pillar of advanced industrial and medical infrastructure. As we navigate 2026, enterprise leaders across energy, healthcare, transportation, and advanced manufacturing must confront a rapidly shifting landscape where material science breakthroughs intersect with supply chain complexity, regulatory recalibration, and accelerating capital deployment. To address this inflection point, PW Consulting has prepared a comprehensive market intelligence study designed to translate macroeconomic signals into actionable strategic guidance.
Our analysis establishes that the superconductor market reached an estimated value of 7.65 billion USD in 2025, expanding from 4.65 billion USD at the beginning of the last decade. The historical trajectory from 2020 through 2025 reflects resilient accumulation across mature application verticals and early-stage commercialization of next-generation materials. Looking forward, the forecast period from 2026 through 2032 projects a sustained compound annual growth rate of 9.5 percent, positioning the sector to surpass 14 billion USD by the close of the forecast window. This expansion is not merely a function of incremental demand; it represents a structural reorientation of how critical infrastructure manages power density, magnetic field generation, and transmission efficiency. For executive teams, the implication is clear: superconductor technologies are transitioning from optional innovations to strategic necessities.
The purpose of this market study is to equip decision-makers with a rigorous, operationally grounded understanding of where capital should be allocated, which partnership models will mitigate execution risk, and how regulatory shifts will reshape competitive positioning. We have deliberately structured the report as a leadership instrument rather than a static data compilation. While high-level valuation trajectories and aggregate growth parameters provide essential context, the true strategic advantage lies in understanding the mechanics behind the numbers. This preview outlines the analytical architecture of our full publication and demonstrates why access to the complete dossier is critical for evidence-based planning in 2026 and beyond.
Macro Trajectory and the 2026 Decision Window
The decade-long progression from 4.65 billion USD to a projected 8.29 billion USD in 2026 illustrates a market that has successfully navigated early adoption challenges and is now scaling through demonstrable value propositions. Historical data reveals a compound trajectory shaped by incremental commercialization in medical diagnostics, steady modernization of power transmission infrastructure, and the emergence of high-temperature architectures capable of reducing cryogenic dependency. Yet the most consequential period for strategic positioning begins now. The 2026 to 2032 forecast window captures an acceleration phase where material supply chains mature, standard-setting bodies codify performance benchmarks, and large-scale demonstration projects convert technological promise into operational reality.
Forward-looking allocation decisions require more than awareness of aggregate valuation figures. Enterprise leaders must evaluate how regional deployment patterns intersect with localized regulatory frameworks, how type-specific material availability influences project timelines, and which application verticals will capture disproportionate value as cooling infrastructure and manufacturing capacity expand. Our full report dissects these interdependencies without exposing premature sensitivity to noise, allowing strategy teams to calibrate investment horizons against realistic commercialization curves. The aggregate growth perspective is intentionally presented here as a directional signal; the granular mapping of capacity utilization, regional absorption rates, and application-specific margin structures is reserved for the complete intelligence package, ensuring that only stakeholders with direct access can operationalize the findings.
Segmentation Architecture and Hidden Value Drivers
Technology Pathways and Application Synergies
The commercial landscape is broadly organized around two material paradigms, each carrying distinct performance characteristics, cost structures, and deployment considerations. Low-temperature architectures continue to anchor established diagnostic and experimental platforms where cryogenic infrastructure is already institutionalized. High-temperature variants are increasingly favored in grid modernization, advanced magnet systems, and emerging fusion-related applications, where reductions in cooling burden translate directly into operational flexibility and total cost of ownership advantages. Understanding the interplay between these material classes is essential for procurement strategy, capital planning, and technology roadmap alignment.
High Temperature Superconductor Market
- Medical imaging applications remain a central driver of demand, leveraging stable magnetic field generation for diagnostic platforms that are increasingly optimized for patient accessibility and workflow efficiency.
- Energy power grid applications are attracting sustained engineering attention, with superconducting cables, fault current limiters, and busbar systems being evaluated for high-density urban corridors and industrial electrolysis environments.
- Transportation and research applications continue to expand the functional envelope, supporting magnetic confinement concepts, high-field experimental setups, and next-generation mobility prototypes that depend on reliable high-current conduction.
Rather than offering isolated percentage breakdowns, our full study presents a sequenced assessment of how each application vertical interacts with underlying material availability, regional engineering talent, and standards compliance timelines. This integrated view enables technology leaders to anticipate substitution dynamics, identify procurement bottlenecks, and prioritize pilot deployments where early-mover advantages are most defensible.
Geographic and Competitive Concentration Patterns
The market exhibits a moderate degree of supplier concentration, with the top three participants accounting for approximately 35 percent of aggregate revenue and the top five entities representing roughly 45 percent. This concentration profile suggests a landscape where scale advantages in tape manufacturing, specialized winding capabilities, and application-specific system integration create meaningful barriers to entry. At the same time, the remaining market share is distributed across a diverse set of specialized producers, regional fabricators, and application-focused integrators, indicating that partnership ecosystems and supply diversification strategies remain viable pathways for organizations seeking to reduce dependency risk.
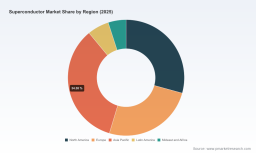
Regional revenue distribution, when viewed in aggregate, reflects the imprint of established industrial bases, research infrastructure density, and policy support environments. However, strategic value is rarely captured through regional averages alone. The complete report maps how local permitting cycles, cooling infrastructure readiness, and domestic content expectations influence the effective velocity of project execution. By holding back precise geographic splits and application-level dollar allocations within this preview, we reinforce the necessity of accessing the full dossier to inform location-specific capex decisions, sourcing commitments, and localized partnership negotiations.
Competitive Landscape and Strategic Positioning
Leadership in the superconductor sector is not defined solely by manufacturing footprint; it is increasingly determined by the ability to secure long-lead material supply, align product roadmaps with emerging application requirements, and respond rapidly to shifting regulatory and standards environments. The competitive field includes organizations that have built specialized capabilities across wire production, magnet assembly, cable integration, and system-level deployment. American Superconductor Corporation continues to advance HTS wire and power system solutions tailored for energy applications. ASG Superconductors S.p.A. has expanded its portfolio around superconducting cables, wires, and magnets, with recent momentum in open MRI platforms and commercial distribution agreements that extend its regional reach. Faraday Factory Japan remains a central figure in high-temperature superconductor tape production, supporting both magnet coil and power system applications at industrial scale. Cutting Edge Superconductors, Inc. has focused on MgB2-based conductors and alternative materials targeting cryogen-free imaging and specialized ambient-temperature conductor concepts. MetOx International operates a major North American HTS wire production facility and supplies superconducting tapes for grid and cable deployments. Advanced Conductor Technologies has developed CORC HTS wire and cable architectures designed for demanding magnet and power applications.
Superconductor Market
Recent execution signals illustrate how competitive advantage is being forged through supply chain reliability and application-specific commercialization. In 2025 and 2026, Faraday Factory Japan moved high-temperature superconductor tape into fusion prototype magnet coils and into large-scale industrial busbar projects, demonstrating the transition from laboratory-scale promise to utility-grade deployment. ASG Superconductors S.p.A. advanced its medical imaging presence through a new open MRI system launch and subsequent distribution agreements that extend commercial availability into additional territories. These developments underscore a broader market reality: winning strategies will depend on the ability to synchronize material throughput with defined project pipelines, rather than relying on speculative demand narratives.
Our full competitive analysis goes beyond corporate profiling. It evaluates partnership readiness, manufacturing scalability constraints, intellectual property positioning, and the strategic implications of recent supply announcements for future procurement calendars. The objective is to help enterprise buyers and investors distinguish between temporary capacity tightness and durable competitive moats.
Regulatory, Standards, and Supply Chain Dynamics
Policy and Standards Inflection Points
The 2026 operating environment is being reshaped by a cluster of policy and standardization actions that carry direct implications for superconductor market participants. In January 2026, the U.S. government imposed a 25 percent ad valorem duty on certain advanced computing chips and derivatives that do not support domestic manufacturing buildout. While this measure is focused on advanced computing components, its ripple effects extend into the broader advanced technology supply chain, particularly for organizations that rely on tightly integrated electronic control, simulation, and cryogenic management systems. In May 2026, the European Committee for Standardization published SIST EN IEC 61788-15:2026, establishing formal requirements for superconducting film properties and testing methods. This standardization milestone is likely to increase comparability across suppliers, accelerate qualification cycles for large infrastructure projects, and elevate the importance of documented process control within manufacturing operations.
On the support side, the Department of Commerce announced letters of intent with nine companies for two billion USD to accelerate U.S. leadership in quantum computing, with explicit support for superconducting qubit and magnet development. This funding signal reinforces a policy environment that views superconducting enabling technologies as strategic assets rather than purely commercial commodities. For enterprises operating across energy, medical, and scientific platforms, these dynamics create both opportunity and complexity: funding pathways and standards alignment can shorten time-to-value, while trade measures and qualification requirements can alter cost structures and sourcing geography preferences.
Supply Constraints and Execution Risk
Beyond policy, the most persistent operational challenge in the sector remains supply chain friction. Industry market data indicates that high-temperature superconductor adoption in fusion and grid projects is constrained by bottlenecks in REBCO tape production and helium-free cooling infrastructure. This constraint is not theoretical; it directly affects project sequencing, pilot scale-up timelines, and the economics of first-of-kind deployments. Organizations that fail to incorporate material throughput assumptions into their planning models risk underestimating lead times, overcommitting to demonstration schedules, or exposing themselves to single-source dependency.
- Tape production capacity remains a critical gating factor for large-scale grid and fusion-adjacent programs, requiring long-lead procurement commitments and close coordination between material suppliers and system integrators.
- Helium-free cooling infrastructure represents a parallel bottleneck, influencing the feasibility of cryogen-light deployments and shaping the commercial attractiveness of next-generation magnet and imaging platforms.
- Standards implementation, particularly around film property testing and performance verification, will likely increase supplier qualification burdens while also providing a clearer framework for risk allocation in multi-party projects.
Our full report translates these dynamics into scenario-based projections, helping strategy teams model how different supply expansion pathways, regulatory outcomes, and standards adoption curves could alter project economics. By withholding the precise scenario parameters and sensitivity ranges in this preview, we preserve the strategic exclusivity of the complete analysis for clients who require defensible, internally auditable planning frameworks.
How the Full Report Translates Intelligence into Execution
The PW Consulting Superconductor Market research study is built for decision-makers who need more than directional optimism. It is structured to provide a comprehensive, evidence-backed foundation for capital allocation, procurement strategy, partnership selection, and technology roadmap alignment. Key components of the full publication include:
- An integrated market sizing framework that connects historical performance with forecast drivers, enabling leadership to test assumptions against multiple commercialization pathways.
- Segment-level analysis that maps material types, application requirements, and deployment contexts to better understand where performance advantages translate into commercial advantage.
- Competitive profiling that evaluates manufacturer capabilities, supply commitments, product launch cadence, and distribution strategies, with emphasis on operational resilience rather than headline announcements alone.
- Regulatory and standards impact assessment that quantifies likely effects on qualification timelines, sourcing flexibility, and project cost structures across major markets.
- Supply chain and bottleneck analysis that identifies where capacity constraints, cooling infrastructure readiness, and material availability are most likely to influence execution risk.
- Strategic scenario guidance that supports internal planning discussions around investment pacing, vendor diversification, and go-to-market sequencing.
To maintain analytical rigor and protect client-sensitive insight, detailed regional revenue splits, application-level dollar allocations, and supplier-level capacity assumptions are presented in full only within the complete study. This deliberate design ensures that the report remains a practical internal tool for strategy formulation, procurement negotiation, and executive alignment, rather than a publicly diluted summary.
Conclusion: Strategic Imperatives for 2026 and Beyond
The superconductor market is entering a phase where scale, standardization, and supply chain maturity will determine which organizations capture durable advantage. The aggregate growth trajectory toward a 9.5 percent CAGR through 2032 signals a sector with substantial momentum, but momentum alone does not guarantee execution success. Enterprise teams must navigate concentration dynamics, evolving trade measures, new testing standards, and persistent material supply bottlenecks while simultaneously aligning investment decisions with the application verticals most likely to deliver near-term commercial returns.
This preview has outlined the strategic contours of our full market study and demonstrated why high-level figures are only the starting point for serious planning. The complete PW Consulting Superconductor Market report delivers the depth, segmentation clarity, competitive intelligence, and scenario-based guidance required to turn market potential into executable strategy. For leaders seeking to position their organizations ahead of the next wave of infrastructure modernization, medical platform innovation, and advanced magnet deployment, the full dossier provides the intelligence architecture necessary to act with confidence in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Superconductor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com