

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Steam Turbine Market to Grow at 2.8% CAGR to $31.79M by 2032, Asia Pacific Leads

Powering the Future: Strategic Insights into the Global Steam Turbine Market 2026-2032
Executive Summary: Navigating a Transitional Decade
The global energy landscape is undergoing a profound transformation. As the world balances the urgent need for reliable baseload power with the accelerating demand for sustainable solutions, the steam turbine remains a critical asset in the infrastructure toolkit. Our latest comprehensive study, the Steam Turbine Market Analysis 2026-2032, offers a granular examination of this evolving sector. This report is not merely a numerical forecast; it is a strategic roadmap designed to guide stakeholders through a period of regulatory shifts, technological innovation, and geopolitical complexity.
Based on rigorous data modeling, the global steam turbine market is projected to reach a valuation of USD 27.39 Million in 2026, growing steadily to approximately USD 31.79 Million by 2032. This trajectory reflects a Compound Annual Growth Rate (CAGR) of 2.8% over the forecast period. While the growth rate may appear moderate, the underlying dynamics driving this expansion are complex, involving a mix of legacy fleet modernization, renewable integration, and emerging power demands. Understanding the nuances behind these figures is essential for capitalizing on market opportunities.
Market Trajectory and Macro Economic Context
The historical data from 2020 to 2025 establishes a baseline of resilience. The market demonstrated consistent recovery and growth, moving from USD 22.82 Million in 2020 to USD 26.2 Million in 2025. This five-year trend underscores the enduring demand for thermal power solutions, even as the grid decarbonizes. The forecast period from 2026 to 2032 anticipates a continuation of this upward trend, driven by specific macroeconomic and industrial forces.
However, interpreting these top-line numbers requires a deeper dive into the segmentation and regional drivers that constitute the whole. The aggregate figure masks significant variations across product types, applications, and geography. Our full report dissects these components, providing the specific revenue breakdowns and volume analysis necessary for precise market sizing and opportunity assessment. Without this detailed segmentation, investment decisions risk being based on incomplete intelligence.
Key Market Drivers: Technology and Demand Shifts
Several critical factors are converging to shape the market landscape in 2026 and beyond. The most prominent driver is the surging power demand from artificial intelligence and data centers. As digital infrastructure expands, the requirement for reliable, high-capacity power generation is accelerating combined-cycle projects that incorporate steam turbines. Industry data indicates that projects targeting online operation by 2028 are already in motion, creating a immediate pipeline for turbine manufacturers.
Additionally, regulatory frameworks are playing a pivotal role in dictating market flow. In the United States, the Environmental Protection Agency finalized New Source Performance Standards for stationary combustion turbines effective January 15, 2026. These standards impose efficiency subcategorization thresholds, requiring large low-utilization units to meet design efficiency levels of 38%. This regulation directly impacts turbine design specifications and compliance strategies. Simultaneously, the U.S. Department of Energy allocated USD 475 million in June 2025 to enhance steam turbine efficiency in clean energy infrastructure, signaling strong government support for technological upgrades.
Furthermore, the regulatory environment regarding existing coal-fired units remains stringent. EPA Section 111 standards require conversion to natural gas or Carbon Capture and Storage (CCS) retrofits by 2030-2039. This mandates a strategic pivot for utilities and investors, influencing the demand for specific turbine configurations capable of handling alternative fuels or adapted cycles. These regulatory pressures create both challenges and opportunities, necessitating a detailed understanding of compliance timelines and technical requirements.
Supply Chain and Material Considerations
The manufacturing landscape is not immune to external economic pressures. Recent industry data highlights that U.S.-China tariffs have driven up prices of nickel and chromium-based alloys essential for steam turbine components. These raw material cost fluctuations impact margins and project economics, requiring careful supply chain management and hedging strategies. Stakeholders must account for these cost variables when bidding on long-term contracts or projecting financial performance.
Our analysis delves into the supply chain vulnerabilities and cost structures associated with high-grade alloys, offering insights into how leading manufacturers are mitigating these risks. Understanding the interplay between geopolitical trade policies and material costs is crucial for accurate pricing strategies and contract negotiations.
Competitive Landscape: Leaders and Innovators
The market is characterized by a mix of established multinational corporations and agile regional players. Concentration remains significant, with the top three companies holding a CR3 of 48.0% and the top five holding a CR5 of 50.0%. This concentration suggests a market where scale, technological IP, and long-term service agreements are key differentiators.
Several key companies are defining the competitive frontier through strategic orders and technological advancements:
Gas Turbine Market
- Siemens Energy AG continues to lead with a broad portfolio spanning 90-1,900 MW for conventional, combined-cycle, and nuclear applications. Recent activity includes a significant contract with Oklo for the Aurora advanced reactor power plant and selection for Applied Digital's 1 GW AI data center power project. Their record backlog of €138 billion reflects strong market confidence.
- GE Vernova Inc. supplies over 30% of global installed steam capacity. Their STF-series, including the STF-A650 and STF-D600, are central to advanced combined-cycle reheat designs, maintaining their dominance in power plant solutions.
- Mitsubishi Heavy Industries, Ltd. focuses on high-efficiency turbines for gas turbine combined-cycle plants, with the M701F series offering hydrogen co-firing capabilities, aligning with decarbonization goals.
- Doosan Enerbility Co., Ltd. has secured recent North American orders, including a contract for two 370 MW-class steam turbines for a U.S. data center project, highlighting the shift towards digital infrastructure power needs.
- Dongfang Electric Corporation Ltd. and Shanghai Electric Group Co., Ltd. remain leading Chinese suppliers, driving volume in large-scale turbine production for utility and combined-cycle systems.
- Bharat Heavy Electricals Limited serves the Indian market with turbines and generators for power generation and cogeneration.
- Toshiba Energy Systems & Solutions Corporation and Ansaldo Energia S.p.A. provide specialized solutions for combined-cycle and cogeneration plants.
- Harbin Electric Corporation leverages strong domestic and export capabilities for power generation turbines.
The competitive dynamics are not static. Recent developments in 2025 and 2026 show a clear trend towards securing long-term backlogs and entering niche high-growth sectors like nuclear and AI data centers. Our report provides a detailed competitive profiling, analyzing market share, strategic positioning, and recent M&A or partnership activities that shape the industry hierarchy. Accessing the full report reveals the specific strategic moves that are defining market leadership in this cycle.
Segmentation Insights: Types and Applications
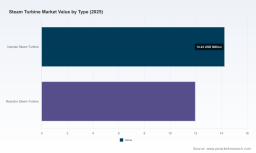
The market is bifurcated primarily by turbine type and application. The two main technological approaches are Impulse and Reaction steam turbines. Each type offers distinct advantages depending on the pressure stages and efficiency requirements of the plant. Similarly, applications range from traditional power generation to industrial oil and gas usage, and other specialized sectors.
Power generation remains the dominant application, but the proportion of revenue contributed by industrial sectors and the specific performance characteristics preferred in different regions vary significantly. The full study provides a deep dive into the performance metrics, efficiency ratings, and cost-benefit analysis of each segment. Knowing which segment is driving growth in specific timeframes allows for targeted product development and marketing strategies.
Regional Analysis and Growth Hotspots
Geographically, the market spans North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Each region presents a unique set of drivers. For instance, Asia Pacific has historically shown substantial volume due to industrialization and energy access goals. North America and Europe are increasingly driven by efficiency upgrades and compliance with stringent environmental regulations.
However, the specific revenue contribution and growth rate for each region are subject to local policy changes, capacity additions, and retirement schedules of older plants. A superficial regional overview is insufficient for strategic planning. The detailed regional analysis in our full report breaks down country-specific regulatory environments, infrastructure projects, and demand forecasts, enabling clients to prioritize markets with the highest potential return on investment.
Steam Turbine Market
Strategic Value for 2026 Decision Makers
Why is this report essential for 2026? Because the margin for error is narrowing. With regulatory deadlines approaching for coal-fired units and rapid shifts in power demand profiles, decisions made today will determine operational viability and profitability over the next decade.
Our report is designed to answer critical strategic questions:
- How should capital be allocated between new builds and retrofits given the 2030-2039 compliance windows?
- Which turbine technologies are best positioned to meet the 38% efficiency thresholds for large units?
- How do raw material cost volatilities impact long-term contract pricing models?
- Which competitors are gaining ground in high-growth niches like nuclear micro-reactors and data center power?
The insights provided are not generic observations but data-backed revelations derived from extensive primary and secondary research. We isolate the signal from the noise, focusing on actionable intelligence that drives bottom-line results.
Conclusion: Accessing Complete Intelligence
The global steam turbine market is at an inflection point. While the top-line forecast indicates steady growth, the real value lies in understanding the mechanical levers driving that growth. From the impact of EPA standards on turbine design to the supply chain implications of alloy tariffs, and the competitive maneuvers of industry giants like Siemens and GE Vernova, the landscape is rich with complexity.
This article serves as a preview of the depth and breadth of our Steam Turbine Market Research. However, the strategic numbers, detailed segmentation splits, and comprehensive competitor matrices are reserved for our full publication. To secure a competitive advantage in 2026, you need more than general trends; you need precise data.
We invite you to access the full report to unlock the complete strategic intelligence required to navigate the 2026-2032 forecast period with confidence. The detailed breakdowns of region-specific values, application-specific revenue, and type-specific market shares are available exclusively through our comprehensive study. Make informed decisions with the full picture.
For detailed analysis of this topic, please visit the official page: Steam Turbine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com