

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting VTS Report: Market Hits $267M in 2025, Projected $373M by 2032 at 4.9% CAGR

Navigating the Currents: Strategic Intelligence for the Vessel Traffic Services Market 2026–2032
The global maritime ecosystem is undergoing a structural transformation. As vessel density increases in crowded waterways and environmental regulations tighten, the operational backbone of port safety and efficiency is being recalibrated around sophisticated digital oversight. Vessel Traffic Services (VTS) have evolved from optional advisory tools into critical infrastructure for maritime domain awareness. For executives operating in shipping, port authorities, defense logistics, and maritime technology, understanding the trajectory of this market is no longer a niche concern—it is a prerequisite for capital allocation and risk management.
Vessel Traffic Services (VTS) Market
PW Consulting’s latest deep-dive research into the Vessel Traffic Services market offers a comprehensive lens on this evolution. This report is designed not merely as a statistical archive, but as a decision-support instrument for the 2026 planning cycle. By synthesizing historical performance data with forward-looking demand indicators, the study provides a clear view of where value is being created and how competitive pressures are reshaping vendor landscapes.
Market Trajectory and Growth Dynamics
The economic footprint of the VTS sector reflects a steady, resilient expansion path. Between 2020 and 2025, global revenue climbed from approximately 205.0 million USD to 267.0 million USD, signaling a consistent demand curve even through periods of broader supply chain volatility. Looking ahead, the forecast period from 2026 to 2032 projects continued upward momentum, with market value anticipated to reach 373.0 million USD by the end of the decade. This growth translates to a compound annual growth rate of 4.9 percent, a figure that underscores the sector’s maturity while highlighting its capacity for incremental innovation-driven expansion.
For strategy teams, this trajectory carries several implications. First, it indicates that VTS procurement is increasingly tied to long-term infrastructure roadmaps rather than reactive safety upgrades. Second, the steady CAGR suggests that while the market is not experiencing speculative hyper-growth, it offers predictable revenue streams for established players and stable entry points for those looking to modernize legacy systems. The revenue progression also hints at shifting procurement cycles, where integration capabilities and interoperability are becoming as valuable as hardware performance.
Structural Segmentation and Demand Drivers
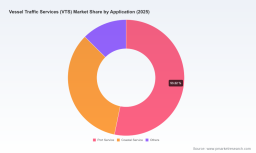
Beneath the aggregate numbers lies a nuanced demand architecture. The market is shaped by distinct operational contexts, ranging from high-density harbor environments to extended coastal surveillance corridors. Procurement decisions are increasingly influenced by the specific regulatory and operational pressures facing different maritime zones. In port-centric environments, the priority remains collision avoidance, berth scheduling optimization, and real-time situational awareness for inbound and outbound traffic. Coastal and open-water applications, meanwhile, demand broader coverage, radar integration, and the ability to coordinate across multiple jurisdictional boundaries.
The technology mix deployed to serve these needs continues to diversify. Solutions are generally categorized into integrated navigation and surveillance systems, traffic operation suites, and specialized adjunct platforms. Each category addresses different layers of the maritime oversight stack, from raw sensor data fusion to the decision-support interfaces used by VTS operators. As ports and coastal agencies modernize, we are seeing a clear preference for platforms that can ingest heterogeneous data sources—AIS, radar, meteorological feeds, and even drone or UAV inputs—into a unified operational picture. This integration requirement is reshaping vendor selection criteria and pushing traditional hardware suppliers to demonstrate software-defined agility.
Regional dynamics further complicate the demand picture. Mature maritime markets are characterized by legacy system upgrade cycles and stringent compliance mandates, while emerging hubs are often entering the VTS space as part of broader port expansion projects. This divergence means that solution providers must calibrate their go-to-market strategies to the specific lifecycle stage of infrastructure in each geography. The report dissects these regional nuances without relying on simplistic geographic splits, instead focusing on the operational triggers that drive procurement timing and budget allocation.
Competitive Landscape: Positioning and Strategic Moves
The VTS vendor ecosystem is defined by a mix of specialized maritime technology firms, large defense and industrial conglomerates, and systems integrators with deep port authority relationships. Market concentration remains moderate, with the top three and top five players holding specific portions of the revenue base, indicating that while brand recognition and installed base matter, there is room for differentiation through niche capabilities and regional partnerships.
Several leading organizations illustrate the diversity of strategic positioning in this space. Signalis, headquartered in Bezons, France, focuses on integrated VTS platforms tailored for harbor and naval base safety and security, emphasizing the intersection of commercial and defense-grade requirements. Kongsberg Gruppen, based in Norway, delivers VTS and coastal surveillance solutions through its Kongsberg Norcontrol division, serving ports and maritime authorities with a reputation for robust maritime automation. Indra Sistemas, from Spain, offers comprehensive VTS and maritime traffic management systems targeting port authorities and coastal administrations, with a strong footprint in government-linked procurement. Saab, in Sweden, provides advanced VTS and Vessel Traffic Management Information Systems for ports, waterways, and coastal regions, leveraging its broader defense and sensing heritage. Wärtsilä, based in Finland, supplies Navi-Harbour Web VTS and VTS simulation solutions that address both live traffic management and operator training scenarios. Tokyo Keiki, from Japan, manufactures VTS and coastal surveillance radar systems, including solid-state radar series, anchoring its strategy in detection hardware and sensor reliability. Frequentis, headquartered in Austria, delivers smartVTS and integrated vessel traffic management solutions for maritime authorities, with an emphasis on communication and command-center integration.
Maritime Intercom Market
Recent corporate developments signal an active consolidation and capability-building phase. In October 2025, Kongsberg announced plans to spin off its Maritime unit as an independent company, with a stock exchange listing targeted for the first half of 2026. This move may unlock focused investment in maritime technologies while allowing the parent organization to streamline its portfolio. Earlier in the year, in February 2025, Indra showcased advanced radar technology at IDEX 2025 and signed a partnership to bolster VTS capabilities, illustrating how sensor innovation and alliances are being used to strengthen competitive positioning. On the consultancy and systems integration side, Arup was appointed by the Hong Kong Marine Department in October 2025 for a comprehensive consultancy to modernize the city’s Vessel Traffic Services system. This engagement highlights the growing role of design and advisory firms in bridging operational requirements with large-scale technology upgrades, particularly in major Asian hub ports.
For procurement leaders and investors, these moves are not merely corporate news—they are indicators of where capability will concentrate in the near term. Spin-offs, partnerships, and major modernization contracts often precede shifts in pricing models, service-level expectations, and product roadmaps. The report tracks these signals and maps them against commercial implications, helping readers anticipate how vendor strategies may affect total cost of ownership and integration risk.
Regulatory and Operational Context
No analysis of the VTS market is complete without grounding it in the regulatory frameworks that shape procurement mandates. International guidelines continue to elevate the role of information services, including the provision of hydro-meteo data and route planning support for high-traffic and environmentally sensitive areas. These requirements drive demand for platforms that can not only monitor traffic but also provide proactive advisory functions.
Standardization efforts further influence market dynamics. The IALA VTS Manual provides recommendations for operator recruitment, qualifications, and training, ensuring a baseline of consistency across global operations. This has downstream effects on product design, as vendors must consider human-machine interface ergonomics, simulation-based training modules, and auditability features. In the United States, the USCG operates multiple Vessel Traffic Centers that implement mandatory reporting for vessel traffic in high-density waterways, creating a regulatory environment that favors systems capable of handling compulsory data exchange and enforcement workflows. Meanwhile, UNECE guidelines on inland vessel traffic services establish harmonized standards for inland waterways across member states, extending the VTS concept beyond coastal and port domains into river and canal networks. These regulatory threads collectively expand the addressable operational scope for VTS providers and reinforce the need for adaptable, standards-compliant architectures.
What This Research Delivers for 2026 Decision-Makers
This market study is structured to translate macroeconomic trends into actionable strategic intelligence. Beyond the headline growth figures, the report examines the operational and commercial factors that will shape procurement behavior over the next several years. It provides a detailed view of solution categories, deployment contexts, and the performance criteria that distinguish winning proposals in competitive tenders. The analysis also evaluates how vendor relationships, service models, and integration requirements affect lifecycle costs, an area often underappreciated in early-stage planning.
The research includes a rigorous competitive profiling section that goes beyond corporate descriptions to assess positioning, capability emphasis, and recent market activity. By connecting corporate developments—such as spin-offs, partnerships, and major consultancy awards—to potential shifts in product strategy and regional focus, the report helps readers anticipate supplier behavior rather than simply react to it. This is particularly valuable for organizations evaluating multi-year contracts, considering vendor diversification, or planning internal system upgrades in alignment with regulatory timelines.
In addition, the study contextualizes the market within the broader maritime technology landscape, highlighting where VTS intersects with port community systems, autonomous vessel preparation, cybersecurity requirements, and data-sharing initiatives. These adjacencies are increasingly relevant as maritime authorities seek to avoid fragmented deployments and instead build coherent digital infrastructures. The report identifies the integration pressure points that matter most and frames them in terms of risk mitigation and operational resilience.
Using the Intelligence: Strategic Imperatives for the Year Ahead
For executives preparing 2026 strategies, the VTS market presents both opportunity and complexity. The growth trajectory is solid, but the value capture is uneven. Success will depend on recognizing where demand is being driven by regulatory mandate versus operational efficiency, and where vendors are differentiating through integration, training, and lifecycle support rather than raw sensor performance alone. Organizations that align their procurement cycles with the modernization rhythm of key ports and coastal agencies will be better positioned to secure favorable terms and reduce deployment risk.
The report is designed to support that alignment. It offers a structured view of market size evolution, demand segmentation logic, competitive dynamics, and regulatory influence—without obscuring the practical considerations that determine project outcomes. By focusing on the factors that shape purchasing behavior and vendor strategy, the research equips stakeholders to make informed choices about technology selection, partnership structures, and investment timing.
To access the full segmentation detail, company profiles, regional demand analysis, and forward forecasts that underpin these insights, we invite you to explore the complete PW Consulting Vessel Traffic Services market research. The complete edition provides the granular intelligence needed to translate market direction into concrete planning decisions for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Vessel Traffic Services (VTS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com