

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
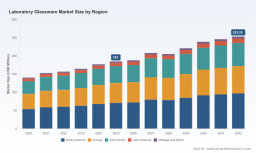
PW Consulting Lab Glassware Market Hits USD 185M in 2025 Projected to Reach 253.28M by 2032 at 4.7 CAGR

Navigating the Laboratory Glassware Market: Strategic Intelligence for 2026 and Beyond
The laboratory glassware sector stands at a critical inflection point as it moves through 2026. What was once considered a mature, commoditized market is undergoing a structural transformation driven by stringent regulatory updates, evolving end-user demands for precision and safety, and a competitive landscape that is consolidating around both premium innovation and cost-optimized manufacturing. For procurement leaders, strategy teams, and investors, navigating this environment requires more than top-line revenue projections. It demands a granular understanding of where growth is materializing, which product categories are gaining relative share, and how regional dynamics are reshaping supply chain strategies.
Our latest market research delivers exactly that intelligence. Built on a rigorous historical analysis spanning 2020 through 2025 and a forward-looking forecast extending to 2032, this report equips decision-makers with the analytical depth required to allocate capital, prioritize product portfolios, and anticipate competitive threats. The baseline year of 2025 anchors a trajectory that reveals a market demonstrating consistent resilience and measured expansion, even as macroeconomic volatility and raw material pricing fluctuations test the agility of manufacturers across the value chain.
The Strategic Imperative of 2026 Intelligence
Why does a comprehensive market assessment matter so acutely in 2026? The answer lies in the convergence of multiple forces that are simultaneously altering demand patterns, regulatory expectations, and competitive positioning. Laboratory glassware is no longer a static category of interchangeable consumables. It is becoming a strategically differentiated asset class, where material specifications, traceability features, and compliance certifications directly influence purchasing decisions in high-stakes environments such as pharmaceutical development, clinical diagnostics, and advanced academic research.
Companies that rely on outdated assumptions about regional demand or product-line growth risk misallocating resources in a market where marginal advantages in product quality, lead times, or certification readiness can translate into outsized market capture. Our research is designed to eliminate that uncertainty. By mapping historical revenue performance against forward-looking growth trajectories, we provide a clear view of how the market has evolved and where it is headed, enabling stakeholders to model scenarios with confidence rather than speculation.
Market Trajectory: A Macro View of Growth and Resilience
The overarching market narrative from 2020 through the forecast horizon is one of steady, compounding expansion. Over the past half-decade, the global laboratory glassware market has demonstrated remarkable consistency, with revenue growth compounding at a pace that reflects both the essential nature of the product category and the gradual scaling of scientific infrastructure across developed and emerging economies. The market has progressed from a baseline in the early 2020s to a position of meaningful scale by 2025, and the forward outlook suggests that this momentum will continue, albeit with year-to-year variation that rewards disciplined, data-informed planning.
The forecast period through 2032 paints a picture of sustained upward movement, with revenue projections pointing toward a substantially larger market than the one observed in the mid-2020s. The compound annual growth rate of 4.7 percent underscores a market that is neither explosive nor stagnant, but rather characterized by reliable, long-term expansion that favors organizations capable of executing consistently across procurement, manufacturing, and go-to-market functions. Currency-denominated revenue in USD millions provides a standardized lens for comparing performance across regions and product categories, ensuring that strategic comparisons are grounded in a common financial framework.
What makes this trajectory particularly relevant for 2026 is the way it interacts with operational realities. Year-over-year movement in the forecast reveals periods of acceleration and modest recalibration, reflecting the complex interplay between end-user investment cycles, raw material availability, and regional purchasing power. Organizations that internalize these patterns are better positioned to time capacity expansions, negotiate supplier contracts, and align product launches with windows of heightened demand.
Laboratory Glassware Market
Competitive Landscape: Where Consolidation Meets Innovation
The laboratory glassware market is defined by a competitive ecosystem that blends established multinational manufacturers with agile regional producers. Concentration metrics indicate that a relatively small group of leading players commands a meaningful portion of total market revenue, while a broader tier of specialized and regional suppliers competes on price, customization, and niche technical capabilities. This dual-layer structure creates both opportunities and risks: it allows buyers to source from a diverse supplier base, but it also places pressure on mid-tier manufacturers to differentiate through quality, compliance, or service agility.
Several companies exemplify the strategic directions shaping the industry today. DWK Life Sciences, headquartered in Germany, has built its reputation on premium laboratory glassware brands including DURAN, KIMBLE, and WHEATON, positioning itself at the intersection of scientific reliability and product innovation. Its recent participation in Analytica 2026 in Munich, where it highlighted new laboratory glassware innovations, signals a continued commitment to visibility and product leadership in a market that values demonstrated expertise. Earlier, in mid-2025, the company introduced DURAN protect+ coated laboratory bottles designed for enhanced shatter protection, an example of how engineered safety features are becoming a competitive differentiator rather than a secondary feature.
Across the Atlantic, Ace Glass Inc. in the United States has long been recognized as a leader in both custom and standard scientific laboratory glassware, spanning beakers, flasks, and reaction systems. Its product breadth appeals to customers who require flexible specifications without sacrificing consistency. This dual focus on customization and standardization reflects a broader industry dynamic: buyers increasingly want the reliability of catalog products alongside the option to adapt equipment to specialized workflows, particularly in complex research and pharmaceutical settings.
The Indian manufacturing base represents another critical pillar of the competitive landscape. Companies such as Borosil Scientific, Glassco Laboratory Equipments, Medilab Exports, Omsons Labs, and Hindustan Glass Works illustrate the breadth of capability present in the region. Borosil Scientific offers general laboratory glassware and consumables manufactured to USP Type 1 and ASTM standards, emphasizing compliance-driven quality. Glassco Laboratory Equipments focuses on interchangeable volumetric, filtration, and general laboratory glassware, while also engaging in targeted exhibitions to showcase premium equipment. Omsons Labs has moved toward greater traceability by updating its product offerings with QR-coded items, a practical response to the growing demand for supply chain visibility and lot-level accountability. Medilab Exports and Hindustan Glass Works round out a competitive field that serves both research and educational markets with borosilicate culture tubes, vials, test tubes, and broader laboratory supplies.
In the United States, Kimble Chase and Bellco Glass continue to reinforce the market's emphasis on specialty and integrated solutions. Kimble Chase's focus on volumetrics, chemistry glassware, and safety-coated products aligns with end-users who prioritize precision and operator protection. Bellco Glass contributes to this ecosystem as a supplier of integrated borosilicate glassware, media bottles, bioreactors, and lab equipment, appealing to customers who value a unified supply relationship across multiple equipment categories.
Glassware Market
Meanwhile, manufacturers in China such as Changde BKMAM Biotechnology and Huida Medical are expanding their footprint with laboratory glassware including flasks, cuvettes, sampling processing items, beakers, flasks, and cylinders. Their presence underscores the ongoing globalization of supply options and the importance of evaluating total cost, quality consistency, and lead-time reliability when integrating international suppliers into procurement strategies.
Standards, Compliance, and the New Operational Baseline
Regulatory and standards developments in 2026 are reshaping how manufacturers qualify products and how buyers validate performance. The emergence of prEN ISO 1042:2026, alongside DIN EN ISO 1042:2026-04, establishes updated international requirements for one-mark volumetric flasks. These standards reflect a broader push toward measurement consistency, documentation rigor, and cross-border comparability in laboratory equipment. For manufacturers, alignment with such specifications is becoming a prerequisite for credibility in markets where analytical precision is non-negotiable. For buyers, it introduces an additional dimension to supplier evaluation, one that intersects with procurement risk, inspection burden, and long-term compliance assurance.
In parallel, regional certification frameworks continue to influence market access. In India, BIS certification applies to laboratory glassware falling within its scope under Indian standards, reinforcing the need for manufacturers and importers to maintain documentation and conformity pathways that satisfy local regulatory expectations. These certification requirements are not merely administrative; they shape product roadmaps, cost structures, and time-to-market for companies seeking to serve regulated end-users in key geographies.
Clinical diagnostics adds another layer of complexity. Laboratory glassware used in clinical diagnostic tests generally falls under laboratory services reimbursement policies without specific CPT codes, meaning that the financial context for downstream use is embedded in broader service reimbursement frameworks rather than in device-level coding. This reality affects purchasing decisions in diagnostic and hospital settings by linking procurement choices to operational efficiency, throughput, and the broader economics of laboratory service delivery.
At the material level, borosilicate glass remains the primary raw material for laboratory glassware due to its thermal shock resistance, a property that continues to anchor product design and manufacturing decisions across a wide range of applications. The stability of this material foundation does not eliminate supply chain risk, but it does provide a predictable performance baseline around which manufacturers can engineer additional features, coatings, and traceability enhancements.
Inside the Report: Practical Intelligence for Execution
This market research is built to support action, not simply description. The report moves beyond headline figures to deliver the analytical architecture needed for strategic planning, commercial prioritization, and risk management. It provides a structured examination of market size and growth patterns across the historical and forecast periods, enabling readers to understand not only where the market has been but how the trajectory changes under different time horizons.
The analysis incorporates segmentation that clarifies which product types are generating meaningful revenue and how different application areas are contributing to overall demand. Rather than presenting these categories as static lists, the report frames them within the operational realities of procurement teams and product leaders, showing how shifts in relative emphasis can inform sourcing strategies, inventory planning, and new product development priorities.
Regional dynamics are examined with a similar emphasis on usability. The report contextualizes demand across major geographic areas, helping stakeholders assess where infrastructure growth, regulatory environments, and purchasing patterns are likely to influence opportunity and competition. This regional perspective is particularly valuable for organizations that must coordinate global supply strategies while remaining responsive to local market conditions.
Competitive analysis forms another essential layer. The report profiles the companies that are shaping market direction, including their strategic positioning, recent developments, and the ways in which product launches and trade presence signal deeper shifts in focus. Recent activities such as product catalog updates with traceability features, participation in major trade exhibitions, and the introduction of safety-oriented coatings are interpreted not as isolated events but as indicators of the capabilities and priorities that will influence competitive outcomes over the forecast period.
Just as importantly, the report integrates the regulatory and standards environment into a practical framework for decision-making. By connecting emerging requirements for volumetric flask specifications, certification obligations in key markets, and the reimbursement context for clinical-use glassware, the analysis helps organizations anticipate the operational impact of compliance changes before they become disruptive.
Why This Research Belongs in Your 2026 Planning Cycle
The laboratory glassware market is not defined by sudden disruption; it is defined by the accumulation of incremental advantages that separate resilient, growth-oriented organizations from those that react too late. A 4.7 percent compound growth trajectory over the forecast horizon may appear measured at first glance, but in a market with concentrated leadership, evolving standards, and divergent regional dynamics, the difference between average execution and disciplined strategy can be substantial.
This report gives strategy and procurement teams the evidence base required to make those distinctions clearly. It supports decisions about supplier portfolio design, product-line emphasis, geographic prioritization, and compliance readiness. It also provides the context needed to interpret competitor moves, such as safety-focused product launches or traceability enhancements, as signals of where the market is heading rather than as isolated updates.
The full depth of this analysis, including the detailed segmentation structure, regional breakdowns, and competitive assessment that ground these strategic conclusions, is available in the complete report. We invite you to explore the full research to access the precise data, company-level insights, and forward-looking scenarios that will inform your 2026 decisions and position your organization for the opportunities emerging through 2032.
For detailed analysis of this topic, please visit the official page: Laboratory Glassware Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com