

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Soy Sauce Market Hits $41.05B in 2025, Poised for 5.4% CAGR Through 2032

Global Soy Sauce Market Strategic Outlook: Navigating Growth, Supply Chains, and Competitive Dynamics Through 2032
The global soy sauce market stands at a pivotal juncture. As consumer tastes diversify across culinary traditions, food manufacturers scale premiumization strategies, and raw material supply chains face renewed macroeconomic pressure, the category is evolving from a staple condiment into a structured, data-driven industry arena. For executives operating in food manufacturing, distribution, or ingredient procurement, understanding the trajectory of soy sauce demand is no longer a niche exercise. It is a strategic imperative.
Our latest market research initiative delivers a comprehensive, forward-looking analysis of this landscape. Designed for decision-makers who require actionable intelligence rather than superficial summaries, the study traces performance from historical baselines through a detailed forecast window, examining where value is created, how competitive advantages are shifting, and which structural forces will dictate profitability in the years ahead. This article offers a strategic preview of the report's analytical framework and explains why its findings are positioned to support high-stakes corporate planning throughout 2026.
Macro Trajectory and Strategic Implications
The market has demonstrated sustained expansion over the recent historical period, with revenue climbing steadily from approximately 29.95 billion USD in 2020 to 35.74 billion USD in 2023, before reaching an estimated 41.05 billion USD in 2025. This progression reflects more than nominal growth; it signals deepening penetration, rising unit values in premium categories, and sustained institutional demand across both household and commercial channels. The forecast horizon carries forward this momentum with a compound annual growth rate of 5.4 percent, positioning the market at 44.69 billion USD in 2026 and advancing toward the upper echelon of the high 50 billion USD range by the close of the projection window in 2032.
For corporate strategists, this trajectory carries several operational implications. A steady mid-single-digit growth profile suggests a maturing but still expandable category where incremental share gains require deliberate positioning rather than passive tailwinds. The sustained upward path also indicates that demand is not solely tethered to population growth in traditional markets; rather, it is being reinforced by product innovation, format diversification, and the continued globalization of Asian culinary influence. Officers tasked with capacity planning, brand portfolio management, or channel expansion should treat this overarching trend as a foundational input, while recognizing that underlying momentum varies meaningfully across segments and geographies. Our research isolates those variations so leadership can allocate resources where marginal returns are highest.
What the Report Delivers: Operational Intelligence for 2026 Decision-Making
This study was constructed to function as a working document for strategy, procurement, and commercial teams. Rather than stopping at headline numbers, the report breaks down the market architecture across multiple dimensions that matter directly to execution. Readers will find structured coverage of:
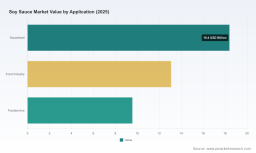
- Segment-Level Performance: Detailed assessments of product type categories, including light and dark soy sauce as well as other variants, with analysis of how each format's utility, flavor profile, and price positioning shape its respective demand curve. Household, food industry, and foodservice applications are examined separately, allowing executives to map consumption behavior to channel strategy and packaging decisions.
- Regional Dynamics: Geographic evaluation of how mature markets, high-growth regions, and emerging trade corridors contribute to total revenue. The analysis considers local culinary traditions, distribution maturity, import-export flows, and the interaction between regional purchasing power and product premiumization.
- Competitive Benchmarking: A focused examination of leading manufacturers and emerging innovators, covering operational scale, manufacturing footprints, export capabilities, and strategic moves that alter market positioning. This includes attention to facility expansion, brand architecture, and the competitive signaling evident in flagship product launches and trade presence.
- Cost and Input Environment: Assessment of the raw material backdrop, including soy commodity pricing trends and their implications for manufacturing cost structures, margin planning, and supplier negotiation timelines.
- Regulatory and Labeling Landscape: Comparative review of classification rules, GMO labeling obligations, and nutritional disclosure requirements across key jurisdictions, helping compliance and market-entry teams anticipate labeling burdens and consumer communication constraints.
- Strategic Scenarios and Forward Indicators: Synthesis of the data into decision-ready frameworks that translate market movement into potential strategic responses, including capacity timing, premiumization pacing, channel prioritization, and geographic expansion sequencing.
Each section is designed to connect directly to operational questions. Procurement leaders can reference the input-cost discussion to align hedging and sourcing windows. Commercial teams can use the segment and application breakdown to refine SKU strategy and packaging formats. Corporate development groups can leverage the competitive and regional analysis to identify where acquisition, partnership, or organic entry offers the most defensible positioning.
Competitive Landscape: Scale, Specialization, and Strategic Posture
The industry is shaped by a blend of large multinational producers, regionally dominant manufacturers, and specialized innovators pursuing differentiated flavor profiles. The concentration pattern reflects a market where scale advantages in brewing capacity, distribution reach, and brand recognition provide meaningful defensive moats, while differentiation in formulation, sourcing story, and premium positioning opens pockets of high-margin growth.
Among the most prominent players, Kikkoman Corporation continues to anchor its global footprint through a long-standing commitment to traditionally brewed production. With major facilities in the United States and a consistent export presence, the company's manufacturing expansion in its home region and overseas reflects a strategy of aligning supply capability with demand growth in key destination markets. Its planned first shipments from a new Wisconsin production facility in fall 2026 underscore the kind of capacity timing that can influence regional availability, cost competitiveness, and brand visibility well into the forecast period.
Foshan Haitian Flavouring and Food Co., Ltd. and Pearl River Bridge represent substantial production and distribution strength within China and broader Asian markets, with product portfolios extending across soy sauce and seasonings. Their scale in domestic channels and expanding international reach makes them central reference points for understanding how regional manufacturers compete on both volume and formulation variety. Lee Kum Kee Company Limited pursues a different strategic emphasis, concentrating on premium, naturally brewed varieties with worldwide distribution. This premium-oriented posture highlights the commercial opportunity that arises when brand narrative and product quality are aligned with global consumer curiosity about authentic condiment craftsmanship.
Yamasa Corporation and Shibanuma Soy Sauce Co., Ltd. further enrich the competitive picture by demonstrating the enduring relevance of specialized fermentation expertise. Their focus on naturally fermented products and established export channels illustrates how traditional production methods can be leveraged as differentiation assets in markets that reward authenticity and-consistency in flavor. At the opposite end of the scale spectrum, Bourbon Barrel Foods exemplifies a niche innovation pathway: microbrewed, barrel-aged soy sauce produced in repurposed bourbon barrels creates a distinct sensory profile that appeals to enthusiast buyers and specialty channels. While small relative to mass-market producers, such innovators signal an important structural truth about the category: differentiation in process and flavor story can command premium positioning even in a mature category.
These competitive postures do not exist in isolation. Recent activity illustrates how companies are using facility expansion, trade presence, and product visibility to reinforce market position. Kikkoman's U.S. facility milestone, with first shipments slated for fall 2026, represents a capacity event with implications for regional supply reliability and brand accessibility. Separately, broader trade activity in early 2026 highlighted the continued showcasing of leading Chinese soy sauce brands across light, dark, and standard varieties, reflecting the ongoing importance of trade platforms as both distribution touchpoints and competitive signaling arenas. Together, these movements suggest a landscape where incumbents defend share through scale and brand equity while challengers pursue differentiation through formulation, packaging, and channel specialization.
Soy Sauce Market
Market Dynamics and Structural Forces Shaping the Forecast Period
Several intersecting dynamics will influence how the projected growth materializes across segments and regions. Raw material economics sit at the center of cost planning. With USDA projections indicating a higher season-average farm price for soybeans ahead, manufacturers and private-label suppliers will need to monitor input-cost trajectories carefully as they set pricing, negotiate contracts, and evaluate margin protection strategies. The direction of soybean pricing can cascade into formulation cost planning, especially for producers operating on thinner margins or those dependent on domestic agricultural supply chains.
Regulatory variation across markets adds another layer of strategic complexity. Classification and labeling rules are not uniform, and the differences matter for product positioning, packaging design, and market-entry sequencing. In the United States, soy sauce is exempt from GM food labeling requirements, and nutritional labeling is not required for soy sauce products, creating a comparatively streamlined compliance environment for domestic production and imported goods sold into that market. By contrast, Taiwan classifies soy sauce as a deeply processed product and requires GMO food labeling, illustrating how the same category can face materially different disclosure obligations depending on jurisdiction. These contrasts matter for companies managing multi-market portfolios, because labeling burden, consumer communication norms, and supplier documentation expectations can differ even when the underlying product is identical.
Beyond input costs and regulation, demand-side shifts continue to reshape commercial strategy. The growing visibility of Asian cuisine in global foodservice and retail environments supports sustained interest in condiment authenticity, while premiumization trends encourage brand investment in brewing narratives, ingredient sourcing, and flavor complexity. At the same time, foodservice and industrial applications introduce volume-based demand that responds to menu innovation, institutional procurement cycles, and supply reliability. The interplay between household purchasing, food industry ingredient demand, and foodservice usage creates multiple pathways for growth, but those pathways are not equally attractive in every region. Our analysis separates these channels so that commercial leaders can match product formats, packaging sizes, and promotional strategies to the environment where they will perform best.
Soy Milk Market
Supply-side logistics also warrant attention. As production footprints expand and export flows intensify, distribution reliability, lead-time management, and regional inventory positioning become increasingly important determinants of market performance. The ability to align manufacturing capacity with demand concentration, while maintaining cost discipline amid variable input prices, will likely separate stronger operators from those that struggle to convert top-line growth into durable margin improvement.
Why This Research Matters for 2026 Strategy
Decision-makers entering 2026 need more than a retrospective snapshot. They need a structured view of where momentum is building, which competitive moves are reshaping positioning, and how external forces such as commodity pricing and regulatory variation will influence execution. This report is built to supply that view. It connects market-scale trajectory to the operational realities of segment differentiation, regional variation, input-cost exposure, and competitive behavior, enabling leadership teams to ground strategic choices in evidence rather than assumption.
For CEOs and division heads, the study offers a context for portfolio prioritization and geographic focus. For commercial and brand leaders, it provides a basis for SKU planning, premiumization pacing, and channel allocation. For procurement and supply chain executives, it frames input-cost planning and supplier strategy against a quantified demand backdrop. For corporate development teams, it highlights where scale, differentiation, and regional penetration create attractive points of entry or partnership.
The full report extends well beyond this overview. It contains the detailed segmentation data, regional assessments, competitive profiles, and scenario-level analysis that executives require to convert market intelligence into concrete action. Readers seeking the complete quantitative breakdown, granular segment evaluations, and the full set of strategic recommendations are encouraged to access the full publication through our official research portal, where the complete dataset and supporting analysis are available. In a market advancing steadily toward the high 50 billion USD range by 2032, the organizations that move earliest with informed, well-structured strategy will be best positioned to capture the value this growth creates.
For detailed analysis of this topic, please visit the official page: Soy Sauce Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com