

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Worldwide Josamycin Market Hits $185.5M in 2025, Projected to Reach $247.4M by 2032
By pmarketresearch, 2026-09-16
Josamycin Market Outlook 2026–2032: Strategic Intelligence for Global Pharmaceutical Decision-Makers
The global pharmaceutical landscape is entering a phase of recalibration where legacy antibiotics with specific clinical niches are being reassessed against modern economic and regulatory realities. Josamycin, a macrolide antibiotic with a decades-long therapeutic track record across Europe and Asia, now sits at the intersection of antimicrobial stewardship priorities, supply chain restructuring, and regional regulatory divergence. Our latest Worldwide Josamycin Market study is designed to translate these intersecting forces into actionable intelligence for executives navigating 2026 and beyond.
This introduction previews the strategic architecture of the full report. It outlines why the market matters today, how the commercial trajectory has evolved, which competitive and regulatory forces are reshaping value capture, and how the complete publication equips leadership teams with the granularity required to set pricing, secure supply, prioritize regional entry, and align portfolio strategy with the 2026–2032 horizon.
Why Josamycin Demands Strategic Attention in 2026
Josamycin is not a high-volume blockbuster commodity; its value lies in targeted therapeutic utility, established tolerability profiles, and sustained demand in specific clinical pathways. That positioning makes the market sensitive to nuanced shifts: changes in prescribing habits for respiratory and soft-tissue indications, the approval status of reference products in key jurisdictions, the cost economics of active pharmaceutical ingredient procurement, and the evolving posture of regulators toward macrolide-class stewardship.
For commercial and supply chain leaders, the strategic question is no longer whether Josamycin will remain relevant, but where margin pools are forming, which manufacturing nodes are becoming strategically fragile, and how regional regulatory asymmetries can be turned into competitive advantage rather than hidden risk. This is precisely the lens through which the new market study was built.
Market Trajectory: Historical Context and the 2026–2032 Forecast Window
The study anchors its forward projection in a rigorous historical baseline. Between 2020 and 2025, the global Josamycin market progressed through a cycle of contraction, recovery, and renewed expansion, reflecting both pandemic-era disruption and the subsequent normalization of pharmaceutical demand patterns. From an estimated market size of approximately 152.14 million USD in 2020, the market moved to 157.38 million USD in 2021, followed by a brief pullback to 156.28 million USD in 2022. A more decisive recovery followed, with the market reaching 177.54 million USD in 2023 and stabilizing near 177.7 million USD in 2024 before climbing to 185.5 million USD in 2025.
This historical sequence matters because it reveals the market's underlying elasticity. The rebound to 185.5 million USD in 2025 establishes a strong base year for forward modeling, while the forecast extends through 2032 to capture long-cycle planning needs in manufacturing, registration, and distribution. The base year for the study is 2025, with the forecast period running from 2026 to 2032, and all financial figures are expressed in USD millions.
Looking ahead, the trajectory points to continued growth, though not along a perfectly linear path. The forecast describes a market reaching approximately 196.58 million USD in 2026, progressing toward 210.2 million USD in 2027, then navigating a short-term moderation to 202.12 million USD in 2028 before resuming expansion toward 226.23 million USD in 2029. The outlook continues through 220.35 million USD in 2030, 227.12 million USD in 2031, and culminates at 247.4 million USD in 2032. This shape of the curve is strategically important: it suggests that growth will be governed less by uniform global expansion and more by regional timing, formulation mix shifts, and the resolution of access constraints in specific markets.
The study calculates a compound annual growth rate of 4.19 percent across the forecast horizon. That figure is not presented as a generic headline. Instead, it serves as a benchmark against which company-specific growth plans, regional entry assumptions, and pricing strategies can be stress-tested. Executives who internalize both the endpoint trajectory and the year-by-year inflection pattern are better positioned to align capacity, inventory, and commercial investment with realistic demand timing.
Geographic and Therapeutic Realities Without the Noise
A defining feature of the Josamycin market is its uneven geographic distribution and its concentration in a limited set of clinical applications. Rather than treating the market as a single global pool, the study maps where demand is structurally anchored and where it remains constrained by regulation, financing, or prescribing tradition.
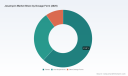
Regionally, the market is not balanced. One region alone accounts for a substantial share of total demand, underscoring the importance of Asia Pacific as a commercial anchor for Josamycin-containing products. Europe follows as a mature but uneven market, shaped by national reimbursement differences and the availability of reference formulations. Latin America, North America, and the Middle East and Africa together represent more varied opportunities, each with its own entry barriers and procurement dynamics. North America's role is particularly instructive: despite the clinical maturity of macrolide antibiotics, regulatory status and historical prescribing patterns have limited the market's footprint there, creating a case study in how access constraints shape regional revenue potential.
On the application side, the market is anchored by respiratory tract infections, which remain the dominant therapeutic driver. Skin and soft tissue infections form a second major pillar, with urogenital infections and a set of other clinical applications contributing additional, more dispersed demand. This concentration is strategically significant. It means that competitive positioning, clinical messaging, and supply planning are best understood through the lens of a few core indications rather than a broad undifferentiated demand base.
Equally important is the formulation mix. Tablet-based products command the largest share of market value, while oral suspensions and other dosage forms serve more specialized administration needs. This split matters for manufacturing strategy, as it links demand forecasting to formulation complexity, packaging requirements, and the economics of different production lines.
In the full report, these regional and application patterns are unpacked in detail. What is emphasized here is the overriding strategic message: Josamycin value is highly concentrated, and successful 2026 planning depends on understanding where that concentration creates resilience and where it exposes companies to concentration risk.
Competitive Landscape: Concentrated, Multilayered, and Regionally Distinct
The Josamycin market is characterized by meaningful concentration at the top, yet it also contains a broad layer of regional manufacturers and formulation marketers. The study uses both top-line concentration ratios and company-level profiles to show how value is distributed between originator-linked brands, generic and API producers, and regional marketers.
At the structural level, the market exhibits a moderately concentrated competitive field. The combined share of the top three players sits at approximately 54.2 percent, while the top five players extend that concentration to around 72.85 percent. This level of concentration has practical implications. It indicates that a relatively small group of firms holds outsized influence over pricing norms, supply reliability, and market signaling, while still leaving meaningful room for regional specialists and formulation-focused players to compete on access, cost, or local regulatory expertise.
Several companies illustrate the different ways participants compete in this market. In Japan, MicroBiopharm Japan Co., Ltd. operates as a producer of Josamycin API with manufacturing located in Japan, supplying pharmaceutical applications and reinforcing the country's role as a production base with strong quality infrastructure. Astellas Pharma Inc. remains a historically significant name in the market, associated with originator and marketed forms such as Josamycin Astellas and related brands, and maintaining relevance through its established commercial footprint and formulation heritage.
In Europe, Sandoz Group AG represents an important formulation presence, marketing Josalid and related Josamycin formulations in Austria and adjacent European markets. That presence matters because it ties the market to established generic and branded-generic distribution channels in a region where reference product availability, reimbursement nuances, and local procurement systems shape competitive outcomes.
China hosts a dense cluster of participants that reflect the country's broader role in API production and pharmaceutical manufacturing. Apino Pharma Co., Ltd. offers Josamycin API with GMP certifications and a focus on macrolide antibiotic supply. BrightGene Bio-Medical Technology Co., Ltd. appears in global supplier directories as a manufacturer of Josamycin API, reinforcing the market's dependence on internationally visible API sourcing channels. Shanghai Minbiotech and Shandong Minglang Chemical are listed suppliers active in international pharmacompass directories, while Guilin Pharmaceutical Co., Ltd. has historical involvement in Josamycin production and formulation development. CSPC OUYI Pharmaceutical Co., Ltd. is identified among key players in the Josamycin tablets market with manufacturing capability, and Shaoxing Minsheng Pharmaceutical Co., Ltd. and Guanghua Pharmaceutical contribute additional formulation and market-oriented activity. Sine Pharmaceutical also participates in Josamycin marketing within China.
This China-anchored manufacturing ecosystem is not just a supply detail; it is a structural feature of the market. It means that pricing dynamics, API availability, and regulatory readiness in China can influence global supply economics, especially when combined with changing trade conditions and API cost volatility.
A recent development worth noting is Promomed's launch of a real-world clinical trial of a Josamycin-based antibiotic in Russia in April 2026. While a single event does not redefine the market, it illustrates how clinical validation, local evidence generation, and regional access strategies can reopen or reinforce demand pathways in markets that operate under different evidentiary and procurement expectations.
Regulatory Friction, Supply Economics, and Market Access Constraints
No strategic assessment of the Josamycin market is complete without attention to the regulatory and supply-side forces that shape where products can be sold, at what cost, and through which channels. The study integrates these forces directly into its market dynamics analysis because they are not peripheral; they define the boundaries of growth.
One of the most consequential constraints is regulatory approval status. Josamycin remains unapproved by the FDA in North America, which restricts market access in that region and reinforces the market's regional skew. This is not merely a procedural note; it is a structural limitation that influences manufacturing allocation, portfolio prioritization, and the relative attractiveness of competing markets for firms with global supply footprints.
Antimicrobial stewardship also shapes the market's environment. Josamycin is included in the WHO List of Medically Important Antimicrobials as a macrolide, with risk management considerations related to antimicrobial resistance. That designation matters for procurement planning and clinical positioning, because stewardship frameworks increasingly influence how macrolides are used, reserved, and prioritized within healthcare systems. In practical terms, stewardship considerations can support judicious demand in core indications while also raising the importance of evidence-based positioning and responsible marketing.
Worldwide Josamycin Market
On the supply side, cost dynamics and trade policy intersect. API price fluctuations, including broader declines in pharmaceutical APIs from major sourcing regions such as China, affect Josamycin supply economics. At the same time, US tariffs implemented in 2025 on active pharmaceutical ingredient imports have increased costs and prompted supply chain reassessment for Josamycin tablets. For companies that source, formulate, or distribute in or through affected trade routes, this creates a direct pressure point on margin and continuity. The strategic response is rarely simple; it may involve sourcing diversification, regional inventory planning, formulation mix adjustments, or renegotiation of supply agreements.
In Europe, market access conditions are further complicated by product-specific developments. Marketing of the reference product Josacin 500 mg tablet has been suspended in some EU markets, an event that affects generic development comparisons and can alter the benchmark against which competing formulations are evaluated. This illustrates a broader point: in a concentrated market, changes in reference product availability can ripple through competitive strategy, pricing expectations, and launch planning.
Taken together, these dynamics mean that Josamycin market strategy in 2026 cannot be built on demand estimates alone. It requires a clear view of regulatory gateways, stewardship context, reference-product stability, API procurement economics, and trade-related cost exposure. The study treats each of these as a variable that can either constrain or enable growth, depending on how they are managed.
What the Full Study Delivers for Executive Decision-Making
The complete Worldwide Josamycin Market report is structured to support concrete decisions rather than abstract observation. It translates market scale, forecast shape, segmentation behavior, competitive concentration, and regulatory context into a decision-ready framework. The following elements are central to the publication:
- A detailed market size and forecast model extending from the 2020 historical baseline through the 2032 outlook, with the 2025 base year anchoring forward analysis and supporting year-by-year planning assumptions.
- Segment-level analysis across region, dosage form, and clinical application, enabling leaders to identify where demand is concentrated, where growth is most defensible, and where segmentation strategy can improve commercial efficiency.
- Competitive profiling of key participants, with attention to manufacturing roles, formulation presence, market positioning, and the distinction between API suppliers, branded originators, and regional marketers.
- Market concentration analysis that clarifies how much of the market is controlled by leading players and what that implies for pricing, supply resilience, and entry strategy.
- An integrated view of regulatory and macroeconomic dynamics, including FDA approval limitations in North America, WHO macrolide stewardship classification, US tariff impacts on API imports, reference product suspension effects in parts of the EU, and API price volatility from major sourcing regions.
- Practical context for supply chain planning, commercial prioritization, and portfolio alignment, especially for companies deciding where to invest, source, register, or expand distribution.
The analytical approach is deliberately detailed. Rather than stopping at aggregate market size, the report connects forecast pathways to the operational realities that determine whether growth is actually captured. For example, the difference between total market growth and company-specific growth often comes down to formulation mix, regional approval status, sourcing economics, and the behavior of reference products in competitive comparison. The study keeps those linkages explicit so that readers can translate market intelligence into operational choices.
How to Use This Intelligence in 2026 and Beyond
For strategic planning in 2026, the Josamycin market should be approached as a concentrated, regionally uneven, and regulation-sensitive opportunity set. The most effective responses will be those that align commercial ambition with the market's structural realities. Three priorities stand out.
Josamycin Tablets Market
First, regional prioritization should be evidence-based rather than assumption-driven. The market's geography is not uniform, and the largest opportunities are not necessarily the easiest to access. Companies need to assess where regulatory status, reimbursement context, reference product availability, and procurement channels support sustainable entry or expansion.
Second, supply chain design should reflect both cost and continuity risk. With API sourcing concentrated in key regions and trade policy adding new cost pressures, firms should evaluate sourcing diversification, inventory buffering, formulation flexibility, and the relative exposure of tablet-based versus other dosage forms to procurement disruption.
Third, competitive strategy should account for concentration without assuming uniformity. The top players shape norms, but regional specialists and formulation-focused firms can still win through local regulatory mastery, supply reliability, and indication-specific positioning. Understanding where the market is concentrated and where fragmentation remains feasible is essential for realistic go-to-market planning.
Closing Perspective
The Worldwide Josamycin Market study is built for leaders who need more than a single growth figure. It provides the historical grounding, forecast discipline, segmentation insight, competitive profiling, and regulatory context required to make informed decisions in a market shaped by clinical specificity, regional access differences, and changing supply economics. The headline trajectory points toward continued expansion through 2032, but the real strategic value lies in understanding the structure beneath that trajectory: where demand is anchored, how competitive power is distributed, and which regulatory and cost factors will determine who can convert market growth into durable business outcomes.
The full report develops each of these themes with the granularity needed for internal planning, investment review, and competitive positioning. For teams preparing 2026 decisions on sourcing, regional focus, formulation strategy, and market entry, the publication is intended to serve as a practical reference point—one that turns a complex and unevenly distributed market into a structured basis for action.
For detailed analysis of this topic, please visit the official page: Worldwide Josamycin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Taxi & Limousine Market Hits $312.45 Billion in 2025, 9.04% CAGR to 2032
By pmarketresearch, 2026-09-16
Strategic Navigation in the Global Taxi and Limousine Services Market: A 2026 Outlook
The global transportation landscape is undergoing a structural transformation. As urbanization intensifies and consumer expectations shift toward seamless, on-demand mobility, the taxi and limousine services sector has evolved from a traditional utility into a dynamic, technology-enabled industry. Our latest comprehensive analysis, the Worldwide Taxi and Limousine Services Market report, provides decision-makers with the strategic clarity needed to navigate this rapidly changing environment through 2032.
Built on a rigorous historical baseline spanning 2020 to 2025 and extending into a forward-looking forecast period of 2026 to 2032, this study captures the scale, trajectory, and underlying forces shaping one of the most critical segments of the urban mobility ecosystem. The findings reveal a market that has demonstrated remarkable resilience and growth, driven by digital platform adoption, evolving regulatory frameworks, and an accelerating pivot toward sustainable fleet operations. For executives, investors, and strategic planners, the report serves not merely as a data compendium but as a decision-support instrument calibrated for the realities of 2026 and beyond.
Macro Trajectory and Market Scale
The historical arc of the global taxi and limousine services market tells a story of sustained expansion. Revenue in the base year of 2025 reached approximately 312.45 billion USD, building on a consistent upward trajectory that began at 165.2 billion USD in 2020. The intervening years reflect a pattern of steady compounding: 199.54 billion USD in 2021, 243.97 billion USD in 2022, 271.35 billion USD in 2023, and 275.54 billion USD in 2024. This progression underscores the sector's capacity to absorb external shocks while capitalizing on digital transformation and rising demand for personalized ground transportation.
Looking ahead, the forecast horizon paints a similarly compelling picture. The market is projected to advance to 341.47 billion USD in 2026, climbing to 370.85 billion USD in 2027, 409.1 billion USD in 2028, and 448.62 billion USD in 2029. By the close of the decade, revenue is expected to reach 480.06 billion USD in 2030, with continued momentum pushing valuations to 539.74 billion USD in 2031 and 572.74 billion USD in 2032. These figures translate into a forecast-period CAGR of 9.04 percent, a rate that signals robust structural growth rather than temporary cyclical uplift. For organizations evaluating capital deployment, market entry, or service-line expansion, this trajectory offers a reliable quantitative anchor for long-range planning.
Force Vectors Shaping the Competitive Landscape
Growth at this scale does not occur in a vacuum. The sector is being reshaped by intersecting forces that demand strategic attention. Digital platform integration continues to redefine how passengers access taxi and limousine services, blurring the lines between traditional street-hail models and app-driven ride-hailing ecosystems. At the same time, regulatory mandates are accelerating fleet modernization, particularly around electrification and accessibility. Jurisdictions across North America have advanced zero-emission requirements targeting the 2030 to 2035 window for transportation network company fleets, while frameworks such as the California Clean Miles Standard require participating companies to achieve 90 percent of vehicle miles traveled powered by electric vehicles by 2030, with greenhouse gas emission reduction plans submitted in 2026, 2028, and 2030.
These regulatory currents are complemented by operational shifts. Government funding and grant programs are increasingly subsidizing the acquisition of wheelchair accessible vehicles, broadening the inclusivity of taxi fleets while supporting compliance objectives. Simultaneously, the premium limousine and chauffeured segments are experiencing heightened demand from corporate clients who prioritize security-focused ground transportation, professionally trained drivers, and advanced safety features. This convergence of regulation, technology, and service-quality expectations is compressing the timeline for strategic adaptation and rewarding organizations that invest early in fleet diversification, compliance infrastructure, and premium service positioning.
Competitive Dynamics and Strategic Positioning
The competitive architecture of the global market reflects a dual structure: concentrated platform leaders operating across multiple continents and a highly fragmented base of regional and local operators. At the macro level, the top three enterprises account for approximately 38.5 percent of market revenue, while the top five collectively represent 46.8 percent. This concentration indicates meaningful scale advantages among platform incumbents, yet it also leaves substantial room for niche differentiation, regional dominance, and specialized service models.
Within this landscape, several enterprises have established themselves as strategic benchmarks. Uber Technologies Inc., headquartered in San Francisco, continues to function as a global leader in ride-hailing and taxi-like services, offering on-demand taxi, premium black car, and limousine-style options through its app platform across multiple continents. Lyft Inc., also based in San Francisco, serves as a major North American ride-hailing provider, delivering standard taxi-equivalent rides, shared options, and premium Lux and Black car services that compete directly in the taxi and limousine segments. In Asia, Didi Chuxing Technology Co., headquartered in Beijing, operates as a dominant Chinese ride-hailing platform providing taxi, express, and premium limousine-style services with extensive operations across Asia and select international markets. Grab Holdings Inc., based in Singapore, leads Southeast Asia as a super-app offering ride-hailing taxi services, GrabCar, and premium options across multiple countries in the region.
The European and African corridors are shaped by Bolt Technology OÜ (Taxify), an Estonian provider delivering taxi and premium car services in over 35 countries with a focus on affordable and reliable urban mobility. Ola (ANI Technologies Pvt. Ltd.), headquartered in Bengaluru, India, stands as a major Indian ride-hailing company providing taxi, micro, and luxury cab and limousine-style services with significant domestic fleet operations. Business-focused mobility is advanced by Gett Inc., operating from Tel Aviv and London, which offers corporate taxi, black cab, and limousine options with strong presence in Europe and Israel. Addison Lee Limited, based in London, specializes in UK premium taxi and private hire and limousine services, emphasizing executive chauffeured transport and corporate contracts. Blacklane GmbH, headquartered in Berlin, functions as a global chauffeur and limousine service provider, offering premium airport transfers, hourly, and inter-city limousine services in hundreds of cities worldwide. In the Middle East, Careem, now a Uber subsidiary headquartered in Dubai, provides taxi, economy, and premium car and limousine services integrated with Uber operations. Cabify, based in Madrid, focuses on Latin American and Spanish ride-hailing with an emphasis on safe, premium taxi and private car transport and corporate positioning.
Public-sector and traditional operators remain strategically relevant. Dubai Taxi Corporation, a government-backed operator, provides standard taxi, ladies' taxi, and limousine services at Dubai airports and across the emirate. In Japan, Nihon Kotsu operates as a major taxi and limousine operator with a large fleet serving urban and airport transport needs, while Daiichi Koutsu Sangyo contributes to the domestic taxi and limousine ecosystem. On the premium chauffeured side, EmpireCLS Worldwide Chauffeured Services, based in the United States, delivers premium global chauffeured limousine and executive transportation for corporate and VIP clients, and Carey International, also US-based, maintains a long-established network of luxury limousine and chauffeured services with an international affiliate structure.
Recent developments illustrate how quickly operational realities can shift. In November 2025, the NYC Taxi and Limousine Commission reported progress on increasing electric vehicle charging infrastructure by 130 percent and making more than half of the taxi fleet wheelchair accessible. In March 2025, the NYC Council set a fiscal 2026 preliminary budget of 58.0 million USD for the Taxi and Limousine Commission to support regulatory and industry oversight. Meanwhile, in December 2024, Toronto Pearson Airport Taxi service was recognized for convenience and reliability in ground transportation, highlighting the enduring importance of service quality at key transit nodes.
Service Architecture and Mobility Segments
The market's internal architecture spans multiple service and vehicle dimensions, each with distinct growth drivers and investment implications. On the service side, online booking and ride-hailing has emerged as a central engine of transaction volume, reflecting the broader shift toward app-mediated mobility. Traditional offline taxi services continue to hold meaningful share, particularly in markets where street-hail infrastructure, medallion systems, or regulated pick-up points remain entrenched. Limousine and luxury services occupy a specialized but high-value position, supported by corporate travel, event transport, and VIP mobility requirements.
Vehicle composition is equally consequential. Economy and standard vehicles form the backbone of urban fleet operations, balancing affordability with coverage density. Executive and luxury cars cater to premium segments where comfort, branding, and driver professionalism are primary purchase drivers. Electric and hybrid vehicles represent a growing but still transitioning slice of the fleet, shaped by charging infrastructure availability, total cost of ownership calculations, and regulatory timelines. The interplay among these segments creates opportunities for operators to optimize fleet mixes, align service tiers with local demand profiles, and position for compliance-driven electrification without sacrificing service reliability.
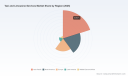
Regional variation further complicates strategic planning. Demand intensity, regulatory posture, platform penetration, and fleet composition differ materially across geographies. Asia Pacific exhibits substantial scale, supported by dense urban populations and rapid digital adoption. North America reflects a mature but evolving environment shaped by platform competition, regulatory experimentation, and premium service demand. Europe presents a patchwork of national and municipal frameworks, with strong emphasis on accessibility, emissions reduction, and urban mobility integration. Latin America and the Middle East and Africa each carry distinct dynamics tied to urbanization patterns, informal transport competition, and platform expansion strategies. Understanding these regional nuances requires granular analysis that goes beyond aggregate totals and into local demand structures, competitive intensity, and policy trajectories.
What the Full Report Delivers
This article provides a strategic preview, but the complete Worldwide Taxi and Limousine Services Market report offers the depth required for actionable decision-making. The study delivers a structured toolkit for executives who need to evaluate market entry, service expansion, fleet investment, partnership strategy, and regulatory preparedness.
Worldwide Taxi and Limousine Services Market
Inside the report, readers will find:
- A detailed segmentation analysis covering service types, vehicle categories, and regional demand structures, with forward-looking estimates that support capacity planning and revenue modeling.
- Competitive profiling of leading enterprises, including business model positioning, geographic footprint, service offerings, and strategic implications for incumbents and new entrants.
- Market concentration metrics and structural analysis that clarify where scale advantages exist and where fragmentation creates room for targeted differentiation.
- Regulatory and policy mapping that tracks electrification mandates, accessibility requirements, and oversight frameworks across key jurisdictions, enabling proactive compliance and risk management.
- Industry context on emerging demand drivers, including corporate security-focused ground transportation, wheelchair accessible vehicle adoption, and premium chauffeured service growth.
- Forecast scenarios through 2032 that help organizations stress-test strategic assumptions against multiple growth pathways and external shocks.
The report is designed to translate macro trends into operational insight. Rather than stopping at headline figures, it connects market size and growth rates to the structural factors that determine which business models thrive, which fleet strategies remain viable, and which regulatory environments will reward early adaptation. For investors, the study supports valuation context and competitive benchmarking. For operators, it informs fleet mix decisions, service-tier positioning, and regional prioritization. For policymakers and industry associations, it provides an external reference point for balancing innovation, accessibility, and sustainability objectives.
Strategic Implications for 2026 Decision-Making
Entering 2026, organizations operating in or adjacent to the taxi and limousine services market face a set of interconnected choices. The projected progression from 341.47 billion USD in 2026 toward 572.74 billion USD in 2032 indicates that demand will continue to expand, but the composition of that growth will vary by segment, region, and service model. Companies that treat electrification as a compliance burden rather than a strategic re-platforming opportunity risk falling behind peers who align fleet investment with charging infrastructure, total cost of ownership improvements, and customer expectations. Organizations that ignore the premiumization trend in corporate and VIP mobility may leave value on the table in segments where security, driver training, and service consistency command pricing power.
Regulatory planning is equally critical. With zero-emission mandates advancing across multiple North American jurisdictions and emission reduction plans coming due in 2026, 2028, and 2030 under frameworks such as the California Clean Miles Standard, operators need clear timelines and capital plans that synchronize with policy calendars. Accessibility mandates and grant-supported vehicle acquisition programs create both obligations and opportunities, particularly for fleets seeking to broaden service coverage while strengthening public-sector relationships. In parallel, the fragmented nature of the US taxi and limousine services industry, where no single company holds more than 5 percent market share and approximately 2 million businesses operate, means that localized strategy, partner selection, and service differentiation remain as important as scale.
The strategic window opened by 2026 is therefore one of alignment: aligning fleet strategy with regulatory horizons, aligning service offerings with corporate and premium demand, aligning regional expansion with local platform dynamics, and aligning investment plans with a growth trajectory that compounds at a 9.04 percent CAGR through 2032. Organizations that approach these choices with rigorous market intelligence will be better positioned to capture share, manage risk, and build durable competitive advantage.
Closing Perspective
The Worldwide Taxi and Limousine Services Market is entering a phase in which growth, regulation, and technology intersect more tightly than ever before. The historical record from 2020 through 2025 demonstrates the sector's capacity to expand under diverse conditions, while the forecast through 2032 signals that the next chapter will reward strategic precision. Platform leaders, regional operators, luxury chauffeured providers, and public-sector fleets each face distinct imperatives, but all share a common need for reliable, forward-looking intelligence.
This article has outlined the macro trajectory, the competitive architecture, the regulatory and operational force vectors, and the strategic questions that define 2026 decision-making. The full report goes further, supplying the segmentation detail, competitive profiles, regulatory mappings, and forecast structure required to convert strategic intent into executable plans. For executives and analysts who need to move beyond headlines and into the operational specifics that drive investment, partnership, and fleet decisions, the complete study provides the necessary foundation.
Ride Sharing Market
The mobility market will continue to evolve at the pace of technology, policy, and consumer expectation. Organizations that equip themselves with a clear, evidence-based view of that evolution will be best prepared to navigate the opportunities and constraints ahead. We invite decision-makers to consult the full Worldwide Taxi and Limousine Services Market report for the comprehensive intelligence needed to act with confidence throughout 2026 and the forecast period beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Taxi and Limousine Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Low-Power Solid State Microwave Generator Market Hits $684.83M in 2025, Forecast 13.52% CAGR to $1.66B by 2032
By pmarketresearch, 2026-09-16
Navigating the Next Wave: Strategic Intelligence for the Worldwide Low-Power Solid State Microwave Generator Market (2026–2032)
The global industrial landscape is undergoing a quiet but decisive shift in how energy is delivered at the component level. Across semiconductor fabrication, medical device sterilization, plasma generation, and precision industrial heating, the reliance on legacy magnetron-based systems is giving way to solid-state microwave generators that offer frequency agility, tighter thermal control, and modular serviceability. For technology buyers, systems integrators, and capital allocators, this transition represents more than a component swap. It signals a structural reconfiguration of supply chains, regulatory compliance pathways, and performance benchmarks that will define competitive positioning through the end of the decade.
Our newly released Worldwide Low-Power Solid State Microwave Generator Market study is designed to translate this complexity into decision-ready intelligence. Built on a rigorous five-year historical baseline and extended through a seven-year forward horizon, the analysis provides a structured view of demand drivers, technology substitution patterns, and regional deployment rhythms. This overview outlines the strategic contours of the market, demonstrates why low-power solid-state microwave architecture matters for enterprise planning in 2026, and explains how the full report equips leadership teams to act with precision rather than speculation.
Why 2026 Is a Defining Inflection Point
The commercial case for low-power solid-state microwave generators rests on a convergence of performance engineering and process reliability. Unlike conventional magnetron architectures, solid-state designs deliver narrower frequency bandwidth, more predictable heating patterns, and granular power modulation. These attributes are not merely technical niceties; they are becoming operational prerequisites in applications where uniformity, repeatability, and compliance documentation directly affect yield, product safety, and audit readiness.
In food engineering and related thermal processing sectors, regulatory expectations increasingly emphasize stable heating patterns and predictable cold-spot behavior for shelf-stable production. Solid-state architectures address this requirement with frequency stability that materially exceeds the broader variability associated with magnetron systems. This precision supports consistent process control and reduces the risk of under-processing or hot-spot degradation. At the same time, industrial users are tightening energy efficiency targets, and solid-state platforms with advanced semiconductor technologies are enabling compact, high-efficiency designs that align with decarbonization roadmaps and zero-emission process ambitions.
For decision-makers evaluating capital projects, equipment roadmaps, or supplier partnerships in 2026, the strategic question is no longer whether solid-state microwave technology is gaining relevance. The question is how to sequence adoption, where to prioritize frequency agility versus power scalability, and which application domains will absorb incremental capacity first. The answers require more than product-level comparisons. They demand a market-wide lens that connects technology maturity, application readiness, and regional deployment dynamics.
Macro Trajectory and the Shape of Demand Growth
The market’s recent trajectory reflects a sustained acceleration that extends well beyond a post-cycle recovery. Historical revenue progression from 2020 through 2025 demonstrates a consistent upward path, with overall market expansion gaining momentum each year as low-power solid-state generators move from specialized R&D and laboratory environments into broader industrial and scientific adoption. The baseline momentum carries into the forecast period, where the total market valuation is projected to scale from approximately 771 million USD in 2026 to over 1.66 billion USD by 2032.
This growth path is underpinned by a compound annual growth rate of 13.52 percent across the 2026 to 2032 forecast window, a pace that signals durable rather than sporadic demand. Importantly, the expansion is not being driven by a single application surge or a single geography. Instead, it reflects staggered adoption across multiple end-use environments, where solid-state benefits are being evaluated against magnetron incumbency, service requirements, and total cost of ownership.
From a strategic standpoint, this trajectory matters because it frames the window of opportunity. Organizations that anticipate capability needs, align sourcing strategies, and prepare integration pathways early can capture advantages in supply continuity, product differentiation, and application-specific customization. Those that wait for mature price compression may find themselves competing in a more crowded and less differentiated environment. The report’s forward modeling is structured to help readers identify where growth concentration is forming and how the pace of adoption may shift as technology maturity and regulatory expectations evolve.
Application and Technology Architecture: Where Value Is Being Created
Low-power solid-state microwave generators occupy a distinct position in the broader RF energy ecosystem. They are typically engineered for outputs below the multi-kilowatt thresholds associated with large-scale industrial heating, and are instead oriented toward laboratory, R&D, plasma, precision medical, and scientific processes that require controlled energy delivery, modular serviceability, and repeatable performance. This positioning shapes both the technology roadmap and the commercial logic of the market.
On the technology side, the competitive center of gravity is increasingly defined by semiconductor device choices and thermal management architectures. Gallium nitride-based designs are emerging as a key enabler for high-efficiency, compact solid-state microwave generators in low-power RF energy applications, offering a combination of performance density and efficiency that supports air-cooled and compact form factors. At the same time, laterally diffused metal oxide semiconductor technology continues to play a meaningful role in specific OEM and industrial module designs, particularly where liquid cooling, distributed software architecture, and modular scalability are prioritized for robustness and flexibility. The market is therefore not moving toward a single technological winner-takes-all outcome. It is evolving into a structured landscape where application requirements, cooling constraints, power levels, and service models determine which semiconductor and system architecture is most appropriate.
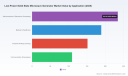
On the application side, demand is distributed across several high-value domains rather than concentrated in one dominant vertical. Semiconductor and electronics processing represents a critical demand center, where precision plasma and process control requirements reward frequency stability and modular generator designs. Medical and healthcare applications form another substantial pillar, driven by sterilization, treatment, and scientific use cases that depend on controlled energy delivery and consistent operational profiles. Industrial heating and drying, along with communication and aerospace-related RF energy needs, add further layers of demand, each with distinct performance tolerances, duty cycles, and integration requirements. The diversity of application pull is one of the market’s most important strategic features: it reduces dependence on any single end-use cycle and creates multiple pathways for incremental adoption as users gain confidence in solid-state reliability and process outcomes.
This application breadth also means that competitive advantage will increasingly come from domain-specific engineering rather than generic component supply. Generators optimized for one environment may not translate cleanly into another without adjustments in frequency accuracy, cooling architecture, protection features, or software-controlled power management. The full study maps these application-technology intersections in detail, helping readers understand where customization delivers differentiable value and where standardization can still support scale.
Worldwide All Solid State RF Power Supply Market
Geographies, Competitive Intensity, and the Emerging Supply Map
The regional distribution of demand and supply is shaping the market’s commercial dynamics in ways that matter for sourcing, localization, and market-entry strategy. Asia Pacific, North America, and Europe together represent the largest share of revenue activity, reflecting the concentration of advanced manufacturing, research infrastructure, and industrial processing capacity in these regions. Latin America and the Middle East and Africa contribute more modest but strategically relevant demand footprints, often tied to specialized industrial, scientific, or healthcare deployments rather than broad mass-market consumption.
This regional structure does more than describe where revenue is generated. It also indicates where engineering support, after-sales service, compliance documentation, and localized integration capabilities will become differentiating factors. In markets with strong R&D and semiconductor processing ecosystems, buyers expect generators that can be integrated into complex process lines, maintained efficiently, and validated against application-specific requirements. In regions with growing industrial modernization agendas, demand may be increasingly influenced by equipment accessibility, service coverage, and total cost of ownership rather than by premium feature sets alone.
Competitive intensity is already evident. The market is not a duopoly or a fragmented low-barrier environment; it is a moderately concentrated space where established RF and microwave technology providers, semiconductor-driven innovators, and OEM-focused module manufacturers are competing on precision, reliability, service architectures, and application alignment. Concentration ratios indicate that the top three players account for a substantial share of market revenue, while the top five extend that footprint even further. This level of concentration suggests that scale, brand trust, and proven application track records still matter significantly, even as new entrants and product-line expansions keep the field dynamic.
Several companies illustrate the strategic diversity now shaping the market. SAIREM offers low-to-medium power solid-state generator models designed for R&D, laboratory, plasma generation, and industrial processes, with patented auto-tune functionality and industrial-grade reliability. Crescend Technologies has positioned itself around solid-state RF microwave generators as alternatives to magnetron systems, emphasizing frequency-agile solutions for industrial, scientific, and laboratory applications with a broader focus on decarbonization and zero-emission process support. Elite RF LLC supplies GaN-based generators with modular, field-repairable designs suited for production environments, plasma, CVD, and RF energy applications, reinforcing the serviceability theme that many industrial buyers now prioritize.
MKS Instruments contributes rack-mountable, water-cooled solid-state microwave generators with precise power and frequency control for industrial, scientific, and research use, while LEANFA Srl, as part of the Muegge Group, designs and manufactures solid-state OEM generators and power amplifiers for ISM applications, including high-power module architectures using LDMOS technology with liquid cooling and distributed software design. RFHIC Corporation offers GaN-based solid-state generators for RF energy with high-efficiency, air-cooled low-power models for heating and plasma applications. Fricke & Mallah Microwave Technology provides compact, water-cooled solid-state generators with advanced protection features for industrial heating and plasma processes. Chengdu Wattsine Electronic Technology Co., Ltd. produces a low-power solid-state generator series covering multiple ISM frequencies for medical, plasma, and broader ISM applications. Qualwave Inc. supplies solid-state microwave power generators for varied applications, and Alaris Kuhne offers microwave power generators with high frequency accuracy across lower and mid-power ranges.
Recent product and market developments reinforce the sense of momentum. In late 2025, one high-performance GaN-based offering expanded scalability up to kilowatt levels across a wide frequency range for test, heating, medical, and industrial systems. Earlier product launches introduced new LDMOS-based modules with liquid cooling and distributed software architecture for enhanced robustness, alongside GaN-based generator lines featuring field-repairable design, automatic power functions, and preventive alarm supervision. Complementary scientific reviews have also highlighted the growing importance of solid-state microwave generators in improving uniformity and efficiency in food heating applications, signaling that application-level validation is becoming part of the broader commercialization narrative.
What the Full Study Delivers for Decision-Makers
This report is built to support practical strategy work rather than abstract market commentary. It integrates historical performance, forward projections, segmentation logic, company-level profiling, and industry context into a single decision framework.Leadership teams can use the analysis to pressure-test assumptions about adoption timing, technology substitution, supplier selection, and regional prioritization.
The study includes detailed coverage of:
- Market sizing and growth trajectory across the historical and forecast periods, with a clear view of how revenue scales through 2032
- Technology and application segmentation that clarifies where demand is forming and which technical attributes matter most in each context
- Regional demand patterns that help identify where adoption is most advanced and where opportunity is still unfolding
- Competitive landscape analysis that profiles leading participants, their product positions, and the strategic implications of market concentration
- Recent product launches, technology expansions, and application-focused research developments that signal near-term market direction
- Regulatory and standardization considerations that influence heating uniformity, process control, and compliance readiness for relevant end-use sectors
- Material and semiconductor technology context, including the role of GaN and LDMOS in shaping efficiency, cooling requirements, and form-factor decisions
Importantly, the report is structured to support multiple decision contexts. For product and R&D leaders, it offers a grounded view of the technology attributes and application requirements that are shaping buyer expectations. For procurement and supply-chain teams, it provides context on competitive concentration, supplier diversity, and the practical implications of modular, serviceable designs. For strategy and corporate development functions, it frames where growth is likely to accumulate and how the market’s structure may evolve as solid-state solutions move further into mainstream industrial and scientific use.
How to Use This Intelligence in 2026
The strategic value of this study lies in its ability to convert macro momentum into actionable prioritization. In 2026, organizations should resist treating low-power solid-state microwave generators as a single procurement category. The market is too application-dependent, too technology-differentiated, and too regionally varied for one-size-fits-all planning. Instead, the most effective use of this intelligence is to align investment and sourcing decisions with the specific performance, compliance, and service requirements of each target deployment environment.
For companies evaluating entry, expansion, or supplier consolidation, the report’s segmentation and competitive profiles can help identify where incumbents have強勢 positioning and where gaps in application-specific optimization, service coverage, or frequency agility may create room for differentiation. For organizations already participating in the market, the forward trajectory and technology context can inform roadmap decisions, capacity planning, and partnership strategies. For investors and advisors, the concentration data and development pipeline provide a basis for assessing where value creation is likely to be most durable.
Because the full report contains the detailed segmentation values, regional breakdowns, application-level estimates, and company-specific assessments that underpin these strategic conclusions, it is best used as a working reference rather than a standalone summary. The macroscopic direction is clear; the operational precision required to act on it is detailed in the complete analysis.
Worldwide Low-Power Solid State Microwave Generator Market
Closing Perspective
The worldwide low-power solid state microwave generator market is at a stage where technology maturity, application validation, and competitive differentiation are converging to create real strategic optionality. Demand is expanding on a solid growth trajectory, technology choices are sharpening the definition of value, and the competitive field is active enough to reward companies that can combine precision, reliability, and serviceable architecture with clear application alignment.
For leaders planning around 2026 and beyond, the opportunity is not simply to track a growing market but to position within it with clarity. The complete study provides the depth required to do that: historical grounding, forecast structure, segmentation insight, competitive context, and the industry developments that connect technical progress to commercial outcomes. The executive summary above offers the strategic frame; the full report delivers the operational intelligence needed to turn that frame into concrete decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Low-Power Solid State Microwave Generator Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Fencing Lame Market Hits $52.18M in 2025, Projected 4.15% CAGR Through 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence in the Worldwide Fencing Lame Market: Navigating Growth, Regulation, and Competitive Shifts Through 2032
Executive Summary
The global fencing lame market represents a highly specialized yet strategically vital segment within athletic equipment manufacturing. As competitive fencing continues to professionalize, standardize, and expand across continents, the conductive jackets, bibs, and mask covers that form the core of scoring apparel are undergoing rapid material innovation, regulatory recalibration, and supply chain consolidation. Our latest Worldwide Fencing Lame Market study delivers a comprehensive, data-forward blueprint for executives, procurement leaders, and strategic planners who must make informed decisions in 2026 and beyond. Rather than offering static snapshots, this research maps the trajectory of market evolution, dissects the competitive architecture, and quantifies the operational implications of newly enforced international standards.
Electric Fencing Market
From a historical baseline spanning 2020 through 2025, the market has demonstrated consistent upward momentum, transitioning from early-cycle stabilization into a phase of accelerated commercial expansion. By the close of the base year, total industry revenue had solidified at a materially higher level than the early 2020s, reflecting sustained institutional procurement, rising club participation, and the gradual professionalization of amateur circuits. Looking ahead, the forecast window from 2026 through 2032 projects a compound annual growth rate of 4.15 percent, translating global valuation into the hundreds of millions of USD by the decade's end. This growth trajectory is neither uniform nor automatic; it will be shaped by regulatory compliance costs, raw material economics, regional distribution maturity, and the strategic positioning of a concentrated supplier base.
For leadership teams evaluating product roadmaps, inventory strategies, partnership frameworks, or market entry options, the study functions as a decision-grade instrument. It provides the structural clarity required to separate durable demand signals from short-term promotional cycles, while highlighting where compliance, certification, and material engineering intersect with commercial viability.
Historical Trajectory and Forward-Looking Growth Dynamics
The market's historical progression tells a story of steady institutionalization. Over the past half-decade, revenue generation has moved beyond cyclical tournament-driven spikes toward more predictable, volume-backed demand. This shift reflects the broader maturation of fencing as a structured sport with standardized training pipelines, formal club networks, and increasingly sophisticated competitive calendars. The transition from early 2020s valuation levels to the 2025 baseline underscores how procurement patterns have stabilized and expanded across both professional and developmental tiers.
The forward-looking horizon introduces a more complex dynamic. Growth will be propelled by sustained adoption of competition-grade apparel, but it will also be filtered through regulatory friction, material cost volatility, and the operational burden of homologation. Stakeholders must therefore interpret top-line projections not as guaranteed outcomes but as conditional pathways that depend on compliance readiness, supply chain agility, and region-specific adoption pacing. The study isolates these variables and maps their interplay, enabling executives to stress-test assumptions rather than rely on aggregate figures alone.
Report Architecture: Practical Intelligence for 2026 Decision-Making
This research is engineered for operational use rather than passive reading. It structures its analysis around the dimensions that directly affect sourcing, product development, pricing strategy, and market positioning. The report delivers actionable visibility across the following operational axes:
- Market sizing and trajectory analysis anchored in a defined historical window and extended through a long-range forecast period, allowing planners to align budgeting cycles, production scheduling, and inventory strategies with credible demand curves.
- Segment-level breakdowns that clarify how product configurations, material compositions, application environments, and end-user categories shape revenue distribution, purchasing frequency, and margin potential without exposing the granular figures reserved for the full dataset.
- Competitive profiling that evaluates manufacturing heritage, geographic footprint, certification status, product engineering emphasis, and distribution reach across the firms actively shaping supply and pricing.
- Regulatory and technical dynamics that translate material standards, electrical resistance thresholds, impact resistance requirements, and homologation procedures into commercial implications for compliance, cost structure, and time-to-market.
- Strategic scenario framing that helps executives anticipate how policy updates, licensing frameworks, and label mandates may reshape supplier economics and procurement planning.
Each section is designed to feed directly into strategic planning workflows. Procurement teams can use the segmentation architecture to align specifications with end-user requirements. Product leaders can benchmark material choices against performance and compliance expectations. Commercial teams can interpret competitive positioning to identify whitespace, partnership opportunities, or distribution gaps. By integrating quantitative direction with qualitative structural analysis, the report transforms market intelligence into executable insight.
Regulatory Regimes and Technical Standards as Strategic Variables
The fencing lame market is unusually sensitive to rule-driven specification changes. International governing bodies dictate not only competitive eligibility but also the technical thresholds that manufacturers must meet to place gear on approved circuits. Recent regulatory activity has introduced meaningful operational considerations for suppliers, distributors, and institutional buyers.
Material rules now require conductive thread architecture in both warp and weft directions, with electrical resistance measured under defined testing conditions not exceeding five ohms between any two points. These specifications directly influence fabric engineering, production consistency, and quality assurance workflows. At the same time, safety standards require FIE-approved fencing clothing and lames to meet 800N perforation resistance thresholds for international competition, a substantial elevation from the 350N level associated with non-FIE gear. For manufacturers, this means that compliance is not a documentation exercise but a material and structural commitment that affects design, sourcing, and production validation.
Recent governance updates have also escalated the administrative and financial footprint of participation in approved supply channels. Supplier registration now carries annual licensing obligations, per-product-type fees, and mandatory labeling requirements for homologated equipment, including jackets and clothing. These requirements influence unit economics, minimum viable scale, and the cost of maintaining an approved catalog. For market entrants or smaller producers, the cumulative burden can function as a barrier that reinforces incumbency advantages. For established manufacturers, it creates an opportunity to differentiate through certification readiness, consistent homologation performance, and transparent compliance documentation.
Additional regulatory attention has extended to apparel presentation and identity standards, including updates to mask drawings and national logo guidelines for fencing clothing and uniforms. While these changes may appear cosmetic, they influence design pipelines, print integration, and manufacturing workflows for lame-integrated apparel. Companies that proactively align design systems with updated visual and structural guidelines can reduce rework cycles and accelerate time-to-market for season releases.
The study integrates these dynamics into a cohesive operational narrative. Rather than treating regulation as an external footnote, it evaluates how compliance architecture interacts with material selection, production planning, certification sequencing, and commercial pricing. This approach ensures that decision-makers understand not only what the rules are, but how they reshape competitive advantage.
Competitive Landscape: Concentration, Capability, and Strategic Positioning
The market's competitive architecture is marked by meaningful concentration. A limited group of firms accounts for a disproportionate share of industry revenue, reflecting the specialized nature of high-performance conductive apparel, the importance of FIE registration, and the procurement preferences of clubs, federations, and professional circuits. This concentration shapes pricing power, supplier relationship dynamics, and the barrier to entry for new manufacturers seeking to compete on technical merit alone.
Within this environment, competitive differentiation emerges through several intersecting capabilities. Manufacturing heritage and in-house production control remain strategically significant, particularly for firms that can manage material selection, conductive fabric integration, and quality validation internally. German and Central European producers have historically emphasized ultralight construction, washable electric jacket designs, and premium stainless steel or conductive fabric solutions tailored to top-level competitors. Their positioning often centers on performance consistency, international registration status, and institutional trust accumulated through long-term use in elite circuits.
Hungary-based manufacturing has carved a distinct role by combining full-range gear production with federation supply relationships and FIE partnership status. This model reinforces both volume stability and credibility in competition-grade equipment. UK-based specialists contribute through established competition equipment distribution, worldwide fulfillment, and product focus on foil and other lame configurations, reinforcing their role as accessible competitive gear providers for a broad international customer base.
In the United States, distributors and suppliers function as critical commercial conduits, aggregating premium brands, maintaining FIE-registered supply channels, and serving clubs, schools, and individual competitors through established retail and B2B networks. Their strategic value lies in distribution reach, brand curation, and the ability to connect end users with certified product lines. Meanwhile, Chinese manufacturers have expanded their footprint by producing foil, sabre, and epee lames alongside conductive fabric solutions, often emphasizing copper-tin combined conductive materials and full-equipment supply capabilities. Their growth reflects broader manufacturing scale, cost efficiency, and increasing integration into globally registered supply networks.
French manufacturing presence and additional registered producers further complicate the landscape by contributing to regional supply diversity and specialty apparel integration. Across these players, the differentiating factors include FIE registration status, material engineering expertise, production geography, distribution model, and the ability to satisfy both competition-grade and developmental-tier requirements.
The report assesses these companies not as isolated profiles but as elements of a competitive system. It examines how concentration influences procurement leverage, how certification and registration shape market access, and where capability gaps or distribution strengths create strategic opportunities. This framing allows executives to evaluate supplier reliability, partnership potential, and competitive vulnerability with greater precision.
Worldwide Fencing Lame Market
Regional Expansion and End-User Demand Architecture
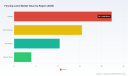
Market growth will not distribute evenly across geographies or customer categories. Regional demand patterns reflect differences in club infrastructure, federation activity, tournament density, procurement funding, and the pace at which competitive programs adopt standardized equipment. Europe continues to represent a substantial share of market activity, supported by established club networks and long-standing competitive traditions. North America contributes a significant but separately structured demand environment, shaped by institutional procurement, retail distribution, and school- and club-level participation. Asia Pacific reflects a growing adoption curve, driven by expanding program development and increasing integration into international competitive pathways. Rest of World demand remains smaller in scale but strategically relevant as emerging programs formalize equipment procurement and seek compliant, competition-ready gear.
End-user demand also follows a layered architecture. Clubs and schools form the most volume-relevant segment, reflecting recurring procurement cycles, training-program expansion, and the need for durable, compliant equipment at accessible price points. Professional athletes represent a narrower but high-specification demand pool, often prioritizing ultralight construction, washable electric jacket performance, and proven scoring reliability. Amateur enthusiasts contribute additional volume through developmental participation, though their purchasing behavior is more fragmented and more sensitive to price and availability. Understanding how these end-user categories interact with product type, material composition, and regional procurement norms is essential for aligning product lines, inventory planning, and channel strategy.
Strategic Takeaways for Leadership Teams in 2026
As the market moves through a period of regulatory tightening, material specification refinement, and competitive consolidation, the strategic implications are clear. First, compliance architecture is no longer peripheral; it is a core component of product viability and supplier credibility. Organizations that anticipate homologation requirements, certification timing, and labeling costs will be better positioned to protect margins and maintain uninterrupted supply.
Second, material and engineering decisions must be evaluated against both performance and regulatory thresholds. Conductive fabric composition, resistance consistency, and impact resistance specifications directly influence eligibility, customer trust, and product lifecycle value. Companies that treat these parameters as strategic levers rather than technical checkboxes can create durable differentiation.
Third, competitive concentration means that sourcing and partnership decisions carry heightened importance. Procurement leaders should evaluate not only unit economics but also registration status, distribution reliability, certification continuity, and the capacity to support institutional and professional programs at scale. Distributors and manufacturers alike must assess where their value proposition aligns with the evolving expectations of clubs, federations, and competition circuits.
Finally, growth planning should be scenario-based rather than linear. While the market's medium-term trajectory points toward continued expansion in global valuation, realized outcomes will depend on regional adoption pacing, regulatory burden distribution, raw material economics, and the strategic response of incumbent suppliers. Leadership teams that integrate these variables into forecasting, capacity planning, and channel strategy will be better equipped to convert market potential into operational results.
Conclusion: Why This Study Matters Now
The Worldwide Fencing Lame Market is entering a phase in which technical precision, regulatory readiness, and competitive positioning converge to define commercial success. The study provides the structural intelligence required to navigate that environment with confidence. It combines historical context, forward-looking growth direction, segmentation clarity, competitive assessment, and regulatory analysis into a single decision-support framework. For executives planning product strategy, procurement alignment, market entry, or partnership development in 2026, this research offers the depth needed to act decisively while avoiding overreliance on surface-level indicators.
To access the full dataset, detailed segmentation splits, company-by-company profiling, regulatory impact analysis, and the complete forecast architecture, we invite you to consult the complete report through our official research portal. The complete publication is designed to serve as a working intelligence asset for strategic planning cycles, procurement reviews, and competitive benchmarking initiatives throughout the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Fencing Lame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Sound Card Revenue Hits $517.25M in 2025, Poised to Reach $771.6M by 2032 at 5.88% CAGR
By pmarketresearch, 2026-09-16
Strategic Sonic Shifts: Why the Worldwide Sound Cards Market Demands Your Attention in 2026
The global audio landscape is undergoing a subtle yet profound transformation. What was once considered a commoditized component of computing hardware has evolved into a critical differentiator for user experience across gaming, professional broadcasting, and home entertainment ecosystems. For enterprise leaders, investors, and product strategists, understanding the trajectories within the Worldwide Sound Cards Market is no longer optional—it is a prerequisite for informed capital allocation and product roadmap planning. As we navigate through 2026, the convergence of semiconductor innovation, shifting consumption habits, and supply chain complexities creates a unique window for strategic advantage.
This article serves as a strategic overview of the market forces at play, drawing upon the comprehensive analysis found in the latest PW Consulting market research. Below, we outline the macro-economic contours, the competitive intensity, and the operational dynamics that will define value creation in this sector over the coming years.
Executive Summary: Market Trajectory and Aggregate Outlook
The Worldwide Sound Cards Market has demonstrated resilience and steady growth over the past five years, recovering robustly from early pandemic-era fluctuations to establish a stable upward trend. Based on historical data spanning from 2020 through 2025, the market has matured into a consistent revenue generator, setting the stage for a projected expansion phase through 2032. The aggregate valuation reflects a healthy demand curve, driven by both replacement cycles in consumer electronics and new adoption in high-fidelity professional environments.
Looking forward, the forecast period from 2026 to 2032 indicates sustained momentum. Analysts project a compound annual growth rate (CAGR) of approximately 5.88 percent during this horizon. This growth is not merely a function of unit volume but is increasingly tied to value-added features, higher fidelity standards, and the integration of advanced processing capabilities within audio interfaces. The revenue trajectory suggests that by the end of the forecast period, the market will reach significant scale, underscoring the enduring relevance of dedicated audio hardware even as integrated motherboard solutions become more sophisticated.
For stakeholders, this top-line growth masks significant variability beneath the surface. Success in this environment requires more than just observing aggregate numbers; it demands a granular understanding of where value is accruing. Is the growth coming from the enthusiast gaming segment pushing for higher signal-to-noise ratios, or is it driven by the professional studio market adopting multichannel solutions for remote production workflows? The strategic implications differ vastly depending on the answer. Our full report dissects these currents to reveal where specific investment opportunities lie, without relying solely on broad-stroke assumptions.
Market Segmentation: Navigating Type, Application, and Geography
While the macro view provides direction, the real strategic insights reside within the segmentation data. The market is not a monolith; it is a composite of distinct segments with unique drivers, barriers to entry, and profit margins. Understanding the interplay between these segments is crucial for targeted marketing and product development.
- Product Type Dynamics: The market is broadly divided between external peripherals and internal expansion cards. External solutions have gained traction due to plug-and-play convenience and the rise of USB-based high-fidelity interfaces, while internal PCIe cards remain dominant in specific enthusiast and gaming builds where latency and integration are paramount. The balance between these two categories shifts based on OEM partnerships and consumer preference for upgradeability versus convenience.
- Application Verticals: End-use application is a primary determinant of value. The gaming sector continues to be a major revenue contributor, fueled by immersive audio standards and competitive gaming requirements. However, the Professional Studio and Broadcasting segment represents a high-value niche where reliability and driver stability command premium pricing. Home Entertainment also contributes significantly, driven by the home theater PC movement and high-quality media consumption.
- Regional Heterogeneity: Geographic performance varies widely based on local electronics manufacturing hubs, consumer spending power, and regulatory environments. While some regions show mature saturation, emerging markets present greenfield opportunities for distribution expansion. Understanding the regional weightings is essential for supply chain localization strategies and sales force allocation.
The Strategic Value of Segmentation Depth
For a product manager or investor, knowing the total market size is insufficient. You need to know which segment is outperforming the CAGR, which application vertical is showing resistance to saturation, and where regional headwinds are emerging. For instance, if external sound cards are outperforming internal cards in the forecast period, inventory strategies must shift accordingly. If the Professional Studio segment shows higher margin resilience than the gaming segment during economic downturns, capital should be allocated differently.
Our detailed analysis provides the specific splits and growth rates for each region, type, and application, allowing you to model scenarios based on your specific exposure. Accessing the full dataset is necessary to validate these strategic hypotheses against precise quantitative evidence.
Competitive Landscape: Manufacturers and Strategic Positioning
The competitive environment in the sound card industry is fragmented yet characterized by distinct clusters of leadership. The market concentration indicates that while no single entity holds absolute dominance, a core group of players commands a significant share of revenue and technological innovation. The top three entities account for a substantial portion of total market revenue, and the top five extend this influence further. This concentration suggests a market where brand loyalty and ecosystem integration play critical roles in retention.
Key Players and Their Strategic Niches
Several major corporations define the competitive boundaries, each leveraging different strengths:
- Creative Technology Ltd. (Singapore): A legacy leader in discrete audio, Creative continues to leverage its Sound Blaster brand among gamers and enthusiasts. Recent developments include new external USB DAC/amp releases with enhanced drivers, signaling a push toward external high-fidelity solutions that complement their PCIe heritage.
- ASUSTeK Computer Inc. (Taiwan): Leveraging its motherboard dominance, ASUS offers the Xonar series, integrating audio solutions directly into the PC building experience. Their strategy relies on bundling and software ecosystems like Sonic Studio to add value for gamers and audiophiles.
- Realtek Semiconductor Corp. (Taiwan): As a major supplier of audio CODECs and chipsets, Realtek powers the majority of onboard and OEM solutions. Their competitive moat lies in volume and integration rather than discrete high-end marketing, making them a critical upstream player.
- Focusrite Plc (United Kingdom) & Universal Audio, Inc. (USA): These companies operate heavily in the professional audio interface space, often categorized within the broader sound card market. Focusrite's Scarlett series targets entry-to-mid-level professionals, while Universal Audio's Apollo series with Unison preamps and DSP processing caters to high-end recording studios requiring pristine conversion and processing power.
- RME Audio (Germany) & MOTU (USA): Focusing on ultra-low latency and robust driver support, these firms serve the professional broadcast and studio sectors where reliability is non-negotiable. Their value proposition centers on performance consistency rather than consumer marketing.
- Others: The landscape includes cost-effective contenders like Behringer and M-Audio for home studios, niche high-end manufacturers like HT Omega for audiophiles, and budget-friendly options from Sabrent. Meanwhile, semiconductor suppliers like C-Media Electronics and CMedia provide the underlying controller technology for various aftermarket solutions.
It is important to note that some former entrants, such as EVGA Corporation, have seen limited activity in recent periods, highlighting the volatility of hardware specialization. The dynamic between chipset suppliers and discrete card manufacturers creates a layered supply chain where strategic partnerships can dictate market access. Our full report includes detailed profile summaries and revenue assessments for each key company, enabling you to benchmark your position against these incumbents.
Industry Dynamics, Challenges, and Critical Success Factors
Operating in the sound card market in 2026 involves navigating a complex web of macroeconomic and technical variables. Supply chain resilience, regulatory compliance, and technological obsolescence are not merely operational headaches; they are strategic risks that can erode margins if not managed proactively.
Worldwide Sound Cards Market
Supply Chain and Component Availability
The semiconductor supply chain remains a critical vulnerability. Electronic component lead times, particularly for passives and discretes, tightened in late 2025. Some MOSFET and small signal devices have seen price increases amid geopolitical factors, impacting the cost structure for hardware manufacturers. Furthermore, U.S. export controls on advanced semiconductors and manufacturing equipment continued into 2026, affecting the availability and pricing of audio IC components. While the U.S. semiconductor industry maintained leadership with over 50 percent of global chip revenues in 2025 supported by CHIPS Act investments, tariff uncertainty persisted with potential impacts on imported semiconductors. Some Section 232 measures included exemptions for domestic use, but the regulatory environment requires constant monitoring. Companies must diversify sourcing and consider inventory buffering strategies to mitigate these shocks.
Technological Innovation and Obsolescence
The pace of innovation in audio conversion technology is accelerating. Audio DAC and ADC innovations continued, with new high-performance converters from specialized semiconductor firms supporting professional sound card applications. This raises the bar for what constitutes acceptable audio quality. Products relying on older conversion standards risk rapid commoditization. Conversely, early adoption of new converter technology can create a temporary competitive advantage in the professional and enthusiast segments. Strategic R&D investment is required to keep pace with these component-level advancements.
Strategic Imperatives for 2026
To thrive in this environment, organizations should focus on three core imperatives:
- Differentiation through Software and Ecosystem: Hardware alone is increasingly difficult to defend. Integration with software ecosystems, driver stability, and user-friendly control panels are becoming key decision factors for consumers and professionals alike.
- Supply Chain Robustness: Given the component lead time tensions and tariff uncertainties, securing reliable supply lines for key chipsets and passives is vital. Diversification of suppliers and strategic stocking may be necessary to maintain production continuity.
- Segment Focus: With varying growth rates across applications and types, a portfolio strategy that balances high-volume consumer segments with high-margin professional segments may offer the best risk-adjusted returns. Understanding which segment drives the overall growth is essential for resource allocation.
Conclusion: The Case for Deep Market Intelligence
The Worldwide Sound Cards Market is at an inflection point where historical patterns meet new technological and geopolitical realities. The projected growth remains positive, but the distribution of that growth is uneven across segments and regions. For decision-makers, the difference between capturing value and missing the window often lies in the granularity of the intelligence available.
This article has outlined the high-level contours of the market, the key players driving competition, and the external factors influencing dynamics. However, the true power of this research lies in the actionable data hidden beneath these summaries. Specific revenue splits, precise CAGR figures for individual regions, detailed company market shares, and quantitative scenario analyses are available only in the complete PW Consulting Worldwide Sound Cards Market research report.
Soundbars Market
Don't rely on generic industry summaries for critical 2026 strategic planning. Secure your organization's decision-making advantage by accessing the full comprehensive intelligence. Visit our source webpage to download the complete report, including detailed segmentation data, competitive landscape analysis, and forecast models tailored for enterprise use.
The audio hardware market rewards those who listen closely to the data. Ensure your strategy is tuned to the right frequency.
For detailed analysis of this topic, please visit the official page: Worldwide Sound Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Parallel Weld Heads Market to Reach $294.06 Million by 2032
By pmarketresearch, 2026-09-16
Strategic Intelligence for the Global Parallel Weld Heads Market: Navigating Growth Through 2032
The global manufacturing landscape is undergoing a profound transformation driven by electrification, miniaturization of medical devices, and the relentless pursuit of precision in high-volume assembly. Within this context, parallel weld heads have emerged as critical enabling technologies, particularly for applications where access is limited to a single side of the workpiece. As enterprises plan their capital expenditure and technology roadmaps for the coming decade, understanding the trajectory of the Worldwide Parallel Weld Heads Market is no longer optional—it is a strategic imperative.
This article serves as a high-level overview of the market dynamics captured in our comprehensive research study, Worldwide Parallel Weld Heads Market. The following analysis highlights the strategic value of the report for corporate decision-makers, outlines the scope of competitive intelligence available, and contextualizes the macroeconomic forces shaping the industry. However, to protect the integrity of our proprietary financial models and segmentation data, specific granular figures beyond the headline metrics discussed below are reserved for the full report.
Market Trajectory and Growth Catalysts
The parallel weld heads market has demonstrated steady resilience and expansion over the past half-decade. According to our analysis, which covers historical data from 2020 through 2025 and forecasts through 2032, the market has evolved from a niche tooling segment into a broader enabler of high-precision joining solutions. The base year valuation for 2025 establishes a significant milestone, reflecting accumulated demand from key end-use sectors.
Looking forward, the forecast period from 2026 to 2032 indicates sustained momentum. The compound annual growth rate (CAGR) projected over this horizon underscores the increasing adoption of parallel gap welding configurations in industries where traditional series welding setups face geometric constraints. This growth is not uniform; it is heavily influenced by technological advancements, shifts in supply chain dynamics, and the scaling of battery manufacturing capacity globally.
Our research identifies several macro drivers propelling this expansion. The continued electrification of transportation and consumer electronics requires robust joining solutions for battery tab welding and pack assembly. Simultaneously, the medical device sector demands increasingly precise welding capabilities for sensors and miniature components, where parallel weld heads offer distinct advantages in terms of force control and accessibility. Furthermore, advancements in aerospace and automotive manufacturing are enforcing stricter standards for repeatability and quality, further cementing the role of specialized welding equipment in production lines.
Key Market Metrics and Structure
To provide decision-makers with a clear baseline, our study aggregates historical revenue data and projects future performance using rigorous econometric modeling. The overall market size has shown a consistent upward trajectory from 2020 to the base year of 2025. This growth reflects both organic adoption and the replacement of aging equipment in established facilities.
The forecast period extends through 2032, allowing stakeholders to model long-term return on investment (ROI) scenarios. The valuation is calculated in United States Dollars (USD) and expressed in millions, providing a standardized metric for global comparison. While the total addressable market continues to grow, it is important to note that market concentration remains a defining characteristic of the industry. The competitive landscape is moderately consolidated, with a significant share of revenue attributable to a subset of leading manufacturers and integrators. This concentration impacts pricing strategies, supply chain negotiations, and technology licensing dynamics.
- Historical analysis covers the evolution of market demand from 2020 to 2025.
- Forecast models project performance trends through 2032 based on sector-specific growth drivers.
- Revenue is standardized in USD millions to facilitate cross-regional benchmarking.
- Market concentration metrics highlight the influence of key market participants on overall dynamics.
Report Scope and Operational Utility
The Worldwide Parallel Weld Heads Market report is designed as a practical toolkit for strategy teams, procurement leaders, and engineering executives. Rather than offering abstract observations, the study delivers actionable intelligence structured to support specific business functions. The depth of analysis ensures that readers can assess market opportunities, evaluate competitive positioning, and anticipate supply chain disruptions with confidence.
Segmentation and Application Analysis
A core component of the report involves a detailed breakdown of market segmentation. Understanding how demand is distributed across different types of weld heads, application verticals, and geographic regions is essential for targeted go-to-market strategies. Our analysis categorizes the market by type, distinguishing between air-actuated, electromagnetic, and manual weld heads, and evaluates their respective adoption rates and performance characteristics in real-world settings.
Additionally, the study examines application-specific demand patterns. Segments such as battery tab welding, medical device manufacturing, electronics and sensors, and automotive and aerospace applications are analyzed to reveal growth trajectories, technical requirements, and emerging use cases. Geographic segmentation is also covered to identify high-potential markets and regional variations in demand drivers. Note that precise regional or application-specific revenue splits are not disclosed in this introduction; these detailed breakdowns are integral to the full report.
Welding Equipment Market
Technology and Workflow Integration
Beyond sizing and segmentation, the report explores how parallel weld heads integrate into broader manufacturing workflows. Parallel gap welding, also known as series welding, is utilized when only one side of the weldment is accessible. This configuration is critical for battery pack manufacturing, medical sensors, solar cells, and hybrid circuitry applications. The report evaluates how manufacturers are combining parallel weld heads with other technologies, such as laser welding systems, to optimize micro-welding workflows.
Recent industry developments illustrate this trend toward integration. For example, advancements in benchtop laser welder comparisons have highlighted options for integrating parallel weld head systems, supporting more versatile micro-welding setups. Additionally, partnerships with industry bodies such as the AWS RWMA and EWI are fostering continued development and application of parallel weld heads in resistance welding, ensuring that equipment aligns with evolving technical standards.
Competitive Landscape and Key Players
The competitive environment for parallel weld heads is characterized by a mix of specialized manufacturers, distributors, and system integrators. Our report provides detailed profiles of key companies, examining their product portfolios, market focus, and strategic initiatives. Understanding the capabilities and positioning of these players is crucial for benchmarking, partnership evaluation, and competitive response planning.
Leading Manufacturers and Integrators
Several companies stand out for their contributions to the development and deployment of parallel weld heads across multiple sectors. One prominent manufacturer based in Payson, Utah, specializes in parallel weld heads including pneumatic and manual models optimized for micro resistance spot welding. Their product series are specifically engineered for battery tab welding, battery pack assembly, and fine wire/foil applications, offering same-side electrode access that addresses common geometric constraints.
Another major player, headquartered in Monrovia, California, offers a comprehensive line of resistance weld heads and actuators. Their portfolio includes motorized, servo, pneumatic, and manual models supporting parallel gap and series welding configurations, serving micro-joining applications in electronics, medical, and automotive sectors. This breadth of offerings positions them as a versatile partner for manufacturers seeking integrated solutions.
Distribution and integration networks also play a significant role in market penetration. A distributor based in Chattanooga, Tennessee, integrates specific parallel weld head series for capacitive discharge spot welders, targeting battery pack manufacturing and micro-joining applications. Meanwhile, a supplier based in Arizona provides parallel micro weld heads with low force capabilities, catering to precision micro-welding requirements that demand minute force control, as low as 30 grams in certain electromagnetic linear motion models.
Additional distribution channels extend the reach of these technologies across aerospace, automotive, electronics, and medical device manufacturing. By mapping these relationships, our report helps clients identify potential supply chain partners and understand the distribution dynamics that influence equipment availability and support services.
Worldwide Parallel Weld Heads Market
Recent Strategic Developments
The competitive landscape is dynamic, with companies actively pursuing product innovation and strategic partnerships. Recent developments highlight the industry's focus on expanding capabilities and reinforcing technical credibility. For instance, a product comparison release in mid-2025 showcased benchtop laser welder options, emphasizing integration possibilities with parallel weld head systems to enhance micro-welding workflows. Such moves signal a broader trend toward hybrid welding solutions that combine the strengths of different joining technologies.
Furthermore, partnerships with recognized industry organizations continue to support the advancement of resistance welding applications. Collaborations with groups like the AWS RWMA and EWI underscore the commitment to developing and applying parallel weld heads in ways that meet rigorous industry standards. These developments are not merely operational; they shape the future trajectory of market acceptance and technical innovation.
Market Dynamics and External Factors
No market analysis is complete without considering the external forces that can influence performance and planning. Our report integrates an assessment of raw material dynamics, regulatory contexts, and broader industry trends that impact the parallel weld heads sector.
Raw Material Volatility and Supply Chain Implications
Recent months have seen significant volatility in raw material prices, particularly within electronics supply chains. The ongoing electrification of various sectors has driven fluctuations in copper prices, directly affecting components and consumables used in resistance welding equipment, including parallel weld heads. In the broader welding consumables and electrodes market, price fluctuations for steel rod, ferroalloys, and copper coating have impacted a notable portion of procurement contracts, with alloy wire lead times increasing. These dynamics introduce cost pressure and require proactive supply chain management to maintain margin stability and production continuity.
Regulatory and Standards Environment
Resistance welding products, including parallel weld heads, operate within a regulatory framework that emphasizes precision and repeatability in high-volume production. Sectors such as automotive, aerospace, and electronic appliances face ongoing demands for quality assurance and compliance with technical standards. As manufacturers scale production to meet growing demand, adherence to these standards becomes a competitive differentiator and a prerequisite for entry into certain supply chains. Our report examines how regulatory expectations influence equipment selection and validation processes.
Strategic Imperatives for 2026 and Beyond
As enterprises look toward 2026 and the remainder of the forecast period, several strategic imperatives emerge. First, aligning capital investment with validated growth segments is critical. The data indicates that demand is not evenly distributed across applications or regions, and targeted investments yield higher returns. Second, supply chain resilience must be prioritized. Given raw material volatility and lead time extensions, building robust supplier relationships and diversifying sourcing options can mitigate risk.
Third, technology integration should be evaluated holistically. The trend toward combining parallel weld heads with laser systems and other joining technologies suggests that standalone equipment purchases may be less valuable than integrated workflow solutions. Finally, competitive intelligence must be continuous. The moderately concentrated nature of the market means that the actions of key players, from product launches to partnership announcements, can quickly shift dynamics. Our report provides the foundation for such intelligence, but ongoing monitoring is essential.
Conclusion: Accessing Comprehensive Intelligence
The Worldwide Parallel Weld Heads Market presents significant opportunities for organizations that can navigate its complexities with data-driven precision. From historical performance and forecast trajectories to segmentation nuances and competitive maneuvers, the market rewards those who invest in thorough analysis. This article has provided a strategic overview of the key themes, drivers, and players shaping the industry, but it represents only a fraction of the insights available in the full study.
For decision-makers seeking detailed regional breakdowns, application-specific revenue distributions, granular segmentation splits, and comprehensive company profiles, the complete report is the essential resource. It offers the depth required to formulate confident strategies, optimize procurement, and identify growth vectors with clarity. To access the full intelligence suite and transform this overview into actionable strategy, we invite you to explore the full report through our official channels.
In an environment defined by rapid technological change and shifting supply chain realities, strategic foresight is the ultimate competitive advantage. The Worldwide Parallel Weld Heads Market report is designed to deliver that foresight, empowering your organization to lead rather than follow in the years ahead.
For detailed analysis of this topic, please visit the official page: Worldwide Parallel Weld Heads Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Oxcarbazepine Market Hits $310M in 2025, Poised for 3.15% CAGR to 2032
By pmarketresearch, 2026-09-16
# Strategic Intelligence for the Coming Cycle: Inside the Global Oxcarbazepine Market Outlook
Executive Overview
The global pharmaceutical landscape for antiepileptic drugs is undergoing a subtle but significant transformation. As patent exclusivities fade and generic penetration deepens, the Oxcarbazepine market stands at a critical inflection point. Our latest Worldwide Oxcarbazepine Market research report provides a comprehensive strategic roadmap for stakeholders navigating this mature yet evolving therapeutic sector. This document serves as an introduction to the full intelligence suite, designed to equip corporate strategy teams, investors, and supply chain executives with the data necessary to make informed decisions throughout the 2026-2032 forecast period.
Oxcarbazepine remains a cornerstone therapy for partial seizures and various neurological conditions. Its position on the WHO Model List of Essential Medicines underscores its clinical necessity, ensuring steady demand regardless of broader economic fluctuations. However, the commercial dynamics are heavily influenced by manufacturing capabilities, regulatory approvals, and regional reimbursement structures. Understanding the interplay between these factors is no longer optional for market participants aiming to secure market share or optimize procurement strategies.
Market Trajectory and Historical Context
To project future performance, one must first understand the historical baseline. The market has demonstrated resilience over the past five years, navigating supply chain disruptions and regulatory shifts while maintaining a positive growth trajectory. Based on our analysis, the global revenue for Oxcarbazepine reached approximately 310.0 Million USD in the base year of 2025. This figure represents the culmination of a recovery phase following earlier market contractions observed in 2022.
Looking forward, the market is projected to expand from this baseline toward a valuation exceeding 385 Million USD by the end of the forecast period in 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 3.15 percent. While this rate may appear moderate compared to novel specialty therapeutics, it reflects the stability of a mature generic market where volume growth is driven primarily by epidemiological factors and increased access in emerging economies rather than price premiums. For strategic planners, this signals a shift from aggressive expansion tactics to efficiency-driven consolidation and supply chain robustness.
Competitive Landscape and Key Players
The competitive environment is characterized by a high concentration of generic manufacturers, predominantly based in India, with significant participation from established pharmaceutical giants in North America and Europe. Our report details the strategies of twelve key companies that define the current market structure. These entities compete not on novel molecular entities, as the primary US patent expired in 2007, but on supply reliability, formulation versatility, and regulatory compliance.
Leading the pack is Teva Pharmaceutical Industries Ltd., headquartered in Petah Tikva, Israel. As a global manufacturer, Teva offers a wide range of strengths including 150mg, 300mg, and 600mg tablets alongside oral suspensions, distributed across the US and European markets. Their scale provides a significant competitive moat in terms of distribution network reliability. Similarly, Viatris Inc., based in Canonsburg, PA, maintains a strong presence with both immediate-release and extended-release formulations distributed worldwide.
The Indian pharmaceutical sector plays a pivotal role in the global supply chain. Sun Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories Ltd., both headquartered in Mumbai and Hyderabad respectively, leverage ANDA and EMA approvals to supply regulated markets. Dr. Reddy's specifically highlights USFDA approval for their tablet exports, marking a key compliance benchmark. Lupin Ltd. and Aurobindo Pharma Ltd. further strengthen this cohort, with Lupin having launched a USFDA-approved oral suspension in 2022 and Aurobindo supplying multiple strengths to North American markets. Additional key players such as Zydus Lifesciences Ltd., Cipla Ltd., Sandoz International GmbH, Apotex Inc., MSN Laboratories Pvt. Ltd., and Alembic Pharmaceuticals Ltd. contribute to a fragmented but highly regulated supply base.
Recent developments highlight the dynamic nature of this competition. In September 2023, MSN Laboratories received final USFDA approval for their extended-release tablets, opening new avenues for US market entry. Conversely, the market faced supply tightness in 2022 and 2023, prompting the US FDA to resolve a national shortage of 300mg tablets by June 2023 following increased manufacturing output. These events illustrate the fragility of supply chains and the strategic importance of manufacturing redundancy.
Segmentation Dynamics
Understanding where value is generated is critical for targeted investment. Our research dissects the market across three primary dimensions: Region, Formulation, and Application. While specific percentage allocations are proprietary data points detailed in the full report, the structural hierarchy is clear.
Formulation and Application Preferences
In terms of formulation, solid oral dosage forms continue to dominate consumption patterns. Tablets represent the bulk of revenue generation, favored for their stability and ease of distribution compared to liquid forms. However, oral suspensions maintain a vital niche, particularly for pediatric patients or those with swallowing difficulties, representing a key area for product differentiation among generic manufacturers.
Regarding therapeutic application, the vast majority of demand is driven by epilepsy treatment. This aligns with the drug's primary indication and its inclusion in essential medicine lists globally. A secondary but stable segment comprises other neurological disorders, providing a diversified revenue stream for manufacturers who hold broader labeling approvals. The interplay between these segments dictates inventory planning and marketing focus for commercial teams.
Regional Distribution
Geographically, the market is distributed across five key regions: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America remains the largest revenue contributor, supported by high prescribing rates and established reimbursement pathways such as Medicare Part D, which typically covers the drug with manageable copays. Europe follows as a significant market, driven by stringent regulatory standards and universal healthcare coverage in many nations. The Asia Pacific region represents a growth frontier, where increasing diagnosis rates and improving healthcare infrastructure are expanding access. Emerging markets in Latin America and the Middle East and Africa, while smaller in total revenue, offer long-term potential for manufacturers with localized supply capabilities.
Industry Dynamics and Strategic Risks
Operating in the Oxcarbazepine market requires navigating a complex web of regulatory and supply chain dynamics. One of the most critical factors is the status of Intellectual Property. With the US patent (US 5,753,697) having expired in December 2007, the market is open to multiple generic entries. This absence of patent protection keeps prices competitive but pressures margins, necessitating high-volume efficiency for manufacturers.
Supply chain resilience is another paramount concern. The reliance on Active Pharmaceutical Ingredient (API) sourcing from India and China creates potential vulnerability. Our analysis notes that over 20 manufacturers have Drug Master File (DMF) filings listed in the US FDA database, indicating a robust but complex supply network. Disruptions in this network were evident during the 2022-2023 period when manufacturing delays led to intermittent shortages of 300mg and 600mg tablets in the US. Companies that secured multiple API sources or maintained higher inventory buffers were better positioned to capture market share during these disruptions.
Reimbursement policies also shape market access. In the United States, coverage under Medicare Part D with average generic copays ranging between 10 and 30 USD per prescription ensures patient adherence but limits pricing power. In other regions, national health service formularies dictate availability. Strategic planners must account for these policy frameworks when forecasting volume and revenue.
Worldwide Carbamazepine Market
Strategic Value for 2026 Decision Making
Why is this research vital for your 2026 planning cycle? The answer lies in the granularity of the intelligence provided. High-level market size figures are available publicly, but understanding the actionable nuances requires deep-dive analysis. This report moves beyond macro trends to provide actionable intelligence on capacity expansion, regulatory pipelines, and competitive maneuvering.
For procurement officers, the report offers insights into supplier reliability and regional manufacturing strengths, crucial for mitigating shortage risks. For commercial leaders, the segmentation data helps identify underserved niches, such as specific formulation strengths or emerging regional markets where competition is less saturated. For investors, the concentration metrics and company profiles provide a clear view of market dominance and potential consolidation opportunities.
The market concentration data indicates that while the top three players hold a significant share, the top five collectively control more than half of the market revenue. This suggests that while barriers to entry exist primarily through regulatory compliance and scale, there is still room for specialized players to compete effectively through niche formulations or superior supply chain logistics.
Worldwide Oxcarbazepine Market
Conclusion and Report Access
The Worldwide Oxcarbazepine Market is a stable yet competitively intense environment where success depends on operational excellence and strategic foresight. The projected growth to 2032 offers opportunities, but realizing them requires a clear understanding of the underlying dynamics detailed in our full study.
This introduction has outlined the macroeconomic landscape, the key competitive actors, and the critical industry drivers. However, the detailed segmentation splits, proprietary growth rates for specific sub-regions, and comprehensive financial modeling are reserved for the complete market research report. To access the full dataset, including specific regional revenue breakdowns, deep-dive company profiles, and actionable strategic recommendations, please visit the PW Consulting website. Equip your organization with the precision intelligence needed to navigate the next cycle of growth in the global neurological therapeutics sector.
For detailed analysis of this topic, please visit the official page: Worldwide Oxcarbazepine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Financial Services App Market to Hit $400.84B by 2032, 13.5% CAGR
By pmarketresearch, 2026-09-16
Global Financial Services Apps: Strategic Intelligence for 2026 and Beyond
The Worldwide Financial Services App Market has crossed a decisive threshold. Between 2020 and 2025, revenue expanded from approximately $84.12 billion to $165.2 billion, reflecting a compound annual growth rate of 13.5 percent across the forecast horizon through 2032. By 2026, the market is projected to reach $183.0 billion, with continuation into the $400 billion range by 2032. These figures are not merely statistical artifacts; they signal a structural realignment in how consumers, enterprises, and institutions access, distribute, and monetize financial services through mobile channels. For executives making capital allocation, product roadmap, and partnership decisions in 2026, this trajectory demands more than awareness. It requires a diagnostically precise, forward-looking intelligence architecture that our latest market research delivers.
This article previews the strategic value embedded in our Worldwide Financial Services App Market study. The preview demonstrates analytical rigor, outlines the operational contents of the report, and sets the stage for deeper engagement. Core segmentation values, regional revenue splits, and platform-level shares are deliberately withheld here. To translate market signals into boardroom decisions, stakeholders must access the full report, where granular data tables, scenario projections, and competitor benchmarks are published in executable format.
The Strategic Imperative: Why 2026 Decisions Require Differentiated Intelligence
Financial services applications no longer operate as discrete digital conveniences. They have become the primary orchestration layer for money movement, asset allocation, insurance distribution, and credit origination. The market's sustained expansion is powered by simultaneous forces: embedded finance integration, real-time payment network maturity, regulatory data-sharing mandates, and rising consumer expectations for unified financial experiences. Yet growth velocity alone is insufficient for strategy. Decision makers must understand where value concentrates, how platform dynamics shape cost structures, which competitor moves alter competitive moats, and what regulatory inflection points will redefine compliance economics.
Our study is engineered for that purpose. It converts macro momentum into actionable decision scaffolding. Rather than offering a single point estimate, the research maps growth durability across multiple horizons, identifies structural shifts in service adoption, and isolates the operational and compliance variables that will differentiate winners from laggards. The result is a decision-grade intelligence asset that supports product investment, geographic prioritization, partnership design, and risk modeling.
What the Research Delivers: Operational Depth for Enterprise Planning
The report is structured to support cross-functional planning teams, from product and engineering to compliance, corporate development, and investor relations. Its contents are designed for immediate operational translation rather than abstract commentary.
Scope and Time Architecture
The research anchors historical analysis in the 2020-2025 window and extends forward-looking projections through 2032. This dual lens enables teams to validate emerging patterns against observed behavior while stress-testing strategic options against credible forward trajectories. Revenue is assessed in U.S. dollars at the billion scale, providing a consistent basis for investment sizing, market entry evaluation, and competitive benchmarking.
Service Category Mapping and Application Pathways
The study decomposes the market across core service categories, including digital banking and payments, investment and wealth management, insurance technology, and personal finance tools. This structure helps enterprises understand where user engagement, monetization intensity, and ecosystem integration are evolving fastest. Importantly, the report avoids static category descriptions. It examines how these segments converge in practice through super app architectures, embedded capabilities, and cross-product bundling strategies.
Financial Planning Software Market
Platform and Distribution Dynamics
Mobile financial services operate across heterogeneous platform environments, and the research captures the relative scale and strategic implications of major operating ecosystems. Rather than treating platform share as a vanity metric, the analysis connects adoption patterns to development cost, user acquisition economics, compliance complexity, and feature rollout cadence. These insights help technology leaders sequence platform investments and avoid misallocated engineering resources.
Competitive Intelligence and Ecosystem Mapping
The report profiles the companies shaping the market's architecture, ranging from consumer-facing super apps and digital wallets to core banking platform providers, payment infrastructure firms, and network operators. Profiles extend beyond corporate summaries to capture functional positioning, partnership relevance, and ecosystem leverage. For corporate development teams, this mapping supports targeted partnership screening, acquisition thesis refinement, and competitive response modeling.
Regulatory and Infrastructure Context
Market expansion does not occur in a vacuum. The research integrates regulatory and operational variables that directly influence product design, data architecture, and cost profiles. This includes the implications of operational resilience requirements for financial entities and critical ICT providers, consumer financial data rights rules that mandate secure API-based data sharing and portability, and data sovereignty mandates that affect where transaction processing can occur. On the infrastructure side, the study accounts for rising energy and data center demands that influence the cost environment for cloud-dependent financial applications. These factors are not peripheral. They shape compliance roadmaps, localization strategies, and total cost of ownership for digital financial services.
Competitive Landscape: Architectures, Not Just Players
The market is defined less by a single dominant monopoly than by layered ecosystems, each competing on distribution, trust, infrastructure, and embedded functionality. The research examines a broad competitive field that includes global super apps, payment and wallet platforms, core banking and digital engagement vendors, payment infrastructure and SDK providers, card network operators, and consumer finance platforms.
Several competitive patterns emerge. First, super app models continue to demonstrate the power of consolidation, where payments, lending, insurance, and wealth capabilities are unified within a single mobile environment. This approach reduces friction, increases session depth, and creates cross-sell pathways that isolated apps struggle to replicate. Second, platform and infrastructure providers exert growing influence by enabling embedded finance through SDKs, APIs, and core banking modules. Their strategic importance lies not only in transaction volume but in their ability to lower integration barriers for institutions and innovative fintechs alike. Third, network operators and payment processors remain critical enablers of secure transaction flows, tokenization, and cross-border interoperability, increasingly partnering with app ecosystems rather than merely processing behind the scenes.
Recent operational developments reinforce the velocity of change. Fraud detection platforms have been strengthened with network-level intelligence to identify emerging fraud rings earlier and support real-time payment integrations. Tokenized deposit offerings and programmable stablecoin experimentation have expanded within institutional and application contexts. Partnerships linking banking clients with stablecoin and digital asset integration capabilities are being launched to support new asset workflows in mobile banking apps. Meanwhile, real-time payment networks have recorded substantial increases in both transaction volume and value, with request-for-payment features enabling smoother account-to-account interactions inside financial applications. These developments matter because they change the baseline for fraud management, settlement design, product innovation, and partnership strategy.
Worldwide Financial Services App Market
Structural Dynamics: Where Value Meets Constraint
The market's trajectory is shaped by intersecting forces that reward scale, interoperability, and resilience while penalizing fragmented or compliance-blind designs.
Regulatory Realignment
New regulatory frameworks are redefining data handling, operational resilience, and consumer control. Financial services apps must increasingly support secure, consumer-directed data sharing and portability through API-based architectures. At the same time, resilience obligations are tightening for financial entities and critical ICT providers, raising the bar for security controls, incident response, and third-party risk management. For global operators, data sovereignty requirements add another layer of complexity, often requiring localized processing and storage decisions that affect architecture, vendor selection, and launch sequencing. These dynamics do not merely constrain; they reshape competitive advantage by favoring organizations that build compliance into product design rather than retrofitting it.
Infrastructure and Cost Pressure
Digital financial services depend on cloud computing and data center capacity, and energy market dynamics are becoming a more visible component of operating economics. Rising electricity costs associated with expanded data center demand can influence total cost structures for high-volume application platforms. In some regions, utility pricing adjustments and dedicated rate structures for large energy users are being introduced to manage the impact on broader rate bases. For financial services application leaders, this means infrastructure economics deserves board-level attention alongside feature roadmaps and user growth targets.
Ecosystem Convergence
The boundaries between banking, payments, investment, insurance, and commerce are blurring inside mobile experiences. Users increasingly expect continuity across functions, and institutions are responding through embedded partnerships, platform modernization, and unified identity and data layers. This convergence amplifies the importance of integration quality, trust signals, and real-time responsiveness. It also increases the strategic stakes of choosing whether to build proprietary capabilities, partner with infrastructure providers, or participate in network ecosystems.
Translating Market Intelligence into 2026 Actions
The strategic value of this research lies in its ability to convert broad momentum into executable priorities. For product and engineering leadership, the study informs sequencing decisions around platform investment, embedded finance integration, real-time payment enablement, and fraud resilience. For corporate development and partnership teams, it supports identification of ecosystem leverage points, infrastructure dependencies, and collaboration models that accelerate time to market without sacrificing control. For compliance and risk functions, it contextualizes regulatory obligations within product design, data localization, and operational resilience planning. For executive teams and investors, it provides a disciplined framework for evaluating growth durability, concentration risk, and the economic implications of infrastructure and regulatory change.
Crucially, the report is not designed to be read once and shelved. It is structured to support scenario analysis, benchmarking, and recurring strategic reviews. Market leaders can use it to validate internal assumptions, challenge optimistic or pessimistic biases, and align cross-functional teams around a shared evidentiary baseline.
Why the Full Report Is the Next Step
This preview establishes the analytical framework and strategic breadth of the study. It demonstrates that the research goes beyond surface-level growth narratives to address service categories, platform dynamics, competitor architectures, regulatory shifts, and infrastructure realities. However, the most decision-relevant elements are contained in the complete report. Detailed segmentation values, regional and category-level revenue structures, platform distribution profiles, concentration metrics, and company-specific benchmarking are essential for calibrated strategy. Without them, leaders risk overgeneralizing from macro trends or mistaking headline growth for actionable opportunity.
To access the full intelligence set, including the data tables, competitive profiles, and forward projections that support precise planning, stakeholders should consult the complete Worldwide Financial Services App Market research. The report is intended for teams that must move from awareness to allocation, from intuition to evidence, and from narrative to execution. In a market expanding toward the $400 billion range over the forecast horizon, the cost of incomplete intelligence is far greater than the effort required to obtain it.
For detailed analysis of this topic, please visit the official page: Worldwide Financial Services App Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Fabric Flame Retardancy Tester Market Hits $115.8M in 2025, 5.45% CAGR to 2032
By pmarketresearch, 2026-09-16
Executive Brief: The Strategic Imperative of Fabric Flame Retardancy Testing in 2026
Global compliance pressure, regional manufacturing shifts, and raw material volatility have converged to make fabric flame retardancy testers no longer a niche procurement line. What was once a back-office quality-control purchase has become a strategic capability that underpins market access, brand protection, and product innovation across textiles, automotive interiors, and construction materials. Our latest research, Worldwide Fabric Flame Retardancy Testers Market, is designed for decision-makers who need to translate regulatory arc, regional demand, and competitive positioning into concrete action. This briefing previews the analytical architecture of the study and explains why, in 2026, these instruments are entering a decisive growth window.
Why 2026 Is a Strategic Inflection Point
Flame retardancy testing sits at the intersection of consumer safety, industrial standards, and product design. The market has matured through multiple phases of rebalancing over the past five years, reflecting broader industrial cycles, regulatory adjustments, and uneven regional adoption rates. Looking forward, the growth trajectory is supported by structural drivers rather than a single event. Procurement teams are facing more nuanced trade-offs: instruments must satisfy a widening palette of test methods, support faster throughput, and integrate with laboratory workflows that increasingly demand repeatability, data traceability, and cross-standard compatibility.
At the same time, the regulatory environment continues to shape the testing landscape with precision. Recent amendments to clothing textile flammability standards in the United States have modernized permissible equipment and procedural requirements without altering core test criteria or flammability classes, a policy signal that reinforces the role of well-calibrated instrumentation in maintaining compliance while streamlining lab operations. In parallel, the ongoing reliance on established vertical flame resistance methods for protective clothing fabrics, alongside international flame spread specifications for protective clothing materials, highlights the necessity for instruments that can reliably replicate these test conditions across supply chains. These dynamics are not abstract; they affect equipment specification, service expectations, and the cadence at which manufacturers upgrade or expand testing capabilities.
Macro Trajectory and the Shape of Demand
Our analysis maps the market’s evolution across a defined historical window and extends the outlook through the end of the decade, offering a framework that supports capacity planning, investment timing, and segmentation strategy. The overall market size and revenue progression show a market that has moved from post-cycle adjustment into renewed expansion, with the forecast period reflecting accelerating relevance of flame retardancy testing instruments across industrial end-segments. Rather than relying on a single-year snapshot, the study tracks the broader curve to identify inflection points and momentum patterns that inform whether a market participant should prioritize near-term distribution expansion, product-line differentiation, or longer-horizon platform investments.
A critical part of understanding the market’s direction is recognizing how revenue concentration and competitive balance affect pricing environments, service expectations, and adoption rates. The sector is not a monolith of fragmented, interchangeable offerings. Instead, the data points to a moderately concentrated competitive field where a cluster of active companies exerts meaningful influence over product specifications, regional coverage, and customer relationships. For procurement and strategy teams, this structure matters: it means that supplier selection is not only about bench testing performance, but also about the durability of technical support, the breadth of standard coverage, and the ability to keep pace with evolving application requirements.
Deep Practical Intelligence Withheld to Preserve Commercial Value
This report is built around operational decision-making rather than abstract trend commentary. It provides an integrated look at the market that analysts, procurement leads, and commercial directors can use to reduce uncertainty when evaluating equipment purchases, channel strategies, geographic priorities, and end-use exposure. The study details testing types, application contexts, and regional activity in a manner that links instrumentation requirements to real-world demand signals. Readers will find guidance on how different test configurations align with specific customer environments and how strategic buyers can assess vendor capability beyond headline specifications.
To support actionable use, the research balances multiple analytical lenses. It examines the practical relevance of distinct testing configurations, outlines the industries and workflow contexts where demand is expanding, and identifies the regional patterns that shape distribution logistics, after-sales service expectations, and competitive exposure. The analysis also connects equipment capabilities to application-level requirements, helping buyers understand where certain instruments may offer operational advantages and where broader multi-purpose solutions could reduce total cost of ownership. This breadth is intended to serve both immediate procurement evaluations and longer-range portfolio planning, giving users a usable map rather than isolated data points.
At the same time, the full segmentation detail—the specific regional shares, application-level breakdowns, and type-level revenue splits—is intentionally reserved for the complete study. That disclosure strategy reflects the commercial reality of the market: the most strategically valuable interpretation is not the raw index itself, but the combination of segmentation, regulatory context, competitive behavior, and forward indicators that tells a buying organization what to prioritize and when. The complete report provides that integrated synthesis, including the deeper comparative views that make it possible to benchmark positioning across key companies and assess market structure with precision.
Competitive Landscape: Who Shapes the Market and How
The marketer landscape in fabric flame retardancy testing is shaped by organizations that combine instrument manufacturing with strong alignment to testing standards, end-use applications, and regional service networks. Several companies stand out for the way they have defined product breadth, specialized use cases, and the practical credibility of their platforms.
DaRong
DaRong has built a comprehensive series of fabric flame retardant testers covering vertical, horizontal, 45-degree, and specialized applications that span carpets, mattresses, face masks, and fire-fighting boots. Its instruments are positioned around core standards such as ISO 6940/6941, ISO 15025, ASTM D1230, and 16 CFR 1610, with additional alignment to GB/T 5455, a standard associated with the company’s own drafting involvement. For buyers, this profile suggests a vendor that emphasizes broad test-method coverage and the ability to support diverse textile applications through a connected instrument family.
AVENO TECHNOLOGY CO., LIMITED
AVENO supplies multiple fabric flammability testers across vertical, horizontal, 45-degree automatic, curtain flame propagation, and furniture-related test configurations. Its portfolio targets textiles, automotive interiors, children’s sleepwear, and upholstered furniture, reflecting a focus on applications where flammability requirements intersect with product safety expectations. This breadth makes the company relevant to laboratories and manufacturers seeking a supplier that can address multiple material categories without fragmenting their testing equipment base.
GESTER
GESTER offers a hanging fabric burning tester designed for NFPA 701 Method 1 evaluation of curtain and hanging fabrics, with stainless steel construction, touch screen control, and adjustable flame height. In a market where end-use-specific methods matter, this type of focused design illustrates how instrument vendors differentiate through application fit and usability features. Buyers evaluating curtain and hanging fabric testing workflows may find such specialization especially relevant when compliance and ease of operation are both priorities.
TESTEX
TESTEX provides a multi-purpose textile flammability tester aimed at vertical burning tests across toy materials, decorative fabrics, tent fabrics, safety nets, and household textiles. Its alignment with ISO 6940/6941, ISO 15025, EN71-2, and ECE R118, combined with PLC control and optical scanning, points to a product emphasis on versatility, repeatability, and modernized instrumentation interfaces. This profile is useful for organizations that need to cover a range of textile classifications and safety-relevant applications within a consolidated testing setup.
FYI Tester
FYI Tester specializes in textile flammability testers, including UL 94 horizontal and vertical configurations, automatic models, 45-degree systems, and SPI 45-degree variants. Its product focus covers garment fabrics, decorative fabrics, and tent fabrics, suggesting a commercial posture centered on textile flammability segments that demand both vertical and angle-based test capabilities. For buyers concerned with alignment to consumer and industrial flammability expectations, this specialization may reduce compatibility risk across garment and decorative material workflows.
Flame Retardant Fabric Market
SDL Atlas
SDL Atlas offers flammability testing solutions for textiles, including a horizontal flammability tester for automotive interior materials and additional chambers for burn rate, burn resistance, and flame spread evaluation. With operations spanning the USA, Hong Kong, and China, the company reflects a multi-region commercial presence that can matter to organizations seeking a supplier with both technical depth and cross-border support capacity. Its automotive interior orientation is especially noteworthy for buyers whose testing requirements intersect with vehicle cabin materials and broader interior compliance considerations.
Taken together, this competitive set indicates a market where differentiation is increasingly tied to test-method coverage, application fit, and regional service reach. The complete report develops this comparison further, connecting each company’s profile to market positioning, end-use relevance, and the practical implications for procurement and channel strategy. The level of competitive granularity required to make those judgments is part of what the full study delivers, since the real value lies in interpreting company capability within the shape of the overall market—not simply listing product features in isolation.
Industry Context: Materials, Regulation, and Testing Practice
No equipment strategy is complete without attention to the operating environment in which instruments are bought, deployed, and maintained. Material cost behavior remains a live factor in procurement planning. Steel market conditions have shown stabilization in the mid-range pricing levels through 2025, with forward indicators suggesting modest firmness entering early 2026. At the same time, aluminum mill shapes have experienced notable year-over-year price increases, and steel mill products have risen in the same period. These movements matter because instrument manufacturing, chamber construction, and durable test-stand components are sensitive to raw material input costs, which in turn influence supplier pricing, lead times, and the timing of equipment refreshes.
Regulatory and standards context continues to shape demand as well. Amendments to clothing textile flammability requirements have expanded permissible equipment and updated procedural requirements without changing core testing criteria or flammability classes, reinforcing the need for instruments that meet current procedural expectations while preserving compatibility with established evaluation frameworks. In the protective clothing space, long-standing vertical flame resistance methods remain central to evaluating afterflame time, hole formation, and flaming debris, while international flame spread specifications continue to define the basis for assessing protective clothing materials against limited flame spread. These standards are not static footnotes; they guide the practical design of test setups and influence which instrument features matter most to buyers in safety-critical segments.
Beyond direct inputs, the broader industrial context reinforces strategic caution and opportunity. As testing demand expands across textile, automotive, and construction-related applications, the practical challenge for organizations is not simply to buy equipment, but to choose instrumentation that can support evolving standards, multiple material classes, and regional compliance expectations over a multi-year horizon. That is exactly the kind of tradeoff the full market study is structured to illuminate.
What the Study Enables for 2026 Decision-Makers
For strategic planners, this research is designed to support concrete decisions. It helps answer questions such as how the market is expanding, where demand intensity is shifting, which testing types and applications carry the most commercial weight, and how competitive concentration affects supplier dynamics. It also provides the analytical grounding needed to evaluate whether to expand testing capacity, diversify supplier relationships, prioritize certain standards coverage, or align procurement timing with demand momentum through the forecast period.
Worldwide Fabric Flame Retardancy Testers Market
Because the report ties together market size progression, segmentation logic, competitive company profiles, and macro context, it can serve multiple functions at once: aligning procurement with product strategy, informing regional market entry or expansion, and sharpening the evaluation criteria used to compare instrument suppliers. Importantly, the most actionable insights come from combining these elements rather than reading any single figure in isolation. The complete study preserves that integration, while the details that would enable precise benchmarking and commercial planning are reserved for the full dataset and accompanying interpretation.
Conclusion: The Case for Full Intelligence
Fabric flame retardancy testing is entering a phase in which strategic choice matters more than ever. Demand is being shaped by regulatory continuity, application diversification, regional variation, and the material-cost environment that surrounds equipment production and deployment. In that environment, the organizations that win are not necessarily the ones that react first, but the ones that see the market clearly: where the growth is concentrated, how competitors are positioned, which standards are becoming more operationally important, and how procurement decisions can be timed to capture advantage without overcommitting.
This executive preview is intended to demonstrate the depth and practical orientation of the Worldwide Fabric Flame Retardancy Testers Market research. The full study extends far beyond this summary, providing the segmentation detail, company comparisons, and forward-looking synthesis that procurement leaders, strategy teams, and industry analysts need to act with confidence in 2026 and beyond. For complete market figures, regional and application-level breakdowns, and the full competitive readout, access the complete report.
For detailed analysis of this topic, please visit the official page: Worldwide Fabric Flame Retardancy Testers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Automatic Cosmetic Powder Pressing Machine Market to Hit $273.05M by 2032
By pmarketresearch, 2026-09-16
Precision Meets Scale: Strategic Imperatives in the Global Automatic Cosmetic Powder Pressing Machine Market
Introduction: The Automation Imperative in Color Cosmetics Manufacturing
The global cosmetic manufacturing landscape is undergoing a structural transformation. As brands intensify production cycles, tighten quality compliance, and respond to volatile labor economics, the machinery that forms the foundation of pressed powder production has evolved from a tactical Capex line item to a strategic operational lever. The Worldwide Automatic Cosmetic Powder Pressing Machine Market 2026–2032 research report examines this inflection point with granular operational and commercial intelligence designed for executives navigating capacity planning, supplier selection, and regional expansion strategies.
For decision-makers in 2026, the question is no longer whether to adopt automated pressing systems, but how to align machine specifications, vendor partnerships, and geographic sourcing with long-term margin targets and regulatory realities. This report functions as a practical reference architecture, translating historical performance into actionable forecasting frameworks while mapping the competitive and regulatory forces that will shape procurement decisions over the next seven years.
Market Trajectory and Historical Context
From 2020 through 2025, the automatic cosmetic powder pressing machine market exhibited sustained expansion, driven by rising output volumes across both brand and contract manufacturing segments and the accelerated replacement of semi-manual forming lines. The market reached an estimated revenue base of approximately 172.5 million USD in 2025, compared with roughly 125.4 million USD at the start of the historical window in 2020. This trajectory reflects a compounding growth pattern that carries meaningful momentum into the forecast horizon.
Our base forecast projects the market to exceed 200 million USD by 2027, surpass 259 million USD in 2031, and approach 273 million USD by 2032. The implied compound annual growth rate of 6.78 percent during the 2026–2032 forecast period signals steady scaling rather than speculative hype. More importantly, the trajectory reflects structural adoption, not cyclical pullback. For procurement leaders, this means that late-stage investment decisions carry increasing opportunity cost as capacity-constrained vendors and high-demand OEM lines tighten delivery timelines. For equipment developers and channel partners, it signals durable demand for modular, automated, and compliance-aligned pressing architectures.
Executives relying on static Capex models risk underpricing automation. The report quantifies these timing dynamics and translates them into scenario-based planning parameters, enabling finance and operations teams to compare upfront equipment spend against multi-year throughput, quality consistency, and labor offset benefits.
Segment Architecture and Operational Demand Patterns
Automatic powder pressing equipment is not a monolithic category. The market bifurcates across machine architecture, regional manufacturing intensity, and end-user operating models. Understanding the relative weight of each segment informs everything from engineering roadmap decisions to channel strategy and service footprint planning.
The report segments machine types into single-color pressing machines, multi-color pressing machines, and rotary powder pressing machines. Single-color pressing machines capture the broadest share of installed and procured capacity, reflecting their suitability for standardized compact production and rapid line changeovers across high-volume color cosmetic SKUs. Multi-color pressing machines serve product lines requiring differentiated palette configurations or compact formats, where modular dosing and pressing arrays create measurable flexibility gains. Rotary powder pressing machines occupy a distinct niche, favored by manufacturers prioritizing continuous throughput and repeatable compaction density in compact and pressed powder lines.
Geographically, demand concentration is heavily skewed toward Asia Pacific, reflecting the region’s scale of contract manufacturing, export-driven production footprints, and rapid adoption of automated compact powder lines. Europe retains a substantial installed base, supported by mature brand manufacturing ecosystems and high-mix output requirements. North America continues to expand automated pressing capacity as U.S. manufacturers respond to compliance and labor pressure, while Latin America and the Middle East and Africa represent developing but increasingly meaningful deployment zones for both OEM supply chains and regional brand growth.
By end user, the market splits across contract manufacturers, cosmetic brands, and R&D and laboratory facilities. Contract manufacturers represent the largest operational demand pool, as they scale output for multiple brand clients and require equipment that balances speed, repeatability, and quick format changeovers. Cosmetic brands purchase pressing equipment to secure in-house production control, protect formulation IP, and reduce dependency on external lines during capacity crunches. R&D and laboratory facilities deploy smaller-scale and hydraulic lab variants to refine formulation behavior, test compaction parameters, and validate compacts before full-scale transfer, making these units strategically critical to product development velocity.
Rather than presenting the numbers as static charts, the report frames each segment through operational implications. Which machine type best matches a fast-SKU palette strategy. Where regional consolidation will tighten vendor lead times. How contract manufacturers prioritize throughput versus flexibility. These questions structure the segmentation analysis so that purchasing and engineering leaders can convert data into equipment selection criteria.
Press Machine Market
Competitive Landscape: Leaders, Specialists, and End-to-End Capabilities
The competitive field combines established European automation heritage with increasingly agile Chinese engineering and trade organizations serving global OEM demand. The report profiles several core participants and evaluates their positioning across automation level, product breadth, and geographic deployment.
GIENI, based in Shanghai, offers automatic and servo-type robotic compact makeup powder press machines, including bottom-up type configurations with PLC control and models such as the JGP-050SE servo robotic variant. Its portfolio targets pressing for eyeshadow, blush, face powder, and compacts, with an emphasis on full automation, consistent compaction, and modular designs suited to global cosmetic manufacturers. In February 2026, GIENI introduced user-friendly automated features on its bottom-up compact powder press machine, incorporating servo motor feeding, hydraulic compaction, auto discharging, and powder suction for eyeshadow, blush, and face powders. The company also showcased precision filling and related cosmetic production solutions, including powder equipment, at Cosmoprof Worldwide Bologna in March 2026, reinforcing its push into integrated production environments.
Eugeng International Trade Co., Ltd., also headquartered in Shanghai, specializes in full automatic cosmetic powder pressing machines such as the EGCP-08A for two-way cake, compacts, eye shadow, and blush, alongside hydraulic lab models like the EGCP-L1 and servo motor variants tailored for pressed powder production. Eugeng presented color cosmetics equipment portfolios at Cosmoprof Asia Hong Kong in 2025 and showcased cosmetic machinery including powder pressing equipment at the 29th China Beauty Expo in Shanghai in May 2025. These appearances underscore its active channel strategy and emphasis on broad format coverage across pressed-powder lines.
Guangzhou Jutao Machinery Equipment Co., Ltd. manufactures compacts powder pressing machines and automatic powder pressing models designed for eyeshadow, blush, pressed powder, and compact production, with customizable options. Guangzhou Yeto Machinery Co., Ltd. provides pneumatic and manual or lab-scale facial powder press machines, including one-mold models for compact powder production. Foshan Henwi Technology Co., Ltd. supplies semi-automatic and automatic hydraulic powder pressing machines for blush, eye shadow, eyebrow, highlighter, and pressed powder cosmetics. These entities illustrate the breadth of China-based capability across full automation, semi-automatic, and laboratory-scale configurations.
On the European side, Lorenzato S.r.l., based in Vicenza, Italy, has produced fully automatic rotary pressing machines, such as the LR 190, and semi-automatic or lab models in the LV120 series for compacting cosmetic powders including eyeshadow, blusher, and face powder into compacts. Its positioning since 1963 emphasizes precision, modularity, and Industry 4.0 compatibility. Bonals Technologies, operating globally from Spain, develops powder compacting presses adaptable for solid cosmetics, including eccentric and rotary models for dry or humid powders in cosmetic tablet and compact formats. Together, these players broaden the technology spectrum beyond high-volume single-type pressing toward continuous rotary architectures and mixed-compaction formats.
The report evaluates each profile against recurring procurement criteria: automation depth, service responsiveness, format adaptability, integration readiness, and regional deployment footprint. For buyers, this competitive mapping supports vendor shortlisting that balances performance with long-term maintainability and supply-chain resilience.
Worldwide Automatic Cosmetic Powder Pressing Machine Market
Market Dynamics: Compliance, Input Economics, and Labor Pressures
Behind every equipment purchase decision sits a set of dynamic forces that alter total cost of ownership and production risk. The report incorporates three core drivers that materially shape the automatic pressing machine market in 2026 and beyond.
Regulatory pressure is intensifying the demand for precision and repeatability. In the United States, the Modernization of Cosmetics Regulation Act of 2022 (MoCRA) requires facilities manufacturing cosmetic products to comply with updated Good Manufacturing Practice standards and adverse event reporting expectations. This shifts compliance from documentation alone to process reliability. For pressed-powder production, that means tighter compaction consistency, reduced variation across batches, and equipment configurations that support traceable, controlled forming operations. Manufacturers that rely on inconsistent or labor-dependent pressing methods face growing operational friction, which in turn increases interest in automated pressing platforms with controlled dosing, repeatable pressing force, and structured discharge workflows.
Input economics also influence equipment strategy. Steel costs matter to pressing machine frames, pressing dies, and structural components. U.S. Midwest Hot-Rolled Coil prices stabilized in the low-to-mid $800s per short ton range through mid-2025, with modest upward pressure expected into early 2026. Although equipment pricing reflects many cost components, the direction of steel pricing affects frame durability tradeoffs, build specifications, and vendor quoting behavior. The report contextualizes this dynamic so that buyers can evaluate whether quotes reflect structural cost escalation or short-term supplier margin adjustments.
Labor cost and availability remain persistent catalysts for automation. Automation in cosmetic manufacturing equipment, including powder presses, addresses ongoing labor shortages and rising input costs. Industry surveys indicate manufacturers expect overall input costs to increase by an average of 5.4 percent into the following year. Equipment that reduces manual loading, pressing, and discharge steps not only improves throughput but also reduces exposure to wage inflation and staffing volatility. For operations leaders, the business case increasingly rests on labor offset, process consistency, and the ability to maintain output during periods of acute labor constraint.
These forces do not operate in isolation. They interact with regional manufacturing economics, end-user procurement cycles, and machine architecture choices, creating a highly differentiated demand environment. The report traces these interactions rather than treating them as separate annotations, enabling Executives to model ROI under changing compliance, labor, and input-cost assumptions.
What the Report Delivers for 2026 Decision-Making
This Worldwide Automatic Cosmetic Powder Pressing Machine Market research is built for execution. It combines historical performance baselines with forecast scenarios, segmentation analysis, competitive profiles, and regulatory and input-market context in a single structured reference for strategy, procurement, and R&D leadership.
- Comprehensive market sizing across the historical window and 2026–2032 forecast period, with annual revenue trajectories and growth rate interpretation framed for planning and budgeting conversations.
- Segment-by-segment analysis across machine type, region, and end user, translated into operational implications for capacity selection, format flexibility, and geographic sourcing.
- Detailed competitive profiles covering product scope, automation emphasis, machine variants, and recent commercial or product developments, supporting vendor evaluation and channel strategy.
- Contextual dynamics on compliance drivers, input material trends, and labor economics, tied directly to equipment adoption and total cost of ownership considerations.
- Practical frameworks for decision-makers evaluating line expansion, format diversification, lab-to-production transfer, and automation investment timing.
Throughout the report, the emphasis remains on actionable intelligence. Readers gain clarity on where demand is concentrated, which machine architectures map to particular operational priorities, how leading suppliers position themselves, and how external pressure points shift the economics of automation. At the same time, precise regional share figures, segment-level revenue amounts, and detailed quantification beyond the headline trajectory are reserved for the full report, where they can be examined with the depth and supporting methodology that procurement and strategy teams require.
Conclusion: Converting Intelligence into Execution
The automatic cosmetic powder pressing machine market is entering a period in which the winners will be defined less by the mere presence of automation and more by how well equipment choices align with compliance, labor economics, format strategy, and regional supply realities. The 6.78 percent CAGR projected through 2032 is not a generic growth headline; it signals sustained investment in pressing automation across contract manufacturing, brand production, and product development environments.
For executives planning 2026 decisions, the opportunity lies in using market intelligence to shorten evaluation cycles, sharpen vendor comparisons, and time Capex against demand and cost trends. This report is designed to make that possible. It provides the strategic scaffolding to move from broad market awareness to specific, defensible equipment and sourcing decisions. To access the full segmentation depth, company-level assessments, and planning scenarios, readers are directed to the complete Worldwide Automatic Cosmetic Powder Pressing Machine Market research publication, where the granular data and proprietary analysis support concrete action across operations, procurement, and growth strategy.
For detailed analysis of this topic, please visit the official page: Worldwide Automatic Cosmetic Powder Pressing Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com