

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Taxi & Limousine Market Hits $312.45 Billion in 2025, 9.04% CAGR to 2032

Strategic Navigation in the Global Taxi and Limousine Services Market: A 2026 Outlook
The global transportation landscape is undergoing a structural transformation. As urbanization intensifies and consumer expectations shift toward seamless, on-demand mobility, the taxi and limousine services sector has evolved from a traditional utility into a dynamic, technology-enabled industry. Our latest comprehensive analysis, the Worldwide Taxi and Limousine Services Market report, provides decision-makers with the strategic clarity needed to navigate this rapidly changing environment through 2032.
Built on a rigorous historical baseline spanning 2020 to 2025 and extending into a forward-looking forecast period of 2026 to 2032, this study captures the scale, trajectory, and underlying forces shaping one of the most critical segments of the urban mobility ecosystem. The findings reveal a market that has demonstrated remarkable resilience and growth, driven by digital platform adoption, evolving regulatory frameworks, and an accelerating pivot toward sustainable fleet operations. For executives, investors, and strategic planners, the report serves not merely as a data compendium but as a decision-support instrument calibrated for the realities of 2026 and beyond.
Macro Trajectory and Market Scale
The historical arc of the global taxi and limousine services market tells a story of sustained expansion. Revenue in the base year of 2025 reached approximately 312.45 billion USD, building on a consistent upward trajectory that began at 165.2 billion USD in 2020. The intervening years reflect a pattern of steady compounding: 199.54 billion USD in 2021, 243.97 billion USD in 2022, 271.35 billion USD in 2023, and 275.54 billion USD in 2024. This progression underscores the sector's capacity to absorb external shocks while capitalizing on digital transformation and rising demand for personalized ground transportation.
Looking ahead, the forecast horizon paints a similarly compelling picture. The market is projected to advance to 341.47 billion USD in 2026, climbing to 370.85 billion USD in 2027, 409.1 billion USD in 2028, and 448.62 billion USD in 2029. By the close of the decade, revenue is expected to reach 480.06 billion USD in 2030, with continued momentum pushing valuations to 539.74 billion USD in 2031 and 572.74 billion USD in 2032. These figures translate into a forecast-period CAGR of 9.04 percent, a rate that signals robust structural growth rather than temporary cyclical uplift. For organizations evaluating capital deployment, market entry, or service-line expansion, this trajectory offers a reliable quantitative anchor for long-range planning.
Force Vectors Shaping the Competitive Landscape
Growth at this scale does not occur in a vacuum. The sector is being reshaped by intersecting forces that demand strategic attention. Digital platform integration continues to redefine how passengers access taxi and limousine services, blurring the lines between traditional street-hail models and app-driven ride-hailing ecosystems. At the same time, regulatory mandates are accelerating fleet modernization, particularly around electrification and accessibility. Jurisdictions across North America have advanced zero-emission requirements targeting the 2030 to 2035 window for transportation network company fleets, while frameworks such as the California Clean Miles Standard require participating companies to achieve 90 percent of vehicle miles traveled powered by electric vehicles by 2030, with greenhouse gas emission reduction plans submitted in 2026, 2028, and 2030.
These regulatory currents are complemented by operational shifts. Government funding and grant programs are increasingly subsidizing the acquisition of wheelchair accessible vehicles, broadening the inclusivity of taxi fleets while supporting compliance objectives. Simultaneously, the premium limousine and chauffeured segments are experiencing heightened demand from corporate clients who prioritize security-focused ground transportation, professionally trained drivers, and advanced safety features. This convergence of regulation, technology, and service-quality expectations is compressing the timeline for strategic adaptation and rewarding organizations that invest early in fleet diversification, compliance infrastructure, and premium service positioning.
Competitive Dynamics and Strategic Positioning
The competitive architecture of the global market reflects a dual structure: concentrated platform leaders operating across multiple continents and a highly fragmented base of regional and local operators. At the macro level, the top three enterprises account for approximately 38.5 percent of market revenue, while the top five collectively represent 46.8 percent. This concentration indicates meaningful scale advantages among platform incumbents, yet it also leaves substantial room for niche differentiation, regional dominance, and specialized service models.
Within this landscape, several enterprises have established themselves as strategic benchmarks. Uber Technologies Inc., headquartered in San Francisco, continues to function as a global leader in ride-hailing and taxi-like services, offering on-demand taxi, premium black car, and limousine-style options through its app platform across multiple continents. Lyft Inc., also based in San Francisco, serves as a major North American ride-hailing provider, delivering standard taxi-equivalent rides, shared options, and premium Lux and Black car services that compete directly in the taxi and limousine segments. In Asia, Didi Chuxing Technology Co., headquartered in Beijing, operates as a dominant Chinese ride-hailing platform providing taxi, express, and premium limousine-style services with extensive operations across Asia and select international markets. Grab Holdings Inc., based in Singapore, leads Southeast Asia as a super-app offering ride-hailing taxi services, GrabCar, and premium options across multiple countries in the region.
The European and African corridors are shaped by Bolt Technology OÜ (Taxify), an Estonian provider delivering taxi and premium car services in over 35 countries with a focus on affordable and reliable urban mobility. Ola (ANI Technologies Pvt. Ltd.), headquartered in Bengaluru, India, stands as a major Indian ride-hailing company providing taxi, micro, and luxury cab and limousine-style services with significant domestic fleet operations. Business-focused mobility is advanced by Gett Inc., operating from Tel Aviv and London, which offers corporate taxi, black cab, and limousine options with strong presence in Europe and Israel. Addison Lee Limited, based in London, specializes in UK premium taxi and private hire and limousine services, emphasizing executive chauffeured transport and corporate contracts. Blacklane GmbH, headquartered in Berlin, functions as a global chauffeur and limousine service provider, offering premium airport transfers, hourly, and inter-city limousine services in hundreds of cities worldwide. In the Middle East, Careem, now a Uber subsidiary headquartered in Dubai, provides taxi, economy, and premium car and limousine services integrated with Uber operations. Cabify, based in Madrid, focuses on Latin American and Spanish ride-hailing with an emphasis on safe, premium taxi and private car transport and corporate positioning.
Public-sector and traditional operators remain strategically relevant. Dubai Taxi Corporation, a government-backed operator, provides standard taxi, ladies' taxi, and limousine services at Dubai airports and across the emirate. In Japan, Nihon Kotsu operates as a major taxi and limousine operator with a large fleet serving urban and airport transport needs, while Daiichi Koutsu Sangyo contributes to the domestic taxi and limousine ecosystem. On the premium chauffeured side, EmpireCLS Worldwide Chauffeured Services, based in the United States, delivers premium global chauffeured limousine and executive transportation for corporate and VIP clients, and Carey International, also US-based, maintains a long-established network of luxury limousine and chauffeured services with an international affiliate structure.
Recent developments illustrate how quickly operational realities can shift. In November 2025, the NYC Taxi and Limousine Commission reported progress on increasing electric vehicle charging infrastructure by 130 percent and making more than half of the taxi fleet wheelchair accessible. In March 2025, the NYC Council set a fiscal 2026 preliminary budget of 58.0 million USD for the Taxi and Limousine Commission to support regulatory and industry oversight. Meanwhile, in December 2024, Toronto Pearson Airport Taxi service was recognized for convenience and reliability in ground transportation, highlighting the enduring importance of service quality at key transit nodes.
Service Architecture and Mobility Segments
The market's internal architecture spans multiple service and vehicle dimensions, each with distinct growth drivers and investment implications. On the service side, online booking and ride-hailing has emerged as a central engine of transaction volume, reflecting the broader shift toward app-mediated mobility. Traditional offline taxi services continue to hold meaningful share, particularly in markets where street-hail infrastructure, medallion systems, or regulated pick-up points remain entrenched. Limousine and luxury services occupy a specialized but high-value position, supported by corporate travel, event transport, and VIP mobility requirements.
Vehicle composition is equally consequential. Economy and standard vehicles form the backbone of urban fleet operations, balancing affordability with coverage density. Executive and luxury cars cater to premium segments where comfort, branding, and driver professionalism are primary purchase drivers. Electric and hybrid vehicles represent a growing but still transitioning slice of the fleet, shaped by charging infrastructure availability, total cost of ownership calculations, and regulatory timelines. The interplay among these segments creates opportunities for operators to optimize fleet mixes, align service tiers with local demand profiles, and position for compliance-driven electrification without sacrificing service reliability.
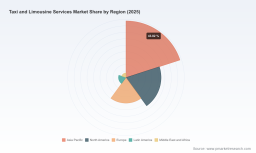
Regional variation further complicates strategic planning. Demand intensity, regulatory posture, platform penetration, and fleet composition differ materially across geographies. Asia Pacific exhibits substantial scale, supported by dense urban populations and rapid digital adoption. North America reflects a mature but evolving environment shaped by platform competition, regulatory experimentation, and premium service demand. Europe presents a patchwork of national and municipal frameworks, with strong emphasis on accessibility, emissions reduction, and urban mobility integration. Latin America and the Middle East and Africa each carry distinct dynamics tied to urbanization patterns, informal transport competition, and platform expansion strategies. Understanding these regional nuances requires granular analysis that goes beyond aggregate totals and into local demand structures, competitive intensity, and policy trajectories.
What the Full Report Delivers
This article provides a strategic preview, but the complete Worldwide Taxi and Limousine Services Market report offers the depth required for actionable decision-making. The study delivers a structured toolkit for executives who need to evaluate market entry, service expansion, fleet investment, partnership strategy, and regulatory preparedness.
Worldwide Taxi and Limousine Services Market
Inside the report, readers will find:
- A detailed segmentation analysis covering service types, vehicle categories, and regional demand structures, with forward-looking estimates that support capacity planning and revenue modeling.
- Competitive profiling of leading enterprises, including business model positioning, geographic footprint, service offerings, and strategic implications for incumbents and new entrants.
- Market concentration metrics and structural analysis that clarify where scale advantages exist and where fragmentation creates room for targeted differentiation.
- Regulatory and policy mapping that tracks electrification mandates, accessibility requirements, and oversight frameworks across key jurisdictions, enabling proactive compliance and risk management.
- Industry context on emerging demand drivers, including corporate security-focused ground transportation, wheelchair accessible vehicle adoption, and premium chauffeured service growth.
- Forecast scenarios through 2032 that help organizations stress-test strategic assumptions against multiple growth pathways and external shocks.
The report is designed to translate macro trends into operational insight. Rather than stopping at headline figures, it connects market size and growth rates to the structural factors that determine which business models thrive, which fleet strategies remain viable, and which regulatory environments will reward early adaptation. For investors, the study supports valuation context and competitive benchmarking. For operators, it informs fleet mix decisions, service-tier positioning, and regional prioritization. For policymakers and industry associations, it provides an external reference point for balancing innovation, accessibility, and sustainability objectives.
Strategic Implications for 2026 Decision-Making
Entering 2026, organizations operating in or adjacent to the taxi and limousine services market face a set of interconnected choices. The projected progression from 341.47 billion USD in 2026 toward 572.74 billion USD in 2032 indicates that demand will continue to expand, but the composition of that growth will vary by segment, region, and service model. Companies that treat electrification as a compliance burden rather than a strategic re-platforming opportunity risk falling behind peers who align fleet investment with charging infrastructure, total cost of ownership improvements, and customer expectations. Organizations that ignore the premiumization trend in corporate and VIP mobility may leave value on the table in segments where security, driver training, and service consistency command pricing power.
Regulatory planning is equally critical. With zero-emission mandates advancing across multiple North American jurisdictions and emission reduction plans coming due in 2026, 2028, and 2030 under frameworks such as the California Clean Miles Standard, operators need clear timelines and capital plans that synchronize with policy calendars. Accessibility mandates and grant-supported vehicle acquisition programs create both obligations and opportunities, particularly for fleets seeking to broaden service coverage while strengthening public-sector relationships. In parallel, the fragmented nature of the US taxi and limousine services industry, where no single company holds more than 5 percent market share and approximately 2 million businesses operate, means that localized strategy, partner selection, and service differentiation remain as important as scale.
The strategic window opened by 2026 is therefore one of alignment: aligning fleet strategy with regulatory horizons, aligning service offerings with corporate and premium demand, aligning regional expansion with local platform dynamics, and aligning investment plans with a growth trajectory that compounds at a 9.04 percent CAGR through 2032. Organizations that approach these choices with rigorous market intelligence will be better positioned to capture share, manage risk, and build durable competitive advantage.
Closing Perspective
The Worldwide Taxi and Limousine Services Market is entering a phase in which growth, regulation, and technology intersect more tightly than ever before. The historical record from 2020 through 2025 demonstrates the sector's capacity to expand under diverse conditions, while the forecast through 2032 signals that the next chapter will reward strategic precision. Platform leaders, regional operators, luxury chauffeured providers, and public-sector fleets each face distinct imperatives, but all share a common need for reliable, forward-looking intelligence.
This article has outlined the macro trajectory, the competitive architecture, the regulatory and operational force vectors, and the strategic questions that define 2026 decision-making. The full report goes further, supplying the segmentation detail, competitive profiles, regulatory mappings, and forecast structure required to convert strategic intent into executable plans. For executives and analysts who need to move beyond headlines and into the operational specifics that drive investment, partnership, and fleet decisions, the complete study provides the necessary foundation.
Ride Sharing Market
The mobility market will continue to evolve at the pace of technology, policy, and consumer expectation. Organizations that equip themselves with a clear, evidence-based view of that evolution will be best prepared to navigate the opportunities and constraints ahead. We invite decision-makers to consult the full Worldwide Taxi and Limousine Services Market report for the comprehensive intelligence needed to act with confidence throughout 2026 and the forecast period beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Taxi and Limousine Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com