

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Financial Services App Market to Hit $400.84B by 2032, 13.5% CAGR

Global Financial Services Apps: Strategic Intelligence for 2026 and Beyond
The Worldwide Financial Services App Market has crossed a decisive threshold. Between 2020 and 2025, revenue expanded from approximately $84.12 billion to $165.2 billion, reflecting a compound annual growth rate of 13.5 percent across the forecast horizon through 2032. By 2026, the market is projected to reach $183.0 billion, with continuation into the $400 billion range by 2032. These figures are not merely statistical artifacts; they signal a structural realignment in how consumers, enterprises, and institutions access, distribute, and monetize financial services through mobile channels. For executives making capital allocation, product roadmap, and partnership decisions in 2026, this trajectory demands more than awareness. It requires a diagnostically precise, forward-looking intelligence architecture that our latest market research delivers.
This article previews the strategic value embedded in our Worldwide Financial Services App Market study. The preview demonstrates analytical rigor, outlines the operational contents of the report, and sets the stage for deeper engagement. Core segmentation values, regional revenue splits, and platform-level shares are deliberately withheld here. To translate market signals into boardroom decisions, stakeholders must access the full report, where granular data tables, scenario projections, and competitor benchmarks are published in executable format.
The Strategic Imperative: Why 2026 Decisions Require Differentiated Intelligence
Financial services applications no longer operate as discrete digital conveniences. They have become the primary orchestration layer for money movement, asset allocation, insurance distribution, and credit origination. The market's sustained expansion is powered by simultaneous forces: embedded finance integration, real-time payment network maturity, regulatory data-sharing mandates, and rising consumer expectations for unified financial experiences. Yet growth velocity alone is insufficient for strategy. Decision makers must understand where value concentrates, how platform dynamics shape cost structures, which competitor moves alter competitive moats, and what regulatory inflection points will redefine compliance economics.
Our study is engineered for that purpose. It converts macro momentum into actionable decision scaffolding. Rather than offering a single point estimate, the research maps growth durability across multiple horizons, identifies structural shifts in service adoption, and isolates the operational and compliance variables that will differentiate winners from laggards. The result is a decision-grade intelligence asset that supports product investment, geographic prioritization, partnership design, and risk modeling.
What the Research Delivers: Operational Depth for Enterprise Planning
The report is structured to support cross-functional planning teams, from product and engineering to compliance, corporate development, and investor relations. Its contents are designed for immediate operational translation rather than abstract commentary.
Scope and Time Architecture
The research anchors historical analysis in the 2020-2025 window and extends forward-looking projections through 2032. This dual lens enables teams to validate emerging patterns against observed behavior while stress-testing strategic options against credible forward trajectories. Revenue is assessed in U.S. dollars at the billion scale, providing a consistent basis for investment sizing, market entry evaluation, and competitive benchmarking.
Service Category Mapping and Application Pathways
The study decomposes the market across core service categories, including digital banking and payments, investment and wealth management, insurance technology, and personal finance tools. This structure helps enterprises understand where user engagement, monetization intensity, and ecosystem integration are evolving fastest. Importantly, the report avoids static category descriptions. It examines how these segments converge in practice through super app architectures, embedded capabilities, and cross-product bundling strategies.
Financial Planning Software Market
Platform and Distribution Dynamics
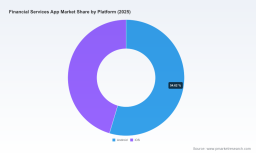
Mobile financial services operate across heterogeneous platform environments, and the research captures the relative scale and strategic implications of major operating ecosystems. Rather than treating platform share as a vanity metric, the analysis connects adoption patterns to development cost, user acquisition economics, compliance complexity, and feature rollout cadence. These insights help technology leaders sequence platform investments and avoid misallocated engineering resources.
Competitive Intelligence and Ecosystem Mapping
The report profiles the companies shaping the market's architecture, ranging from consumer-facing super apps and digital wallets to core banking platform providers, payment infrastructure firms, and network operators. Profiles extend beyond corporate summaries to capture functional positioning, partnership relevance, and ecosystem leverage. For corporate development teams, this mapping supports targeted partnership screening, acquisition thesis refinement, and competitive response modeling.
Regulatory and Infrastructure Context
Market expansion does not occur in a vacuum. The research integrates regulatory and operational variables that directly influence product design, data architecture, and cost profiles. This includes the implications of operational resilience requirements for financial entities and critical ICT providers, consumer financial data rights rules that mandate secure API-based data sharing and portability, and data sovereignty mandates that affect where transaction processing can occur. On the infrastructure side, the study accounts for rising energy and data center demands that influence the cost environment for cloud-dependent financial applications. These factors are not peripheral. They shape compliance roadmaps, localization strategies, and total cost of ownership for digital financial services.
Competitive Landscape: Architectures, Not Just Players
The market is defined less by a single dominant monopoly than by layered ecosystems, each competing on distribution, trust, infrastructure, and embedded functionality. The research examines a broad competitive field that includes global super apps, payment and wallet platforms, core banking and digital engagement vendors, payment infrastructure and SDK providers, card network operators, and consumer finance platforms.
Several competitive patterns emerge. First, super app models continue to demonstrate the power of consolidation, where payments, lending, insurance, and wealth capabilities are unified within a single mobile environment. This approach reduces friction, increases session depth, and creates cross-sell pathways that isolated apps struggle to replicate. Second, platform and infrastructure providers exert growing influence by enabling embedded finance through SDKs, APIs, and core banking modules. Their strategic importance lies not only in transaction volume but in their ability to lower integration barriers for institutions and innovative fintechs alike. Third, network operators and payment processors remain critical enablers of secure transaction flows, tokenization, and cross-border interoperability, increasingly partnering with app ecosystems rather than merely processing behind the scenes.
Recent operational developments reinforce the velocity of change. Fraud detection platforms have been strengthened with network-level intelligence to identify emerging fraud rings earlier and support real-time payment integrations. Tokenized deposit offerings and programmable stablecoin experimentation have expanded within institutional and application contexts. Partnerships linking banking clients with stablecoin and digital asset integration capabilities are being launched to support new asset workflows in mobile banking apps. Meanwhile, real-time payment networks have recorded substantial increases in both transaction volume and value, with request-for-payment features enabling smoother account-to-account interactions inside financial applications. These developments matter because they change the baseline for fraud management, settlement design, product innovation, and partnership strategy.
Worldwide Financial Services App Market
Structural Dynamics: Where Value Meets Constraint
The market's trajectory is shaped by intersecting forces that reward scale, interoperability, and resilience while penalizing fragmented or compliance-blind designs.
Regulatory Realignment
New regulatory frameworks are redefining data handling, operational resilience, and consumer control. Financial services apps must increasingly support secure, consumer-directed data sharing and portability through API-based architectures. At the same time, resilience obligations are tightening for financial entities and critical ICT providers, raising the bar for security controls, incident response, and third-party risk management. For global operators, data sovereignty requirements add another layer of complexity, often requiring localized processing and storage decisions that affect architecture, vendor selection, and launch sequencing. These dynamics do not merely constrain; they reshape competitive advantage by favoring organizations that build compliance into product design rather than retrofitting it.
Infrastructure and Cost Pressure
Digital financial services depend on cloud computing and data center capacity, and energy market dynamics are becoming a more visible component of operating economics. Rising electricity costs associated with expanded data center demand can influence total cost structures for high-volume application platforms. In some regions, utility pricing adjustments and dedicated rate structures for large energy users are being introduced to manage the impact on broader rate bases. For financial services application leaders, this means infrastructure economics deserves board-level attention alongside feature roadmaps and user growth targets.
Ecosystem Convergence
The boundaries between banking, payments, investment, insurance, and commerce are blurring inside mobile experiences. Users increasingly expect continuity across functions, and institutions are responding through embedded partnerships, platform modernization, and unified identity and data layers. This convergence amplifies the importance of integration quality, trust signals, and real-time responsiveness. It also increases the strategic stakes of choosing whether to build proprietary capabilities, partner with infrastructure providers, or participate in network ecosystems.
Translating Market Intelligence into 2026 Actions
The strategic value of this research lies in its ability to convert broad momentum into executable priorities. For product and engineering leadership, the study informs sequencing decisions around platform investment, embedded finance integration, real-time payment enablement, and fraud resilience. For corporate development and partnership teams, it supports identification of ecosystem leverage points, infrastructure dependencies, and collaboration models that accelerate time to market without sacrificing control. For compliance and risk functions, it contextualizes regulatory obligations within product design, data localization, and operational resilience planning. For executive teams and investors, it provides a disciplined framework for evaluating growth durability, concentration risk, and the economic implications of infrastructure and regulatory change.
Crucially, the report is not designed to be read once and shelved. It is structured to support scenario analysis, benchmarking, and recurring strategic reviews. Market leaders can use it to validate internal assumptions, challenge optimistic or pessimistic biases, and align cross-functional teams around a shared evidentiary baseline.
Why the Full Report Is the Next Step
This preview establishes the analytical framework and strategic breadth of the study. It demonstrates that the research goes beyond surface-level growth narratives to address service categories, platform dynamics, competitor architectures, regulatory shifts, and infrastructure realities. However, the most decision-relevant elements are contained in the complete report. Detailed segmentation values, regional and category-level revenue structures, platform distribution profiles, concentration metrics, and company-specific benchmarking are essential for calibrated strategy. Without them, leaders risk overgeneralizing from macro trends or mistaking headline growth for actionable opportunity.
To access the full intelligence set, including the data tables, competitive profiles, and forward projections that support precise planning, stakeholders should consult the complete Worldwide Financial Services App Market research. The report is intended for teams that must move from awareness to allocation, from intuition to evidence, and from narrative to execution. In a market expanding toward the $400 billion range over the forecast horizon, the cost of incomplete intelligence is far greater than the effort required to obtain it.
For detailed analysis of this topic, please visit the official page: Worldwide Financial Services App Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com