

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Oxcarbazepine Market Hits $310M in 2025, Poised for 3.15% CAGR to 2032

# Strategic Intelligence for the Coming Cycle: Inside the Global Oxcarbazepine Market Outlook
Executive Overview
The global pharmaceutical landscape for antiepileptic drugs is undergoing a subtle but significant transformation. As patent exclusivities fade and generic penetration deepens, the Oxcarbazepine market stands at a critical inflection point. Our latest Worldwide Oxcarbazepine Market research report provides a comprehensive strategic roadmap for stakeholders navigating this mature yet evolving therapeutic sector. This document serves as an introduction to the full intelligence suite, designed to equip corporate strategy teams, investors, and supply chain executives with the data necessary to make informed decisions throughout the 2026-2032 forecast period.
Oxcarbazepine remains a cornerstone therapy for partial seizures and various neurological conditions. Its position on the WHO Model List of Essential Medicines underscores its clinical necessity, ensuring steady demand regardless of broader economic fluctuations. However, the commercial dynamics are heavily influenced by manufacturing capabilities, regulatory approvals, and regional reimbursement structures. Understanding the interplay between these factors is no longer optional for market participants aiming to secure market share or optimize procurement strategies.
Market Trajectory and Historical Context
To project future performance, one must first understand the historical baseline. The market has demonstrated resilience over the past five years, navigating supply chain disruptions and regulatory shifts while maintaining a positive growth trajectory. Based on our analysis, the global revenue for Oxcarbazepine reached approximately 310.0 Million USD in the base year of 2025. This figure represents the culmination of a recovery phase following earlier market contractions observed in 2022.
Looking forward, the market is projected to expand from this baseline toward a valuation exceeding 385 Million USD by the end of the forecast period in 2032. This growth is underpinned by a Compound Annual Growth Rate (CAGR) of 3.15 percent. While this rate may appear moderate compared to novel specialty therapeutics, it reflects the stability of a mature generic market where volume growth is driven primarily by epidemiological factors and increased access in emerging economies rather than price premiums. For strategic planners, this signals a shift from aggressive expansion tactics to efficiency-driven consolidation and supply chain robustness.
Competitive Landscape and Key Players
The competitive environment is characterized by a high concentration of generic manufacturers, predominantly based in India, with significant participation from established pharmaceutical giants in North America and Europe. Our report details the strategies of twelve key companies that define the current market structure. These entities compete not on novel molecular entities, as the primary US patent expired in 2007, but on supply reliability, formulation versatility, and regulatory compliance.
Leading the pack is Teva Pharmaceutical Industries Ltd., headquartered in Petah Tikva, Israel. As a global manufacturer, Teva offers a wide range of strengths including 150mg, 300mg, and 600mg tablets alongside oral suspensions, distributed across the US and European markets. Their scale provides a significant competitive moat in terms of distribution network reliability. Similarly, Viatris Inc., based in Canonsburg, PA, maintains a strong presence with both immediate-release and extended-release formulations distributed worldwide.
The Indian pharmaceutical sector plays a pivotal role in the global supply chain. Sun Pharmaceutical Industries Ltd. and Dr. Reddy's Laboratories Ltd., both headquartered in Mumbai and Hyderabad respectively, leverage ANDA and EMA approvals to supply regulated markets. Dr. Reddy's specifically highlights USFDA approval for their tablet exports, marking a key compliance benchmark. Lupin Ltd. and Aurobindo Pharma Ltd. further strengthen this cohort, with Lupin having launched a USFDA-approved oral suspension in 2022 and Aurobindo supplying multiple strengths to North American markets. Additional key players such as Zydus Lifesciences Ltd., Cipla Ltd., Sandoz International GmbH, Apotex Inc., MSN Laboratories Pvt. Ltd., and Alembic Pharmaceuticals Ltd. contribute to a fragmented but highly regulated supply base.
Recent developments highlight the dynamic nature of this competition. In September 2023, MSN Laboratories received final USFDA approval for their extended-release tablets, opening new avenues for US market entry. Conversely, the market faced supply tightness in 2022 and 2023, prompting the US FDA to resolve a national shortage of 300mg tablets by June 2023 following increased manufacturing output. These events illustrate the fragility of supply chains and the strategic importance of manufacturing redundancy.
Segmentation Dynamics
Understanding where value is generated is critical for targeted investment. Our research dissects the market across three primary dimensions: Region, Formulation, and Application. While specific percentage allocations are proprietary data points detailed in the full report, the structural hierarchy is clear.
Formulation and Application Preferences
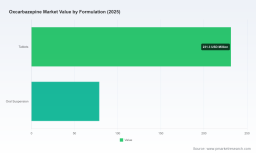
In terms of formulation, solid oral dosage forms continue to dominate consumption patterns. Tablets represent the bulk of revenue generation, favored for their stability and ease of distribution compared to liquid forms. However, oral suspensions maintain a vital niche, particularly for pediatric patients or those with swallowing difficulties, representing a key area for product differentiation among generic manufacturers.
Regarding therapeutic application, the vast majority of demand is driven by epilepsy treatment. This aligns with the drug's primary indication and its inclusion in essential medicine lists globally. A secondary but stable segment comprises other neurological disorders, providing a diversified revenue stream for manufacturers who hold broader labeling approvals. The interplay between these segments dictates inventory planning and marketing focus for commercial teams.
Regional Distribution
Geographically, the market is distributed across five key regions: North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. North America remains the largest revenue contributor, supported by high prescribing rates and established reimbursement pathways such as Medicare Part D, which typically covers the drug with manageable copays. Europe follows as a significant market, driven by stringent regulatory standards and universal healthcare coverage in many nations. The Asia Pacific region represents a growth frontier, where increasing diagnosis rates and improving healthcare infrastructure are expanding access. Emerging markets in Latin America and the Middle East and Africa, while smaller in total revenue, offer long-term potential for manufacturers with localized supply capabilities.
Industry Dynamics and Strategic Risks
Operating in the Oxcarbazepine market requires navigating a complex web of regulatory and supply chain dynamics. One of the most critical factors is the status of Intellectual Property. With the US patent (US 5,753,697) having expired in December 2007, the market is open to multiple generic entries. This absence of patent protection keeps prices competitive but pressures margins, necessitating high-volume efficiency for manufacturers.
Supply chain resilience is another paramount concern. The reliance on Active Pharmaceutical Ingredient (API) sourcing from India and China creates potential vulnerability. Our analysis notes that over 20 manufacturers have Drug Master File (DMF) filings listed in the US FDA database, indicating a robust but complex supply network. Disruptions in this network were evident during the 2022-2023 period when manufacturing delays led to intermittent shortages of 300mg and 600mg tablets in the US. Companies that secured multiple API sources or maintained higher inventory buffers were better positioned to capture market share during these disruptions.
Reimbursement policies also shape market access. In the United States, coverage under Medicare Part D with average generic copays ranging between 10 and 30 USD per prescription ensures patient adherence but limits pricing power. In other regions, national health service formularies dictate availability. Strategic planners must account for these policy frameworks when forecasting volume and revenue.
Worldwide Carbamazepine Market
Strategic Value for 2026 Decision Making
Why is this research vital for your 2026 planning cycle? The answer lies in the granularity of the intelligence provided. High-level market size figures are available publicly, but understanding the actionable nuances requires deep-dive analysis. This report moves beyond macro trends to provide actionable intelligence on capacity expansion, regulatory pipelines, and competitive maneuvering.
For procurement officers, the report offers insights into supplier reliability and regional manufacturing strengths, crucial for mitigating shortage risks. For commercial leaders, the segmentation data helps identify underserved niches, such as specific formulation strengths or emerging regional markets where competition is less saturated. For investors, the concentration metrics and company profiles provide a clear view of market dominance and potential consolidation opportunities.
The market concentration data indicates that while the top three players hold a significant share, the top five collectively control more than half of the market revenue. This suggests that while barriers to entry exist primarily through regulatory compliance and scale, there is still room for specialized players to compete effectively through niche formulations or superior supply chain logistics.
Worldwide Oxcarbazepine Market
Conclusion and Report Access
The Worldwide Oxcarbazepine Market is a stable yet competitively intense environment where success depends on operational excellence and strategic foresight. The projected growth to 2032 offers opportunities, but realizing them requires a clear understanding of the underlying dynamics detailed in our full study.
This introduction has outlined the macroeconomic landscape, the key competitive actors, and the critical industry drivers. However, the detailed segmentation splits, proprietary growth rates for specific sub-regions, and comprehensive financial modeling are reserved for the complete market research report. To access the full dataset, including specific regional revenue breakdowns, deep-dive company profiles, and actionable strategic recommendations, please visit the PW Consulting website. Equip your organization with the precision intelligence needed to navigate the next cycle of growth in the global neurological therapeutics sector.
For detailed analysis of this topic, please visit the official page: Worldwide Oxcarbazepine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com