

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Fencing Lame Market Hits $52.18M in 2025, Projected 4.15% CAGR Through 2032

Strategic Intelligence in the Worldwide Fencing Lame Market: Navigating Growth, Regulation, and Competitive Shifts Through 2032
Executive Summary
The global fencing lame market represents a highly specialized yet strategically vital segment within athletic equipment manufacturing. As competitive fencing continues to professionalize, standardize, and expand across continents, the conductive jackets, bibs, and mask covers that form the core of scoring apparel are undergoing rapid material innovation, regulatory recalibration, and supply chain consolidation. Our latest Worldwide Fencing Lame Market study delivers a comprehensive, data-forward blueprint for executives, procurement leaders, and strategic planners who must make informed decisions in 2026 and beyond. Rather than offering static snapshots, this research maps the trajectory of market evolution, dissects the competitive architecture, and quantifies the operational implications of newly enforced international standards.
Electric Fencing Market
From a historical baseline spanning 2020 through 2025, the market has demonstrated consistent upward momentum, transitioning from early-cycle stabilization into a phase of accelerated commercial expansion. By the close of the base year, total industry revenue had solidified at a materially higher level than the early 2020s, reflecting sustained institutional procurement, rising club participation, and the gradual professionalization of amateur circuits. Looking ahead, the forecast window from 2026 through 2032 projects a compound annual growth rate of 4.15 percent, translating global valuation into the hundreds of millions of USD by the decade's end. This growth trajectory is neither uniform nor automatic; it will be shaped by regulatory compliance costs, raw material economics, regional distribution maturity, and the strategic positioning of a concentrated supplier base.
For leadership teams evaluating product roadmaps, inventory strategies, partnership frameworks, or market entry options, the study functions as a decision-grade instrument. It provides the structural clarity required to separate durable demand signals from short-term promotional cycles, while highlighting where compliance, certification, and material engineering intersect with commercial viability.
Historical Trajectory and Forward-Looking Growth Dynamics
The market's historical progression tells a story of steady institutionalization. Over the past half-decade, revenue generation has moved beyond cyclical tournament-driven spikes toward more predictable, volume-backed demand. This shift reflects the broader maturation of fencing as a structured sport with standardized training pipelines, formal club networks, and increasingly sophisticated competitive calendars. The transition from early 2020s valuation levels to the 2025 baseline underscores how procurement patterns have stabilized and expanded across both professional and developmental tiers.
The forward-looking horizon introduces a more complex dynamic. Growth will be propelled by sustained adoption of competition-grade apparel, but it will also be filtered through regulatory friction, material cost volatility, and the operational burden of homologation. Stakeholders must therefore interpret top-line projections not as guaranteed outcomes but as conditional pathways that depend on compliance readiness, supply chain agility, and region-specific adoption pacing. The study isolates these variables and maps their interplay, enabling executives to stress-test assumptions rather than rely on aggregate figures alone.
Report Architecture: Practical Intelligence for 2026 Decision-Making
This research is engineered for operational use rather than passive reading. It structures its analysis around the dimensions that directly affect sourcing, product development, pricing strategy, and market positioning. The report delivers actionable visibility across the following operational axes:
- Market sizing and trajectory analysis anchored in a defined historical window and extended through a long-range forecast period, allowing planners to align budgeting cycles, production scheduling, and inventory strategies with credible demand curves.
- Segment-level breakdowns that clarify how product configurations, material compositions, application environments, and end-user categories shape revenue distribution, purchasing frequency, and margin potential without exposing the granular figures reserved for the full dataset.
- Competitive profiling that evaluates manufacturing heritage, geographic footprint, certification status, product engineering emphasis, and distribution reach across the firms actively shaping supply and pricing.
- Regulatory and technical dynamics that translate material standards, electrical resistance thresholds, impact resistance requirements, and homologation procedures into commercial implications for compliance, cost structure, and time-to-market.
- Strategic scenario framing that helps executives anticipate how policy updates, licensing frameworks, and label mandates may reshape supplier economics and procurement planning.
Each section is designed to feed directly into strategic planning workflows. Procurement teams can use the segmentation architecture to align specifications with end-user requirements. Product leaders can benchmark material choices against performance and compliance expectations. Commercial teams can interpret competitive positioning to identify whitespace, partnership opportunities, or distribution gaps. By integrating quantitative direction with qualitative structural analysis, the report transforms market intelligence into executable insight.
Regulatory Regimes and Technical Standards as Strategic Variables
The fencing lame market is unusually sensitive to rule-driven specification changes. International governing bodies dictate not only competitive eligibility but also the technical thresholds that manufacturers must meet to place gear on approved circuits. Recent regulatory activity has introduced meaningful operational considerations for suppliers, distributors, and institutional buyers.
Material rules now require conductive thread architecture in both warp and weft directions, with electrical resistance measured under defined testing conditions not exceeding five ohms between any two points. These specifications directly influence fabric engineering, production consistency, and quality assurance workflows. At the same time, safety standards require FIE-approved fencing clothing and lames to meet 800N perforation resistance thresholds for international competition, a substantial elevation from the 350N level associated with non-FIE gear. For manufacturers, this means that compliance is not a documentation exercise but a material and structural commitment that affects design, sourcing, and production validation.
Recent governance updates have also escalated the administrative and financial footprint of participation in approved supply channels. Supplier registration now carries annual licensing obligations, per-product-type fees, and mandatory labeling requirements for homologated equipment, including jackets and clothing. These requirements influence unit economics, minimum viable scale, and the cost of maintaining an approved catalog. For market entrants or smaller producers, the cumulative burden can function as a barrier that reinforces incumbency advantages. For established manufacturers, it creates an opportunity to differentiate through certification readiness, consistent homologation performance, and transparent compliance documentation.
Additional regulatory attention has extended to apparel presentation and identity standards, including updates to mask drawings and national logo guidelines for fencing clothing and uniforms. While these changes may appear cosmetic, they influence design pipelines, print integration, and manufacturing workflows for lame-integrated apparel. Companies that proactively align design systems with updated visual and structural guidelines can reduce rework cycles and accelerate time-to-market for season releases.
The study integrates these dynamics into a cohesive operational narrative. Rather than treating regulation as an external footnote, it evaluates how compliance architecture interacts with material selection, production planning, certification sequencing, and commercial pricing. This approach ensures that decision-makers understand not only what the rules are, but how they reshape competitive advantage.
Competitive Landscape: Concentration, Capability, and Strategic Positioning
The market's competitive architecture is marked by meaningful concentration. A limited group of firms accounts for a disproportionate share of industry revenue, reflecting the specialized nature of high-performance conductive apparel, the importance of FIE registration, and the procurement preferences of clubs, federations, and professional circuits. This concentration shapes pricing power, supplier relationship dynamics, and the barrier to entry for new manufacturers seeking to compete on technical merit alone.
Within this environment, competitive differentiation emerges through several intersecting capabilities. Manufacturing heritage and in-house production control remain strategically significant, particularly for firms that can manage material selection, conductive fabric integration, and quality validation internally. German and Central European producers have historically emphasized ultralight construction, washable electric jacket designs, and premium stainless steel or conductive fabric solutions tailored to top-level competitors. Their positioning often centers on performance consistency, international registration status, and institutional trust accumulated through long-term use in elite circuits.
Hungary-based manufacturing has carved a distinct role by combining full-range gear production with federation supply relationships and FIE partnership status. This model reinforces both volume stability and credibility in competition-grade equipment. UK-based specialists contribute through established competition equipment distribution, worldwide fulfillment, and product focus on foil and other lame configurations, reinforcing their role as accessible competitive gear providers for a broad international customer base.
In the United States, distributors and suppliers function as critical commercial conduits, aggregating premium brands, maintaining FIE-registered supply channels, and serving clubs, schools, and individual competitors through established retail and B2B networks. Their strategic value lies in distribution reach, brand curation, and the ability to connect end users with certified product lines. Meanwhile, Chinese manufacturers have expanded their footprint by producing foil, sabre, and epee lames alongside conductive fabric solutions, often emphasizing copper-tin combined conductive materials and full-equipment supply capabilities. Their growth reflects broader manufacturing scale, cost efficiency, and increasing integration into globally registered supply networks.
French manufacturing presence and additional registered producers further complicate the landscape by contributing to regional supply diversity and specialty apparel integration. Across these players, the differentiating factors include FIE registration status, material engineering expertise, production geography, distribution model, and the ability to satisfy both competition-grade and developmental-tier requirements.
The report assesses these companies not as isolated profiles but as elements of a competitive system. It examines how concentration influences procurement leverage, how certification and registration shape market access, and where capability gaps or distribution strengths create strategic opportunities. This framing allows executives to evaluate supplier reliability, partnership potential, and competitive vulnerability with greater precision.
Worldwide Fencing Lame Market
Regional Expansion and End-User Demand Architecture
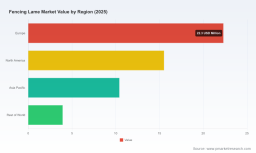
Market growth will not distribute evenly across geographies or customer categories. Regional demand patterns reflect differences in club infrastructure, federation activity, tournament density, procurement funding, and the pace at which competitive programs adopt standardized equipment. Europe continues to represent a substantial share of market activity, supported by established club networks and long-standing competitive traditions. North America contributes a significant but separately structured demand environment, shaped by institutional procurement, retail distribution, and school- and club-level participation. Asia Pacific reflects a growing adoption curve, driven by expanding program development and increasing integration into international competitive pathways. Rest of World demand remains smaller in scale but strategically relevant as emerging programs formalize equipment procurement and seek compliant, competition-ready gear.
End-user demand also follows a layered architecture. Clubs and schools form the most volume-relevant segment, reflecting recurring procurement cycles, training-program expansion, and the need for durable, compliant equipment at accessible price points. Professional athletes represent a narrower but high-specification demand pool, often prioritizing ultralight construction, washable electric jacket performance, and proven scoring reliability. Amateur enthusiasts contribute additional volume through developmental participation, though their purchasing behavior is more fragmented and more sensitive to price and availability. Understanding how these end-user categories interact with product type, material composition, and regional procurement norms is essential for aligning product lines, inventory planning, and channel strategy.
Strategic Takeaways for Leadership Teams in 2026
As the market moves through a period of regulatory tightening, material specification refinement, and competitive consolidation, the strategic implications are clear. First, compliance architecture is no longer peripheral; it is a core component of product viability and supplier credibility. Organizations that anticipate homologation requirements, certification timing, and labeling costs will be better positioned to protect margins and maintain uninterrupted supply.
Second, material and engineering decisions must be evaluated against both performance and regulatory thresholds. Conductive fabric composition, resistance consistency, and impact resistance specifications directly influence eligibility, customer trust, and product lifecycle value. Companies that treat these parameters as strategic levers rather than technical checkboxes can create durable differentiation.
Third, competitive concentration means that sourcing and partnership decisions carry heightened importance. Procurement leaders should evaluate not only unit economics but also registration status, distribution reliability, certification continuity, and the capacity to support institutional and professional programs at scale. Distributors and manufacturers alike must assess where their value proposition aligns with the evolving expectations of clubs, federations, and competition circuits.
Finally, growth planning should be scenario-based rather than linear. While the market's medium-term trajectory points toward continued expansion in global valuation, realized outcomes will depend on regional adoption pacing, regulatory burden distribution, raw material economics, and the strategic response of incumbent suppliers. Leadership teams that integrate these variables into forecasting, capacity planning, and channel strategy will be better equipped to convert market potential into operational results.
Conclusion: Why This Study Matters Now
The Worldwide Fencing Lame Market is entering a phase in which technical precision, regulatory readiness, and competitive positioning converge to define commercial success. The study provides the structural intelligence required to navigate that environment with confidence. It combines historical context, forward-looking growth direction, segmentation clarity, competitive assessment, and regulatory analysis into a single decision-support framework. For executives planning product strategy, procurement alignment, market entry, or partnership development in 2026, this research offers the depth needed to act decisively while avoiding overreliance on surface-level indicators.
To access the full dataset, detailed segmentation splits, company-by-company profiling, regulatory impact analysis, and the complete forecast architecture, we invite you to consult the complete report through our official research portal. The complete publication is designed to serve as a working intelligence asset for strategic planning cycles, procurement reviews, and competitive benchmarking initiatives throughout the forecast period.
For detailed analysis of this topic, please visit the official page: Worldwide Fencing Lame Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com