

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
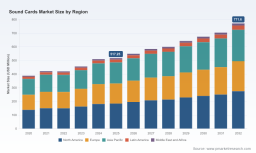
PW Consulting: Global Sound Card Revenue Hits $517.25M in 2025, Poised to Reach $771.6M by 2032 at 5.88% CAGR

Strategic Sonic Shifts: Why the Worldwide Sound Cards Market Demands Your Attention in 2026
The global audio landscape is undergoing a subtle yet profound transformation. What was once considered a commoditized component of computing hardware has evolved into a critical differentiator for user experience across gaming, professional broadcasting, and home entertainment ecosystems. For enterprise leaders, investors, and product strategists, understanding the trajectories within the Worldwide Sound Cards Market is no longer optional—it is a prerequisite for informed capital allocation and product roadmap planning. As we navigate through 2026, the convergence of semiconductor innovation, shifting consumption habits, and supply chain complexities creates a unique window for strategic advantage.
This article serves as a strategic overview of the market forces at play, drawing upon the comprehensive analysis found in the latest PW Consulting market research. Below, we outline the macro-economic contours, the competitive intensity, and the operational dynamics that will define value creation in this sector over the coming years.
Executive Summary: Market Trajectory and Aggregate Outlook
The Worldwide Sound Cards Market has demonstrated resilience and steady growth over the past five years, recovering robustly from early pandemic-era fluctuations to establish a stable upward trend. Based on historical data spanning from 2020 through 2025, the market has matured into a consistent revenue generator, setting the stage for a projected expansion phase through 2032. The aggregate valuation reflects a healthy demand curve, driven by both replacement cycles in consumer electronics and new adoption in high-fidelity professional environments.
Looking forward, the forecast period from 2026 to 2032 indicates sustained momentum. Analysts project a compound annual growth rate (CAGR) of approximately 5.88 percent during this horizon. This growth is not merely a function of unit volume but is increasingly tied to value-added features, higher fidelity standards, and the integration of advanced processing capabilities within audio interfaces. The revenue trajectory suggests that by the end of the forecast period, the market will reach significant scale, underscoring the enduring relevance of dedicated audio hardware even as integrated motherboard solutions become more sophisticated.
For stakeholders, this top-line growth masks significant variability beneath the surface. Success in this environment requires more than just observing aggregate numbers; it demands a granular understanding of where value is accruing. Is the growth coming from the enthusiast gaming segment pushing for higher signal-to-noise ratios, or is it driven by the professional studio market adopting multichannel solutions for remote production workflows? The strategic implications differ vastly depending on the answer. Our full report dissects these currents to reveal where specific investment opportunities lie, without relying solely on broad-stroke assumptions.
Market Segmentation: Navigating Type, Application, and Geography
While the macro view provides direction, the real strategic insights reside within the segmentation data. The market is not a monolith; it is a composite of distinct segments with unique drivers, barriers to entry, and profit margins. Understanding the interplay between these segments is crucial for targeted marketing and product development.
- Product Type Dynamics: The market is broadly divided between external peripherals and internal expansion cards. External solutions have gained traction due to plug-and-play convenience and the rise of USB-based high-fidelity interfaces, while internal PCIe cards remain dominant in specific enthusiast and gaming builds where latency and integration are paramount. The balance between these two categories shifts based on OEM partnerships and consumer preference for upgradeability versus convenience.
- Application Verticals: End-use application is a primary determinant of value. The gaming sector continues to be a major revenue contributor, fueled by immersive audio standards and competitive gaming requirements. However, the Professional Studio and Broadcasting segment represents a high-value niche where reliability and driver stability command premium pricing. Home Entertainment also contributes significantly, driven by the home theater PC movement and high-quality media consumption.
- Regional Heterogeneity: Geographic performance varies widely based on local electronics manufacturing hubs, consumer spending power, and regulatory environments. While some regions show mature saturation, emerging markets present greenfield opportunities for distribution expansion. Understanding the regional weightings is essential for supply chain localization strategies and sales force allocation.
The Strategic Value of Segmentation Depth
For a product manager or investor, knowing the total market size is insufficient. You need to know which segment is outperforming the CAGR, which application vertical is showing resistance to saturation, and where regional headwinds are emerging. For instance, if external sound cards are outperforming internal cards in the forecast period, inventory strategies must shift accordingly. If the Professional Studio segment shows higher margin resilience than the gaming segment during economic downturns, capital should be allocated differently.
Our detailed analysis provides the specific splits and growth rates for each region, type, and application, allowing you to model scenarios based on your specific exposure. Accessing the full dataset is necessary to validate these strategic hypotheses against precise quantitative evidence.
Competitive Landscape: Manufacturers and Strategic Positioning
The competitive environment in the sound card industry is fragmented yet characterized by distinct clusters of leadership. The market concentration indicates that while no single entity holds absolute dominance, a core group of players commands a significant share of revenue and technological innovation. The top three entities account for a substantial portion of total market revenue, and the top five extend this influence further. This concentration suggests a market where brand loyalty and ecosystem integration play critical roles in retention.
Key Players and Their Strategic Niches
Several major corporations define the competitive boundaries, each leveraging different strengths:
- Creative Technology Ltd. (Singapore): A legacy leader in discrete audio, Creative continues to leverage its Sound Blaster brand among gamers and enthusiasts. Recent developments include new external USB DAC/amp releases with enhanced drivers, signaling a push toward external high-fidelity solutions that complement their PCIe heritage.
- ASUSTeK Computer Inc. (Taiwan): Leveraging its motherboard dominance, ASUS offers the Xonar series, integrating audio solutions directly into the PC building experience. Their strategy relies on bundling and software ecosystems like Sonic Studio to add value for gamers and audiophiles.
- Realtek Semiconductor Corp. (Taiwan): As a major supplier of audio CODECs and chipsets, Realtek powers the majority of onboard and OEM solutions. Their competitive moat lies in volume and integration rather than discrete high-end marketing, making them a critical upstream player.
- Focusrite Plc (United Kingdom) & Universal Audio, Inc. (USA): These companies operate heavily in the professional audio interface space, often categorized within the broader sound card market. Focusrite's Scarlett series targets entry-to-mid-level professionals, while Universal Audio's Apollo series with Unison preamps and DSP processing caters to high-end recording studios requiring pristine conversion and processing power.
- RME Audio (Germany) & MOTU (USA): Focusing on ultra-low latency and robust driver support, these firms serve the professional broadcast and studio sectors where reliability is non-negotiable. Their value proposition centers on performance consistency rather than consumer marketing.
- Others: The landscape includes cost-effective contenders like Behringer and M-Audio for home studios, niche high-end manufacturers like HT Omega for audiophiles, and budget-friendly options from Sabrent. Meanwhile, semiconductor suppliers like C-Media Electronics and CMedia provide the underlying controller technology for various aftermarket solutions.
It is important to note that some former entrants, such as EVGA Corporation, have seen limited activity in recent periods, highlighting the volatility of hardware specialization. The dynamic between chipset suppliers and discrete card manufacturers creates a layered supply chain where strategic partnerships can dictate market access. Our full report includes detailed profile summaries and revenue assessments for each key company, enabling you to benchmark your position against these incumbents.
Industry Dynamics, Challenges, and Critical Success Factors
Operating in the sound card market in 2026 involves navigating a complex web of macroeconomic and technical variables. Supply chain resilience, regulatory compliance, and technological obsolescence are not merely operational headaches; they are strategic risks that can erode margins if not managed proactively.
Worldwide Sound Cards Market
Supply Chain and Component Availability
The semiconductor supply chain remains a critical vulnerability. Electronic component lead times, particularly for passives and discretes, tightened in late 2025. Some MOSFET and small signal devices have seen price increases amid geopolitical factors, impacting the cost structure for hardware manufacturers. Furthermore, U.S. export controls on advanced semiconductors and manufacturing equipment continued into 2026, affecting the availability and pricing of audio IC components. While the U.S. semiconductor industry maintained leadership with over 50 percent of global chip revenues in 2025 supported by CHIPS Act investments, tariff uncertainty persisted with potential impacts on imported semiconductors. Some Section 232 measures included exemptions for domestic use, but the regulatory environment requires constant monitoring. Companies must diversify sourcing and consider inventory buffering strategies to mitigate these shocks.
Technological Innovation and Obsolescence
The pace of innovation in audio conversion technology is accelerating. Audio DAC and ADC innovations continued, with new high-performance converters from specialized semiconductor firms supporting professional sound card applications. This raises the bar for what constitutes acceptable audio quality. Products relying on older conversion standards risk rapid commoditization. Conversely, early adoption of new converter technology can create a temporary competitive advantage in the professional and enthusiast segments. Strategic R&D investment is required to keep pace with these component-level advancements.
Strategic Imperatives for 2026
To thrive in this environment, organizations should focus on three core imperatives:
- Differentiation through Software and Ecosystem: Hardware alone is increasingly difficult to defend. Integration with software ecosystems, driver stability, and user-friendly control panels are becoming key decision factors for consumers and professionals alike.
- Supply Chain Robustness: Given the component lead time tensions and tariff uncertainties, securing reliable supply lines for key chipsets and passives is vital. Diversification of suppliers and strategic stocking may be necessary to maintain production continuity.
- Segment Focus: With varying growth rates across applications and types, a portfolio strategy that balances high-volume consumer segments with high-margin professional segments may offer the best risk-adjusted returns. Understanding which segment drives the overall growth is essential for resource allocation.
Conclusion: The Case for Deep Market Intelligence
The Worldwide Sound Cards Market is at an inflection point where historical patterns meet new technological and geopolitical realities. The projected growth remains positive, but the distribution of that growth is uneven across segments and regions. For decision-makers, the difference between capturing value and missing the window often lies in the granularity of the intelligence available.
This article has outlined the high-level contours of the market, the key players driving competition, and the external factors influencing dynamics. However, the true power of this research lies in the actionable data hidden beneath these summaries. Specific revenue splits, precise CAGR figures for individual regions, detailed company market shares, and quantitative scenario analyses are available only in the complete PW Consulting Worldwide Sound Cards Market research report.
Soundbars Market
Don't rely on generic industry summaries for critical 2026 strategic planning. Secure your organization's decision-making advantage by accessing the full comprehensive intelligence. Visit our source webpage to download the complete report, including detailed segmentation data, competitive landscape analysis, and forecast models tailored for enterprise use.
The audio hardware market rewards those who listen closely to the data. Ensure your strategy is tuned to the right frequency.
For detailed analysis of this topic, please visit the official page: Worldwide Sound Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com