

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Security Screening Market Soars to USD 14,100M by 2032 at 7.8% CAGR
By pmarketresearch, 2026-07-23
Security Screening Systems Market 2026: Strategic Imperatives for Procurement, Technology and Compliance
As global security priorities shift from episodic responses to persistent, intelligence-driven screening architectures, the Security Screening Systems market is entering a phase where strategic purchasing decisions in 2026 will dictate both near‑term operational resilience and multi-year cost outcomes. PW Consulting’s latest market study — grounded in five years of historical tracing and a seven-year forecast horizon — frames those decisions with rigorous financial projections, competitive intelligence, regulatory mapping, and operational playbooks designed for program owners, chief security officers, and procurement teams.
Security Screening Systems Market
Macroeconomic trajectory: validation for strategic investment
The market’s macro trajectory validates renewed capital allocation to screening capabilities. Using a 2025 base year, our topline metrics show sustained growth across the historical window and a forecast compound annual growth rate (CAGR) of 7.8% through 2032. In practical terms, this translates into a meaningful expansion of the addressable market over the next several years, driven by technology refresh cycles, regulatory upgrades, and demand for higher throughput and automated screening in transportation hubs and critical infrastructure.
Security Screening Systems Market
For decision-makers, the implication is twofold: first, competition for best‑of‑breed systems will intensify, increasing the importance of precise vendor evaluation; second, procurement windows are opening for integrators and managed‑service models that can deliver scale quickly while absorbing lifecycle risk. Our study quantifies the opportunity curve and, more importantly, isolates the investment inflection points where CapEx-to-Service tradeoffs yield optimal total cost of ownership (TCO).
Security Screening Systems Market
What this report delivers — actionable content, not generic summary
- Scenario‑based market forecasts and sensitivity analysis tied to technology adoption rates and regulatory shifts, enabling portfolio managers to stress‑test procurement plans under realistic upside/downside scenarios.
- Vendor strategy dossiers and a practical vendor scorecard methodology that evaluates suppliers on technical performance, systems interoperability, lifecycle services, cybersecurity posture, and commercial flexibility.
- Procurement playbooks and RFP templates crafted to minimize vendor lock‑in, accelerate deployment timelines, and ensure compliance with cross‑border data and radiation safety requirements.
- Operational deployment checklists for remote and centralized screening architectures, including guidance on staffing models, image‑review workflows, and performance SLAs for automated detection systems.
- Financial tools: TCO calculators, payback models, and procurement vs. as‑a‑service comparative analyses that contextualize capital investment against recurring costs and technology obsolescence risk.
Each deliverable is designed to be operational — not academic — allowing program leads to move from strategy to procurement within a standard fiscal quarter with clear governance artifacts and negotiation levers.
Market structure and competitive dynamics
Industry concentration remains moderate. The three‑firm concentration ratio (CR3) and five‑firm concentration ratio (CR5) indicate a market where leading platform providers hold meaningful but not dominant shares, leaving room for specialist entrants and regional incumbents to win targeted contracts. That structure creates a two‑track competitive dynamic: large systems integrators pursue scale projects (airports, ports, national border programs), while agile innovators capture trials and niche venue deployments (stadiums, schools, corporate campuses) with differentiated detection modalities.
Key players profiled in the report — each with distinct strategic plays — include long‑established scanning OEMs and emerging AI‑first entrants:
- Smiths Detection (United Kingdom): advancing CT‑based baggage and cargo screening with integrated AI and remote screening platforms; recent deployments include automated international remote baggage screening pilots that underscore a push into distributed operations supporting cross‑border customs authorities.
- OSI Systems / Rapiscan (United States): focused on high‑throughput non‑intrusive inspection systems for cargo and vehicle screening; recent contract wins reflect ongoing demand from logistics and border security programs.
- Leidos (United States): expanding capabilities through strategic partnerships to combine enterprise security solutions with advanced imaging, including millimeter wave and AI‑enabled passenger detection.
- Nuctech (China): offering advanced X‑ray and CT screening with increasing integration of machine‑learning stacks for automated threat recognition in cargo and passenger checkpoints.
- CEIA (Italy): continuing to defend core market share in walk‑through and handheld metal detection with robust product portfolios for public venues and transport hubs.
- L3Harris, Analogic, Evolv Technologies, and AS&E: each presents differentiated plays across imaging performance, medical‑grade imaging crossover, AI‑driven walk‑through detection, and non‑intrusive inspection systems respectively.
The most important takeaway for procurement leaders is to align vendor choice with program scale and risk appetite: incumbent OEMs and integrators offer stability and global service footprints, while newer entrants can deliver speed and disruptive detection capabilities but may require more stringent validation and contractual safeguards.
Regulatory and compliance imperatives shaping purchases in 2026
Regulation and standards are a decisive factor in procurement timing and system selection. The report synthesizes the practical implications of several key standards and funding signals that will influence buying behavior this year:
- Radiation safety frameworks (e.g., ANSI/HPS N43.17 guidance on dose limits) constrain design and operational use cases for systems employing ionizing radiation; screening programs must plan for regulatory testing and public communication strategies.
- Safety standards for millimeter‑wave systems (IEEE C95.1 family) remain the technical baseline for non‑ionizing screening solutions; certification lead times can affect rollout schedules, especially for public‑venue deployments.
- Targeted government funding — including dedicated allocations for computed tomography checkpoint baggage systems in recent fiscal appropriations — creates short windows for capex procurement aligned to budget cycles and grants.
- Interoperability and data handling: deployments that encompass cross‑border remote screening must embed personal data protection and cybersecurity controls to comply with national frameworks and customs agency requirements; these mandates have real contractual and systems‑architectural consequences.
Procurement teams must therefore include regulatory milestones and testing cycles in procurement schedules; failure to do so risks costly retrofit projects and delayed time‑to‑mission.
Technology trends and procurement implications
Three technology vectors are shaping procurement choices:
- AI‑augmented detection and image analytics — improving throughput and decreasing false positives, but increasing the need for explainability, labeled data governance, and performance benchmarking under adversarial conditions.
- Computed Tomography (CT) and advanced imaging — enabling higher detection fidelity and automated resolution, increasingly preferred at high‑throughput checkpoints; lifecycle and energy costs must be considered in TCO models.
- Distributed/remote screening operations — centralizing human image review away from checkpoints reduces staffing constraints and enables specialist operators, but raises data sovereignty, latency, and cybersecurity requirements.
In practice, these vectors shift procurement conversations from “box purchase” to “service and data contract” negotiations: buyers must secure software update guarantees, data access rights for model retraining, and explicit SLAs for algorithmic performance drift.
Risk and mitigation — what 2026 should prioritize
Major downside risks include regulatory delays, supply chain disruptions for critical imaging components, and cybersecurity breaches exposing screening data. To mitigate, the report prescribes:
- Staggered procurement phases with plug‑and‑play upgrade pathways to avoid single‑vendor lock‑in.
- Contract language that ties payment to accredited performance tests and independent validation, including adversarial penetration tests for AI models.
- Governance frameworks for data handling that satisfy multi‑jurisdictional privacy laws and customs cybersecurity protocols for cross‑border operations.
Recommended next steps for 2026 decision-makers
Based on the analysis, security program owners should take the following actions this fiscal year:
- Commission a short, vendor‑agnostic technology assessment to map existing assets against emerging capability requirements and regulatory obligations.
- Run a controlled pilot with clearly defined acceptance criteria tied to throughput, detection efficacy, and false‑alarm economics; include independent third‑party validation in the pilot scope.
- Update procurement specifications to require transparent AI model performance reporting, data portability clauses, and lifecycle upgrade commitments.
- Negotiate flexible financing — consider hybrid CapEx/Opex structures that retain upgrade options as detection technologies mature over the forecast horizon.
Why PW Consulting’s report matters for your 2026 plans
Our analysis is intentionally tactical: it translates macro growth (the market’s ascent from its 2025 base through a multi‑year CAGR) into procurement roadmaps, vendor evaluation frameworks, and compliance checklists that are immediately usable. The market’s moderate concentration profile provides both incentive and challenge — it rewards due diligence, not impulse purchases.
We have deliberately withheld detailed sub‑segment revenue breakdowns and granular regional or application shares in this preview to preserve the full strategic value of the research. The published report contains the complete segmentations, vendor scorecards, downloadable RFP templates, and working financial models you will need to finalize procurement in 2026.
Schedule a briefing with PW Consulting to align your program priorities to market timing, secure access to our vendor matrices, and accelerate procurement with validated TCO tools and compliance checklists.
For detailed analysis of this topic, please visit the official page: Security Screening Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Leather Market Poised to Reach USD 1,138 Million by 2032
By pmarketresearch, 2026-07-23
Leather Market 2026 Strategic Outlook — A PW Consulting Briefing
Executive snapshot
As a foundational material linking agriculture, manufacturing, fashion and mobility, the global leather market is entering 2026 from a position of cautious expansion. Our market model (base year 2025) shows the industry valued at approximately USD 732 million and tracking to a mid-single-digit compound annual growth rate (CAGR) of roughly 6.5% over the 2026–2032 forecast window. After pandemic-era shocks and subsequent uneven recovery through 2020–2025, the sector is re-accelerating, driven by premiumization in developed markets, resilient demand in select emerging markets, and sustained investment in downstream manufacturing and finished goods.
Leather Market
Why this report matters for 2026 corporate decision-making
2026 is a hinge year for leather-sector strategy: regulatory regimes (regional and global) are converging on traceability and chemical safety; consumer sentiment is reshaping premium vs. sustainable sourcing choices; and industry structure remains fragmented with top firms accounting for a minority share of global turnover. For executives deciding where to allocate capital, which suppliers to qualify, how to de-risk supply chains, or whether to pursue vertical integration or M&A, the strategic value of accurate, up-to-date market intelligence cannot be overstated. This briefing articulates the pathways where that intelligence converts into concrete decisions.
Leather Market
Macro dynamics and directional signals
- Growth trajectory: The market baseline in 2025 (~USD 732 million) and our 6.5% CAGR imply meaningful upside to 2032. The shape of that growth is not uniform—segments and geographies will outpace the headline due to differential demand drivers.
- Regulatory inflection points: The regulatory calendar through 2026 tightens requirements on origin verification, chemical management and documentation. Notable updates include EU-level deforestation due diligence affecting hides and prepared leather, OEKO-TEX® standards requiring supply-chain transparency, and revised chemical restrictions in major importing jurisdictions. These shifts create both compliance costs and competitive advantage for early adopters.
- Trade and geopolitics: Export behavior and trade flows remain sensitive to geopolitical tensions and tariff adjustments. Recent slippage in some national export volumes underscores the need for market diversification strategies.
- Industry concentration: The sector remains moderately fragmented—the aggregate share of the largest firms does not dominate the market—opening opportunities for consolidation, platform plays and specialist value-chain integration.
Five strategic priorities for 2026
- Secure traceable raw hides now:
With mandatory deforestation and origin verification regimes coming into force, firms that implement traceability systems (slaughterhouse delivery note reconciliation, digital chain-of-custody, supplier audits) in 2026 will avoid production bottlenecks and be first-movers in sustainability claims. Prioritize investments where your product mix is most exposed to regulatory scrutiny and where premium customers demand provenance.
Leather Market - Upgrade chemical and process controls:
Revised chemical restrictions and voluntary standards mean procurement teams must requalify tanneries and finishes against new limits. Implement a tiered supplier qualification (critical, strategic, conditional) and introduce contractual obligations for compliance testing and disclosure to limit downstream rejection and recall risk.
- Differentiate through product and service architecture:
Premiumization provides margin expansion opportunities—designers and manufacturers should convert material science advances (blended leathers, low-impact tanning) into distinct SKUs and marketing narratives while protecting core legacy ranges. For B2B players, bundle traceability and small-batch production as a value-added service for premium brands.
- Position for consolidation and strategic partnerships:
Fragmentation at the supplier and finished-goods levels creates acquisition and JV opportunities. Define acquisition criteria now—capacity, geographic footprint, supply-chain transparency, and niche branding—and prepare integration playbooks that preserve artisanal value while delivering scale improvements.
- Operational resilience and near-market manufacturing:
Reassess production footprints with an emphasis on reducing lead times for premium segments and de-risking exposures to single-source countries. Nearshoring or regionalization can be a competitive lever when combined with automated finishing and higher-margin product focus.
Competitive landscape — what to watch among established players
The market combines heritage tanneries, global branded manufacturers, and nimble niche players. Our qualitative benchmarking highlights strategic archetypes:
- Premium heritage tanneries (e.g., Horween Leather Company):
Strengths: Brand aura, high-margin full-grain and exotic leathers, long-standing OEM relationships. Strategic moves to monitor: selective capacity expansion, collaborations with fashion houses, and traceability pilots that extend the premium story.
- Branded footwear and apparel manufacturers (e.g., Wolverine Worldwide):
Strengths: Brand distribution, vertical integration potential, stable retail channels. Strategic moves: accelerating direct-to-consumer channels, embedding sustainability credentials into product lines, and hedging supply risk through multi-sourcing.
- Specialist European tanneries (e.g., Weinheimer Leder):
Strengths: Technical finishing expertise and proximity to luxury European buyers. Strategic moves: certifications to meet tightening EU standards and partnerships with niche luxury brands seeking traceability.
- D2C leather goods & lifestyle brands (e.g., Saddleback Leather Co.):
Strengths: Distinctive product narratives, customer loyalty, long warranties. Strategic moves: leveraging digital-first channels for premiumization, and collaborating with tanneries that can guarantee origin and high-quality finishes.
- North American furniture specialists (e.g., American Leather Holdings):
Strengths: Customization, domestic manufacturing cachet. Strategic moves: capitalizing on nearshoring demand and certifying supply chains to reassure commercial buyers.
- Export-focused manufacturers in South Asia (e.g., A.V. Thomas Leather; Bhartiya International):
Strengths: Cost-competitive manufacturing, scale in small leather goods and apparel. Strategic moves: upgrading compliance capabilities, pursuing higher-value product mixes, and leveraging trade fairs and export promotion programs to diversify markets.
For incumbent managers and investors, the competitive takeaway is clear: firms that combine product differentiation, verified supply chains, and regulatory-ready operations will capture disproportionate margin improvement in the next three years.
Regulatory and market events to monitor in 2026
- Implementation and enforcement timelines for EU deforestation due diligence affecting hides and prepared leather — immediate implications for exporters to the EU.
- OEKO-TEX® and similar voluntary standards raising the bar on disclosure and traceability ahead of regulatory enforcement.
- Revised chemical restrictions in major import markets tightening allowable treatments and requiring stronger upstream testing and documentation.
- National standards updates in major producing countries that will influence supplier qualification and export readiness.
- Industry trade fairs and showcases (regional leather fairs, design showcases, and international exhibitions) that are concentrating order flows and commercial visibility for manufacturers—use these as points for competitive intelligence and partnership discovery.
What PW Consulting’s Leather Market report delivers (operationally oriented)
Our full report is tailored for decision-makers who need executable intelligence rather than high-level commentary. It combines an audited market model (historical 2020–2025 and forecasts 2026–2032), scenario-led demand stacks, and practical tools that include:
- Regulatory heatmap and compliance checklist aligned to jurisdiction and product category through 2026.
- Supply-chain due-diligence templates (traceability, delivery-note reconciliation, audit protocols) that procurement teams can operationalize within 90 days.
- Supplier scorecards and a short-list of candidate partners for nearshoring, low-impact tanning and premium finishing.
- Go-to-market playbooks for premiumization, B2B partnerships, and D2C leather goods expansion.
- M&A playbook with valuation heuristics for target screening in a fragmented market (integration risks, product/brand preservation and synergies).
- Event and trade-fair calendar plus curated insights from industry showcases and primary interviews conducted during 2025–2026.
- Scenario-based financials and sensitivity analysis that link raw material volatility and regulatory compliance costs to margin outcomes.
On data transparency and what this briefing omits
In line with our “trailer” approach, this introduction highlights strategic conclusions and the operational levers you can employ in 2026—while we intentionally withhold granular segment-level tables (regional and application splits) and supplier-level financials from this public summary. The full intelligence set, including downloadable spreadsheets with detailed segmentation and supplier benchmarking, is available via the PW Consulting portal and through tailored briefings.
Recommended next steps for executives (quick checklist)
- Initiate a 90-day traceability sprint with top-10 raw hide suppliers and prioritized tanneries.
- Commission a compliance gap analysis against EUDR, OEKO-TEX and revised chemical restrictions to quantify near-term remediation costs.
- Identify one pilot nearshoring or small-batch manufacturing partner to reduce lead times for premium SKUs.
- Develop a bolt-on M&A shortlist focused on artisanal tanneries or niche finished-goods brands with defensible customer relationships.
- Schedule engagement at one major trade fair in 2026 to revalidate supplier claims and source innovations in finishes and low-impact tanning.
Concluding perspective
The leather market in 2026 offers a classic strategic paradox: enduring demand and margin pathways coexist with rising regulatory and reputational risk. Firms that treat compliance as a gateway to premium positioning—rather than a cost center—will convert regulatory alignment into commercial differentiation. Our full Leather Market study provides the granular segmentation, supplier-level intelligence, and operational playbooks you need to make those strategic choices with conviction. For access to the complete data, segmentation matrices, and a bespoke briefing customized to your strategic priorities, visit the PW Consulting Leather Market page or contact our industry team for a confidential executive session.
For detailed analysis of this topic, please visit the official page: Leather Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Epoxidized Soybean Oil Market Poised for 7.58% CAGR Through 2032
By pmarketresearch, 2026-07-23
Epoxidized Soybean Oil Market — Strategic Outlook for 2026
As companies calibrate strategy for the mid-decade inflection, epoxidized soybean oil (ESBO) sits at a crossroads of renewable feedstock dynamics, regulatory scrutiny, and PVC formulation demand. PW Consulting’s latest market study — anchored on a 2025 base year and providing a 2026–2032 forecast horizon — synthesizes historical performance (2020–2025) with forward-looking scenarios to help executives convert market movement into defensible decisions. The market’s compound annual growth rate in the forecast window is modeled at 7.58%, and the study traces a steady increase in absolute market value from the low hundreds of millions (USD Million) in 2020 to a forecasted mid-hundreds by 2026 and beyond — culminating in a projected market size of approximately USD 825.3 Million by 2032 under the base case.
Epoxidized Soybean Oil Market
Why this study matters for 2026 decision-makers
-
Timing advantage: Manufacturers, distributors, and polymers formulators face a narrow window in which to translate capacity investments, product innovation, and contracting strategies into sustainable margin improvement. With the sector growing at a mid-single-digit to high-single-digit CAGR, 2026 is the year to move from exploratory pilots to binding commercial commitments.
Epoxidized Soybean Oil Market -
Raw-material-driven exposure: Epoxidized soybean oil production remains deeply linked to soybean oil markets. USDA forecasts and industry signals point to pronounced demand pressure on soybean oil—as an example, USDA projected soybean oil season-average prices for the 2025/26 marketing year in the neighborhood of $0.59 per pound and a record-level soybean crush demand. These inputs materially influence cost curves and require more sophisticated hedging and sourcing strategies than conventional petrochemical plasticizers.
Epoxidized Soybean Oil Market -
Regulatory and trade risk: Trade remedies and import probes can re-route volumes and distort pricing rapidly. Recent antidumping activity targeting ESBO imports is a reminder that supply-side reconfiguration can be abrupt and regionally concentrated; commercial planners must build playbooks that factor potential import restrictions into supply, contract length, and price pass-through decisions.
-
Concentration and competitive posture: The market exhibits a moderate degree of concentration at the top end (the study’s concentration metrics indicate meaningful share accumulation among the largest suppliers). For both incumbents and challengers, understanding competitive intent — capacity moves, certifications, and channel partnerships — is essential to avoid being an operational follower.
Report contents — What you’ll get (practical, deal-ready outputs)
-
Market sizing and trajectory: Annualized historical data (2020–2025) and multi-scenario forecasts (2026–2032) with a transparent methodology. The base case uses a 7.58% CAGR; alternate scenarios stress raw-material shocks, accelerated renewable-fuel demand, and trade disruptions.
-
Go-to-market and product playbooks: Tactical analysis for product positioning (e.g., food-contact and Kosher-certified grades, high-heat-stability blends), channel strategies (direct sale vs. distribution), and margin optimization levers.
-
Supply chain and cost-sensitivity models: Practical frameworks to quantify exposure to soybean oil pricing, processing yields, and logistics. These models are designed to map to commercial KPIs — break-even pricing, minimum order quantities, and contract tenors.
-
Regulatory and trade-risk matrix: A decision-ready assessment of active trade measures, potential escalation scenarios, and prescribed mitigation steps for procurement, pricing, and customer communication.
-
Competitive intelligence dossiers: Executive profiles, capacity footprints, capability maps, and recent strategic moves for the sector’s relevant players. The report integrates primary and secondary diligence and identifies likely strategic plays you should expect from competitors.
-
Transaction and partnership frameworks: M&A target screening criteria, JV structures, and partnership archetypes tailored for companies seeking rapid market entry or downstream integration.
Note: while the report contains detailed region- and application-level tables and routable data views, this introduction intentionally omits granular segment figures to preserve the value of the full dataset and deliverable models.
Competitive landscape — who matters and why
-
Cargill, Incorporated : A vertically integrated agri-player with manufacturing scale and recent capacity modernization. Its investment in facility expansion signals a strategic intent to secure upstream feedstock flows and to compete on reliability and cost-competitiveness. For partners and buyers, Cargill’s scale creates a stable source but also a competitive pricing benchmark for market bids.
-
Valtris Specialty Chemicals : Differentiates through product certification (food-contact, Kosher) and brand-backed ESBO grades. Its marketing of such grades positions Valtris well in regulated and premium segments where additive provenance and certification are commercial prerequisites.
-
Galata Chemicals LLC : An example of a focused technical innovator, bringing enhanced heat-stable ESBO plasticizers to market. Fast-follower product launches like Galata’s indicate that performance differentiation — not only price — is a durable source of value in PVC formulations.
-
CHS Inc. : Vertical integration via crushing and processing translates into a structural cost advantage when soybean oil is the dominant feedstock. CHS’s position illustrates the strategic benefit of upstream ownership in a commodity-driven input market.
-
ADEKA Corporation : Global distribution reach and established additive platforms enable rapid market access for specialty ESBO variants. For buyers in complex, multi-jurisdiction supply chains, ADEKA’s global footprint reduces execution risk for cross-border procurement.
-
Acme‑Hardesty, ChemCeed, Interstate Chemical and similar suppliers: These companies occupy important niches — branded grades, distribution logistics, and technical-grade offerings respectively. Collectively, specialty and channel-focused suppliers add flexibility to procurement networks and are often acquirers’ targets to quickly extend distribution or technical capabilities.
Recent vendor activity underlines market dynamics: product promotions emphasizing renewability and certification, targeted launches of higher-performance ESBO grades, and capacity expansions by integrated players. These moves align with the broader market signals PW Consulting models: demand growth, feedstock sensitivity, and premiumization for certified, high-performance additives.
Strategic implications and recommended moves for 2026
-
Hedge and diversify feedstock exposure: Given the heavy dependence on soybean oil and the volatility introduced by competing demand streams (e.g., biofuels), buyers and producers should implement multi-layered hedging — a mix of financial hedges, forward purchase agreements, and localized sourcing partnerships to smooth cost shocks.
-
Prioritize product certification as a growth lever: Food-contact, Kosher, and other credentials materially expand addressable demand and create margin protection. Where feasible, accelerate certification programs for high-margin formulations.
-
Build trade-risk contingency plans: The ongoing use of trade remedies means companies must stress-test contracts for force majeure, re-route options, and alternative supplier readiness. Short-term tactical measures (stock buffers, cross-border logistics flexibility) combined with medium-term strategic moves (local assembly or tolling) limit downside exposure.
-
Evaluate vertical integration selectively: Upstream integration into crushing or feedstock aggregation offers cost advantages, but it requires capital and operational capacity. Use the report’s scenario models to assess payback under different soybean price regimes and demand outcomes.
-
Invest in technical differentiation: High-heat-stability variants and specialty ESBO blends are less commoditized and command premium positioning. R&D and co-development partnerships with formulation houses can create sustainable competitive advantages.
-
Design M&A and partnership playbooks: With observable concentration among top players, acquisitive strategies (bolt-ons for channel reach, tech buyers for product breadth) can shorten time-to-market for new grades and regions.
How to use this intelligence
-
Scenario workshops: PW Consulting recommends running a two-day executive scenario workshop using the report’s alternate paths (baseline, raw-material shock, accelerated renewable demand) to align procurement, R&D, and commercial teams on a single set of decisions.
-
Commercial scorecards: Translate the report’s sensitivity analyses into pricing scorecards and contract templates so sales teams can react in real time to raw-material fluctuations while preserving target margins.
-
Due-diligence accelerators: Use our competitive dossiers and financial models to compress target screening and valuation tasks during M&A processes, cutting weeks from diligence timelines.
Final note: this article is a strategic “trailer” designed to surface the decision-relevant signals from PW Consulting’s full ESBO study. For clients seeking the granular, actionable tables (detailed regional and application-level demand curves, supplier share models, and drillable cost curves), the full report includes downloadable data packs and interactive models. Those deliverables are where the revenue-by-segment and contract-level implications are mapped into operational plans — the very details we intentionally hold for the full report to preserve client value.
If your 2026 planning cycle includes portfolio optimization, procurement redesign, or M&A in the ESBO value chain, PW Consulting’s full study provides the templates and scenario engines to convert market outlook into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Epoxidized Soybean Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Aluminum Nitride (AlN) Market 2026: Strategic Imperatives for Corporate Decision-Makers
Executive snapshot
As organizations prepare strategic plans for 2026, Aluminum Nitride (AlN) is moving from a niche technical ceramic to a material of strategic consequence across power electronics, microelectronics, and next‑generation optoelectronics. PW Consulting’s latest market model, based on a 2025 base year and a 2026–2032 forecast horizon, shows a steady, mid‑single‑digit expansion trajectory (compound annual growth rate of approximately 5.5%). The total market has expanded meaningfully since 2020 and, under our base case, continues to grow toward an appreciably larger addressable market by the end of the forecast window.
Aluminum Nitride (AIN) Market
Market structure remains concentrated: the top three suppliers control a sizeable portion of global revenue, and the top five further increase that concentration—an indicator that scale, process technology and customer qualification barriers remain high. For executives evaluating investments in 2026, these dynamics make timing, partner selection and regulatory positioning as important as product innovation.
Aluminum Nitride (AIN) Market
Why this matters in 2026: strategic value of AlN intelligence
- Materials-led differentiation: AlN’s unique combination of high thermal conductivity and electrical insulation makes it a preferred substrate and heat‑dissipation solution for power modules, RF devices and certain microelectronic assemblies. Product roadmaps that assume legacy substrates persist risk thermal, reliability and size disadvantages.
- Supply chain and regulatory risk: High‑purity inputs and specialized manufacturing create natural supply constraints. Compounding that are evolving export controls and licensing regimes across key jurisdictions that directly affect cross‑border sourcing and commercial deployment strategies.
- Commercial inflection points: Advances in single‑crystal substrate production and new pilot lines have lowered the lead time and qualification hurdles for some AlN end‑uses. Firms that accelerate qualification cycles can secure early adopter premiums or lock in co‑development partnerships with OEMs.
What our report delivers — practical, decision‑ready outputs
To translate material science into commercial strategy, PW Consulting’s AlN Market study goes beyond descriptive analysis. Clients get pragmatic tools and playbooks designed for 2026 decision cycles, including:
Aluminum Nitride (AIN) Market
- Top‑down market sizing and a seven‑year forecast (2026–2032) with scenario levers for adoption speed, price trajectory and regulatory shock events.
- Demand‑driver analysis tying device architectures (power modules, RF, optoelectronics) to material requirements and adoption roadmaps.
- Price and margin frameworks that model how input volatility and capacity additions affect supplier economics and OEM procurement strategies.
- Supply chain maps and supplier risk matrices that highlight single‑points‑of‑failure, lead‑time curves and near‑term expansion plans.
- A regulatory & trade compliance matrix tailored to export licensing regimes and dual‑use controls that influence route‑to‑market choices.
- Competitive benchmarking, capability heatmaps and an M&A playbook for buyers and strategic investors.
- Actionable go‑to‑market plans and qualification roadmaps for product and application engineers to shorten time‑to‑revenue.
Note: this introduction intentionally omits granular regional and application splits so that procurement teams and strategy leads seeking the full segmentation tables and supplier revenue models can access the complete dataset on our report page.
Competitive landscape: who’s shaping the market and why it matters
The current competitive dynamic blends established technical ceramics manufacturers with specialized single‑crystal innovators. Incumbents with deep ceramic processing expertise have leverage in bulk powders, sintered substrates and machined components. Meanwhile, upstream innovators focusing on single‑crystal AlN are creating new pathways for high‑performance RF and power semiconductors.
- Large ceramic manufacturers continue to compete on formulation control, production scale and downstream value‑added services (e.g., machined components and packaging). These players benefit from broad customer relationships across industrial and electronics OEMs.
- Specialized single‑crystal providers are commercializing larger diameter substrates and pilot production lines, a development that can redefine qualification cycles for power and RF device OEMs.
- Powder and granule suppliers underpin the entire value chain; raw material purity and consistent quality are prime competitive levers.
Recent industry moves underline how competitive advantage is being pursued in 2025–2026. Several suppliers announced pilot or expanded production lines for large‑diameter single‑crystal substrates and launched optimized product variants tailored for power/RF device development. Others updated product literature and application guides to accelerate customer qualification. For firms evaluating partners or acquisition targets in 2026, the difference between ownership of proprietary processing IP versus scale of manufacturing capacity will materially affect post‑deal integration plans and margin upside.
Dynamics and risks to factor into 2026 decision‑making
- Raw‑material constraints and price volatility: High‑purity aluminum and nitrogen feedstocks show periodic volatility tied to supply shocks. Procurement strategies that rely on single suppliers or spot markets will face margin erosion and delivery risk.
- Regulatory and export controls: In several jurisdictions, AlN substrates and associated technologies are subject to licensing for certain end uses, especially where military or sanctioned entities are potential customers. Compliance frameworks must be embedded in commercial agreements and supply‑chain mappings.
- Geopolitical re‑shoring and trade frictions: Elevated US‑China tensions and tighter controls on critical materials necessitate alternative sourcing and contingency manufacturing footprints for firms with global customers.
- Technology displacement risk: While AlN adoption is accelerating in targeted applications, competing substrate technologies and packaging innovations could compress addressable markets in scenarios where cost or integration complexity outweighs performance benefits.
Recommended strategic playbook for 2026
For executives who need to convert market intelligence into board‑level choices this year, we recommend a prioritized set of actions:
- Secure multi‑tier supply commitments: Move from spot purchases to dual‑sourced long‑term agreements with tiered pricing and capacity reservation clauses. Include quality KPIs and contingency allocations tied to capacity expansions.
- Accelerate qualification through co‑development: Establish shared engineering teams with substrate suppliers and OEM customers to shorten device qualification cycles and capture first‑mover adoption incentives.
- Invest selectively in capabilities: Where margin and strategic value align, pursue minority equity stakes or JVs with single‑crystal innovators to secure priority access to new wafer sizes and substrate grades.
- Embed regulatory compliance in commercial strategy: Implement export‑control screening tools and contractual language to manage licensing risk, including clauses for restricted end‑use and destination countries.
- Design for supply flexibility: Re‑architect BOMs and qualification plans to accept multiple substrate grades when feasible; build modular designs that can tolerate material substitution with minimal re‑qualification.
- Use pricing levers wisely: Protect margins via value‑based pricing for differentiated substrate solutions, while retaining a competitive offering for commoditized grades.
- Scenario funding & capex gating: Adopt milestone‑based funding for capacity expansions—link capex tranches to customer qualification and binding offtake agreements to avoid stranded assets.
Scenario planning & watch‑list triggers
We recommend three monitoring triggers tied to adaptive strategies for 2026:
- Supply shock trigger: Sudden raw‑material shortages or export control changes that materially increase lead times—activate strategic stockpiles and close‑in sourcing.
- Demand acceleration trigger: Rapid adoption in a high‑volume end market (e.g., electrified powertrain or a new RF standard)—accelerate capacity and prioritize preferred customers.
- Technology substitution trigger: Breakthroughs in rival materials or packaging approaches—defer major capex and increase R&D pivot funding.
How PW Consulting supports 2026 decisions
PW Consulting brings integrated advisory services combining market models, raw‑material economics, regulatory intelligence and M&A execution. For clients acting in 2026 we offer tailored deliverables:
- Segment‑level revenue tables, price curves and supplier P&L models to run internal investment committees.
- Regulatory checklists and export‑control playbooks mapped to sourcing scenarios.
- Supplier due diligence packs and integration plans for minority investments or acquisitions.
- Customer‑specific qualification roadmaps and cost‑to‑qualify calculators to shorten commercialization timing.
AlN is no longer a laboratory curiosity—its adoption curve and the competitive moves we track make it a boardroom issue for any company competing in thermal‑limited electronics. This preview outlines the key decision vectors you must consider in 2026: supply, standards, strategic partnerships, and regulatory posture. For the full, data‑rich report with complete regional and application segmentation, supplier revenue breakdowns, price models and downloadable Excel workbooks designed to feed your planning systems, access the PW Consulting Aluminum Nitride Market report page.
For detailed analysis of this topic, please visit the official page: Aluminum Nitride (AIN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Real Time Location Systems in Sports: Strategic Briefing for 2026 Decision-Makers
Executive snapshot
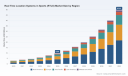
The RTLS (Real Time Location Systems) market serving sports venues, teams and event operators is no longer experimental — it is a fast-growing market shaping competitive advantage across performance, operations and fan engagement. Our base-year analysis (2025) shows the market scaling rapidly from a small base in 2020 through 2025 and, under current technology and adoption trends, accelerating to a materially larger market by 2032. The report uses USD (Million) as its currency and models a compound annual growth rate of 26.4% for the forecast period, with mid-2020s momentum translating into a multiyear expansion through 2032.
Real Time Location Systems in Sports (RTLS) Market
For senior leaders planning budgets and partnerships in 2026, this trajectory implies two things: (1) the window to establish first-mover commercial, operational and data advantages in venue-level and team-level RTLS deployments is now, and (2) technology and commercial choices made this year will substantially shape costs, integration complexity and monetization opportunities over the next 5–7 years.
Real Time Location Systems in Sports (RTLS) Market
What the report delivers — practical, procurement-ready intelligence
-
Market sizing and trend scaffolding: a clear chronology of market evolution from 2020 through 2025 and forward-looking forecasts across the 2026–2032 horizon, enabling scenario-based budgeting and business case modeling.
Real Time Location Systems in Sports (RTLS) Market -
Technology decision framework: a side-by-side evaluation of UWB, Bluetooth AoA, GPS and hybrid approaches focused on accuracy envelopes, latency, infrastructure complexity, interference sensitivity and integration effort with existing analytics stacks.
-
Deployment playbooks: step-by-step blueprints for stadium-level, training-facility and event-scale rollouts, including RF site survey checklists, antenna placement heuristics, tagging strategies for players/equipment and staff, and contingency protocols for multi-technology coexistence.
-
Vendor shortlists and fit-for-purpose mapping: practical profiles and selection criteria tailored to buyer archetypes (elite professional clubs, collegiate athletic departments, venue operators, and large-scale event organizers) to accelerate RFP development and vendor engagement.
-
Commercial models and ROI templates: total cost of ownership models covering capex/opex tradeoffs, lifecycle replacement scheduling, data-hosting options (on-prem vs cloud), and three monetization pathways — enhanced broadcast/data licensing, sponsor activation, and operational savings.
-
Data governance and privacy playbook: compliance checklist and contract clauses oriented to athlete data protection, fan privacy in spectator-tracking scenarios, and anonymization techniques to reconcile analytics needs with regulatory exposures.
-
Pilot and KPI toolkit: predefined success criteria and measurement approaches for short pilots (4–12 weeks) including accuracy acceptance limits, uptime SLAs, analytics-to-action velocity, and business KPIs tied to revenue or cost objectives.
Strategic value for 2026 decisions
-
Accelerate monetization with measured risk: the report equips commercial leads to assess which RTLS-enabled data products (player performance feeds, heatmaps for sponsors, crowd pathing for concessions) can be monetized immediately versus which require longer-term maturation.
-
Budget prioritization with clarity: finance and procurement teams get a scenario matrix to compare incremental spend now (to secure technical advantage and data ownership) against deferred spend with potentially higher integration costs.
-
Vendor selection as strategic choice: in 2026, choosing the right RTLS partner is less about lowest cost and more about ecosystem fit — analytics partnerships, API openness, and roadmap alignment should weigh heavily in RFP evaluation criteria.
-
Operational readiness and risk mitigation: operations teams receive practical guidance to stage RF surveys, run parallel systems during season-critical windows, and reduce event-disruption risk while deriving actionable telemetry for coaching and venue operations.
-
Data & IP strategy: legal and commercial leaders can use our templates to negotiate clear IP and data rights, ensuring teams and venues retain the ability to commercialize anonymized analytics while protecting athlete and patron privacy.
Competitive landscape — how key vendors compare
The RTLS vendor ecosystem for sports spans specialist sports-tech incumbents, wireless-location platform providers and hybrid-systems vendors. Market concentration is meaningful: the top three vendors control a substantial portion of revenue, and the top five firms account for an even larger share — a structure that favors a small set of well-known providers while leaving room for agile specialists and regional integrators.
-
Catapult Sports (Australia): A recognized brand in athlete monitoring and team performance analytics. Catapult’s Vector product family combines GPS and LPS capabilities and is deeply embedded in professional and high-performance amateur sport workflows. Strengths: strong data analytics stack, longstanding relationships with elite clubs and federations, and integrated athlete data workflows. Consideration: platform lock-in and integration complexity with third-party venue systems.
-
Quuppa Oy (Finland): Specialist in high-precision Bluetooth AoA positioning and an ecosystem-builder approach. Recent developments (March 2026) include compatibility announcements and a new “Precision Label” tag class through strategic partnerships, signaling a push to lower per-node costs and broaden enterprise use cases. Strengths: cost-efficient scale potential, partner-friendly integrations. Consideration: AoA performance in high-density RF stadium environments versus UWB.
-
Blueiot (China): A vendor focused on Bluetooth AoA solutions with emphasis on stadium navigation, crowd management and staff coordination. Strengths: regional market access in Asia, competitive pricing, and solutions tailored to venue-scale visitor flows. Consideration: enterprise-grade service levels and integration maturity for elite-sport analytics.
-
Eliko (Finland): UWB specialist supplying high-precision platforms for indoor athlete and equipment tracking. Strengths: sub-meter and centimeter-level accuracy in controlled indoor environments and a focus on performance monitoring. Consideration: UWB infrastructure costs and line-of-sight sensitivity for certain venue architectures.
-
WISER (United States): UWB-focused RTLS provider with proven stadium deployments and operational features for crowd and guide services. Strengths: experience in large venues and operational use-cases beyond pure performance analytics. Consideration: alignment to custom analytics and sports-data product roadmaps.
-
Sewio Networks (Denmark): Multi-technology supplier offering UWB, BLE and GPS options, positioned for venue asset and staff tracking. Strengths: multi-technology flexibility and suitability for venues that need mixed deployments. Consideration: clarity around primary focus (industrial vs sports) when negotiating sports-specific SLAs.
-
Litum (United States): Hybrid provider combining UWB, BLE and LoRaWAN to offer a flexible platform for stadiums and facilities. Strengths: hybrid architectures that can address both high-precision athlete tracking and lower-power, long-range asset monitoring. Consideration: integration complexity and single-vendor accountability across multiple radio stacks.
Recent vendor moves to watch (March 2026)
-
Quuppa announced compatibility between an InPlay NanoBeacon product and its Intelligent Locating System, enabling lower-cost Bluetooth AoA implementations at scale — a development that could shift buyer calculus for large-volume tag deployments in venues and events.
-
Quuppa also introduced a “Precision Label” tag class in collaboration with strategic partners, positioning itself to address enterprise RTLS use cases with a tighter cost-to-accuracy tradeoff.
Actionable roadmap for 2026 — prioritized next steps
-
Q2–Q3 2026: Run a focused pilot aligned to a single, high-value use case (e.g., in-game player telemetry for broadcast enhancement or training-derived injury-risk analytics). Use our KPI toolkit to define success criteria that link technical outcomes to commercial or operational value.
-
Immediately: Commission an RF site survey and vendor interoperability assessment. Even when a single technology looks attractive on paper, real-world RF and structural factors often necessitate hybrid approaches.
-
Within 6–9 months: Negotiate vendor contracts that preserve data ownership and provide phased SLAs tied to accuracy and uptime. Include pilot-to-scale pricing schedules and API-level commitments for third-party analytics integration.
-
By year-end 2026: Consolidate a supplier shortlist based on pilot results, operational fit and commercial terms. Prioritize vendors that demonstrate both technical performance and a clear roadmap for product updates relevant to sports analytics and venue operations.
-
Ongoing: Build internal capabilities for data governance, anonymization and analytics ingestion so that RTLS feeds can be monetized safely and quickly once the technical baseline is proven.
Closing — why this briefing matters
Decisions made in 2026 about RTLS platforms will determine whether an organization secures durable advantages in player performance, operational efficiency and commercial data products. Our full report expands each of the topics summarized here into actionable templates, vendor-scoring matrices and deployment playbooks designed to shorten procurement cycles and reduce rollout risk. Consider this article a strategic trailer: it outlines the stakes, direction and practical next steps, while the report itself contains the granular models, vendor comparisons and proprietary decision tools needed to execute with confidence.
Access to the complete dataset, vendor scorecards and the step-by-step pilot blueprints is available via our report page — designed to support CFOs, CIOs, Head Coaches, Venue Directors and Commercial Leads as they translate RTLS potential into measurable business outcomes in 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Real Time Location Systems in Sports (RTLS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: TCB Bonder Market to Surge at 18.31% CAGR, Reaching USD 679.93M by 2032
By pmarketresearch, 2026-07-23
TCB Bonder Market — 2026 Strategic Outlook: A PW Consulting Preview
As PW Consulting’s lead industry analyst, I present a concise, strategy-focused preview of our new TCB (thermocompression) Bonder Market study. This briefing distills the study’s executive implications for enterprise decision-makers planning 2026 capital, product, and M&A strategies. It demonstrates the analytical depth of our full report while intentionally withholding granular regional and application breakdowns — the precise data tables and vendor scorecards are available in the full report for subscribers and clients.
TCB Bonder Market
Market Trajectory: What the macro numbers tell you
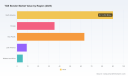
Thermocompression bonder demand has entered a high-growth phase driven by advanced packaging requirements, medical-device miniaturization, and rising adoption in photonics and high-performance compute subsystems. On a market-wide basis, the industry more than doubled in size during the 2020–2025 historical period and reached a clear inflection point in 2025. From this base year, our modelling shows the market expanding at a sustained, high-teens compound annual growth rate (CAGR) over the 2026–2032 forecast window — a rise that translates into roughly threefold market scale by the end of the decade under the baseline scenario.
TCB Bonder Market
Why these headline figures matter for 2026 planning: growth at this magnitude compresses the typical technology adoption curve, shortens payback windows for automation investments, and moves supplier selection from “nice to have” to strategic gatekeeping for manufacturing competitiveness. Capital allocation decisions taken in 2026 will either secure capacity and capabilities for the next product cycle, or risk being priced out or capacity-constrained as demand accelerates.
TCB Bonder Market
Strategic themes that will shape 2026 decisions
-
From throughput to tolerance: Buyers are no longer solely focused on cycle time; sub-micron placement accuracy and repeatable heat-and-pressure profiles are now equally critical for advanced multi-die constructs and hybrid bonding workflows.
-
Regulatory and premium markets: Medical and other regulated end-markets command differentiated system specifications and documentation practices, driving willingness to pay for medical-grade platforms and certified suppliers.
-
Concentration and counterparty risk: The market exhibits meaningful concentration at the top end of the supplier base. That amplifies supply-side bargaining power for market leaders, and raises the premium for qualification programs and long-term service commitments with those vendors.
-
Modularity as optionality: Platforms that permit modular upgrades (automation, vision systems, thermal controls) are valuable for firms balancing near-term costs against long-term capability needs.
Regulatory and medical-device dynamics — operational implications
Medical-device applications represent a strategically important, higher-margin segment for TCB equipment. These customers require stringent documentation, lot traceability, and facility-level qualifications aligned with Class II/III device manufacturing. For suppliers, that translates into extended qualification cycles, premium pricing, and long-term service contracts. For buyers, it means procurement timelines must factor in regulatory lead times and validated change-control processes — delaying a decision by a few quarters can impose months of lost time for product launches in regulated portfolios.
Competitive landscape: what to watch in supplier selection
The competitive map is anchored by a set of specialized equipment vendors delivering differentiated value propositions. Our report profiles each vendor not merely by headline claims but by tested performance metrics, field yield evidence, and aftermarket responsiveness. High-level competitive themes include: ultra-fine pitch thermomechanical control, sub-micron placement and high-throughput die attach systems, large-panel support for new form factors, and niche offerings tailored to medical/photonic device makers.
-
Kulicke & Soffa Industries, Inc. (Willow Grove, PA, USA) — APAMA™ PLUS series and advanced thermo-compression platforms focusing on ultra-fine pitch interconnects with precise heat-and-pressure control for high-density assembly. ( https://www.kns.com/)
-
ASMPT Amicra (Singapore) — NOVA Pro die attach systems emphasizing die placement accuracy and short cycle times for high-volume TCB production. ( https://www.asmpt.com/)
-
BE Semiconductor Industries N.V. (BESI) (Duiven, Netherlands) — Thermocompression systems proven in volume for advanced flip chip and die bonding (CoWoS, HBM) deployments. ( https://www.besi.com/)
-
Toray Engineering Co., Ltd. (Japan) — Flip chip bonders supporting TCB, DAF, and hybrid bonding across wafer and large-panel formats up to substantial panel sizes. ( https://www.toray-eng.com/)
-
Palomar Technologies (Carlsbad, CA, USA) — 3880-II Die Bonder series applying thermocompression processes for ultra-precise applications in medical devices and photonics. ( https://www.palomartechnologies.com/)
These vendors illustrate distinct go-to-market approaches: platform breadth and field volume, high-precision niche offerings, and large-panel capability. In the full study we map supplier strengths against key procurement criteria (precision, throughput, regulatory readiness, upgrade path, total cost of ownership), enabling an apples-to-apples shortlist for different buyer archetypes.
Market structure and implications for partnerships and M&A
Market concentration indicators show the top-tier incumbents control a majority share of the addressable market. That dynamic creates both barriers and opportunities: suppliers seeking to scale may find M&A or partnership the fastest route to augment capability stacks, while buyers may seek bundled procurement deals to secure preferential lead times and pricing. For private equity and strategic acquirers, the TCB sector presents consolidation potential — particularly in automation, in-line inspection, and aftermarket services where scale drives margin expansion.
What the full PW Consulting report delivers (high-level)
Our full TCB Bonder Market study goes beyond headline forecasts to provide hands-on tools for decision-making. Highlights include:
-
Detailed market sizing and scenario-based financial models (baseline, upside, downside) covering 2026–2032, with sensitivity levers for cycle time, yield improvement, and pricing pressure.
-
Supplier benchmarking matrices and vendor scorecards that evaluate performance across technical, commercial, and service dimensions — calibrated for medical, HVM consumer, and specialty photonics use cases.
-
Purchase-and-qualification playbooks: step-by-step templates for RFQs, factory acceptance testing (FAT) criteria, and change-control protocols for regulated environments.
-
Capital allocation frameworks that translate market growth and lead-time risk into CAPEX phasing options and ROI timeframes suitable for CFO-level decision making.
-
Operational ramp plans including spare-parts forecasting, yield-debugging sequences, and workforce skilling pathways to minimize time-to-volume.
Note: the granular regional and application splits, as well as sensitive vendor performance scores, are intentionally omitted from this preview. The full datasets and appendices are available to subscribers and advisory clients, and are essential for transaction-level or plant-level decisions.
Actionable recommendations for 2026 (prioritized)
-
Re-evaluate CAPEX timing now: Given the high growth trajectory, organizations should model a near-term tranche of procurement to secure capacity while preserving optionality for subsequent upgrades.
-
Lock in regulatory-ready vendors where medical exposure exists: If your roadmap includes regulated device launches, prioritize suppliers with documented medical-device qualifications and material traceability workflows.
-
Negotiate service and spare-part commitments up-front: Service availability and spares can become strategic chokepoints in periods of demand growth; multi-year SLAs and consignment strategies mitigate risk.
-
Pilot hybrid/large-panel workflows early: Conduct focused pilots with vendors that support hybrid bonding and larger panel sizes to validate process windows before full-scale investment.
-
Design for modularity: Favor platforms that enable staged automation and feature upgrades to spread CAPEX and align with evolving product roadmaps.
Signals to monitor through 2026
-
Supplier lead-time movements and backorder levels — early indicators of capacity tightness.
-
Field yield trends for early hybrid bonding deployments — yielding improvements materially affect unit economics.
-
Regulatory guidance updates for medical manufacturing — any tightening will increase qualification cost and schedule risk.
-
Announcements of strategic partnerships or M&A among equipment suppliers — these can rapidly shift bargaining dynamics.
Each of the above signals is incorporated into our scenario models and vendor risk matrices in the full report; these tools translate observed signals into quantified impacts on margin, time-to-volume, and product launch schedules.
Closing — why access the full study
2026 is a pivot year. The macro growth profile, concentrated supplier base, and the rising regulatory and technical demands together create both outsized opportunity and asymmetric risk. PW Consulting’s TCB Bonder Market study is designed to convert market-level forecasts into operational and financial decisions: from supplier selection and CAPEX phasing to regulatory qualification strategy and M&A screening.
If your 2026 plan includes investments in thermocompression bonding capability — whether to support advanced packaging, medical devices, or photonics — the full report supplies the granular segmentation, vendor scorecards, and scenario-playbook required to act with conviction. Contact PW Consulting or visit our TCB Bonder Market page to access the complete analysis, datasets, and client-only decision tools.
For detailed analysis of this topic, please visit the official page: TCB Bonder Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Underlayment Market to Reach USD 1,935.6M in 2025 at 4.8% CAGR
By pmarketresearch, 2026-07-23
Flooring Underlayment Market — Strategic Outlook for 2026 Decision-Makers
Executive overview
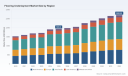
As PW Consulting’s senior industry analyst, I present a focused strategic primer to orient executive teams, corporate development groups, and portfolio managers preparing for a critical planning window in 2026. Our new market study uses 2025 as the base year and traces historical performance from 2020–2025, then projects out across 2026–2032. The global flooring underlayment market—measured in USD Million—has expanded steadily since 2020 and, based on our modeling, is expected to continue growing at a compound annual growth rate (CAGR) of approximately 4.8% through 2032.
Flooring Underlayment Market
This briefing highlights why this research matters now, where structural growth and risk converge, and how the report’s practical modules equip leaders to make informed capital, product, and commercial decisions in 2026. In keeping with our “trailer” approach, we signal analytical depth while reserving the full granular tables and interactive models for the full report.
Flooring Underlayment Market
Why this research matters for 2026 planning
- Reliable macro trajectory: After pandemic-era dislocations, the underlayment market regained momentum through 2023–2025. By the 2026 planning cycle, companies need clarity on sustainable demand drivers versus transient surges. Our base-year benchmarking and 2026–2032 forecast provide that macro view.
- Cost and input risk are front and center: Polyethylene foam—the primary feedstock for the largest underlayment type—links industry margins directly to crude oil and refinery cycles. Procurement, hedging, and product re-specification are strategic levers that will shape 2026 P&Ls.
- Warranty and standards shape product design: Resilient flooring manufacturers enforce strict installation tolerances (e.g., maximum cumulative underlayment thickness constraints). Product innovation must balance acoustic/moisture performance with dimensional limits to avoid voided warranties—an operational detail with immediate commercial implications.
- Margin pressure from logistics and trade: Tariff volatility and transport surcharges for imported foams, rubber, and cork have introduced a new layer of cost unpredictability. Executives must plan sourcing and regional footprint adjustments in response.
What our full report delivers (practical, actionable modules)
The study is designed as an operating manual for decision-makers, not just a descriptive market summary. Key actionable elements include:
Flooring Underlayment Market
- Forward-looking demand scenarios (base, upside, downside) for 2026–2032 with sensitivity to energy price shocks, trade disruptions, and durable-goods substitution trends.
- Detailed cost-stack modeling that isolates raw material, conversion, freight, and tariff impacts—enabling rapid re-pricing and margin simulation for alternative formulations.
- Go-to-market playbooks for OEMs, private-label manufacturers, and specialty suppliers—covering channel priorities, specification strategies, and installer economics.
- M&A and partnership scorecards: vintage multiples, strategic fit matrices, and integration risk checklists tailored to underlayment assets and adjacent capabilities (acoustics, moisture mitigation, recycled-material processing).
- Operational playbooks for capacity planning and CAPEX timing—anchored to supply normalization scenarios and the sector’s evolving recycling ecosystem.
- Regulatory and warranty compliance matrix with design thresholds that protect OEM warranties while maximizing product differentiation.
Competitive landscape — who matters and why
The market structure displays a moderate concentration: the top three players account for a meaningful share of market capacity, with the top five representing a larger consolidated footprint. This balance creates opportunities for both scale-driven incumbents and technically nimble challengers.
- MP Global Products — Known for acoustic fiber underlayments (QuietWalk brand) and an early mover in integrating recycled content. Their value proposition emphasizes acoustic performance, moisture protection, and sustainability—attributes resonating with both renovation and multi-family residential demand.
- Leggett & Platt Flooring Products — The largest U.S. player in carpet cushion and hard-surface underlayment. Their scale and formulation breadth (foam, rubber, others) give them cost and channel advantages, particularly in private-label supply to major flooring brands.
- Pak-Lite, Inc. — A dominant private-label specialist for floating floors, with deep capabilities in bespoke performance ratings (IIC/STC/Delta). Their bespoke focus makes them a preferred supplier for retailers and OEMs seeking specification control without heavy capex.
- Wise Flooring Products LLC — A U.S.-made, recyclable-product differentiator targeting sustainability-conscious channels. They illustrate how “Made-in” positioning and circular-material messaging can command premium placements in specified projects.
- FloorMuffler — Offers a blended portfolio (XLPP foam, recycled-fiber, rubber) with product lines addressing acoustic and moisture concerns for vinyl, laminate, and hardwood—an example of product-line breadth supporting diverse retail and installer channels.
- Cyg Tefa and other Asia-based suppliers — Represent high-density IXPE/XPE foam capabilities, cost-competitive manufacturing, and strong LVP/laminate alignment. Their trade exposure amplifies sensitivity to tariffs and freight congestion trends.
- Chinese and regional manufacturers — Several professional manufacturers expand capacity and product types to serve global OEMs and private-label partners; competitive dynamics will hinge on quality certification, logistics economics, and the ability to meet warranty-sensitive specs.
Recent industry moves underscore strategic priorities for 2026:
- New product introductions (e.g., premium acoustic solutions with enhanced stability and moisture protection) signal a push toward higher-value underlayments that address end-user comfort and lifecycle performance.
- Promotions highlighting recycled materials reflect growing buyer willingness to trade cost for sustainability credentials—especially in B2B specification channels and commercial projects.
- Regional product showcases and trade participation indicate continued demand growth in emerging LVP and laminate markets, but also point to distribution gaps that incumbents can exploit.
Market dynamics that will drive boardroom moves in 2026
- Raw material volatility: Polyethylene foam pricing remains the single largest input risk; it is correlated to crude oil cycles and refinery capacity. Companies should stress-test margins against oil-price scenarios and consider strategic inventory, alternative feedstocks, or long-term purchasing arrangements.
- Regulatory and technical constraints: Flooring system warranties impose practical limits (e.g., cumulative thickness tolerances). Product development must prioritize thin-profile high-performance solutions to avoid disqualification from major floorcovering warranties.
- Transport and tariff pressure: Escalating import surcharges for foam, rubber, and cork mean regional sourcing and nearshoring strategies can materially affect landed costs and service levels.
- Recycling and supply normalization: The post-2023 stabilization of recycled rubber and natural cork supplies has enabled selective capacity investments. Suppliers that lock-in circular-material feedstocks gain both ESG credentials and a buffer against petrochemical swings.
- Installation economics: Labor and moisture mitigation requirements alter the total installed cost. Manufacturers that simplify installation or partner with installer networks can win specification share even at modest price premiums.
Strategic moves we recommend for 2026
- Prioritize product sets that combine thin profiles, acoustic performance, and moisture mitigation—this triad addresses warranty constraints while matching buyer preferences in residential and commercial refurbishments.
- Adopt a mixed sourcing model: combine regional manufacturing for warranty-sensitive, high-service customers with offshore cost advantages for commoditized SKUs. Use tariff-pass-through frameworks in contracts to reduce margin shock.
- Invest selectively in recycled-material lines where procurement can secure feedstock at scale; these products support differentiated pricing and improve resilience against petrochemical swings.
- Build installer-aligned value propositions—training, bundled moisture systems, and labor-saving product formats—to lower total installed cost and accelerate spec acceptance among flooring contractors.
- Use our scenario-based valuation templates to evaluate M&A targets: prioritize manufacturing assets with quality certifications and incumbent customer lists rather than pure capacity plays vulnerable to margin compression.
How to use the full PW Consulting study
The complete report provides the raw and modeled data—annual market totals, supply-demand balances, cost curves, and heat-mapped opportunity zones—that underpin the recommendations summarized above. If you are preparing 2026 budgets, a product roadmap, or evaluating acquisition targets, the study equips you to:
- Quickly quantify the revenue and margin impact of alternative sourcing and product strategies under multiple macro scenarios.
- Compare competitive positioning across formulation, channel, and geographic axes without re-building industry models in-house.
- Prioritize R&D and CAPEX to align with warranty-driven product specs and installer economics that will determine share shifts through 2028–2030.
Closing — the strategic moment
The flooring underlayment market has entered a phase where product-level engineering, supply-chain agility, and installer economics will determine winners more than scale alone. With a 2025 base and an explicit 2026–2032 forecast horizon at ~4.8% CAGR, executives have an opportunity in 2026 to lock in advantaged positions—whether through targeted product innovation, tactical nearshoring, or acquisition of specification-focused assets.
PW Consulting’s full study contains the data tables, regional demand matrices, and playbooks required to convert the strategic imperatives outlined here into executable plans. For access to the complete dataset, segment breakdowns, and downloadable modeling tools, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Flooring Underlayment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Plating Equipment Market to Hit USD 279.35M by 2032 at 6.5% CAGR
By pmarketresearch, 2026-07-23
Plating Equipment Market — Strategic Preview for 2026 Decision‑Making
As PW Consulting’s senior strategy team, we present a concise, decision‑focused preview of our full Plating Equipment Market study. This brief is designed as a strategic trailer: it delivers rigorous, data‑grounded context and clear implications for 2026 capital, product and supply‑chain choices — while intentionally withholding granular segment-level tables and region/application breakdowns to preserve the commercial value of the full report.
Plating Equipment Market
Market snapshot: the macro trajectory
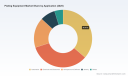
The plating equipment market has demonstrated steady expansion through the 2020–2025 historical window and is projected to continue this momentum across our 2026–2032 forecast horizon. On a consolidated basis (USD, revenue unit: Million), the market reached a notable scale in the base year (2025) and expands at a compound annual growth rate of roughly 6.5% across the forecast period. By 2032 the market is materially larger than in 2025, reflecting a combination of demand tailwinds from electronics, automotive electrification, and industrial refurbishment, together with technology replacement cycles and regulatory-driven retrofit spending.
Plating Equipment Market
Two structural metrics matter for strategy formation: (1) market concentration is moderate — the top three players account for under one third of the market while the top five approach four tenths — indicating meaningful room for regional specialists, technology‑led entrants and M&A to reshape shares; and (2) growth is broad‑based but unevenly driven by distinct end‑markets and technology adoption curves (which we analyze in the full study).
Plating Equipment Market
Near‑term drivers and 2026 strategic imperatives
-
CapEx timing and phasing: For executive teams planning mid‑cycle capacity investments in 2026, the confluence of steady demand growth and accelerating regulatory compliance costs argues for staged capital deployment. Targeted upgrades that prioritize wastewater treatment and closed‑loop chemistries reduce long‑term OPEX and limit regulatory exposure — especially where effluent rules have recently tightened.
-
Supply‑chain and raw material risk management: Elevated copper and specialty metal prices, combined with evolving export controls on strategic inputs, are compressing margins and increasing lead‑time volatility for plating line components. Buyers should build dual‑sourcing strategies, consider nearshoring critical assemblies, and lock in strategic hedges on key commodities to reduce price‑sensitivity in 2026 budgets.
-
Automation to mitigate labor constraints: Labor shortages and rising labor costs in finishing operations are driving a rapid shift toward robotic integration, modular automated lines and remote process control. Investment in automation not only reduces operating costs but also improves process repeatability and environmental compliance — a clear priority for high‑mix, low‑volume customers such as aerospace and luxury jewelry manufacturers.
-
Regulatory and sustainability compliance as product enablers: New effluent and emissions standards are creating both a compliance burden and a commercial opportunity. Vendors who can package low‑waste chemistries, efficient wastewater management and compliance service offerings into turnkey solutions will win faster adoption and command premium positioning.
-
Technology differentiation and aftermarket services: Incremental equipment performance improvements — e.g., advanced agitation systems, process sensors, and selective/brush plating innovations — are increasingly monetized through service contracts, spare parts and consumable supply agreements. Companies that align equipment roadmaps with long‑duration service revenue models will enhance lifetime value.
Competitive landscape — patterns and strategic postures
The competitive field features established chemical/equipment integrators, specialist equipment OEMs and a network of regional system integrators. Key players profiled in our research illustrate three dominant archetypes:
-
Integrated chemistry + equipment leaders (platform plays): Firms that combine plating chemistries with turnkey equipment and process know‑how are positioned to capture higher margins through system solutions and recurring chemical supply. These incumbents leverage R&D in low‑waste chemistries and cross‑industry packaging to penetrate adjacent applications.
-
Specialist OEMs focused on selective & on‑site systems: Companies that dominate brush and selective plating systems serve aftermarket repair and niche industrial use cases. Their strength lies in portability, responsiveness and application know‑how — making them attractive partners for MRO networks and service‑led business models.
-
Turnkey integrators and automation vendors: Providers specializing in automated lines, conveyors and tailored finishing suites win in high‑volume, high‑automation customer segments. Their competitive advantage is delivering predictable throughput, regulatory compliance and integration with MES/Industry 4.0 stacks.
Recent vendor activity points to how competition will unfold in 2026. Suppliers are emphasizing sustainable chemistries and packaging at trade events, and the market is witnessing product innovations (e.g., new barrel geometries and modular line components) aimed at improving yield and reducing waste. These moves indicate an industry pivot where new product introductions are as much about environmental performance and serviceability as about nominal throughput gains.
What the full PW Consulting report delivers (practical, operational content)
Our comprehensive study is organized to serve decision‑makers tasked with investment approvals, procurement strategy and business development. The deliverables include:
- Macro sizing and detailed forecasts (historical 2020–2025, baseline 2025, and 2026–2032 scenarios) with sensitivity analysis under alternative demand and commodity price shocks.
- Scenario planning templates for CapEx phasing and ROI under regulatory tightening and raw material inflation assumptions.
- Technology roadmaps and adoption curves, showing where automation, selective plating and low‑waste chemistries intersect with key end markets.
- Go‑to‑market playbooks for OEMs and systems integrators — including pricing strategies, bundling approaches for equipment + chemistry + service and recommended channel models.
- M&A and partnership decision frameworks, with valuation multipliers, integration risk checklists and target screening criteria tailored to both regional consolidators and capability buyers.
- Procurement and supplier resilience playbooks: dual‑sourcing templates, vendor scorecards and inventory/consumption models to mitigate commodity exposure.
- Compliance checklists and implementation roadmaps for wastewater and emissions management aligned to new regulatory baselines.
How leading companies are positioning (high‑level profiles)
-
Atotech (Berlin): A platform player integrating plating chemistries with turnkey equipment; active in advanced PCB/packaging and sustainable surface finishing. Recent trade show activity underscores their emphasis on integrated solutions for electronics and automotive supply chains.
-
Technic Inc. (Cranston, RI): Known for specialty chemistry and brush systems; strong in selective electroplating and industrial decorative applications. Their product breadth supports both in‑line and repair‑oriented use cases.
-
SIFCO ASC (Cleveland, OH): Specialist in on‑site brush plating and repair systems, serving aerospace and heavy industry segments where field repair capability is mission‑critical.
-
KOCH Finishing Systems (Chicago): A turnkey automation and surface finishing provider; recent product introductions highlight innovations in barrel geometries and process performance.
-
Becker Industries, Allied Plating Supplies, A Brite Company, IPT LLC: These vendors represent the ecosystem of regional suppliers, chemical and kit providers, and line integrators that feed OEMs and end users. Their proximity to customers and responsive service models are distinguishing assets.
Industry noise and systemic risks to factor into 2026 planning
- Regulatory shifts: Recent effluent limitation updates require capital and process changes for many operators — factor compliance CAPEX into 2026 budgets.
- Raw material pressure: Record highs in key anode and specialty metal prices have compressed margins; commodity hedges and supplier partnerships are essential risk mitigants.
- Geopolitical supply constraints: Export controls and trade measures affecting critical components and rare earths can create sudden sourcing constraints — scenario‑based continuity plans are advised.
- Labor and automation dynamic: Persistent labor shortages are accelerating the ROI case for automation investments that would previously have been deferred.
How to use this preview to make better decisions in 2026
- Executive teams should convert the macro growth profile and concentration metrics into a prioritized set of initiatives: immediate compliance upgrades, medium‑term automation projects, and longer‑term product/market plays.
- Procurement must adopt a two‑track approach: lock in strategic supply agreements for critical inputs now, while qualifying secondary suppliers to reduce single‑source risk.
- R&D and product leaders should align roadmaps to sustainability and service models — packaging low‑waste chemistries with remote monitoring and service contracts will be a competitive differentiator.
- Corporate development should use the moderate concentration landscape to pursue bolt‑on acquisitions that add regional market access or unique technical capabilities, rather than large transformative buys.
Closing — where this preview fits and next steps
This preview synthesizes the high‑level market trajectory, competitive archetypes and decision‑critical implications for 2026. It is intentionally focused on strategic signals rather than the granular segment tables and regional/application splits that commercial teams rely on for execution. If you are preparing 2026 budgets, vendor evaluations or an M&A shortlist, the full PW Consulting Plating Equipment Market report provides the granular segmentation, downloadable datasheets, company profiles, scenario models and implementation templates you will need.
Contact PW Consulting to access the complete study and the companion decision‑support toolkit that operationalizes these insights into executable 90‑ to 180‑day plans.
For detailed analysis of this topic, please visit the official page: Plating Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Guitar Amplifier Market to Reach USD 182.7M by 2032 at 2.11% CAGR
By pmarketresearch, 2026-07-23
Guitar Amplifier Market 2026 Strategic Preview — Actionable Intelligence for Corporate Leaders
As PW Consulting’s Senior Strategy Advisor and Head of Industry Analysis, I present a focused, executive-level preview of our comprehensive Guitar Amplifier Market study. Built on a 2025 base year and projecting through 2032, the market model shows a steady, moderate expansion from roughly USD 142.0 Million in 2025 to an expected USD 182.7 Million by 2032, representing a compound annual growth rate of approximately 2.11%. This preview highlights the strategic implications of that trajectory for product, supply chain, channel, and M&A decision-making in 2026 — while preserving the granular splits and proprietary scenario outputs for readers of the full report.
Guitar Amplifier Market
Why this research matters for 2026 corporate decisions
-
Strategy alignment: The market is growing, but not explosively. Companies that assume continued, easy expansion risk misallocating R&D and sales capital. Our forecast nuances where investment will yield disproportionate returns — from premium and hybrid product niches to service and aftermarket revenue streams.
Guitar Amplifier Market -
Supply chain & commodities risk: Recent component inflation and extreme lead times create asymmetric downside for manufacturers without sourcing redundancy. Tactical sourcing, inventory posture, and alternative component strategies are now competitive differentiators, not just operational necessities.
Guitar Amplifier Market -
Regulatory and trade shocks: Newly enacted tariffs and surtaxes in North American and European markets materially alter landed costs for boutique and imported product lines. Understanding the interplay of duties and product mix is essential to pricing and go-to-market choices in 2026.
-
Consolidation dynamics: Market concentration is notable but not overwhelming. The top few players account for a majority share, which creates both competitive headwinds for independents and M&A opportunities for focused acquirers seeking scale in distribution, IP, or component supply.
Near-term dynamics shaping the market
-
Component inflation and lead-time constraints — Transformative for strategy: Transformer prices (power and output) have increased sharply, and high-voltage models now face multi-year lead times. These supply-side shocks are forcing manufacturers to redesign product BOMs, re-evaluate vertical integration, and consider strategic inventory or long-term offtake agreements.
-
Tariffs and localization calculus — Reassess origin strategies: Recent tariff actions and surtaxes impacting imports from neighboring trade partners and some EU duties on amplifier tubes have made origin-of-manufacture choices far more consequential. Companies must weigh near-term cost increases against long-term brand positioning and access to boutique talent pools.
-
Technology convergence — Tube, modeling, hybrid: The market continues to bifurcate between heritage tube-based products, digitally modeled platforms, and hybrid architectures. Each segment presents distinct margin profiles, service requirements, and channel behaviors; winners will align product roadmaps to a clear customer segmentation strategy.
-
Channel and end-user shifts — Commercial and home studios: Adoption patterns in commercial venues versus household/home-studio settings are diverging in use case and willingness-to-pay. Channel strategies must be calibrated accordingly, from pro-audio dealer partnerships to direct-to-consumer digital experiences and subscription-based software/effects ecosystems.
Competitive landscape — what matters in 2026
The market exhibits a mixture of legacy OEMs with strong brand equity, specialized boutique builders, and technology-led entrants. The top-tier concentration suggests meaningful competitive advantages for established names, yet the boutique segment continues to be a hotbed for innovation and margin expansion.
-
Fender Musical Instruments Corporation (Scottsdale, AZ) — Leverages a deep heritage in tube and modeling products. Product cadence of anniversary and limited-edition amplifiers keeps brand premiumization active. Expect continued focus on flagship lines and strategic licensing/partnering to reach adjacent segments.
-
Gibson Brands, Inc. (Nashville, TN) — Historically important in amp production; recent relaunch activity signals intent to re-enter more aggressively. This could reset competitive benchmarks for bundled instrument-plus-amp offerings and cross-sell strategies with legacy guitar lines.
-
Marshall Amplification (London, UK) — Iconic for high-gain tube heritage. Their strategic advantage lies in cultural relevance and artist endorsements. Expect continued focus on stage-grade hardware and premiumized limited runs.
-
PRS Guitars (Stevensville, MD) — Expanding combo amp offerings, including artist-signature products. Their route to market emphasizes integrated instrument/amp experiences and SE-series accessibility.
-
Friedman Amplification (Los Angeles, CA) — Boutique, high-margin tube and hybrid players. Innovation such as IR-load and compact high-fidelity designs demonstrates how boutique engineering can be packaged for broader adoption.
-
BOSS Corporation (Kobe, Japan) — Strong positioning in modeling and compact digital amps. Their product strategies are centered on connectivity, effects integration, and price-competitive modeling platforms targeting both prosumers and professionals.
-
Orange Amplification (London, UK) — British voicing and solid-state/tube mixes remain distinctive. Their brand and tonal signature drive global niche demand.
-
Peavey Electronics Corporation (Meridian, MS) — Notable for professional-grade products and strategic production decisions in Asia Pacific to optimize cost and scale.
-
Benson Amps (Portland, OR) — Hand-wired, artisanal tube amplifiers that capture premium niches and artist partnerships.
-
Hammond Manufacturing (Guelph, ON) — A critical component supplier producing replacement and OEM transformers; supply constraints and price moves in this segment reverberate across the industry.
Recent public developments reflect these strategic themes: high-profile product announcements from legacy OEMs and boutique innovators, ongoing product feature races (e.g., IR-load, Bluetooth/effects integration), and a supply-side environment punctuated by tariff actions and component price inflation.
What the full report delivers — practical, transaction-ready content
-
Robust market model: historical 2020–2025 base, detailed 2026–2032 forecasts, and scenario variants that isolate the impact of tariffs, transformer price inflation, and supply chain disruption on realized revenues and margins.
-
Go-to-market playbooks: differentiating approaches for OEMs, boutique builders, and digital-first entrants, including channel maps, pricing elasticity tests, and dealer incentive structures.
-
Component & supplier risk matrix: vendor concentration, lead-time stress tests, and mitigation strategies including dual-sourcing, vertical integration ROI models, and contract negotiation templates.
-
Regulatory & trade impact analysis: country-level duty scenarios and effective landed-cost modeling to support sourcing and transfer-pricing decisions.
-
Competitive benchmarking: SWOTs, product-roadmap implications, and M&A target heatmaps segmented by strategic rationale (scale, tech, channel, supply).
-
Financial playbooks: product-level P&L templates, margin-improvement levers, and investor-ready slices for buy-side diligence.
Note: this preview intentionally omits the granular regional, type, and application-level shares and detailed numeric splits that underpin our recommendations. Those segment-level models and downloadable data tables are included in the full report and are essential for executing precise pricing, sourcing, and M&A actions.
How to use these insights — 90-day, 12-month, and 3-year priorities
-
90-day play: Conduct a rapid supplier stress test and landed-cost re-run incorporating current tariff scenarios and updated transformer lead times. Identify single points of failure and prioritize near-term hedges or inventory buys for critical components.
-
12-month play: Refresh product roadmaps to reflect a bifurcated market — invest selectively in differentiated premium offerings and modular digital platforms that enable recurring revenue (software/effects, IR packs). Re-negotiate distribution terms where needed to protect margin.
-
3-year play: Consider strategic M&A to shore up component supply, consolidate regional distribution, or acquire IP in digital modeling. Evaluate deeper vertical integration where component scarcity materially threatens go-to-market execution.
Concluding guidance
For executives deciding where to allocate scarce 2026 investment dollars, the choice is between defensive moves to protect core margin and offensive bets that capture premium pockets of growth. The overall market provides a stable growth backdrop, but the real opportunities — and risks — are concentrated in product architecture decisions, supplier relationships, and tariff-sensitive sourcing strategies. Our full report provides the granular segment data, scenario outputs, and transaction-ready templates required to turn these strategic themes into executable plans.
Access the complete study to view the full segmentation, regional and application-level models, and the proprietary Excel workbooks that power our recommendations. PW Consulting stands ready to translate these findings into a tailored strategic roadmap or a readiness audit for your supply chain, product portfolio, or M&A pipeline.
For detailed analysis of this topic, please visit the official page: Guitar Amplifier Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Point-of-Care Testing (POCT) Market — Strategic Outlook for 2026
As healthcare delivery continues its decade-long shift toward decentralization, the Point-of-Care Testing (POCT) market stands out as both a growth engine and a strategic battleground for 2026. PW Consulting’s latest market study (base year 2025; forecast 2026–2032) synthesizes market-sizing, competitive positioning, regulatory dynamics, and actionable commercial playbooks designed to inform capital allocation, product roadmaps, and M&A decisions in the coming 12–18 months.
Point-of-Care Testing (POCT) Market
Why this study matters for 2026
- It translates a fast-evolving industry into clear choices: where to invest, where to partner, and where to cede ground.
- It converts macro momentum — a market that recovered from pandemic volatility to reach a substantially larger base by 2025 and is projected to grow at an 8.5% CAGR through 2032 — into tactical steps you can execute in 2026.
- It aligns commercial, regulatory and manufacturing priorities around realistic scenarios: steady adoption of decentralized diagnostics, regulatory tightening, and platform-versus-consumable economics that will determine sustainable margin pools.
- It provides executable frameworks (M&A scorecards, launch readiness, reimbursement playbooks) rather than abstract forecasts, enabling immediate use in board- and investor-level deliberations.
High-level trajectory and inflection points
The POCT market experienced notable volatility in the early 2020s, driven by episodic infectious-disease demand and supply-chain disruption. After an initial dip and recalibration, the industry expanded through 2023–2025, establishing a stronger baseline entering 2026. Our bottom-up synthesis shows an accelerating adoption curve across clinical settings, home care and acute-care triage that supports a sustained mid-single-digit to high-single-digit compound annual growth rate through the 2026–2032 forecast window.
Point-of-Care Testing (POCT) Market
Two structural inflection points shape the near-term landscape:
Point-of-Care Testing (POCT) Market
- Regulatory tightening and standardization: With the full effect of CLIA regulatory updates (implemented in early 2025), proficiency testing and defined performance bands for certain analytes have raised the bar for market entry and post-market surveillance.
- Platform economics and consumables monetization: Winners will be those who can pair rugged, reliable platforms with high-margin recurring reagents and digital services that lock in clinical workflows.
Competitive landscape — platforms, portfolios, and posture
The POCT arena is concentrated but dynamic. The top-tier vendors command meaningful scale, reflected in a moderately concentrated market (our concentration metrics show a clear leading group). These incumbents are differentiated along several axes: breadth of test menus, accuracy vs. speed trade-offs, regulatory clearances (including CLIA waivers), channel reach, and installed-base service economics.
- Abbott Laboratories — Known for rapid, high-frequency analyzers and molecular platforms that target cardiac, infectious and metabolic markers. Their strategy emphasizes integrated point-of-care workflows and strong commercial channels.
- F. Hoffmann‑La Roche Ltd — Focused on rapid molecular panels enabling multi-target diagnostics at the point of care. Recent regulatory wins have strengthened their position in ambulatory and clinic settings.
- Siemens Healthineers — Competes with extensive POCT solutions for blood gas, cardiac and routine testing; their emphasis is on interoperability with hospital information systems and throughput for acute care environments.
- Danaher Corporation — Combines molecular platforms and immunoassay capability via established brands; the company’s playbook centers on test development agility and global service networks.
- QuidelOrtho — Rapid immunoassay and lateral flow expertise, with an acquisitive posture to bring complementary POCT systems to market quickly.
- Becton, Dickinson and Company (BD) — Positioning across antigen and molecular rapid tests, with an increasing focus on regulatory transitions from emergency authorizations to permanent clearances.
- bioMérieux — Strength in rapid molecular diagnostics and automated rapid systems that serve both hospital and decentralized sites.
- Thermo Fisher Scientific — A growing presence in clinical molecular POCT, leveraging a broad diagnostics portfolio and distribution reach.
Recent vendor activity underscores dynamic competitive moves: leading manufacturers secured new regulatory clearances and CLIA approvals in 2025, another key player moved from EUA-era products to permanent market authorizations mid‑year, and strategic acquisitions are being used to accelerate capability gaps. These events are shifting product mix, channel power and clinical adoption curves.
Regulatory and product dynamics to watch in 2026
- CLIA updates that took effect in 2025 impose stricter proficiency testing and defined performance bands for several analytes — companies must demonstrate routine compliance and robust training/QA programs.
- Transitioning tests from emergency pathways to full clearances has become a commercial imperative for scale; expect sustained submission activity and a renewed focus on formal clinical validation.
- Novel rapid assays for respiratory pathogens and multiplexed panels have entered the market; these expand use cases but also raise clinical‑utility questions that payers will scrutinize.
Strategic implications for executives — the PW Consulting playbook
Below are pragmatic moves to prioritize in 2026. Each is grounded in the report’s quantitative scenarios and validated by client advisory work across the diagnostics value chain.
- Prioritize platform investments that unlock consumable annuities. Build roadmaps that balance capital-light instruments with high-margin reagent franchises.
- Design modular validation plans. Sequentially pursue CLIA waivers or equivalent local designations that expand point-of-care adoption while containing regulatory risk.
- Align channel strategies to clinical workflows. For acute-care platforms, invest in hospital service and IT integration; for ambulatory and home use, build distribution and telehealth partnerships.
- Use M&A tactically to fill capability gaps. Target acquisitions or licensing deals that accelerate multiplexing, sample-to-answer automation or connectivity features rather than chasing low-margin, standalone assays.
- Lock in payers early. Build health-economic dossiers and real-world evidence generation plans in tandem with clinical rollouts to shorten reimbursement timelines.
- Stress-test supply chains. Scenario-plan for reagent shortages, single-supplier risks and regional manufacturing contingencies to avoid revenue loss during demand spikes.
- Monetize data and services. Beyond tests and instruments, bundle analytics, quality-assurance services and teleconsultation to expand customer lifetime value.
What this PW Consulting report delivers (practical contents)
The full report is engineered for decisions, not curiosity. It includes:
- Methodology and transparent market-sizing assumptions (historical 2020–2025 and forecast 2026–2032), with scenario and sensitivity modelling tailored to varying adoption rates and reimbursement outcomes.
- Platform- and test-level competitive benchmarking and vendor scorecards, including regulatory posture, installed-base economics, and R&D pipelines.
- Commercial playbooks: go-to-market templates, pricing and reimbursement strategies, market-entry checklists, and sales-force deployment models.
- M&A heatmaps and diligence checklists highlighting logical targets by capability and geography.
- Operational readiness tools: manufacturing scale-up templates, validation timelines, and supply-chain risk matrices.
- Case studies and primary interviews with hospital labs, clinic purchasing leads and payers that illustrate adoption barriers and procurement levers.
In keeping with a “trailer” approach, this introduction intentionally omits granular segmentation tables and finer breakdowns (regional shares, application splits and product-line dollar splits) that are included exclusively in the full report. That granularity is central to transaction-level diligence and is available with the complete report package.
How to use these insights in 2026 — a one-page execution checklist
- CEO / Board: Validate portfolio against the 2026 operating plan using PW’s scenario models — prioritize cash-generative, high-consumables platforms.
- Head of R&D: Accelerate modular clinical studies aligned to CLIA-level targets; design early payer-engagement protocols for economic evidence.
- Commercial Leader: Map top 50 accounts by POCT adoption readiness and align field resources to high-return segments (acute triage, ambulatory clinics, home health partnerships).
- Head of Corporate Development: Use the M&A heatmap to shortlist targets that deliver either rapid menu expansion or critical digital/connectivity capabilities.
- Operations / Supply Chain: Implement dual-sourcing and reagent-inventory buffers for the next 24 months to mitigate demand shocks.
Concluding perspective
The POCT market presents a clear growth runway through 2032 — with substantial opportunity for well-positioned sellers to capture both device and high-margin consumable value. Regulatory tightening and a return to evidence-driven procurement mean that market access is increasingly a function of clinical, operational and commercial excellence. PW Consulting’s study converts this complex landscape into prioritized actions for 2026: invest where annuities are defensible, partner to accelerate capability gaps, and build evidence to secure durable reimbursement.
For executive teams preparing near-term budgets, M&A pipelines, or product launches, our full report provides the granular segmentation, scenario outputs and playbooks required to de-risk decisions and capture a disproportionate share of upside. PW Consulting can also deliver tailored workshops to convert the report insights into a 90-day execution plan aligned to your organization’s objectives.
For detailed analysis of this topic, please visit the official page: Point-of-Care Testing (POCT) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com