

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Leather Market Poised to Reach USD 1,138 Million by 2032

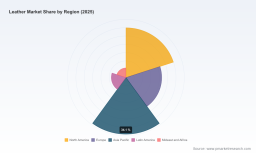
Leather Market 2026 Strategic Outlook — A PW Consulting Briefing
Executive snapshot
As a foundational material linking agriculture, manufacturing, fashion and mobility, the global leather market is entering 2026 from a position of cautious expansion. Our market model (base year 2025) shows the industry valued at approximately USD 732 million and tracking to a mid-single-digit compound annual growth rate (CAGR) of roughly 6.5% over the 2026–2032 forecast window. After pandemic-era shocks and subsequent uneven recovery through 2020–2025, the sector is re-accelerating, driven by premiumization in developed markets, resilient demand in select emerging markets, and sustained investment in downstream manufacturing and finished goods.
Leather Market
Why this report matters for 2026 corporate decision-making
2026 is a hinge year for leather-sector strategy: regulatory regimes (regional and global) are converging on traceability and chemical safety; consumer sentiment is reshaping premium vs. sustainable sourcing choices; and industry structure remains fragmented with top firms accounting for a minority share of global turnover. For executives deciding where to allocate capital, which suppliers to qualify, how to de-risk supply chains, or whether to pursue vertical integration or M&A, the strategic value of accurate, up-to-date market intelligence cannot be overstated. This briefing articulates the pathways where that intelligence converts into concrete decisions.
Leather Market
Macro dynamics and directional signals
- Growth trajectory: The market baseline in 2025 (~USD 732 million) and our 6.5% CAGR imply meaningful upside to 2032. The shape of that growth is not uniform—segments and geographies will outpace the headline due to differential demand drivers.
- Regulatory inflection points: The regulatory calendar through 2026 tightens requirements on origin verification, chemical management and documentation. Notable updates include EU-level deforestation due diligence affecting hides and prepared leather, OEKO-TEX® standards requiring supply-chain transparency, and revised chemical restrictions in major importing jurisdictions. These shifts create both compliance costs and competitive advantage for early adopters.
- Trade and geopolitics: Export behavior and trade flows remain sensitive to geopolitical tensions and tariff adjustments. Recent slippage in some national export volumes underscores the need for market diversification strategies.
- Industry concentration: The sector remains moderately fragmented—the aggregate share of the largest firms does not dominate the market—opening opportunities for consolidation, platform plays and specialist value-chain integration.
Five strategic priorities for 2026
- Secure traceable raw hides now:
With mandatory deforestation and origin verification regimes coming into force, firms that implement traceability systems (slaughterhouse delivery note reconciliation, digital chain-of-custody, supplier audits) in 2026 will avoid production bottlenecks and be first-movers in sustainability claims. Prioritize investments where your product mix is most exposed to regulatory scrutiny and where premium customers demand provenance.
Leather Market - Upgrade chemical and process controls:
Revised chemical restrictions and voluntary standards mean procurement teams must requalify tanneries and finishes against new limits. Implement a tiered supplier qualification (critical, strategic, conditional) and introduce contractual obligations for compliance testing and disclosure to limit downstream rejection and recall risk.
- Differentiate through product and service architecture:
Premiumization provides margin expansion opportunities—designers and manufacturers should convert material science advances (blended leathers, low-impact tanning) into distinct SKUs and marketing narratives while protecting core legacy ranges. For B2B players, bundle traceability and small-batch production as a value-added service for premium brands.
- Position for consolidation and strategic partnerships:
Fragmentation at the supplier and finished-goods levels creates acquisition and JV opportunities. Define acquisition criteria now—capacity, geographic footprint, supply-chain transparency, and niche branding—and prepare integration playbooks that preserve artisanal value while delivering scale improvements.
- Operational resilience and near-market manufacturing:
Reassess production footprints with an emphasis on reducing lead times for premium segments and de-risking exposures to single-source countries. Nearshoring or regionalization can be a competitive lever when combined with automated finishing and higher-margin product focus.
Competitive landscape — what to watch among established players
The market combines heritage tanneries, global branded manufacturers, and nimble niche players. Our qualitative benchmarking highlights strategic archetypes:
- Premium heritage tanneries (e.g., Horween Leather Company):
Strengths: Brand aura, high-margin full-grain and exotic leathers, long-standing OEM relationships. Strategic moves to monitor: selective capacity expansion, collaborations with fashion houses, and traceability pilots that extend the premium story.
- Branded footwear and apparel manufacturers (e.g., Wolverine Worldwide):
Strengths: Brand distribution, vertical integration potential, stable retail channels. Strategic moves: accelerating direct-to-consumer channels, embedding sustainability credentials into product lines, and hedging supply risk through multi-sourcing.
- Specialist European tanneries (e.g., Weinheimer Leder):
Strengths: Technical finishing expertise and proximity to luxury European buyers. Strategic moves: certifications to meet tightening EU standards and partnerships with niche luxury brands seeking traceability.
- D2C leather goods & lifestyle brands (e.g., Saddleback Leather Co.):
Strengths: Distinctive product narratives, customer loyalty, long warranties. Strategic moves: leveraging digital-first channels for premiumization, and collaborating with tanneries that can guarantee origin and high-quality finishes.
- North American furniture specialists (e.g., American Leather Holdings):
Strengths: Customization, domestic manufacturing cachet. Strategic moves: capitalizing on nearshoring demand and certifying supply chains to reassure commercial buyers.
- Export-focused manufacturers in South Asia (e.g., A.V. Thomas Leather; Bhartiya International):
Strengths: Cost-competitive manufacturing, scale in small leather goods and apparel. Strategic moves: upgrading compliance capabilities, pursuing higher-value product mixes, and leveraging trade fairs and export promotion programs to diversify markets.
For incumbent managers and investors, the competitive takeaway is clear: firms that combine product differentiation, verified supply chains, and regulatory-ready operations will capture disproportionate margin improvement in the next three years.
Regulatory and market events to monitor in 2026
- Implementation and enforcement timelines for EU deforestation due diligence affecting hides and prepared leather — immediate implications for exporters to the EU.
- OEKO-TEX® and similar voluntary standards raising the bar on disclosure and traceability ahead of regulatory enforcement.
- Revised chemical restrictions in major import markets tightening allowable treatments and requiring stronger upstream testing and documentation.
- National standards updates in major producing countries that will influence supplier qualification and export readiness.
- Industry trade fairs and showcases (regional leather fairs, design showcases, and international exhibitions) that are concentrating order flows and commercial visibility for manufacturers—use these as points for competitive intelligence and partnership discovery.
What PW Consulting’s Leather Market report delivers (operationally oriented)
Our full report is tailored for decision-makers who need executable intelligence rather than high-level commentary. It combines an audited market model (historical 2020–2025 and forecasts 2026–2032), scenario-led demand stacks, and practical tools that include:
- Regulatory heatmap and compliance checklist aligned to jurisdiction and product category through 2026.
- Supply-chain due-diligence templates (traceability, delivery-note reconciliation, audit protocols) that procurement teams can operationalize within 90 days.
- Supplier scorecards and a short-list of candidate partners for nearshoring, low-impact tanning and premium finishing.
- Go-to-market playbooks for premiumization, B2B partnerships, and D2C leather goods expansion.
- M&A playbook with valuation heuristics for target screening in a fragmented market (integration risks, product/brand preservation and synergies).
- Event and trade-fair calendar plus curated insights from industry showcases and primary interviews conducted during 2025–2026.
- Scenario-based financials and sensitivity analysis that link raw material volatility and regulatory compliance costs to margin outcomes.
On data transparency and what this briefing omits
In line with our “trailer” approach, this introduction highlights strategic conclusions and the operational levers you can employ in 2026—while we intentionally withhold granular segment-level tables (regional and application splits) and supplier-level financials from this public summary. The full intelligence set, including downloadable spreadsheets with detailed segmentation and supplier benchmarking, is available via the PW Consulting portal and through tailored briefings.
Recommended next steps for executives (quick checklist)
- Initiate a 90-day traceability sprint with top-10 raw hide suppliers and prioritized tanneries.
- Commission a compliance gap analysis against EUDR, OEKO-TEX and revised chemical restrictions to quantify near-term remediation costs.
- Identify one pilot nearshoring or small-batch manufacturing partner to reduce lead times for premium SKUs.
- Develop a bolt-on M&A shortlist focused on artisanal tanneries or niche finished-goods brands with defensible customer relationships.
- Schedule engagement at one major trade fair in 2026 to revalidate supplier claims and source innovations in finishes and low-impact tanning.
Concluding perspective
The leather market in 2026 offers a classic strategic paradox: enduring demand and margin pathways coexist with rising regulatory and reputational risk. Firms that treat compliance as a gateway to premium positioning—rather than a cost center—will convert regulatory alignment into commercial differentiation. Our full Leather Market study provides the granular segmentation, supplier-level intelligence, and operational playbooks you need to make those strategic choices with conviction. For access to the complete data, segmentation matrices, and a bespoke briefing customized to your strategic priorities, visit the PW Consulting Leather Market page or contact our industry team for a confidential executive session.
For detailed analysis of this topic, please visit the official page: Leather Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com