

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
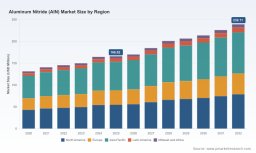
PW Consulting: AIN Market to Reach USD 239.11M by 2032 at 5.5% CAGR

Aluminum Nitride (AlN) Market 2026: Strategic Imperatives for Corporate Decision-Makers
Executive snapshot
As organizations prepare strategic plans for 2026, Aluminum Nitride (AlN) is moving from a niche technical ceramic to a material of strategic consequence across power electronics, microelectronics, and next‑generation optoelectronics. PW Consulting’s latest market model, based on a 2025 base year and a 2026–2032 forecast horizon, shows a steady, mid‑single‑digit expansion trajectory (compound annual growth rate of approximately 5.5%). The total market has expanded meaningfully since 2020 and, under our base case, continues to grow toward an appreciably larger addressable market by the end of the forecast window.
Aluminum Nitride (AIN) Market
Market structure remains concentrated: the top three suppliers control a sizeable portion of global revenue, and the top five further increase that concentration—an indicator that scale, process technology and customer qualification barriers remain high. For executives evaluating investments in 2026, these dynamics make timing, partner selection and regulatory positioning as important as product innovation.
Aluminum Nitride (AIN) Market
Why this matters in 2026: strategic value of AlN intelligence
- Materials-led differentiation: AlN’s unique combination of high thermal conductivity and electrical insulation makes it a preferred substrate and heat‑dissipation solution for power modules, RF devices and certain microelectronic assemblies. Product roadmaps that assume legacy substrates persist risk thermal, reliability and size disadvantages.
- Supply chain and regulatory risk: High‑purity inputs and specialized manufacturing create natural supply constraints. Compounding that are evolving export controls and licensing regimes across key jurisdictions that directly affect cross‑border sourcing and commercial deployment strategies.
- Commercial inflection points: Advances in single‑crystal substrate production and new pilot lines have lowered the lead time and qualification hurdles for some AlN end‑uses. Firms that accelerate qualification cycles can secure early adopter premiums or lock in co‑development partnerships with OEMs.
What our report delivers — practical, decision‑ready outputs
To translate material science into commercial strategy, PW Consulting’s AlN Market study goes beyond descriptive analysis. Clients get pragmatic tools and playbooks designed for 2026 decision cycles, including:
Aluminum Nitride (AIN) Market
- Top‑down market sizing and a seven‑year forecast (2026–2032) with scenario levers for adoption speed, price trajectory and regulatory shock events.
- Demand‑driver analysis tying device architectures (power modules, RF, optoelectronics) to material requirements and adoption roadmaps.
- Price and margin frameworks that model how input volatility and capacity additions affect supplier economics and OEM procurement strategies.
- Supply chain maps and supplier risk matrices that highlight single‑points‑of‑failure, lead‑time curves and near‑term expansion plans.
- A regulatory & trade compliance matrix tailored to export licensing regimes and dual‑use controls that influence route‑to‑market choices.
- Competitive benchmarking, capability heatmaps and an M&A playbook for buyers and strategic investors.
- Actionable go‑to‑market plans and qualification roadmaps for product and application engineers to shorten time‑to‑revenue.
Note: this introduction intentionally omits granular regional and application splits so that procurement teams and strategy leads seeking the full segmentation tables and supplier revenue models can access the complete dataset on our report page.
Competitive landscape: who’s shaping the market and why it matters
The current competitive dynamic blends established technical ceramics manufacturers with specialized single‑crystal innovators. Incumbents with deep ceramic processing expertise have leverage in bulk powders, sintered substrates and machined components. Meanwhile, upstream innovators focusing on single‑crystal AlN are creating new pathways for high‑performance RF and power semiconductors.
- Large ceramic manufacturers continue to compete on formulation control, production scale and downstream value‑added services (e.g., machined components and packaging). These players benefit from broad customer relationships across industrial and electronics OEMs.
- Specialized single‑crystal providers are commercializing larger diameter substrates and pilot production lines, a development that can redefine qualification cycles for power and RF device OEMs.
- Powder and granule suppliers underpin the entire value chain; raw material purity and consistent quality are prime competitive levers.
Recent industry moves underline how competitive advantage is being pursued in 2025–2026. Several suppliers announced pilot or expanded production lines for large‑diameter single‑crystal substrates and launched optimized product variants tailored for power/RF device development. Others updated product literature and application guides to accelerate customer qualification. For firms evaluating partners or acquisition targets in 2026, the difference between ownership of proprietary processing IP versus scale of manufacturing capacity will materially affect post‑deal integration plans and margin upside.
Dynamics and risks to factor into 2026 decision‑making
- Raw‑material constraints and price volatility: High‑purity aluminum and nitrogen feedstocks show periodic volatility tied to supply shocks. Procurement strategies that rely on single suppliers or spot markets will face margin erosion and delivery risk.
- Regulatory and export controls: In several jurisdictions, AlN substrates and associated technologies are subject to licensing for certain end uses, especially where military or sanctioned entities are potential customers. Compliance frameworks must be embedded in commercial agreements and supply‑chain mappings.
- Geopolitical re‑shoring and trade frictions: Elevated US‑China tensions and tighter controls on critical materials necessitate alternative sourcing and contingency manufacturing footprints for firms with global customers.
- Technology displacement risk: While AlN adoption is accelerating in targeted applications, competing substrate technologies and packaging innovations could compress addressable markets in scenarios where cost or integration complexity outweighs performance benefits.
Recommended strategic playbook for 2026
For executives who need to convert market intelligence into board‑level choices this year, we recommend a prioritized set of actions:
- Secure multi‑tier supply commitments: Move from spot purchases to dual‑sourced long‑term agreements with tiered pricing and capacity reservation clauses. Include quality KPIs and contingency allocations tied to capacity expansions.
- Accelerate qualification through co‑development: Establish shared engineering teams with substrate suppliers and OEM customers to shorten device qualification cycles and capture first‑mover adoption incentives.
- Invest selectively in capabilities: Where margin and strategic value align, pursue minority equity stakes or JVs with single‑crystal innovators to secure priority access to new wafer sizes and substrate grades.
- Embed regulatory compliance in commercial strategy: Implement export‑control screening tools and contractual language to manage licensing risk, including clauses for restricted end‑use and destination countries.
- Design for supply flexibility: Re‑architect BOMs and qualification plans to accept multiple substrate grades when feasible; build modular designs that can tolerate material substitution with minimal re‑qualification.
- Use pricing levers wisely: Protect margins via value‑based pricing for differentiated substrate solutions, while retaining a competitive offering for commoditized grades.
- Scenario funding & capex gating: Adopt milestone‑based funding for capacity expansions—link capex tranches to customer qualification and binding offtake agreements to avoid stranded assets.
Scenario planning & watch‑list triggers
We recommend three monitoring triggers tied to adaptive strategies for 2026:
- Supply shock trigger: Sudden raw‑material shortages or export control changes that materially increase lead times—activate strategic stockpiles and close‑in sourcing.
- Demand acceleration trigger: Rapid adoption in a high‑volume end market (e.g., electrified powertrain or a new RF standard)—accelerate capacity and prioritize preferred customers.
- Technology substitution trigger: Breakthroughs in rival materials or packaging approaches—defer major capex and increase R&D pivot funding.
How PW Consulting supports 2026 decisions
PW Consulting brings integrated advisory services combining market models, raw‑material economics, regulatory intelligence and M&A execution. For clients acting in 2026 we offer tailored deliverables:
- Segment‑level revenue tables, price curves and supplier P&L models to run internal investment committees.
- Regulatory checklists and export‑control playbooks mapped to sourcing scenarios.
- Supplier due diligence packs and integration plans for minority investments or acquisitions.
- Customer‑specific qualification roadmaps and cost‑to‑qualify calculators to shorten commercialization timing.
AlN is no longer a laboratory curiosity—its adoption curve and the competitive moves we track make it a boardroom issue for any company competing in thermal‑limited electronics. This preview outlines the key decision vectors you must consider in 2026: supply, standards, strategic partnerships, and regulatory posture. For the full, data‑rich report with complete regional and application segmentation, supplier revenue breakdowns, price models and downloadable Excel workbooks designed to feed your planning systems, access the PW Consulting Aluminum Nitride Market report page.
For detailed analysis of this topic, please visit the official page: Aluminum Nitride (AIN) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com