

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Security Screening Market Soars to USD 14,100M by 2032 at 7.8% CAGR

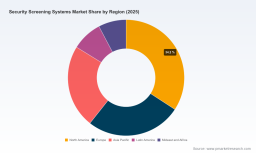
Security Screening Systems Market 2026: Strategic Imperatives for Procurement, Technology and Compliance
As global security priorities shift from episodic responses to persistent, intelligence-driven screening architectures, the Security Screening Systems market is entering a phase where strategic purchasing decisions in 2026 will dictate both near‑term operational resilience and multi-year cost outcomes. PW Consulting’s latest market study — grounded in five years of historical tracing and a seven-year forecast horizon — frames those decisions with rigorous financial projections, competitive intelligence, regulatory mapping, and operational playbooks designed for program owners, chief security officers, and procurement teams.
Security Screening Systems Market
Macroeconomic trajectory: validation for strategic investment
The market’s macro trajectory validates renewed capital allocation to screening capabilities. Using a 2025 base year, our topline metrics show sustained growth across the historical window and a forecast compound annual growth rate (CAGR) of 7.8% through 2032. In practical terms, this translates into a meaningful expansion of the addressable market over the next several years, driven by technology refresh cycles, regulatory upgrades, and demand for higher throughput and automated screening in transportation hubs and critical infrastructure.
Security Screening Systems Market
For decision-makers, the implication is twofold: first, competition for best‑of‑breed systems will intensify, increasing the importance of precise vendor evaluation; second, procurement windows are opening for integrators and managed‑service models that can deliver scale quickly while absorbing lifecycle risk. Our study quantifies the opportunity curve and, more importantly, isolates the investment inflection points where CapEx-to-Service tradeoffs yield optimal total cost of ownership (TCO).
Security Screening Systems Market
What this report delivers — actionable content, not generic summary
- Scenario‑based market forecasts and sensitivity analysis tied to technology adoption rates and regulatory shifts, enabling portfolio managers to stress‑test procurement plans under realistic upside/downside scenarios.
- Vendor strategy dossiers and a practical vendor scorecard methodology that evaluates suppliers on technical performance, systems interoperability, lifecycle services, cybersecurity posture, and commercial flexibility.
- Procurement playbooks and RFP templates crafted to minimize vendor lock‑in, accelerate deployment timelines, and ensure compliance with cross‑border data and radiation safety requirements.
- Operational deployment checklists for remote and centralized screening architectures, including guidance on staffing models, image‑review workflows, and performance SLAs for automated detection systems.
- Financial tools: TCO calculators, payback models, and procurement vs. as‑a‑service comparative analyses that contextualize capital investment against recurring costs and technology obsolescence risk.
Each deliverable is designed to be operational — not academic — allowing program leads to move from strategy to procurement within a standard fiscal quarter with clear governance artifacts and negotiation levers.
Market structure and competitive dynamics
Industry concentration remains moderate. The three‑firm concentration ratio (CR3) and five‑firm concentration ratio (CR5) indicate a market where leading platform providers hold meaningful but not dominant shares, leaving room for specialist entrants and regional incumbents to win targeted contracts. That structure creates a two‑track competitive dynamic: large systems integrators pursue scale projects (airports, ports, national border programs), while agile innovators capture trials and niche venue deployments (stadiums, schools, corporate campuses) with differentiated detection modalities.
Key players profiled in the report — each with distinct strategic plays — include long‑established scanning OEMs and emerging AI‑first entrants:
- Smiths Detection (United Kingdom): advancing CT‑based baggage and cargo screening with integrated AI and remote screening platforms; recent deployments include automated international remote baggage screening pilots that underscore a push into distributed operations supporting cross‑border customs authorities.
- OSI Systems / Rapiscan (United States): focused on high‑throughput non‑intrusive inspection systems for cargo and vehicle screening; recent contract wins reflect ongoing demand from logistics and border security programs.
- Leidos (United States): expanding capabilities through strategic partnerships to combine enterprise security solutions with advanced imaging, including millimeter wave and AI‑enabled passenger detection.
- Nuctech (China): offering advanced X‑ray and CT screening with increasing integration of machine‑learning stacks for automated threat recognition in cargo and passenger checkpoints.
- CEIA (Italy): continuing to defend core market share in walk‑through and handheld metal detection with robust product portfolios for public venues and transport hubs.
- L3Harris, Analogic, Evolv Technologies, and AS&E: each presents differentiated plays across imaging performance, medical‑grade imaging crossover, AI‑driven walk‑through detection, and non‑intrusive inspection systems respectively.
The most important takeaway for procurement leaders is to align vendor choice with program scale and risk appetite: incumbent OEMs and integrators offer stability and global service footprints, while newer entrants can deliver speed and disruptive detection capabilities but may require more stringent validation and contractual safeguards.
Regulatory and compliance imperatives shaping purchases in 2026
Regulation and standards are a decisive factor in procurement timing and system selection. The report synthesizes the practical implications of several key standards and funding signals that will influence buying behavior this year:
- Radiation safety frameworks (e.g., ANSI/HPS N43.17 guidance on dose limits) constrain design and operational use cases for systems employing ionizing radiation; screening programs must plan for regulatory testing and public communication strategies.
- Safety standards for millimeter‑wave systems (IEEE C95.1 family) remain the technical baseline for non‑ionizing screening solutions; certification lead times can affect rollout schedules, especially for public‑venue deployments.
- Targeted government funding — including dedicated allocations for computed tomography checkpoint baggage systems in recent fiscal appropriations — creates short windows for capex procurement aligned to budget cycles and grants.
- Interoperability and data handling: deployments that encompass cross‑border remote screening must embed personal data protection and cybersecurity controls to comply with national frameworks and customs agency requirements; these mandates have real contractual and systems‑architectural consequences.
Procurement teams must therefore include regulatory milestones and testing cycles in procurement schedules; failure to do so risks costly retrofit projects and delayed time‑to‑mission.
Technology trends and procurement implications
Three technology vectors are shaping procurement choices:
- AI‑augmented detection and image analytics — improving throughput and decreasing false positives, but increasing the need for explainability, labeled data governance, and performance benchmarking under adversarial conditions.
- Computed Tomography (CT) and advanced imaging — enabling higher detection fidelity and automated resolution, increasingly preferred at high‑throughput checkpoints; lifecycle and energy costs must be considered in TCO models.
- Distributed/remote screening operations — centralizing human image review away from checkpoints reduces staffing constraints and enables specialist operators, but raises data sovereignty, latency, and cybersecurity requirements.
In practice, these vectors shift procurement conversations from “box purchase” to “service and data contract” negotiations: buyers must secure software update guarantees, data access rights for model retraining, and explicit SLAs for algorithmic performance drift.
Risk and mitigation — what 2026 should prioritize
Major downside risks include regulatory delays, supply chain disruptions for critical imaging components, and cybersecurity breaches exposing screening data. To mitigate, the report prescribes:
- Staggered procurement phases with plug‑and‑play upgrade pathways to avoid single‑vendor lock‑in.
- Contract language that ties payment to accredited performance tests and independent validation, including adversarial penetration tests for AI models.
- Governance frameworks for data handling that satisfy multi‑jurisdictional privacy laws and customs cybersecurity protocols for cross‑border operations.
Recommended next steps for 2026 decision-makers
Based on the analysis, security program owners should take the following actions this fiscal year:
- Commission a short, vendor‑agnostic technology assessment to map existing assets against emerging capability requirements and regulatory obligations.
- Run a controlled pilot with clearly defined acceptance criteria tied to throughput, detection efficacy, and false‑alarm economics; include independent third‑party validation in the pilot scope.
- Update procurement specifications to require transparent AI model performance reporting, data portability clauses, and lifecycle upgrade commitments.
- Negotiate flexible financing — consider hybrid CapEx/Opex structures that retain upgrade options as detection technologies mature over the forecast horizon.
Why PW Consulting’s report matters for your 2026 plans
Our analysis is intentionally tactical: it translates macro growth (the market’s ascent from its 2025 base through a multi‑year CAGR) into procurement roadmaps, vendor evaluation frameworks, and compliance checklists that are immediately usable. The market’s moderate concentration profile provides both incentive and challenge — it rewards due diligence, not impulse purchases.
We have deliberately withheld detailed sub‑segment revenue breakdowns and granular regional or application shares in this preview to preserve the full strategic value of the research. The published report contains the complete segmentations, vendor scorecards, downloadable RFP templates, and working financial models you will need to finalize procurement in 2026.
Schedule a briefing with PW Consulting to align your program priorities to market timing, secure access to our vendor matrices, and accelerate procurement with validated TCO tools and compliance checklists.
For detailed analysis of this topic, please visit the official page: Security Screening Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com