

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Underlayment Market to Reach USD 1,935.6M in 2025 at 4.8% CAGR

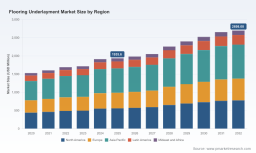
Flooring Underlayment Market — Strategic Outlook for 2026 Decision-Makers
Executive overview
As PW Consulting’s senior industry analyst, I present a focused strategic primer to orient executive teams, corporate development groups, and portfolio managers preparing for a critical planning window in 2026. Our new market study uses 2025 as the base year and traces historical performance from 2020–2025, then projects out across 2026–2032. The global flooring underlayment market—measured in USD Million—has expanded steadily since 2020 and, based on our modeling, is expected to continue growing at a compound annual growth rate (CAGR) of approximately 4.8% through 2032.
Flooring Underlayment Market
This briefing highlights why this research matters now, where structural growth and risk converge, and how the report’s practical modules equip leaders to make informed capital, product, and commercial decisions in 2026. In keeping with our “trailer” approach, we signal analytical depth while reserving the full granular tables and interactive models for the full report.
Flooring Underlayment Market
Why this research matters for 2026 planning
- Reliable macro trajectory: After pandemic-era dislocations, the underlayment market regained momentum through 2023–2025. By the 2026 planning cycle, companies need clarity on sustainable demand drivers versus transient surges. Our base-year benchmarking and 2026–2032 forecast provide that macro view.
- Cost and input risk are front and center: Polyethylene foam—the primary feedstock for the largest underlayment type—links industry margins directly to crude oil and refinery cycles. Procurement, hedging, and product re-specification are strategic levers that will shape 2026 P&Ls.
- Warranty and standards shape product design: Resilient flooring manufacturers enforce strict installation tolerances (e.g., maximum cumulative underlayment thickness constraints). Product innovation must balance acoustic/moisture performance with dimensional limits to avoid voided warranties—an operational detail with immediate commercial implications.
- Margin pressure from logistics and trade: Tariff volatility and transport surcharges for imported foams, rubber, and cork have introduced a new layer of cost unpredictability. Executives must plan sourcing and regional footprint adjustments in response.
What our full report delivers (practical, actionable modules)
The study is designed as an operating manual for decision-makers, not just a descriptive market summary. Key actionable elements include:
Flooring Underlayment Market
- Forward-looking demand scenarios (base, upside, downside) for 2026–2032 with sensitivity to energy price shocks, trade disruptions, and durable-goods substitution trends.
- Detailed cost-stack modeling that isolates raw material, conversion, freight, and tariff impacts—enabling rapid re-pricing and margin simulation for alternative formulations.
- Go-to-market playbooks for OEMs, private-label manufacturers, and specialty suppliers—covering channel priorities, specification strategies, and installer economics.
- M&A and partnership scorecards: vintage multiples, strategic fit matrices, and integration risk checklists tailored to underlayment assets and adjacent capabilities (acoustics, moisture mitigation, recycled-material processing).
- Operational playbooks for capacity planning and CAPEX timing—anchored to supply normalization scenarios and the sector’s evolving recycling ecosystem.
- Regulatory and warranty compliance matrix with design thresholds that protect OEM warranties while maximizing product differentiation.
Competitive landscape — who matters and why
The market structure displays a moderate concentration: the top three players account for a meaningful share of market capacity, with the top five representing a larger consolidated footprint. This balance creates opportunities for both scale-driven incumbents and technically nimble challengers.
- MP Global Products — Known for acoustic fiber underlayments (QuietWalk brand) and an early mover in integrating recycled content. Their value proposition emphasizes acoustic performance, moisture protection, and sustainability—attributes resonating with both renovation and multi-family residential demand.
- Leggett & Platt Flooring Products — The largest U.S. player in carpet cushion and hard-surface underlayment. Their scale and formulation breadth (foam, rubber, others) give them cost and channel advantages, particularly in private-label supply to major flooring brands.
- Pak-Lite, Inc. — A dominant private-label specialist for floating floors, with deep capabilities in bespoke performance ratings (IIC/STC/Delta). Their bespoke focus makes them a preferred supplier for retailers and OEMs seeking specification control without heavy capex.
- Wise Flooring Products LLC — A U.S.-made, recyclable-product differentiator targeting sustainability-conscious channels. They illustrate how “Made-in” positioning and circular-material messaging can command premium placements in specified projects.
- FloorMuffler — Offers a blended portfolio (XLPP foam, recycled-fiber, rubber) with product lines addressing acoustic and moisture concerns for vinyl, laminate, and hardwood—an example of product-line breadth supporting diverse retail and installer channels.
- Cyg Tefa and other Asia-based suppliers — Represent high-density IXPE/XPE foam capabilities, cost-competitive manufacturing, and strong LVP/laminate alignment. Their trade exposure amplifies sensitivity to tariffs and freight congestion trends.
- Chinese and regional manufacturers — Several professional manufacturers expand capacity and product types to serve global OEMs and private-label partners; competitive dynamics will hinge on quality certification, logistics economics, and the ability to meet warranty-sensitive specs.
Recent industry moves underscore strategic priorities for 2026:
- New product introductions (e.g., premium acoustic solutions with enhanced stability and moisture protection) signal a push toward higher-value underlayments that address end-user comfort and lifecycle performance.
- Promotions highlighting recycled materials reflect growing buyer willingness to trade cost for sustainability credentials—especially in B2B specification channels and commercial projects.
- Regional product showcases and trade participation indicate continued demand growth in emerging LVP and laminate markets, but also point to distribution gaps that incumbents can exploit.
Market dynamics that will drive boardroom moves in 2026
- Raw material volatility: Polyethylene foam pricing remains the single largest input risk; it is correlated to crude oil cycles and refinery capacity. Companies should stress-test margins against oil-price scenarios and consider strategic inventory, alternative feedstocks, or long-term purchasing arrangements.
- Regulatory and technical constraints: Flooring system warranties impose practical limits (e.g., cumulative thickness tolerances). Product development must prioritize thin-profile high-performance solutions to avoid disqualification from major floorcovering warranties.
- Transport and tariff pressure: Escalating import surcharges for foam, rubber, and cork mean regional sourcing and nearshoring strategies can materially affect landed costs and service levels.
- Recycling and supply normalization: The post-2023 stabilization of recycled rubber and natural cork supplies has enabled selective capacity investments. Suppliers that lock-in circular-material feedstocks gain both ESG credentials and a buffer against petrochemical swings.
- Installation economics: Labor and moisture mitigation requirements alter the total installed cost. Manufacturers that simplify installation or partner with installer networks can win specification share even at modest price premiums.
Strategic moves we recommend for 2026
- Prioritize product sets that combine thin profiles, acoustic performance, and moisture mitigation—this triad addresses warranty constraints while matching buyer preferences in residential and commercial refurbishments.
- Adopt a mixed sourcing model: combine regional manufacturing for warranty-sensitive, high-service customers with offshore cost advantages for commoditized SKUs. Use tariff-pass-through frameworks in contracts to reduce margin shock.
- Invest selectively in recycled-material lines where procurement can secure feedstock at scale; these products support differentiated pricing and improve resilience against petrochemical swings.
- Build installer-aligned value propositions—training, bundled moisture systems, and labor-saving product formats—to lower total installed cost and accelerate spec acceptance among flooring contractors.
- Use our scenario-based valuation templates to evaluate M&A targets: prioritize manufacturing assets with quality certifications and incumbent customer lists rather than pure capacity plays vulnerable to margin compression.
How to use the full PW Consulting study
The complete report provides the raw and modeled data—annual market totals, supply-demand balances, cost curves, and heat-mapped opportunity zones—that underpin the recommendations summarized above. If you are preparing 2026 budgets, a product roadmap, or evaluating acquisition targets, the study equips you to:
- Quickly quantify the revenue and margin impact of alternative sourcing and product strategies under multiple macro scenarios.
- Compare competitive positioning across formulation, channel, and geographic axes without re-building industry models in-house.
- Prioritize R&D and CAPEX to align with warranty-driven product specs and installer economics that will determine share shifts through 2028–2030.
Closing — the strategic moment
The flooring underlayment market has entered a phase where product-level engineering, supply-chain agility, and installer economics will determine winners more than scale alone. With a 2025 base and an explicit 2026–2032 forecast horizon at ~4.8% CAGR, executives have an opportunity in 2026 to lock in advantaged positions—whether through targeted product innovation, tactical nearshoring, or acquisition of specification-focused assets.
PW Consulting’s full study contains the data tables, regional demand matrices, and playbooks required to convert the strategic imperatives outlined here into executable plans. For access to the complete dataset, segment breakdowns, and downloadable modeling tools, please consult the full report on our website.
For detailed analysis of this topic, please visit the official page: Flooring Underlayment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com