

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Epoxidized Soybean Oil Market Poised for 7.58% CAGR Through 2032

Epoxidized Soybean Oil Market — Strategic Outlook for 2026
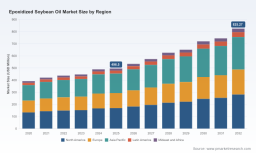
As companies calibrate strategy for the mid-decade inflection, epoxidized soybean oil (ESBO) sits at a crossroads of renewable feedstock dynamics, regulatory scrutiny, and PVC formulation demand. PW Consulting’s latest market study — anchored on a 2025 base year and providing a 2026–2032 forecast horizon — synthesizes historical performance (2020–2025) with forward-looking scenarios to help executives convert market movement into defensible decisions. The market’s compound annual growth rate in the forecast window is modeled at 7.58%, and the study traces a steady increase in absolute market value from the low hundreds of millions (USD Million) in 2020 to a forecasted mid-hundreds by 2026 and beyond — culminating in a projected market size of approximately USD 825.3 Million by 2032 under the base case.
Epoxidized Soybean Oil Market
Why this study matters for 2026 decision-makers
-
Timing advantage: Manufacturers, distributors, and polymers formulators face a narrow window in which to translate capacity investments, product innovation, and contracting strategies into sustainable margin improvement. With the sector growing at a mid-single-digit to high-single-digit CAGR, 2026 is the year to move from exploratory pilots to binding commercial commitments.
Epoxidized Soybean Oil Market -
Raw-material-driven exposure: Epoxidized soybean oil production remains deeply linked to soybean oil markets. USDA forecasts and industry signals point to pronounced demand pressure on soybean oil—as an example, USDA projected soybean oil season-average prices for the 2025/26 marketing year in the neighborhood of $0.59 per pound and a record-level soybean crush demand. These inputs materially influence cost curves and require more sophisticated hedging and sourcing strategies than conventional petrochemical plasticizers.
Epoxidized Soybean Oil Market -
Regulatory and trade risk: Trade remedies and import probes can re-route volumes and distort pricing rapidly. Recent antidumping activity targeting ESBO imports is a reminder that supply-side reconfiguration can be abrupt and regionally concentrated; commercial planners must build playbooks that factor potential import restrictions into supply, contract length, and price pass-through decisions.
-
Concentration and competitive posture: The market exhibits a moderate degree of concentration at the top end (the study’s concentration metrics indicate meaningful share accumulation among the largest suppliers). For both incumbents and challengers, understanding competitive intent — capacity moves, certifications, and channel partnerships — is essential to avoid being an operational follower.
Report contents — What you’ll get (practical, deal-ready outputs)
-
Market sizing and trajectory: Annualized historical data (2020–2025) and multi-scenario forecasts (2026–2032) with a transparent methodology. The base case uses a 7.58% CAGR; alternate scenarios stress raw-material shocks, accelerated renewable-fuel demand, and trade disruptions.
-
Go-to-market and product playbooks: Tactical analysis for product positioning (e.g., food-contact and Kosher-certified grades, high-heat-stability blends), channel strategies (direct sale vs. distribution), and margin optimization levers.
-
Supply chain and cost-sensitivity models: Practical frameworks to quantify exposure to soybean oil pricing, processing yields, and logistics. These models are designed to map to commercial KPIs — break-even pricing, minimum order quantities, and contract tenors.
-
Regulatory and trade-risk matrix: A decision-ready assessment of active trade measures, potential escalation scenarios, and prescribed mitigation steps for procurement, pricing, and customer communication.
-
Competitive intelligence dossiers: Executive profiles, capacity footprints, capability maps, and recent strategic moves for the sector’s relevant players. The report integrates primary and secondary diligence and identifies likely strategic plays you should expect from competitors.
-
Transaction and partnership frameworks: M&A target screening criteria, JV structures, and partnership archetypes tailored for companies seeking rapid market entry or downstream integration.
Note: while the report contains detailed region- and application-level tables and routable data views, this introduction intentionally omits granular segment figures to preserve the value of the full dataset and deliverable models.
Competitive landscape — who matters and why
-
Cargill, Incorporated : A vertically integrated agri-player with manufacturing scale and recent capacity modernization. Its investment in facility expansion signals a strategic intent to secure upstream feedstock flows and to compete on reliability and cost-competitiveness. For partners and buyers, Cargill’s scale creates a stable source but also a competitive pricing benchmark for market bids.
-
Valtris Specialty Chemicals : Differentiates through product certification (food-contact, Kosher) and brand-backed ESBO grades. Its marketing of such grades positions Valtris well in regulated and premium segments where additive provenance and certification are commercial prerequisites.
-
Galata Chemicals LLC : An example of a focused technical innovator, bringing enhanced heat-stable ESBO plasticizers to market. Fast-follower product launches like Galata’s indicate that performance differentiation — not only price — is a durable source of value in PVC formulations.
-
CHS Inc. : Vertical integration via crushing and processing translates into a structural cost advantage when soybean oil is the dominant feedstock. CHS’s position illustrates the strategic benefit of upstream ownership in a commodity-driven input market.
-
ADEKA Corporation : Global distribution reach and established additive platforms enable rapid market access for specialty ESBO variants. For buyers in complex, multi-jurisdiction supply chains, ADEKA’s global footprint reduces execution risk for cross-border procurement.
-
Acme‑Hardesty, ChemCeed, Interstate Chemical and similar suppliers: These companies occupy important niches — branded grades, distribution logistics, and technical-grade offerings respectively. Collectively, specialty and channel-focused suppliers add flexibility to procurement networks and are often acquirers’ targets to quickly extend distribution or technical capabilities.
Recent vendor activity underlines market dynamics: product promotions emphasizing renewability and certification, targeted launches of higher-performance ESBO grades, and capacity expansions by integrated players. These moves align with the broader market signals PW Consulting models: demand growth, feedstock sensitivity, and premiumization for certified, high-performance additives.
Strategic implications and recommended moves for 2026
-
Hedge and diversify feedstock exposure: Given the heavy dependence on soybean oil and the volatility introduced by competing demand streams (e.g., biofuels), buyers and producers should implement multi-layered hedging — a mix of financial hedges, forward purchase agreements, and localized sourcing partnerships to smooth cost shocks.
-
Prioritize product certification as a growth lever: Food-contact, Kosher, and other credentials materially expand addressable demand and create margin protection. Where feasible, accelerate certification programs for high-margin formulations.
-
Build trade-risk contingency plans: The ongoing use of trade remedies means companies must stress-test contracts for force majeure, re-route options, and alternative supplier readiness. Short-term tactical measures (stock buffers, cross-border logistics flexibility) combined with medium-term strategic moves (local assembly or tolling) limit downside exposure.
-
Evaluate vertical integration selectively: Upstream integration into crushing or feedstock aggregation offers cost advantages, but it requires capital and operational capacity. Use the report’s scenario models to assess payback under different soybean price regimes and demand outcomes.
-
Invest in technical differentiation: High-heat-stability variants and specialty ESBO blends are less commoditized and command premium positioning. R&D and co-development partnerships with formulation houses can create sustainable competitive advantages.
-
Design M&A and partnership playbooks: With observable concentration among top players, acquisitive strategies (bolt-ons for channel reach, tech buyers for product breadth) can shorten time-to-market for new grades and regions.
How to use this intelligence
-
Scenario workshops: PW Consulting recommends running a two-day executive scenario workshop using the report’s alternate paths (baseline, raw-material shock, accelerated renewable demand) to align procurement, R&D, and commercial teams on a single set of decisions.
-
Commercial scorecards: Translate the report’s sensitivity analyses into pricing scorecards and contract templates so sales teams can react in real time to raw-material fluctuations while preserving target margins.
-
Due-diligence accelerators: Use our competitive dossiers and financial models to compress target screening and valuation tasks during M&A processes, cutting weeks from diligence timelines.
Final note: this article is a strategic “trailer” designed to surface the decision-relevant signals from PW Consulting’s full ESBO study. For clients seeking the granular, actionable tables (detailed regional and application-level demand curves, supplier share models, and drillable cost curves), the full report includes downloadable data packs and interactive models. Those deliverables are where the revenue-by-segment and contract-level implications are mapped into operational plans — the very details we intentionally hold for the full report to preserve client value.
If your 2026 planning cycle includes portfolio optimization, procurement redesign, or M&A in the ESBO value chain, PW Consulting’s full study provides the templates and scenario engines to convert market outlook into measurable outcomes.
For detailed analysis of this topic, please visit the official page: Epoxidized Soybean Oil Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com