

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Worldwide Tilt & Turn Window Handles Market Set to Expand at a 5.23% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Handles of Tilt & Turn Windows Market — Strategic Briefing for 2026 Decision-Makers
Executive preview
As PW Consulting’s lead industry analyst, I present a targeted strategic briefing drawn from our comprehensive Worldwide Handles of Tilt & Turn Windows Market report (base year 2025). The product category—specialised handles and related hardware for tilt & turn windows—sits at the intersection of building energy-performance regulation, materials cost volatility, and accelerating smart-home integration. Our analysis finds the market has recovered from mid‑cycle volatility and is tracking a steady expansion trajectory, underpinned by regulatory retrofit demand and rising preference for durable metal-based hardware. The market size in 2025 was measured at USD 648.5 million and, given current dynamics, we project steady growth at a compound annual growth rate (CAGR) of 5.23% across our 2026–2032 forecast horizon, with long‑term upside if smart‑home and energy retrofits accelerate.
Worldwide Infiltration Marketing Market
Why this briefing matters for 2026 strategic planning
- Pinpointing inflection points: The next 18–36 months will determine winners in both specification‑driven commercial projects and high-volume residential retrofit channels. Companies that move early on energy‑compliant and connected hardware will capture disproportionate share.
- Cost‑to‑value pressure: Manufacturers face higher input costs (notably aluminum) while buyers demand enhanced functionality. Strategic choices on material mix, finish technologies, and supply contracts will materially affect margin outcomes in 2026.
- Consolidation and partnership windows: Industry concentration is moderate—top manufacturers command meaningful but not dominant shares—creating attractive M&A and joint‑venture opportunities for platform expansion or geographic scale.
Market outlook — a data‑led snapshot (high level)
From a macro perspective the handles market shows resilience and structural expansion. After a modest mid‑cycle dip, total market revenue reached USD 648.5 million in 2025. Under our base scenario—reflecting current regulation, construction and retrofit pipelines, and normalised raw‑material inputs—the market grows at a 5.23% CAGR during 2026–2032, reaching an elevated market size by the end of the forecast period. This trajectory reflects steady demand for high‑performing hardware in both new construction and retrofit markets, with periodic acceleration tied to major regulatory milestone years and smart‑home adoption cycles.
Worldwide Productivity Bots Software Market
Dynamics shaping supplier and buyer strategy
- Regulation as demand lever: Updated energy performance standards in major jurisdictions (notably the EU’s EPBD revisions and the UK’s Future Homes/Part L updates) are driving window replacement and specification upgrades. Tilt & turn systems—due to their airtightness, ease of retrofit, and compatibility with advanced locking hardware—are frequently specified in compliance projects.
- Raw‑material volatility: Producer prices for aluminium mill shapes rose materially in 2025 (notable year‑over‑year increases). This has immediate cost implications for metal‑dominant handle portfolios and places a premium on procurement sophistication—longer contracts, metal hedging or strategic alloy substitution where performance allows.
- Material and finish priorities: Aluminum‑based handles continue to gain share where corrosion resistance and weight are priorities; zinc and stainless offerings retain roles where cost or design premium drive selection. Metal finishes and coatings that extend lifespan in coastal or corrosive environments are becoming specification differentiators.
- Smart integration and standards: Smart window hardware is transitioning from niche to mainstream. Recent product launches supporting Matter and robust radio ecosystems create a new vector of value—security, occupant comfort and system‑level energy optimisation. Suppliers who integrate open, cross‑platform connectivity will find easier entry into premium retrofit projects and OEM spec lists.
- Form and fabrication: Trends toward concealed hinges, multi‑point locking and special‑shape window solutions (round tops, trapezoids) are influencing handle design and mounting systems—requiring closer collaboration between handle makers and hardware system suppliers.
Competitive landscape — positioning and implications
The competitive field blends established European system houses with value‑oriented regional suppliers and design‑led premium brands. Market concentration is moderate—top three players collectively hold a meaningful but not overwhelming portion of market sales, leaving room for nimble specialists and regional consolidators.
Worldwide Inorganic Waveplates Market
- HOPPE (Germany) — https://www.hoppe.com
Strengths: Broad design portfolio across multiple series and finishes; strong brand recognition in Europe; integrated security features for tilt & turn. Strategic implication: HOPPE’s design depth makes it a preferred partner for high‑quality residential and bespoke commercial specifications.
- Gretsch‑Unitas (G‑U) (Germany) — https://www.g-u.com
Strengths: Certified hardware meeting EN standards; lockable handle options; engineering focus for modern systems. Strategic implication: G‑U is well positioned for spec‑led projects requiring tested, certified performance—an important differentiator in regulatory procurement.
- MACO (Austria) — https://www.maco.eu
Strengths: Integrated turn & tilt systems for different profile materials; strong OEM and fabricator relationships. Strategic implication: MACO’s multi‑profile capability supports scale through fabrication channels—key for volume growth in retrofit markets.
- Roto Frank (Germany) — https://www.roto-frank.com
Strengths: Focus on aluminium solutions, concealed hinges, and long‑life corrosion performance; recent product updates emphasize design and endurance. Strategic implication: Roto is the go‑to for premium aluminium systems and international manufacturers seeking robust aesthetic and functional solutions.
- Siegenia (Germany) — https://www.siegenia.com
Strengths: Smart handle development and Matter‑ready 2nd generation products; recent FENSTERBAU showcase. Strategic implication: Siegenia’s connectivity roadmap is a blueprint for entrants pursuing smart‑home and retrofit value pools—expect accelerated adoption where installers can upsell connectivity.
- Winkhaus (Germany) — https://www.winkhaus.com
Strengths: High‑performance hardware solutions including concealed hinge options; strong engineering pedigree. Strategic implication: Winkhaus competes strongly on performance features for premium windows and special shapes.
- ASSA ABLOY Fenestration — https://www.assaabloyfenestration.com
Strengths: Global scale, corrosion‑resistant aluminium solutions, and offerings for special shapes. Strategic implication: Benefitting from group scale, ASSA ABLOY targets international OEM channels and specification projects that demand global supply consistency.
- Trojan (UK) — https://www.trojan.co.uk
Strengths: Value and performance for uPVC and common profiles. Strategic implication: Trojan is a go‑to in price‑sensitive segments where installers prioritise reliability and cost control.
- FPL Hardware (US) — https://fplhardware.com
Strengths: Range tailored for tilt‑turn and casement applications; US‑market orientation. Strategic implication: Regionalisation matters—FPL’s portfolio illustrates the advantage of tailoring SKUs to local profile systems and distributor expectations.
- Formani (Netherlands) — https://www.formani.com
Strengths: Design‑led, award‑winning premium handles for architectural projects. Strategic implication: Formani captures premium margins where aesthetics and brand cachet matter, especially in high‑end European retrofits and new build projects.
Recent signals worth watching in 2026
- Siegenia’s launch of a Matter‑version smart handle (Jan 2026) signals a migration to industry standard smart protocols—buyers will increasingly request Matter compatibility in tender documents.
- Roto’s continued promotion of aluminium‑focused tilt & turn systems (2025 updates) highlights ongoing demand for corrosion‑resistant, premium aluminium solutions in international markets.
- Trade show activity (e.g., new products showcased at IBS 2026) indicates suppliers are pushing integrated system narratives—handle + hardware + connectivity—rather than standalone SKUs.
Actionable strategic playbook for 2026
- Procurement and cost management: Lock targeted aluminium volumes under multi‑year contracts where feasible; assess alloy substitution or partial material mix shifts for non‑structural components to protect margin against metal price spikes.
- Product strategy: Prioritise development of energy‑compliant handle assemblies and Matter‑capable smart handles. Invest in robust radio links and cyber‑security certification to reduce installation friction and reassure specifiers.
- Channel and go‑to‑market: Accelerate partnerships with fabricators and window system OEMs. Offer bundled hardware + connectivity packages to installers to increase attachment rates in retrofits.
- Aftermarket and services: Develop retrofit kits and certification packages for energy‑upgrade projects (labelling, testing, and installer training) to capture high‑margin downstream revenues.
- M&A and partnerships: With moderate top‑end concentration, there is strategic logic to bolt‑on acquisitions that fill material, connectivity, or geographic gaps—targeted tuck‑ins can rapidly expand specification reach.
- Regulatory and standards engagement: Proactively engage with certification bodies and standards consortia to ensure product compliance and to influence emerging test protocols for smart window hardware.
What our full report delivers (operational value)
The PW Consulting report goes beyond headline growth to provide decision-ready deliverables for 2026 planning cycles, including:
- Proprietary market sizing and scenario forecasts through 2032 with sensitivity to raw‑material price paths and regulatory accelerants.
- Supply‑chain mapping and a cost‑to‑serve model that isolates procurement levers and margin pressure points.
- Detailed competitor profiles, product matrices, and go‑to‑market playbooks for market entry, expansion, and consolidation strategies.
- Regulatory impact assessment across major jurisdictions and a compliance roadmap for manufacturers and specifiers.
- Commercial tools: pricing frameworks, bundling strategies, and aftermarket monetisation options tailored to manufacturers, distributors and installers.
To respect the role of this briefing as a prelude, we intentionally reserve the granular segment and regional splits, SKU‑level unit economics and modelled price‑elasticity matrices for the full report and interactive dashboard available on our site.
How to use this insight immediately
- Run a 90‑day procurement stress test: model current supplier contracts against a +20% aluminium price scenario and quantify margin exposure.
- Pilot Matter‑capable handle deployments with two installer partners in retrofit projects to validate installation workflows and capture first‑mover premium data.
- Identify one regional M&A target that closes a capability gap (connectivity, coating tech, or fabrication scale) and initiate commercial diligence.
Next steps
PW Consulting’s full Worldwide Handles of Tilt & Turn Windows Market report is the practical resource for teams preparing 2026 budgets, R&D roadmaps, or M&A pipelines. For bespoke briefings, scenario runs, or to access the full dataset and interactive dashboard (including regional and subsegment detail), contact our research team and download the report from the PW Consulting portal. Use the intelligence to convert regulatory and material volatility into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Handles of Tilt & Turn Windows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Market Insights: Worldwide Electrical Orchard Sprayer Market to Reach USD 1,000.44 Million by 2032
By pmarketresearch, 2026-08-12
Worldwide Electrical Orchard Sprayer Market — Strategic Outlook for 2026 Decision-Making
PW Consulting is pleased to announce the release of our in-depth market research brief on the Worldwide Electrical Orchard Sprayer Market. Built to be immediately usable by executive teams, product leaders, procurement officers and investors, this briefing synthesizes five years of historical performance, a detailed forward-looking model, and practical decision frameworks to guide capital allocation and go-to-market choices in 2026. The analysis demonstrates where value will be created in the next wave of orchard electrification while intentionally reserving core segmentation tables in order to drive clients to the full report for the granular inputs that underpin commercial decisions.
VCSEL Laser Chips Market
Executive snapshot
Electrification of orchard spraying is no longer a pilot-stage curiosity. Our market model values the global market at approximately USD 631.24 Million in the base year 2025 and forecasts growth to about USD 1,000.44 Million by 2032, representing a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 forecast window. The market has accelerated from the historical period of 2020–2025, driven by advances in battery energy density, autonomy and precision application technologies, and by a faster-than-expected willingness by growers to trade capital expense for operating cost reduction and regulatory compliance.
Worldwide Infrared Transmitting Glass Market
Why this matters for 2026 decision-makers
- Capital allocation: Manufacturers and component suppliers must decide whether to prioritize electrified orchard platforms, hybrid architectures, or modular retrofits. The mid-single-digit CAGR through 2032 signals a growth runway long enough to justify factory retooling, but decision timing will affect margin and market share.
- Technology integration: Battery systems and autonomy stacks are now sufficiently mature to deliver full-shift operation in many orchard use-cases. Third‑party battery packs (notably 60–70 kWh-class systems) have been demonstrated to support 10–12 hours of continuous operation in representative deployments, removing a key operational barrier for adoption.
- Operational economics and sustainability: Precision spot-spraying using AI-powered weed detection has been shown in field demonstrations to cut chemical usage substantially. Where installed, these systems materially reduce input spend and regulatory compliance risk, changing the payback calculus for end users.
- Channel and service model implications: With electrified and autonomous platforms, the aftermarket and software subscription layers become as important as hardware sales. Dealer networks that move from pure equipment sales to outcome-based services will capture disproportionate lifetime value.
What our report delivers — practical tools and proven frameworks
PW Consulting’s report is structured as a commercial playbook for 2026 implementation. We pair a transparent market model with actionable tools designed to accelerate good decisions and de-risk execution:
CTA Head and Neck Analysis System Market
- Proprietary market model (Excel): fully auditable top‑down and bottom‑up demand estimates, scenario toggles (adoption curves, battery-cost declines, regulatory tightening) and sensitivity analysis to test strategic options.
- Five strategic scenarios for 2026–2032: baseline, accelerated electrification, delayed battery rollout, rapid autonomy adoption, and fragmented standards — each with P&L impact for OEMs and expected payback periods for growers.
- Vendor scorecards and supplier due-diligence templates: a standardized assessment across technology readiness, manufacturing scale, channel strength, service capability and regulatory posture.
- Field validation case studies: operational KPIs from commercial pilots that explain the gap between lab claims and on-farm economics — including real-world duty cycles, maintenance profiles and operator acceptance metrics.
- TCO / TCA calculators and financing frameworks: factory-to-farm total cost of ownership worksheets incorporating battery life, chemical-use reductions, labour displacement, and service revenue streams to support procurement decisions and leasing structures.
- Regulatory and safety matrix: regional compliance checklists, data privacy considerations for telematics, and operator-safety design priorities for autonomous spraying in mixed-use orchard environments.
Competitive landscape — what recent moves mean
The vendor environment is transitioning from fragmented hardware specialists toward integrated systems players that combine electrification, autonomy and software. Notable industry developments tracked in the report illustrate these dynamics and the strategic responses required of incumbents and newcomers alike:
- John Deere’s integration of an autonomous electric orchard sprayer platform has been a watershed event. The acquisition completed in 2025 brings a fully electric autonomous herbicide sprayer — built around high-capacity battery packs and advanced AI weed-detection — into a global dealer network. This move signals OEM commitment to bundling autonomy, battery and telematics as a single commercial offering targeted at high-value orchard segments.
- Specialist manufacturers are doubling down on complementary strategies. Select European and Oceania-based suppliers have prioritized compact, fully electric sprayers designed for compatibility with electric tractors and small-farm ergonomics. These firms emphasize modularity, field serviceability and crop-specific application techniques (for example, recapture/recycling technologies for disease control in high-density plantings).
- Product updates from established agricultural equipment brands show a parallel playbook: incremental performance improvements in tank design and control systems paired with simplified operation for specialty crop contexts, making electric options more accessible to traditional buyers.
The net effect: a moderately concentrated market where a small group of well-capitalized OEMs and specialist innovators shape platform standards, while a broad base of niche suppliers address diverse orchard types and regional channel structures. For strategy teams, this means monitoring both headline consolidation moves and the ecosystem of accessory suppliers (battery manufacturers, AI detection software providers, retrofit specialists) that will determine who can deliver end-to-end solutions at scale.
Key operational implications and strategic imperatives for 2026
- Design for serviceability and modular upgrades: Battery and autonomy components evolve quickly. OEMs should design platforms that allow battery swaps, electronic control upgrades and sensor refreshes without full-system replacements.
- Build dealer capacity for electric and software services: Training, tooling and new parts inventories are prerequisites for scaling commercial deployments; dealers that invest here will capture aftersales revenue and reduce downtime for growers.
- Pursue strategic battery and software partnerships: Vertical integration can fast-track capability, but partnering with battery specialists and AI providers preserves capex and accelerates time-to-market.
- Create clear financing and subscription offers: Leasing batteries, offering software-as-a-service for precision application, and bundling maintenance into subscription packages materially reduce buyer friction.
- Operationalize safety and compliance: Autonomous sprayers must embed robust person-detection and automatic pause mechanisms to align with liability expectations in orchard work environments.
How growers and procurement leaders should think about 2026 purchases
- Run TCO scenarios that include chemical-use savings from precision spot-spraying and expected battery replacement cycles; the combination often materially shortens payback for high-input, labor-constrained operations.
- Require field trial data from vendors in similar crop architectures and climates. Benchmarks for spray accuracy, drift reduction and maintenance intervals should be contractually specified.
- Prioritize interoperability: if you are electrifying a fleet, choose solutions that integrate with your preferred tractor OEMs and telematics systems to avoid lock-in and stranded assets.
- Factor in dealer footprint and service SLAs: uptime in spray seasons is a business-critical KPI; ensure vendor contractual commitments reflect real-season response times.
Investor and M&A perspective
John Deere’s strategic move to internalize an autonomous electric sprayer underscores the market’s growing strategic value. Investors evaluating targets should focus on four valuation levers: IP in autonomy and detection models, proven battery integration for full-shift operations, established channel or distribution agreements, and recurring revenue potential from software and service offerings. Our report includes precedent transaction analysis and a valuation sensitivity tool built around those levers to support diligence and offer strategy.
Next steps — how to use PW Consulting’s full report
This briefing is designed to be a decision-ready trailer: it communicates the direction and the levers that matter without disclosing every cell in the model. The full PW Consulting report contains the complete, auditable market model (with regional, type and application splits), supplier scorecards with graded assessments, downloadable TCO calculators and step-by-step implementation roadmaps tailored to grower size segments and regional regulatory regimes.
For teams preparing 2026 budgets and product roadmaps, the full dataset and playbooks will materially shorten evaluation cycles and reduce execution risk. Access to vendor-level segmentation and the full scenario matrices enables precise capital planning, procurement evaluation and go-to-market sequencing that can convert the projected growth runway into defensible revenue streams.
To request the full report, the interactive Excel model, or a tailored briefing for your executive team, please contact PW Consulting through our website and reference the Worldwide Electrical Orchard Sprayer Market 2026 Briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Electrical Orchard Sprayer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Non‑Filtering Cloth Vacuum Filters Market Forecast to Hit USD 378.74 Million by 2032, Growing at a 5.85% CAGR
By pmarketresearch, 2026-08-12
Worldwide Non-Filtering Cloth Vacuum Filters Market — Strategic Outlook for 2026: A PW Consulting Preview
PW Consulting’s latest market study on the Worldwide Non-Filtering Cloth Vacuum Filters market provides an operationally focused intelligence package for executives who must make consequential 2026 decisions across procurement, product strategy, operations and M&A. This is a preview designed to demonstrate the report’s depth and immediate relevance while reserving detailed segment-level figures for the full report.
Worldwide Dioctyl Fumarate Market
Market snapshot: Growth trajectory and concentration
The non-filtering cloth vacuum filters market has shown steady expansion through the current decade. Our compiled historical database records market size growth from approximately USD 192 million in 2020 to about USD 254 million in 2025. Looking forward, the market is projected to continue expanding through the 2026–2032 forecast window, reaching roughly USD 379 million by 2032 under a compounding annual growth rate of about 5.85%.
4K Endoscopy Camera System Market
Concentration dynamics matter for strategy: the market remains moderately fragmented, with the top-three vendors accounting for under half of revenues and the top-five approaching just over half. Such a structure creates room for both niche specialists and consolidation plays, depending on technology, service depth and supply chain integration.
Worldwide Inhaler Devices Market
Why this matters for 2026 decision-making
-
Capital allocation and product development: sustained mid-single-digit CAGR signals predictable demand across core industrial end users—enough to justify targeted capex for product line upgrades and automation of manufacturing lines for synthetic yarns and woven cloths.
-
Supplier selection and risk mitigation: fragmentation combined with concentrated material inputs (polypropylene, polyester and specialized multifilament yarns) increases vendor dependency risks. Procurement strategies in 2026 must balance cost, lead-time and technical collaboration ability—particularly for high-stability, wide-format belts and high-temperature synthetics.
-
M&A and partnership discipline: the market structure supports bolt-on acquisitions for firms seeking immediate access to filtration fabrics expertise, regional footprints or specific polymer technologies. A focused due diligence framework will separate scale-driven targets from technology-led niche players.
-
Regulatory and quality-driven segmentation: increasing regulatory scrutiny in food, pharmaceutical and certain clean-water applications favors suppliers that can demonstrate food-grade certifications, hygienic manufacturing and traceable supply chains—criteria that should be embedded in 2026 supplier scorecards.
Market dynamics shaping 2026 priorities
-
Raw material tightness and cost pass-through. Polypropylene and polyester remain the dominant feedstocks for woven and non-woven vacuum filter cloths. Price volatility in these polymers, together with periodic logistic constraints, will influence manufacturers’ margin structures and contract terms in 2026. Buyers will look for vendors with upstream relationships or hedging strategies to stabilize supply and pricing.
-
Performance-driven adoption. Across mining, mineral processing and wastewater treatment, demand is being driven by requirements for improved cake dryness, faster throughput and reduced downtime. Customers are increasingly procuring tailored cloth architectures (monofilament vs multifilament, specialized coatings, edge reinforcements) and demanding validated life-cycle metrics rather than simple unit price comparisons.
-
Certification and hygiene. Where vacuum filter cloths interface with food processing or pharmaceutical streams, compliance with food-grade standards (FDA, CE-equivalent hygiene standards) is a gating factor—affecting which vendors can participate in shortlists and how product life-cycle documentation is managed.
-
Technology and manufacturing scale. The ability to produce wide-format belts with dimensional stability and abrasion resistance (some vendors report belt widths of several meters) differentiates suppliers in industries requiring large-area filtration. Proprietary closures, edge reinforcement techniques and polymer blends are practical competitive levers.
Competitive landscape — profiles and positioning
The market combines global engineering groups, vertically integrated manufacturers and specialized European fabric innovators. The following is an analytical primer on five emblematic competitors identified in our study and the strategic implications for buyers and investors.
-
Micronics Engineered Filtration Group (part of Cleanova) — A US-based custom-engineering leader with deep capabilities across rotary disc, drum and horizontal belt filters. Micronics’ strength lies in application engineering and systems-level integration, making them a preferred partner for operations-constrained industrial users seeking turnkey upgrades and performance validation across mining, alumina refining and wastewater. For 2026 procurement strategies, Micronics is a candidate where technical co-development and long-term service agreements are priority selection criteria.
-
Bolian Filtration Solutions (Liaoning Bolian) — A China-headquartered manufacturer focused on woven filter cloths for a wide range of vacuum filtration variants and expanding into energy-related niches such as lithium battery processing. Recent activity shows an emphasis on industry engagement—exhibitions and supplier awards—indicating an aggressive commercial push and growing recognition among large OEMs and process operators. For buyers, Bolian represents a cost-competitive, rapidly scaling alternative with improving credentials for global project supply.
-
GKD Group (GKD Gebr. Kufferath AG) — A German supplier offering belt systems and cloths with integrated know-how in vacuum box design and wash-water management. GKD’s proposition is systems-oriented: cloth + hardware + spares. Companies prioritizing uptime and system harmonization often favor this model, as it reduces specification risk and simplifies warranty and maintenance pathways.
-
Testori S.p.A. — An Italian supplier focused on polymer-variant filter media and cake-discharge engineering. Testori’s strength is customization in polymer selection and yarn architecture, making them viable for applications where precise cake-release behavior and polymer compatibility are critical—food and specialty chemicals among them.
-
K2TEC — A French firm noted for material breadth (PP, PES, PA, PVDF, PTFE) and mechanical innovations such as patented closures and reinforced edges. K2TEC’s technical IP is valuable for operations requiring very fine control over pore size and mechanical durability—pharmaceuticals, fine chemicals and abrasive mineral processing.
Recent vendor movements and what they signal
-
Trade-show activity and supplier awards are more than marketing; they are barometers of market momentum and procurement recognition. Bolian’s sustained presence at major filtration exhibitions and recent supplier commendations in 2026 signal rising commercial acceptance and should prompt global buyers to include them in competitive bid lists where cost and scale matter.
-
European and US suppliers continue to compete on engineering depth and service models, while Asian manufacturers increasingly offer competitive lead-times and modular customization. Expect supplier strategies in 2026 to converge around hybrid offers: engineering + localized manufacturing footprints.
What the full PW Consulting report delivers (practical, executable content)
The full report is structured for action. Key deliverables include:
-
Transparent market sizing and conservative-to-optimistic scenario modelling for 2026–2032, including sensitivity testing on polymer price swings and capex cycles in mining and wastewater sectors.
-
A competitive scorecard with supplier capability maps, including manufacturing footprint, material range, certifications, lead-time profiles and aftermarket service models—designed to fast-track vendor shortlisting.
-
Procurement playbook for 2026: recommended contractual clauses, SLAs tied to cake dryness and belt lifetime, inventory buffers and raw-material pass-through templates.
-
Operational improvement guide: process KPIs to validate cloth upgrade ROI (cake moisture reduction, cycle-time uplift, cloth service life) and a template workshop agenda for supplier co-engineering pilots.
-
M&A and partnership framework: valuation multipliers for niche fabricors, integration risk checklist, and price/volume threshold models to justify bolt-on acquisitions.
-
Regulatory and compliance appendix: food-grade and hygiene checklists mapped to procurement gate criteria for 2026 tenders.
How to use the preview in 2026 planning
-
Prioritize proof-of-value projects: use short pilot programs to validate supplier claims on cloth life and cake moisture benefits before committing to large rollouts.
-
Lock flexible supply agreements: structure contracts with optionality on volumes to protect against raw-material cost swings while preserving preferred pricing for scale.
-
Embed certification milestones: require evidence of hygiene and material certifications for food and pharma applications early in the RFP phase to avoid late disqualifications.
-
Consider targeted acquisitions: small fabricators with IP in edge-reinforcement or closure systems may be high-impact, lower-cost ways to accelerate technical capability.
Next steps — where to get the complete intelligence
This preview highlights the broad contours and strategic imperatives the PW Consulting report provides to executives planning for 2026. The full report contains the granular supplier matrices, validated methodology, scenario models and downloadable procurement templates instrumental for executable decisions. For procurement directors, operations heads and strategy teams preparing budgets and R&D roadmaps in 2026, the complete report is the practical tool to convert market opportunity into measurable outcomes.
Access the full Worldwide Non-Filtering Cloth Vacuum Filters Market report on our website to download the comprehensive dataset, supplier scorecards and actionable playbooks required for confident decision-making in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Non-Filtering Cloth Vacuum Filters Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide 2D Game Market to Surge from USD 55,200 Million in 2025 to USD 91,579.5 Million by 2032 at 7.5% CAGR — Mobile (USD 35,955.7M), Asia‑Pacific (USD 27,593.4M) and RPGs (USD 19,291.6M) Lead the Charge
By pmarketresearch, 2026-08-12
Worldwide 2D Game Market — 2026 Strategic Outlook: What Leaders Need to Know
PW Consulting’s latest market intelligence brief, the Worldwide 2D Game Market, delivers a focused, decision‑grade synthesis for executives, investors, and studio leaders preparing strategies in 2026 and beyond. Built on a detailed historical baseline (2020–2025) and a forward forecast (2026–2032), the study combines quantitative forecasting with tactical playbooks and competitor diagnostics to convert trends into actionable choices. This release is intended as a strategic “trailer”: we surface the critical implications and frameworks that matter for boardrooms and product teams, while directing decision‑makers to the full report for granular segment tables, interactive models, and proprietary vendor scoring.
Worldwide Liquorice Extract Market
Market snapshot: the macro trajectory that underpins 2026 decisions
Over the last half‑decade the global 2D game market has shown steady expansion. From a solid baseline in 2020, the market reached an institutional milestone in our base year, 2025, and is projected to continue growing through the 2026–2032 forecast window at a compound annual growth rate of 7.5%. Underlying this trajectory are persistent consumer demand for accessible experiences, renewed commercial interest in retro and “HD‑2D” aesthetics, and tooling advances that lower time‑to‑market for studios of all sizes.
Worldwide Land-Based Salmon Market
For strategy teams evaluating product roadmaps, regional entry or M&A, the headline facts matter because they change capital allocation, talent hiring and platform prioritization. The magnitude of the market and the multi‑year growth profile create room for differentiated bets — but only when organizations align offering design, monetization and distribution to contemporary market dynamics rather than legacy assumptions.
Engine Cabin Market
Why 2D is a strategic priority in 2026
- Creative leverage: 2D enables distinctive art direction and compact production cycles, giving indie and mid‑sized studios pathways to global attention without AAA budgets.
- Technical leverage: Advances in 2D engines and pipelines (sprite atlases, lighting, particle systems) are reducing friction for high fidelity visual styles, including HD‑2D remakes and hybrid titles.
- Commercial leverage: Niche communities and retro IP revivals demonstrate outsized engagement and durable monetization — if product, pricing and community management are well aligned.
- Distribution leverage: Emerging regulatory scrutiny and evolving store economics are reshaping discoverability; a nuanced distribution strategy is now a material competitive factor.
What the PW Consulting report delivers — practical, implementable content
Our research is built for action. The report is organized to support three immediate use cases: product strategy and roadmaps, corporate development and M&A screening, and operational optimization for studios and publishers. Key deliverables include:
- Quantitative forecast model (2026–2032) with scenario variants and sensitivity analysis calibrated to alternative consumer, pricing and regulatory outcomes.
- Engine and tool selection matrix that evaluates total cost of ownership, platform reach, talent availability and upgrade paths for Unity, Godot, GameMaker and other toolchains.
- Go‑to‑market playbooks for indie titles, mid‑tier launches and legacy IP remasters — including launch cadence, pricing levers, live ops frameworks and UA sequencing.
- Monetization decision framework comparing premium, tiered, ad‑supported and subscription cross‑sells against player segment behavior profiles.
- Outsourcing and delivery scorecards for art, animation and QA providers with recommended governance, SLAs and cost‑control templates.
- M&A screening filters and valuation heuristics tailored to 2D assets, IP portfolios and specialist studios, plus a short‑list methodology for bolt‑on acquisitions.
- Regulatory and distribution risk register with mitigation steps for discoverability disruption and platform policy changes.
- Executive dashboards and KPIs (LTV, CAC, retention cohorts, creative iteration velocity) ready for integration into investor decks and product war rooms.
Competitive landscape and strategic positions
The 2D ecosystem in 2026 is a mosaic of legacy platform holders, indie specialists, engine providers and outsourcing partners. Our competitive chapter synthesizes the strategic posture of the most consequential players and the implications for partners and competitors.
- Nintendo (Kyoto): Continues to set a premium standard for platform‑level 2D delivery and IP stewardship. Its first‑party titles remain a commercial lighthouse and a benchmark for quality expectations in platformers and adventure games.
- Capcom (Osaka): Leverages legacy franchises and specialist teams to sustain catalog value in 2D fighting and side‑scroll genres; their episodic and remaster strategies are instructive for monetizing classic IP.
- Konami (Tokyo): Recent announcements signal continued investment in retro‑inspired 2D titles; publishers with strong IP catalogs are demonstrating viable paths for mid‑cycle revivals and co‑development partnerships.
- Devolver Digital (Austin): The indie publisher’s global distribution and marketing finesse shows how curated, auteur‑driven 2D titles can achieve outsized returns with disciplined UA and PR.
- Engine providers — Unity (San Francisco), Godot (open source), YoYo Games (GameMaker): Each engine plays a distinct role. Unity’s broad reach and recent 2D improvements accelerate scale projects and cross‑platform parity; Godot offers cost advantages and community velocity for lightweight titles; GameMaker remains a rapid‑prototyping staple for 2D-first teams.
- Platform and storefront players (Epic, Ubisoft): Epic’s store and partnerships can amplify discoverability for curated 2D releases; Ubisoft’s indie programs illustrate publisher support models and hybrid publishing opportunities.
- Outsourcers and co‑development specialists (Keywords Studios, Virtuos, Room 8, Kevuru, Stepico): These firms are critical leverage points for studios scaling art, animation and QA with consistent quality. Their geographic footprint and specialization allow buyers to optimize cost, speed and creative fidelity.
Recent catalysts and what they mean for strategy
- Tooling updates (Unity 6.3 LTS, March 2026): Reductions in art pipeline friction and improved sprite atlas practices lower development risk for higher‑quality 2D titles and enable teams to push into HD‑2D aesthetics without disproportionate engineering lift.
- IP-driven releases (Konami’s 2026 announcement): High‑profile legacy IP revivals validate the commercial runway for curated remakes and create marketing halos that benefit adjacent indie sales windows.
- Authoring platform movement (RPG Maker HD‑2D support teased, March 2026): Democratization of HD‑2D toolchains expands the addressable community of creators and increases supply of stylistically similar titles — intensifying discoverability competition.
- Industry reports (e.g., BCG, Dec 2025) highlighting tiered pricing and subscription pressure: Monetization strategies must be nimble. Our consumer segmentation insight — with a material cohort willing to pay premium and another that is price sensitive — should guide mixed pricing experiments.
- Macro context: Global video game software and content revenues hit record levels in 2025, signaling capital availability and buyer interest; concurrently, evolving platform regulation affects distribution economics and discoverability strategies.
Five strategic imperatives for executives in 2026
- Prioritize engine and toolchain fit by product archetype. For episodic, cross‑platform releases choose engines with mature 2D pipelines; for lean indie projects evaluate open‑source and lightweight engines to preserve margin and control.
- Design monetization as a portfolio, not a point decision. Use a mix of premium, episodic DLC, season passes and low‑friction subscriptions tailored to the distinct player segments identified in market research.
- Build a discoverability playbook that anticipates platform regulation. Invest in owned channels (community, direct commerce), strategic storefront partnerships and data-driven UA to reduce dependence on single‑source discoverability.
- Operationalize outsourcing with governance. Use scorecarded outsourcing for art and QA while preserving core creative competencies in‑house; establish rapid feedback loops and IP protections in contracts.
- Adopt a dynamic M&A and IP strategy. Target acquisitions that provide creative teams, proprietary tech or stable live revenue streams; valuation should reflect the relatively fragmented competitive structure and the ability to scale niche hits.
How PW Consulting’s report accelerates 2026 decision cycles
Executives facing constrained time horizons need evidence‑based, executable guidance. Our report reduces uncertainty by combining an audited macro model, scenario testing and hands‑on playbooks that product, commercial and corporate development teams can deploy immediately. Whether you’re sizing a new studio investment, prioritizing an engine migration, or calibrating pricing tests, the report supplies the quantitative inputs, qualitative diagnostics and templates to fast‑track decisions without sacrificing rigor.
We intentionally withhold detailed regional, platform and genre splits in this press summary to preserve the investigative value of the full research package. The full report includes the complete segmentation matrices, interactive forecast workbooks, granular vendor ratings and case studies required to operationalize the recommendations above.
Next steps
For boards, PE sponsors, publishers and studio leaders preparing 2026 budgets and strategic plans, this report is designed to be a working document: import the model into planning cycles, run scenarios against your own KPIs and use the vendor scorecards to inform procurement and M&A screening. Visit PW Consulting’s Worldwide 2D Game Market page to access the full dataset, dashboards and downloadable templates that power these recommendations.
For detailed analysis of this topic, please visit the official page: Worldwide 2D Game Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Porcine Fibrin Sealant Market Poised to Grow at a 7.2% CAGR Through 2032
By pmarketresearch, 2026-08-12
Worldwide Porcine Fibrin Sealant (PFS) Market: Strategic Signals for 2026 Decision-Making
As healthcare providers, medtech investors, and corporate strategy teams prepare roadmaps for 2026, porcine fibrin sealants (PFS) are shifting from niche adjuncts to a clearly defined market segment with durable growth dynamics. PW Consulting’s newest market study synthesizes seven years of historical performance with a robust 2026–2032 forecast to provide pragmatic, executable guidance for commercial, regulatory, and R&D strategies.
Industrial Flame Photometers Market
Market Snapshot: Growth Trajectory and Market Structure
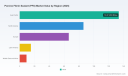
Our model shows the global PFS market expanded from the low hundreds of millions in 2020 to USD 310.5 million in 2025, reflecting steady clinical uptake and expanding hospital access pathways. Looking forward, the market is projected to reach roughly USD 505.2 million by 2032, underpinned by a compound annual growth rate (CAGR) of approximately 7.2% over the forecast horizon. These headline numbers underscore a market that is both material and investible — large enough to justify dedicated commercialization efforts, yet fragmented enough to reward focused competitive plays.
Bulk Tote Dumpers Market
Competitive concentration is meaningful: the top three suppliers account for roughly two-thirds of reported market revenues, while the top five approach mid‑80s market share. This structure creates a dual dynamic: incumbents can leverage scale economies and hospital relationships, while agile challengers can capture share through targeted access strategies, differentiated clinical evidence, and nimble pricing/reimbursement positioning.
Worldwide Firewall Security Management Software Market
Why 2026 Is a Strategic Inflection Point
- Regulatory and reimbursement momentum: Recent product catalog inclusions and local market access initiatives have accelerated hospital procurement timelines in multiple locales. Where catalog access and prioritized negotiation pathways exist, adoption curves compress and product uptake becomes a matter of transaction execution rather than clinical persuasion.
- Supply-chain and raw-material sensitivity: PFS depends on porcine-derived plasma or blood proteins, which makes supply resilience and validated virus-inactivation processes critical risk factors. Buyers and regulators are increasingly weighting supplier biosafety controls as a procurement criterion.
- Clinical adoption maturity: Accumulating clinical evidence across general surgery, cardiovascular, orthopedics, and neurosurgical indications has shifted the conversation from “does it work?” to “which product and which delivery format fits our workflow and price-point?”
For decision-makers planning 2026 initiatives — whether market entry, geographic expansion, or portfolio rationalization — these dynamics mean that the window for securing preferential hospital listing, early reimbursement terms, and clinician champions is immediate and finite.
Practical, Actionable Insights Contained in the PW Consulting Report
This study is designed as an operational playbook as much as an industry report. Key deliverables include:
- Quantitative market model with transparent assumptions: historical actuals (2020–2025) and a scenario‑based forecast (2026–2032) that lets users stress-test growth against alternative uptake, pricing, and reimbursement scenarios.
- Regulatory and reimbursement mapping: country-by-country regulatory considerations, dossier expectations, and practical pathways for securing hospital formulary access and reimbursement engagement.
- Commercial go-to-market toolkit: route-to-market options (direct, distributor, partnership), pricing and contracting playbooks, tender and group purchasing strategies, and best-practice hospital engagement protocols.
- Clinical evidence optimization plan: recommended study designs, registry approaches, and real-world evidence (RWE) strategies to accelerate adoption across key surgical specialties.
- Supply-chain and manufacturing playbook: risk maps for porcine raw-material sourcing, recommendations for virus-inactivation validation, and contingency strategies for scaling production while maintaining biosafety compliance.
- Deal & valuation intelligence: M&A playbook, valuation benchmarks, and scenario analysis for both strategic and financial buyers operating in a concentrated supplier landscape.
Each module is designed to be directly actionable: annotated checklists, templated negotiation messages, and decision matrices that translate market intelligence into boardroom-ready options.
Regulatory, Safety and Reimbursement Imperatives
Porcine-derived fibrin sealants carry specific regulatory and biosafety requirements. Market authorization in several jurisdictions depends on validated virus-inactivation steps and specific declarations on xenogeneic sourcing. For purchasers and regulators, these controls are non-negotiable and increasingly integral to procurement evaluations.
On the reimbursement side, local catalog inclusions and “green channel” designations can dramatically shorten the time-to-adoption in public hospitals. Companies that secure prioritized listing and early-stage reimbursement negotiation leverage these advantages into rapidly expanding tender access and accelerated clinician exposure.
Competitive Landscape: Profiles and Strategic Readiness
Our competitive analysis evaluates both established incumbents and emergent local players, with attention to commercialization reach, clinical positioning, manufacturing capability, and access achievements.
- Shanghai Haohai Biological Technology Co., Ltd. — Launched Kangrui Gel, a porcine fibrin sealant kit that has shown tangible early market traction, including notable interim-period revenue and prioritized catalog inclusion in select municipal procurement lists. This combination of clinical entry and local market access demonstrates how regional approval plus targeted insurance negotiation can unlock high-velocity adoption.
- Guangzhou Bioseal Biotech Co., Ltd. (now aligned with a global medtech sponsor) — The affiliation with a global strategic partner brings scale, distribution reach, and accelerated regulatory know‑how. Products with virus-inactivation claims and neurosurgical/dural closure evidence are positioned to seek premium clinical adoption windows.
- Guangzhou Beixiu Biotechnology Co., Ltd. and Guangzhou Baisew Biological Technology Co., Ltd. — These suppliers represent the domestic competitive base offering multiple delivery formats and clinical use-cases. Their advantages typically lie in local relationships, cost-competitive pricing, and flexible supply arrangements for institution-level needs.
Across the competitive set, differentiation is driven less by the basic mechanism of action and more by delivery format (ease-of-use within an OR workflow), documented safety (virus-inactivation validation), and market access (catalog listings, tenders, and distributor relationships).
Strategic Plays for 2026
- Prioritize market-access execution. Firms that convert regulatory approvals into formalized hospital access (catalog listings, reimbursement negotiation slots) will capture disproportionate early demand.
- Invest in biosafety and supply resilience communications. Demonstrable virus-inactivation validation and transparent raw-material controls are now table-stakes in procurement evaluations; publicizing these controls reduces adoption friction.
- Align clinical evidence to purchaser pain-points. Short, pragmatic RWE studies that show OR time-savings, reduced transfusion rates, or shortened length-of-stay will outperform large, costly superiority trials in driving hospital formulary decisions.
- Segment GTM by buyer economics. National tenders, private hospital group deals, and high-volume surgical centers require different contracting templates — tailor offers to margin expectations and buying cadence.
- Prepare M&A and partnership optionality. Given the market concentration dynamics, strategic partnerships or carve‑outs can be the most efficient route to scale outside of organic growth.
Risks and Mitigations
Key downside scenarios include raw-material shocks, increased regulatory scrutiny on xenogeneic products, and price competition compressing margins. Mitigations include diversified sourcing, proactive engagement with regulators on virus-inactivation protocols, and the development of bundled clinical-service offerings that justify premium pricing (e.g., training, OR efficiency guarantees, and warranty-like safety assurances).
How PW Consulting’s Report Helps Executive Teams in 2026
Executives will find the report valuable for three immediate uses:
- Strategic planning: Integrate our scenario-based forecast into corporate budgets and resource-allocation conversations for product launches or geographic expansions.
- Commercial diligence: Use our go-to-market playbooks and tender negotiation templates to accelerate hospital access and shorten sales cycles.
- Transaction support: Leverage our valuation frameworks and competitive benchmarking for M&A diligence, partnership negotiations, or licensing discussions.
We intentionally present high-resolution strategic guidance while reserving detailed segment-level tables and per‑region / per‑application breakdowns for the full report—these are essential for operational execution and are accessible through our client portal.
Closing Recommendation
Porcine fibrin sealants represent a growth segment with predictable drivers: clinical evidence consolidation, targeted market access wins, and supply-chain security. For 2026, the decisive advantage will go to organizations that translate approval into access — securing catalog listings, validated biosafety credentials, and pragmatic clinical evidence that aligns with hospital purchasing criteria.
PW Consulting’s Worldwide Porcine Fibrin Sealant (PFS) Market report packages these insights with executable templates, scenario models, and supplier-level analysis to support board-level decision-making. For teams preparing 2026 budgets, tender strategies, or M&A plays, the report converts market intelligence into action plans designed to capture share in a concentrated, high-growth environment.
Next Steps
Contact PW Consulting to request the full report and unlock the detailed per‑segment sizing, regional and application splits, primary interview transcripts, and our downloadable financial model tailored for corporate planning and M&A diligence.
For detailed analysis of this topic, please visit the official page: Worldwide Porcine Fibrin Sealant (PFS) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Worldwide Complicated Urinary Tract Infections Treatment Market Set to Grow at a 6.5% CAGR, New Report Reveals
By pmarketresearch, 2026-08-12
PW Consulting Strategic Brief: Navigating the Worldwide Complicated Urinary Tract Infections (cUTI) Treatment Market — Tactical Priorities for 2026
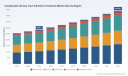
As health systems, pharmaceutical executives, and investors set strategic plans for 2026, our new Worldwide Complicated Urinary Tract Infections Treatment Market report (base year 2025, historical 2020–2025, forecast 2026–2032) delivers a decision-grade view of an evolving therapeutic landscape. The market is on a steady upward trajectory — rising from approximately USD 2,555 million in 2023 to USD 2,850.5 million in 2025 and projected to reach about USD 4,429.6 million by 2032 at a compound annual growth rate (CAGR) of 6.5% over the forecast window. This trajectory reflects a mix of clinical innovation, shifting care settings, and persistent antimicrobial resistance pressures that together create near- and medium-term opportunities — and operational risks — for incumbent manufacturers and new entrants alike.
Worldwide Flight Reservation System Market
Why this report matters for 2026 decision-making
-
Actionable clarity on growth drivers and inflection points: Our analysis translates epidemiology, prescribing signals, and payer levers into tactical timing for launches, label extensions, and formulary negotiations.
Worldwide Permit Software Market -
Forward-looking scenario analysis calibrated to 2026 resource cycles: The report models multiple adoption curves (conservative, base, accelerated) for oral and IV assets, enabling finance teams to stress-test revenue plans and to identify breakpoint years for ROI.
Worldwide Renewable Energy Technology Market -
M&A and licensing playbooks: We identify categories and subsegments where clinical differentiation, regulatory exclusivity, or scarcity of supply can materially increase asset value — crucial for deal teams preparing 2026 pipelines and budgets.
Market trajectory: what the numbers conceal and reveal
The headline growth rate (6.5% CAGR, 2026–2032) packages heterogeneous dynamics. On the demand side, an aging population, higher hospitalization rates for complicated infections, and heightened surveillance for multidrug-resistant organisms sustain baseline volume growth. On the supply side, clinical innovation — including next-generation beta-lactam/beta-lactamase inhibitors, oral carbapenems in late-stage development, and targeted combination therapies — is expanding treatment options and shifting care pathways toward outpatient and step-down models.
However, beneath the aggregate growth are differentiated pockets of margin pressure and tactical opportunity: pricing and reimbursement variability across healthcare systems, the economics of hospital stewardship programs, and the timing of patent cliffs and generic entries that will reallocate value between branded players and generic manufacturers. Our report maps these drivers against a robust financial model that translates epidemiology into revenue sensitivities for 2026 planning.
Competitive landscape — strategic takeaways (not a roster of figures)
The cUTI space is a mix of global pharmaceutical leaders with established antibacterial franchises, small- and mid-cap biotechs advancing novel oral or combination approaches, and regional players focused on formulary penetration within hospitals. Key archetypes and strategic postures emerge:
-
Large integrated pharmas (portfolio defense and lifecycle management): Companies with marketed cephalosporin and beta-lactam combination products are prioritizing lifecycle extensions, label expansions into high-unmet-need subpopulations, and formulary access strategies that emphasize stewardship collaboration with hospitals.
-
Specialist biotech contenders (clinical differentiation and regulatory incentives): Smaller developers pursuing oral carbapenem prodrugs and novel combination therapies are leveraging designations such as QIDP to accelerate regulatory pathways and create near-term exclusivity windows that are valuable to licensing and partnership discussions.
-
Hospital-centric suppliers and generics players (volume and margin play): Distribution-to-hospital models remain central for severe cUTIs, while generics entrants are preparing to monetize patent expiries over the medium term, pressuring pricing trajectories unless mitigated by differentiated clinical data or contracting strategies.
Strategically, incumbents should prioritize defensible assets (e.g., products with demonstrated activity against critical MDR pathogens, strong PK/PD profiles, or compelling step-down oral options), while potential entrants should target regulatory incentives and fast-to-market tactics (partnerships, small indication entries, and targeted hospital campaigns).
Recent developments shaping 2026 priorities
-
Regulatory milestones and approvals have changed therapeutic options available to clinicians, and several recent approvals underscore how regulation can re-order competition and formulary positioning within months.
-
Late-stage clinical readouts for oral agents — including Phase 3 positive topline results announced recently — signal a potential shift from inpatient-only regimens to more outpatient-capable therapies, with meaningful implications for distribution strategy and payer negotiation.
-
Reimbursement updates in major public payers and formulary decisions are already influencing prescribing behavior, and our report models the near-term impact of common payer outcomes on revenue and access.
Regulatory, reimbursement, and patent landscape — implications for 2026 planning
Regulatory incentives such as QIDP designation materially shorten timelines and grant exclusivity corridors that should be central to commercial valuation models. Parallelly, recent decisions by European and U.S. regulators to approve targeted combination agents for limited-use indications demonstrate how regulators balance unmet need against stewardship concerns. For 2026 planning, companies must integrate regulatory timelines, anticipated exclusivity periods, and known patent expiry windows into launch sequencing and repricing scenarios.
Reimbursement dynamics differ by market: coverage decisions and tier placements materially impact uptake in outpatient settings. Our report includes payer decision trees and formulary negotiation playbooks tailored to 2026 budget cycles, identifying which evidence packages and real-world data strategies are most likely to secure favorable access.
Supply chain and operational risks
The cUTI market is sensitive to API availability and manufacturing complexity. Our analysis highlights recent disruptions — including reported shortages of specific beta-lactam APIs — and quantifies the potential commercial impact of supply interruptions and lead-time elongation. For supply chain and operations teams preparing 2026 budgets, the report includes a supplier-risk heat map, mitigation options (dual sourcing, contract manufacturing strategies), and cost implications for inventory strategies aligned to demand volatility.
What’s inside the report — practical, executable content
-
Comprehensive market sizing and forecast model (2020–2032) — scenario-enabled for stress testing through 2026 planning cycles.
-
Granular go-to-market playbooks for hospital and outpatient channels, including contracting, stewardship alignment, and value demonstration templates.
-
Competitive and pipeline intelligence dossiers on leading global players and high-priority biotech assets, with tactical recommendations for partnering, in-licensing, and M&A prioritization.
-
Payer and health-economics frameworks, with sample dossiers and evidence-generation roadmaps to improve formulary positioning in key markets.
-
Operational risk assessments: API and manufacturing supply stress tests, distribution contingencies, and inventory-to-demand optimization levers.
-
Commercial financial model with sensitivity analyses (price, uptake, reimbursement) and a dashboard for board-level scenario briefings.
How executives should use this analysis for 2026 planning
-
R&D and portfolio leads: Use our exclusivity calendars and clinical-readout scenarios to determine which assets should be accelerated, paired, or deprioritized for 2026 filings or partnerships.
-
Commercial teams: Leverage our go-to-market templates to build differentiated hospital access strategies and to prepare value dossiers targeted to expected payer objections during 2026 negotiations.
-
Finance and strategy: Apply the report’s scenario model to capital allocation, M&A valuation caps, and contingency reserves for supply-chain shocks.
-
Supply chain and manufacturing: Implement the report’s supplier risk mitigations and contract manufacturing playbook to maintain continuity through potential API shortages.
Final perspective — an invitation to deeper intelligence
The cUTI treatment market presents a classic combination of steady aggregate growth and localized structural disruption. Learning where clinical innovation intersects with payer pragmatism and supply constraints is essential for converting the 6.5% CAGR into durable commercial returns. PW Consulting’s report equips leaders with the models, playbooks, and tactical intelligence needed to make high-conviction decisions for 2026 and beyond.
For full tables, segment-level forecasts, and the downloadable financial model that underpin these strategic recommendations, please access the full report on the PW Consulting report page or contact our advisory team for a tailored briefing. The executive summary and selected graphical outputs are publicly available; the granular segmentation, modeled scenarios, and deal-ready annexes are reserved for report subscribers and advisory clients.
For detailed analysis of this topic, please visit the official page: Worldwide Complicated Urinary Tract Infections Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Peeling Machines Market to Expand at 5.45% CAGR, Reaching USD 557.46 Million by 2032
By pmarketresearch, 2026-08-12
Worldwide Peeling Machines Market 2026: A Strategic Briefing for Decision‑Makers
As global food processors confront intensifying pressure to increase throughput, improve hygiene, and reduce labor dependency, the peeling machines market has emerged as a bellwether for capital investment and operational transformation in 2026. PW Consulting’s new Worldwide Peeling Machines Market report — built on a rigorous 2020–2025 historical analysis and a 2026–2032 forecast horizon — frames the commercial opportunities and execution risks that matter most to executives, capital allocators, and equipment OEMs preparing decisions this year.
Fuel Gauging Valve Market
Macro outlook: scale, growth and concentration
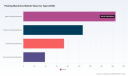
Our analysis positions the worldwide peeling machines market on a structurally positive trajectory. Using 2025 as the base year, the market is sized to reflect industry consolidation, rising automation demand and steady replacement cycles; the forecast through 2032 is driven by a compound annual growth rate (CAGR) of 5.45%. These dynamics underline a market that is large enough to support specialized technology providers and service-focused challengers, yet vibrant with whitespace for adjacent innovation.
Worldwide Flight Reservation System Market
Competitive intensity is moderate: market concentration metrics indicate leading firms capture meaningful share while a long tail of regional and niche suppliers remains active. For buyers and investors, this configuration creates both margin compression risks for commodity offerings and premium opportunities for differentiated systems and lifecycle services.
Worldwide Semiconductor Glass Market
Why this report matters for 2026 decisions
- CapEx prioritization under uncertainty: Food processors must decide whether to retrofit, expand, or build new processing lines. Our report provides modeling that links peeling technology choices to plant-level throughput, yield, and lifecycle OPEX, enabling finance teams to quantify payback windows under multiple labor and material‑cost scenarios.
- Technology selection with downstream impact: Knife, abrasive, steam and sensor-driven peelers differ materially in yield, waste profile and cleaning regimes. Choosing a suboptimal technology can cascade into higher product losses, longer line downtimes and compliance challenges—particularly under stricter hygienic design standards.
- Supply‑chain and procurement risk management: Raw material cost dynamics, notably food‑grade stainless steel pricing and availability, are an increasingly significant input to equipment unit economics. The report integrates recent pricing signals and vendor lead‑time trends to inform procurement timing and hedging strategies.
- M&A and partnership scenarii: With a mid-range industry concentration and accelerating automation adoption, strategically timed acquisitions or partnerships can rapidly expand capabilities (e.g., sensor/laser sorting, ultrasonic peeling) and service footprints. Our deal‑level playbook highlights criteria and red flags for investors active in 2026.
What the report contains: practical, actionable content
- Executive dashboards that translate market growth and volatility into decision metrics for CFOs, plant managers and CTOs.
- Plant-level ROI templates that compare retrofits versus greenfield installations across multiple product profiles and throughput bands.
- Supplier scorecards and negotiation scripts tailored to different buyer personas (large CPG, fresh‑cut processors, foodservice aggregators), including TCO and service performance KPIs.
- Technology roadmaps showing adoption timing for sensor-based sorting, ultrasonic peeling, and integrated washing/peeling lines—paired with practical retrofitting pathways.
- Risk heatmaps covering raw-material price exposure (stainless steel), regulatory shifts in hygienic design, and labor-market tightness by processing segment.
- Competitive landscape intelligence with strategic profiles and capability matrices for the leading OEMs, plus an M&A playbook identifying attractive bolt-on technologies.
- Validation appendices summarizing primary research: vendor interviews, factory visits, procurement tenders, and end‑user surveys.
Competitive landscape—how to interpret vendor moves in 2026
The vendor ecosystem combines long‑established OEMs, technology specialists, and regional fabricators. A subset of players focus on high‑throughput industrial lines, while others compete on adaptability and service for professional kitchens and fresh‑cut operations. Notable industry participants demonstrate clear strategic archetypes:
- Integrated systems and automation champions — Vendors combining peeling with advanced sorting, sensing and control systems are positioned to capture higher ASPs and recurring service revenue. Their value proposition centers on throughput optimization and yield improvement for large processors.
- Specialists and niche innovators — Firms introducing ultrasonic peeling, laser/sensor‑guided systems, or purpose‑built peelers for specific fruit types are competing on differentiation; their success depends on demonstrating superior yield and lower lifecycle costs.
- Regional and service-led providers — Smaller OEMs and local engineering houses win on responsiveness, spare‑parts availability and installation support, especially where local regulations and supply chain constraints favor proximity.
Recent market activity underlines these trends. For example, visible product launches and trade‑show demonstrations in late 2025 and early 2026 showcased both performance innovations and targeted industrial deployments. Such events are effective near‑term indicators of product maturation and commercialization readiness, signaling where early adopter demand will concentrate in 2026.
Practical recommendations for each stakeholder
- For food processors: Prioritize systems that reduce total yield loss rather than lowest upfront price. Insist on vendor-provided empirical yield and downtime metrics and secure service-level agreements tied to throughput outcomes. If stainless steel input costs are a meaningful line-item in your capex, consider staged procurement or price‑capture clauses to reduce exposure.
- For OEMs: Invest in modular, serviceable designs that facilitate field upgrades (sensor modules, software upgrades), and build aftermarket capabilities—remote monitoring and predictive maintenance have become differentiating profit centers.
- For investors and M&A teams: Target companies that combine a credible technology moat (e.g., sensor fusion, ultrasonic tooling) with a scalable service model. Expect attractive consolidation arbitrage in high‑volume segments where integration creates cross‑sell and spare‑parts synergies.
- For procurement and operations leaders: Map spare‑parts lead times and establish multi‑sourcing for critical wear components. Align specifications with hygienic design requirements so regulatory compliance does not become a retrofit cost later in the asset lifecycle.
Sector dynamics and material context
Three structural forces are shaping the market in 2026:
- Automation to address labor scarcity: Demand for higher-capacity, easy‑to‑operate peelers is rising as processors cope with tighter labor markets. Automation reduces dependence on skilled operators and improves line consistency.
- Hygienic design and compliance: Increasing food‑safety requirements make food‑grade stainless steel and cleanable designs non‑negotiable. This reality affects both equipment specification and supplier selection.
- Input‑cost vigilance: Stainless steel remains the dominant construction material; recent pricing and supply signals—reflecting regional alloying costs and steady industrial demand—should be evaluated when timing capital orders and negotiating contracts.
Methodology and confidence framework
The report synthesizes quantitative market sizing (historical 2020–2025, forecast 2026–2032) with qualitative primary research. Our methodology includes vendor revenue triangulation, equipment shipment analysis, OEM and end‑user interviews, and observed pricing from tenders and trade events. To ensure conservative forecasting, we stress‑test growth paths under alternative macro scenarios and provide scenario outputs that feed the ROI templates in the report.
What we intentionally hold back — and why you should read the full report
Following the “trailer” principle, this briefing presents the strategic implications and high‑level metrics you need to shape 2026 decisions, while withholding detailed segmentation tables, regional and application‑level share data, unit price curves, and the full supplier scorecard. These granular datasets and downloadable models are the core deliverables of the full report and are critical if you intend to:
- Validate a specific retrofit or greenfield investment using plant‑level inputs;
- Prioritize vendors by detailed capability and cost comparisons in your target region;
- Run an M&A diligence on prospective targets with fully populated financial scenarios and sensitivity analyses.
Next steps
If you are planning capital expenditure, supplier consolidation, or a technology pilot in 2026, PW Consulting’s full Worldwide Peeling Machines Market report contains the models, validated benchmarks and vendor intelligence necessary to move from strategy to execution with confidence. Contact our team to access the complete dataset, segmented market maps, and the executable playbooks that underpin the recommendations in this briefing.
In an environment where small choices in peeling technology can translate into meaningful differences in yield, compliance and lifetime cost, decision‑makers who combine data‑driven procurement criteria with a service‑centric vendor strategy will capture the greatest value as the market advances through 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Peeling Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts 5.48% CAGR for Worldwide Charge Plate Monitor Market During 2026–2032
By pmarketresearch, 2026-08-12
Worldwide Charge Plate Monitor Market: Strategic Imperatives for 2026 — PW Consulting Release
Executive summary
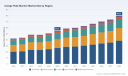
PW Consulting’s latest market intelligence on the Worldwide Charge Plate Monitor market delivers a concise, practitioner-focused view that senior leaders can use to align 2026 investment, sourcing, and compliance decisions. Our modelling shows the global market expanding from a 2025 baseline of USD 55.21 Million to an expected USD 80.22 Million by 2032, representing a compound annual growth rate (CAGR) of approximately 5.48% over the 2026–2032 forecast window. This trajectory is driven by steady demand in electronics manufacturing, cleanroom-controlled sectors such as medical devices and life sciences, and ongoing regulatory scrutiny of ionization performance in ESD-protected environments.
Worldwide Direct Deposit Payroll Software Market
Why this report matters for 2026 decision-makers
Charge plate monitors (CPMs) play a tactical yet high-leverage role in electrostatic discharge (ESD) programs: they convert ionizer performance into auditable metrics that inform quality, yield, and compliance. For procurement heads, plant managers, and EHS/quality leads, the 2026 strategic questions are straightforward but consequential—how to cost-effectively validate ionization performance across distributed production sites, how to incorporate CPM metrics into ESD audit cycles, and how to balance investments between portable field tools and integrated benchtop systems. Our report synthesizes hard market sizing, regulatory drivers, supplier capability maps, and deployment playbooks so that those stakeholders can move from reactive troubleshooting to proactive control.
Worldwide Compensation Management Software Market
What the analysis delivers (practical modules)
- Market sizing and trend analysis — longitudinal view from 2020 through 2025, and forward-looking forecasts across 2026–2032 with scenario sensitivity to adoption and regulatory tightening.
- Regulatory and standards alignment — pragmatic interpretation of ANSI/ESD STM3.1 and ANSI/ESD SP3.3 implications for ionizer verification and EPA auditing, including application-specific checklists for medical device cleanrooms.
- Technology and product taxonomy — clear differentiation between portable/collapsible CPMs optimized for field audits versus benchtop systems designed for continuous verification and R&D labs.
- Competitive landscaping — vendor profiles, capability benchmarking, go-to-market vectors, and a market concentration assessment to support supplier risk management.
- Procurement playbook — total cost of ownership templates, RFx guidance, evaluation criteria, and contract clauses to protect IP and calibration integrity.
- Implementation playbook — sample audit schedules, instrument placement heuristics, data capture and reporting templates for integrating CPM outputs into quality management systems.
- Investment and M&A lens — decision heuristics for capex vs. opex purchase models and signals for potential vendor consolidation or acquisition targets.
Market dynamics and regulatory context
Three structural forces underpin the market outlook for 2026:
Worldwide Liquid Optically Clear Adhesive (LOCA) Market
- Standards-driven verification: Charge plate monitors are the industry-accepted method for verifying ionizer balance and discharge times in accordance with ANSI/ESD STM3.1. In ESD Protected Areas, referencing ANSI/ESD SP3.3 is becoming routine in supplier audits and internal compliance checks.
- Sectoral demand concentration: High-sensitivity manufacturing—particularly electronics, semiconductor packaging, and medical device production—continues to prioritize ESD validation as a low-cost insurance against yield loss and field failures. Cleanroom environments require specific protocols that drive demand for portable, easy-to-deploy CPMs for on-the-floor verification.
- Product form-factor innovation: Portable and collapsible designs (for example, compact 6-inch plate configurations with defined capacitance characteristics) are gaining traction because they allow auditors to carry complete ESD kits between lines and remote sites without forfeiting measurement fidelity.
Competitive landscape — what buyers need to know
The market demonstrates moderate concentration: the top three suppliers hold a meaningful share of accessible market value, and the top five account for a majority. This creates both opportunities and risks for buyers—scale benefits from established vendors are real, but supplier concentration also concentrates calibration and spare-part risk.
- Advanced Energy (Trek/Monroe) — Known for active CPMs such as models in the Trek and Monroe families, this supplier emphasizes instrument accuracy for evaluating air ionization systems and measuring both offset voltage and discharge time. Strengths: recognized technical pedigree, broad instrument portfolio, and deep validation tooling for ESD control applications. Buyer implication: strong technical fit for R&D and critical production lines, but buyers should evaluate service coverage and calibration turnaround times regionally.
- Simco-Ion, Technology Group — Offers CPMs with programmable automated testing and explicit support for multiple ionizer types (high-frequency AC, pulsed DC, steady-state DC). Strengths: automated testing workflows and clear positioning against ionizer evaluation in high-throughput environments. Buyer implication: suitable for operators seeking repeatable, standardized verification across multiple ionizer technologies; consider integration points with factory automation and audit reporting systems.
- SCS (Desco Industries) — Focused on portable CPMs that address SMT lines and EPA environments. Strengths: simplicity, portability, and channel availability to electronics assemblers. Buyer implication: practical choice for line-level audits and ESD programs where mobility is prioritized; ensure your procurement balances user-friendliness with measurement traceability.
- Transforming Technologies (Warmbier) — Provides CPM instruments and verification meters engineered to meet ANSI/ESD STM3.1 testing regimes. Strengths: instrumentation designed to map directly to standard test methods and technical documentation that aligns with compliance needs. Buyer implication: particularly relevant for regulated manufacturing sectors where standards alignment must be demonstrable during regulatory inspections or supplier audits.
- Prostat Corporation — Offers compact 6-inch CPM assemblies designed for collapsible storage and use in audit kits, compliant with accepted ESD standards. Strengths: ergonomic designs for field auditors and small-footprint storage. Buyer implication: ideal for distributed manufacturing footprints and mobile ESD teams; evaluate longevity of mechanical components in harsh factory environments.
- Static Clean International — Supplies handheld CPM instruments oriented to quick static decay and ionizer balance checks. Strengths: low barrier to entry for small operations and maintenance teams. Buyer implication: effective for fast checks and preventive maintenance but often requires complementary documentation to fulfill audit traceability requirements.
Strategic recommendations for 2026
- Embed CPM metrics into quality KPIs: Convert discharge-time and offset voltage outputs into leading indicators for yield and contamination risk. Use a centralized dashboard to highlight trends that trigger preventive maintenance or ionizer recalibration.
- Adopt a tiered procurement model: Combine a fleet of portable CPMs for line audits with a smaller number of benchtop units for lab-based verification. This hybrid approach optimizes mobility without sacrificing measurement fidelity for R&D or formal validation tasks.
- Standardize on instrument traceability: Require supplier calibration records, turnaround SLAs, and secure calibration certificates as part of contracts. Consider local calibration partners in regions with high manufacturing concentration to reduce downtime risk.
- Rationalize vendor portfolio with a focus on service: With moderate market concentration among leading suppliers, prioritize vendors that can offer regional service, rapid calibration, and integration support over those that compete on price alone.
- Plan for regulatory scrutiny in regulated verticals: Medical device and life sciences manufacturers should formalize CPM-based audit templates that directly cite ANSI/ESD STM3.1 and SP3.3 test steps to expedite supplier qualification and regulatory submissions.
- Monitor product innovation and consolidation signals: The relatively compact market size and concentration create fertile ground for acquisition activity—purchasers and integrators should watch for emerging bundled offerings that combine CPM hardware, automated testing routines, and cloud-backed audit repositories.
Research methodology and limitations
PW Consulting’s market model triangulates primary interviews with procurement and ESD program leads, supplier public disclosures, product specifications, and an extensive review of industry standards. Forecasts incorporate base-year data through 2025 and apply scenario-driven assumptions to 2032. As part of our “trailer” approach, this release presents headline market sizing, growth trajectories, and concentration metrics to guide 2026 planning. Detailed segment tables, region-specific drivers, and vendor market-share breakdowns are intentionally withheld from this summary to preserve the actionable value of the full report.
Concluding note — how to use this intelligence
For executives preparing 2026 budgets and operational plans, the CPM market offers a pragmatic efficiency play: modest capital outlays in monitoring capability yield outsized improvements in yield protection, regulatory resilience, and audit-readiness. PW Consulting’s full Worldwide Charge Plate Monitor Market report provides the granular segmentation, supplier scorecards, deployment templates, and downloadable audit tools needed to operationalize the recommendations in this release. To obtain the complete dataset, supplier-level market shares, and the FTP-ready implementation kit, please visit our report page.
For detailed analysis of this topic, please visit the official page: Worldwide Charge Plate Monitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Hotel Market to Expand at 6.5% CAGR, New Insights Reveal
By pmarketresearch, 2026-08-12
Worldwide Hotel Market 2026: Strategic Imperatives from PW Consulting’s Market Intelligence
As global travel rebounds beyond pandemic-era constraints, hotel industry stakeholders face a window of strategic opportunity — and complexity. PW Consulting’s new Worldwide Hotel Market report (base year 2025) synthesizes five years of historical performance (2020–2025) and delivers an actionable forecast through 2032. Anchored by a 6.5% compound annual growth rate (CAGR) and a global market base of USD 1,230.0 Billion in 2025, the study maps where value will accumulate, what disruptors will matter most, and how investors, operators, franchisors, and lenders should reposition for 2026 decision cycles.
Intra-Array Submarine Cable Market
Market Snapshot: Scale, Trajectory, and What It Means for 2026
By 2025 the worldwide hotel economy reached a substantively larger scale compared with the early-2020 landscape, reflecting stronger RevPAR recovery and renewed corporate travel. Under a central-case trajectory, the market is projected to expand at a 6.5% CAGR across 2026–2032, with PW Consulting’s modelling pointing to nearly double-digit expansion in aggregate value by 2032. For executives planning capital allocation, talent deployment, or brand expansion in 2026, this macro envelope creates a portfolio of choices — accelerate pipeline and capture share in growth corridors, or defend margins via operational efficiency and direct-booking capture.
ADHD Management Software Market
What the Report Contains (Practical, Hands-on Tools)
- Forward-looking market sizing and scenario forecasts (2026–2032) with sensitivity analysis across demand, pricing, and supply shocks.
- Actionable playbooks for asset owners and operators: conversion vs new-build decision matrices, franchise negotiation checklists, and a CapEx prioritization framework.
- Commercial performance toolkits: RevPAR sensitivity models, dynamic pricing levers, channel-mix optimization templates, and loyalty-program monetization playbooks.
- Regulatory and distribution primer: implications of digital pricing disclosure rules, OTA commission dynamics, and strategies to reclaim direct demand.
- Talent and operations playbook: workforce planning templates, outsourcing vs insourcing decision aids, and automation ROI calculators for front- and back-of-house functions.
- Investment and M&A scanner: deal-screen scorecards, valuation stress-tests under rising construction and labor costs, and integration readiness checklists.
- Regional and segment strategy briefs (available in full report): growth corridors, demand archetypes, and prioritized go-to-market tactics — presented without divulging proprietary granular splits in this release.
- Data appendices and model files: downloadable Excel models and a documented methodology to replicate key scenarios for portfolio-level decision-making.
Competitive Landscape: Who’s Moving — and How to Read Their Moves
The global hotel market remains structurally fragmented, with leading chains expanding distribution while an active base of asset-light franchisors and independent operators compete on niche experiences and cost advantage. The report profiles the sector’s major platform players and synthesizes recent strategic actions to distil playbook insights for 2026.
Worldwide Machine Glazed Uncoated Paper Market
- Marriott International (Bethesda, Maryland, USA) — Marriott continues to press growth through a hybrid approach of new openings and brand depth. Their late‑2025 expansion added substantial room inventory with a pronounced focus on Asia‑Pacific and the Middle East. Strategic takeaway: Marriott’s scale advantage and brand architecture enable rapid market share capture in growth corridors, but investors should assess conversion economics versus greenfield returns in markets with rising construction costs.
- Hilton Worldwide (McLean, Virginia, USA) — With the November 2025 launch of a midscale conversion brand, Hilton is honing conversion-first growth in mature markets. Strategic takeaway: midscale conversions present faster ROI and reduced construction exposure; but success depends on backend distribution and loyalty integration.
- InterContinental Hotels Group (Denham, UK) — IHG’s partnership pipeline emphasizes luxury and lifestyle projects in Europe. Strategic takeaway: co‑development partnerships with institutional real estate managers lower capital intensity for brands while enabling access to premium city-center assets — an essential model for competing where construction and labor inflation compress margins.
- Wyndham Hotels & Resorts (Parsippany, New Jersey, USA) — Focused on asset-light franchise growth, Wyndham’s expansion in India and Southeast Asia underscores the opportunity in economy and midscale conversions. Strategic takeaway: franchise-heavy models are resilient to capex shocks but require robust quality-control and brand-support economics.
- Accor (Issy‑les‑Moulineaux, France) — Accor’s recent openings in Asia and Latin America reflect a dual strategy of market diversification and brand layering. Strategic takeaway: multi-brand portfolios can extract yield across trip purposes, but require disciplined channel strategies to avoid cannibalization.
- Hyatt Hotels Corporation (Chicago, USA) — Hyatt’s emphasis on lifestyle and all-inclusive formats positions it to capture premium leisure rebounds and extended-stay demand. Strategic takeaway: lifestyle is brand-differentiated but asset-intensive; partnerships and management agreements lower balance-sheet exposure.
- Choice Hotels International (Rockville, Maryland, USA) — Primarily franchising in North America, Choice’s model benefits from steady domestic business and leisure flows. Strategic takeaway: domestic consolidation and conversion pipelines are key levers to sustain unit growth in mature markets.
- Radisson Hotel Group (Brussels, Belgium) — Radisson’s global footprint focuses on brand refresh and selective growth. Strategic takeaway: mid-sized international platforms can out-maneuver big chains in tertiary cities with tailored offerings and nimble franchise economics.
Across these competitors, two common strategic moves warrant attention in 2026: accelerating conversion pipelines to mitigate construction inflation, and using brand architecture to segment demand without eroding loyalty returns.
Macro and Operational Headwinds: What to Price into 2026 Plans
- Regulatory friction in distribution: Digital pricing transparency regulations are reshaping OTA economics and increasing the value of direct-booking channels. Operators must reconfigure channel commissions and direct incentives accordingly.
- Labor market pressures: U.S. hotel labor costs rose materially in 2025, reflecting wage inflation and staffing shortages. Workforce productivity improvements and targeted automation will be core margin levers.
- Construction and capex inflation: Material costs rose across 2025, compressing new-build economics and shortening payback horizons. Conversion strategies and refurbishment-first approaches are commercially compelling.
- Revenue recovery pattern: Global RevPAR improved in 2025 amid international travel normalization. However, demand composition is shifting — leisure remains robust while business travel is reaccelerating, driven by corporate spend recovery.
- Business travel tailwinds: Corporate travel spending is rebounding strongly, driving an incremental demand pool that benefits upper-midscale to premium inventory and group business segments.
Strategic Priorities for Decision-Makers in 2026
- Prioritize conversion-capable assets: Where construction inflation compresses new-build returns, conversions and soft-refurbishments produce faster time-to-market and improved IRR profiles.
- Rebalance commercial mix toward direct relationships: Invest in loyalty, CRM, and direct-booking propositions to mitigate OTA share and to capture richer guest data for personalization.
- Embed workforce strategies into operating budgets: Design flexible labor models, invest in multi-skill training, and apply automation where guest experience is not degraded.
- Stress-test pipelines under capex inflation: Use scenario-based valuations that include rising material and labor inputs; consider JV structures or management-led growth to de-risk balance sheets.
- Monetize ancillary revenue: Capture incremental revenue via F&B enhancements, meetings & events optimization, subscription and membership products, and integrated local experiences.
- Adopt a modular sustainability lens: Prioritize energy and water efficiency upgrades with clear payback thresholds to reduce operating costs and meet evolving ESG expectations.
- Design M&A with integration checklists: Target bolt-on asset clusters for synergies in procurement, channel management, and centralized services rather than one-off trophy assets.
Why PW Consulting’s Report Is Strategic for 2026 Decisions
Executives use our market study not just for high-level validation but as a practical decision-making toolkit. The report couples a robust macro forecast (anchored by a 6.5% CAGR through 2032) with granular scenario models, operator playbooks, and transaction-focused analytic templates. It exposes where economics are shifting, quantifies sensitivity to distribution and cost shocks, and provides the operational checklists that translate strategy into implementation.
To honor the trailer principle and protect proprietary modeling, this summary intentionally omits the report’s detailed regional and application splits and the full company-level data appendices. Subscribers and clients receive the complete datasets, interactive model files, and bespoke strategy workshops that convert insights into executable 100‑day plans and three‑year roadmaps.
Next Steps: How to Use These Insights
- For investors: request the deal-screen pack to stress-test target assets under capex and labor inflation scenarios.
- For operators and brands: deploy the conversion decision matrix and the loyalty monetization toolkit to accelerate market share capture with limited capex.
- For lenders and asset managers: use the RevPAR sensitivity models and covenant-ready scenario outputs to align finance structures with operational realities.
PW Consulting is scheduling a limited series of 2026 advisory workshops to walk clients through baseline and downside scenarios, partner matching for conversion pipelines, and implementation playbooks customized to portfolio risk tolerances. For access to the full report, the data appendices, and our model files — including the regional and segment-level breakdowns not presented here — visit PW Consulting’s Worldwide Hotel Market page or contact our research team to arrange a briefing.
In an environment of rising costs and returning demand, 2026 will reward participants who act with analytic rigor, operational discipline, and agile portfolio design. PW Consulting’s report equips leaders to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Hotel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Agar Resin Market Forecast to Hit USD 580.04 Million by 2032 on a 9.24% CAGR
By pmarketresearch, 2026-08-12
Worldwide Agar Resin Market — Strategic Outlook for 2026: Executive Trailer
Executive summary
The global market for agar resin is at an inflection point. After steady expansion through the early 2020s, total industry revenue reached USD 312.45 Million (USD Million) in the base year 2025. Our forecast model, driven by demand acceleration in biopharmaceutical purification, diagnostics and advanced research applications, projects the market to exceed USD 580.04 Million by 2032 — a compound annual growth rate (CAGR) of 9.24% across the 2026–2032 forecast window. This trajectory reflects a mix of volume growth, upward pricing pressure for higher-purity grades, and incremental value capture from specialty resin formulations and services.
Sterile Surgical Impervious Drape Market
For senior executives making capital, sourcing, product and M&A decisions in 2026, the implications are immediate: supply-side resilience and technology differentiation matter as much as near-term demand signals. Our report translates market-scale dynamics into operational levers and board-level options without compromising commercial confidentiality; the detailed segment-level metrics, vendor scorecards and financial models are reserved for report subscribers.
Worldwide Public Works Software Market
Why this report matters for 2026 decision-makers
- Actionable foresight: We convert top-line growth and sector momentum into short- and medium-term decision frameworks — from procurement hedging and capacity timing to product roadmaps and price-setting strategies.
- Risk-to-reward clarity: The market is growing, but raw-material volatility and concentrated supplier networks introduce asymmetric risks. We quantify these exposures and present mitigations tailored to corporates, private equity sponsors and strategic suppliers.
- Competitive intelligence for dealmakers: The industry’s competitive footprint shows meaningful concentration at the top end; our CR analysis identifies where consolidation will be accretive and where niche players can sustain premium positions.
What the core report delivers (practical content highlights)
- Demand & revenue model — transparent, auditable Excel workbooks that reconcile historicals (2020–2025) and provide probabilistic forecasts (2026–2032) by price tier and end-usage class.
- Supply-chain mapping — farm-to-resin flowcharts, supplier capacity maps, yield assumptions, SKU-level conversion economics and a supplier credit / quality risk scoring template.
- Cost and margin engine — bottom-up manufacturing cost models (feedstock, utilities, labor, waste management) that allow scenario testing for unit economics under different feedstock price regimes.
- Procurement playbook — contracting templates (fixed-price, index-linked, CPI-linked), inventory strategies, and hedging triggers suitable for mid-sized producers and large purchasers alike.
- Regulatory & quality checklist — consolidated GMP and pharmacopeia implications for agar/agarose grades used in biopharma and diagnostics, with a roadmap for certification and audit preparedness.
- Commercial go-to-market & pricing toolkit — customer segmentation, value-based pricing matrices, and a field-sales playbook for launching premium resin grades and services.
- M&A and partnership playbook — target screening criteria, integration checklists, synergy quantification templates and a prioritized list of partner archetypes (feedstock growers, specialty bead manufacturers, contract manufacturers and distributors).
- Stress-tested scenarios — four strategic scenarios reflecting demand shocks, feedstock disruption, rapid adoption of sustainable bead technologies, and accelerated capacity additions; each scenario includes operational triggers and contingency plans.
Competitive landscape: who to watch
The industry structure blends long-established agar processors with specialized chromatography-resin manufacturers and vertically integrated suppliers. Market concentration at the top is material: our CR3 and CR5 metrics indicate that the three largest players account for a dominant share of sales and the top five capture a substantial portion of market value. This concentration creates strategic opportunities — and points of vulnerability — for both buyers and challengers.
Inverter Generator Bundle Market
Key corporate profiles included in the report (representative, non-exhaustive):
- Hispanagar S.A. (Burgos, Spain) — a legacy producer focused on high-quality agar and agarose grades suitable for food, bacteriological and bioprocessing uses; strong manufacturing know-how for agarose resin feedstocks.
- Marine Hydrocolloids (Meron Group) (Kochi, India) — significant export-focused capacity for food- and bacteriological-grade agar; a cost-competitive footprint serving global commodity channels.
- B&V srl (The Agar Company) (Italy) — specialist in differentiated formulations and custom grades for microbiology and pharma-adjacent applications.
- PT Agarindo Bogatama & PT Surya Indoalgas (Indonesia) — Indonesian origin producers with integrated sourcing of local seaweed and export-oriented commercial models.
- Global BioIngredients (Doral, FL; manufacturing partnerships in Spain and Mexico) — a supply-focused model combining sourcing partnerships with distribution reach for higher-value agar products used in tissue culture and laboratory applications.
- Bio-Works Technologies AB (Sweden) — developer and manufacturer of agarose-based chromatography resins (WorkBeads) with patented, sustainability-oriented manufacturing routes.
- Agarose Bead Technologies (ABT) (Spain) — a European resin manufacturer investing in capacity expansion and internationalization to serve biopharma purification needs.
Two recent developments illustrate competing strategic vectors: Bio-Works secured a patent for a greener bead-manufacturing method that replaces fossil-derived oils with vegetable oils, creating both differentiation and potential cost-structure benefits for sustainable resin lines; and ABT announced capacity expansion in late 2025, signaling rising downstream demand for agarose resins at scale. These moves underscore the bifurcation between technology-led differentiation and scale-driven cost advantages.
Market dynamics and raw-material risks
Raw-materials sit at the heart of industry economics. While global aquaculture output of macroalgae reached multi‑million-tonne scale in recent years, high-quality Gelidium and Gracilaria feedstocks required for premium agar extraction remain exposed to climatic variability and ocean temperature shifts. In 2025, Asian agar-agar prices experienced upward pressure driven by robust demand from food and pharmaceutical sectors, compressing thin processing margins in commodity channels.
Operational realities include seasonal harvest swings, variable feedstock quality, and working-capital implications from inventory buildup. The report provides a granular risk matrix and mitigation strategies for supply volatility — including supplier diversification thresholds, forward-stocking triggers, and low-capex options for on-shore processing partnerships.
Strategic playbook for 2026 (recommended actions)
- Secure feedstock: Lock in multi-year, index-linked supply contracts with quality clauses, and evaluate minority equity or off-take arrangements with primary growers to stabilize throughput and margin.
- Pursue selective vertical integration: For mid-sized producers, integrating upstream (seaweed cultivation/primary processing) can be value-accretive where logistics are favorable; for large buyers, near-supply ownership reduces exposure to spot price spikes.
- Invest in differentiation: Prioritize R&D for high-purity agarose beads, sustainable bead processes, and formulation IP to capture premium pricing in biopharma and diagnostic segments.
- Time capacity build-outs cautiously: Monitor capex commitments from peers (capacity announcements, patent filings) and use scenario triggers from our model to avoid overbuilding into cyclical price softening.
- Use M&A as a capability play: Target acquisitions that close capability gaps (e.g., specialty bead chemistry, regulatory dossiers, distribution networks) rather than solely seeking incremental volume.
- Adopt adaptive pricing: Implement value-based pricing for specialty grades, and maintain a commodity-pricing ledger for standard grades to preserve margin resilience.
- Prepare regulatory dossiers early: Companies targeting biopharma and diagnostics should complete pharmacopeial alignment and GMP certifications now to avoid multi-year commercialization delays.
How PW Consulting supports your 2026 agenda
We help executive teams convert the insights above into executable programs: bespoke due diligence for transactions, supplier and technology audits, build-versus-buy financial models, pilot planning for new bead technologies, and implementation roadmaps aligned with board-level KPIs. Our subscription to the full Worldwide Agar Resin Market report includes the underlying datasets, vendor scorecards, contract templates, and an interactive scenario model you can use to stress-test strategic choices.
For a concise, board-ready briefing or to purchase the full dataset and modeling suite, please refer to the official report landing page — the detailed segment breakdowns, region- and application-level economics, and vendor-level financials are reserved there to preserve commercial integrity and support confidential decision-making.
For detailed analysis of this topic, please visit the official page: Worldwide Agar Resin Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com