

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Peeling Machines Market to Expand at 5.45% CAGR, Reaching USD 557.46 Million by 2032

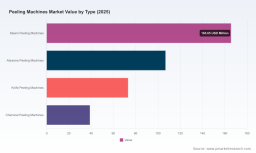
Worldwide Peeling Machines Market 2026: A Strategic Briefing for Decision‑Makers
As global food processors confront intensifying pressure to increase throughput, improve hygiene, and reduce labor dependency, the peeling machines market has emerged as a bellwether for capital investment and operational transformation in 2026. PW Consulting’s new Worldwide Peeling Machines Market report — built on a rigorous 2020–2025 historical analysis and a 2026–2032 forecast horizon — frames the commercial opportunities and execution risks that matter most to executives, capital allocators, and equipment OEMs preparing decisions this year.
Fuel Gauging Valve Market
Macro outlook: scale, growth and concentration
Our analysis positions the worldwide peeling machines market on a structurally positive trajectory. Using 2025 as the base year, the market is sized to reflect industry consolidation, rising automation demand and steady replacement cycles; the forecast through 2032 is driven by a compound annual growth rate (CAGR) of 5.45%. These dynamics underline a market that is large enough to support specialized technology providers and service-focused challengers, yet vibrant with whitespace for adjacent innovation.
Worldwide Flight Reservation System Market
Competitive intensity is moderate: market concentration metrics indicate leading firms capture meaningful share while a long tail of regional and niche suppliers remains active. For buyers and investors, this configuration creates both margin compression risks for commodity offerings and premium opportunities for differentiated systems and lifecycle services.
Worldwide Semiconductor Glass Market
Why this report matters for 2026 decisions
- CapEx prioritization under uncertainty: Food processors must decide whether to retrofit, expand, or build new processing lines. Our report provides modeling that links peeling technology choices to plant-level throughput, yield, and lifecycle OPEX, enabling finance teams to quantify payback windows under multiple labor and material‑cost scenarios.
- Technology selection with downstream impact: Knife, abrasive, steam and sensor-driven peelers differ materially in yield, waste profile and cleaning regimes. Choosing a suboptimal technology can cascade into higher product losses, longer line downtimes and compliance challenges—particularly under stricter hygienic design standards.
- Supply‑chain and procurement risk management: Raw material cost dynamics, notably food‑grade stainless steel pricing and availability, are an increasingly significant input to equipment unit economics. The report integrates recent pricing signals and vendor lead‑time trends to inform procurement timing and hedging strategies.
- M&A and partnership scenarii: With a mid-range industry concentration and accelerating automation adoption, strategically timed acquisitions or partnerships can rapidly expand capabilities (e.g., sensor/laser sorting, ultrasonic peeling) and service footprints. Our deal‑level playbook highlights criteria and red flags for investors active in 2026.
What the report contains: practical, actionable content
- Executive dashboards that translate market growth and volatility into decision metrics for CFOs, plant managers and CTOs.
- Plant-level ROI templates that compare retrofits versus greenfield installations across multiple product profiles and throughput bands.
- Supplier scorecards and negotiation scripts tailored to different buyer personas (large CPG, fresh‑cut processors, foodservice aggregators), including TCO and service performance KPIs.
- Technology roadmaps showing adoption timing for sensor-based sorting, ultrasonic peeling, and integrated washing/peeling lines—paired with practical retrofitting pathways.
- Risk heatmaps covering raw-material price exposure (stainless steel), regulatory shifts in hygienic design, and labor-market tightness by processing segment.
- Competitive landscape intelligence with strategic profiles and capability matrices for the leading OEMs, plus an M&A playbook identifying attractive bolt-on technologies.
- Validation appendices summarizing primary research: vendor interviews, factory visits, procurement tenders, and end‑user surveys.
Competitive landscape—how to interpret vendor moves in 2026
The vendor ecosystem combines long‑established OEMs, technology specialists, and regional fabricators. A subset of players focus on high‑throughput industrial lines, while others compete on adaptability and service for professional kitchens and fresh‑cut operations. Notable industry participants demonstrate clear strategic archetypes:
- Integrated systems and automation champions — Vendors combining peeling with advanced sorting, sensing and control systems are positioned to capture higher ASPs and recurring service revenue. Their value proposition centers on throughput optimization and yield improvement for large processors.
- Specialists and niche innovators — Firms introducing ultrasonic peeling, laser/sensor‑guided systems, or purpose‑built peelers for specific fruit types are competing on differentiation; their success depends on demonstrating superior yield and lower lifecycle costs.
- Regional and service-led providers — Smaller OEMs and local engineering houses win on responsiveness, spare‑parts availability and installation support, especially where local regulations and supply chain constraints favor proximity.
Recent market activity underlines these trends. For example, visible product launches and trade‑show demonstrations in late 2025 and early 2026 showcased both performance innovations and targeted industrial deployments. Such events are effective near‑term indicators of product maturation and commercialization readiness, signaling where early adopter demand will concentrate in 2026.
Practical recommendations for each stakeholder
- For food processors: Prioritize systems that reduce total yield loss rather than lowest upfront price. Insist on vendor-provided empirical yield and downtime metrics and secure service-level agreements tied to throughput outcomes. If stainless steel input costs are a meaningful line-item in your capex, consider staged procurement or price‑capture clauses to reduce exposure.
- For OEMs: Invest in modular, serviceable designs that facilitate field upgrades (sensor modules, software upgrades), and build aftermarket capabilities—remote monitoring and predictive maintenance have become differentiating profit centers.
- For investors and M&A teams: Target companies that combine a credible technology moat (e.g., sensor fusion, ultrasonic tooling) with a scalable service model. Expect attractive consolidation arbitrage in high‑volume segments where integration creates cross‑sell and spare‑parts synergies.
- For procurement and operations leaders: Map spare‑parts lead times and establish multi‑sourcing for critical wear components. Align specifications with hygienic design requirements so regulatory compliance does not become a retrofit cost later in the asset lifecycle.
Sector dynamics and material context
Three structural forces are shaping the market in 2026:
- Automation to address labor scarcity: Demand for higher-capacity, easy‑to‑operate peelers is rising as processors cope with tighter labor markets. Automation reduces dependence on skilled operators and improves line consistency.
- Hygienic design and compliance: Increasing food‑safety requirements make food‑grade stainless steel and cleanable designs non‑negotiable. This reality affects both equipment specification and supplier selection.
- Input‑cost vigilance: Stainless steel remains the dominant construction material; recent pricing and supply signals—reflecting regional alloying costs and steady industrial demand—should be evaluated when timing capital orders and negotiating contracts.
Methodology and confidence framework
The report synthesizes quantitative market sizing (historical 2020–2025, forecast 2026–2032) with qualitative primary research. Our methodology includes vendor revenue triangulation, equipment shipment analysis, OEM and end‑user interviews, and observed pricing from tenders and trade events. To ensure conservative forecasting, we stress‑test growth paths under alternative macro scenarios and provide scenario outputs that feed the ROI templates in the report.
What we intentionally hold back — and why you should read the full report
Following the “trailer” principle, this briefing presents the strategic implications and high‑level metrics you need to shape 2026 decisions, while withholding detailed segmentation tables, regional and application‑level share data, unit price curves, and the full supplier scorecard. These granular datasets and downloadable models are the core deliverables of the full report and are critical if you intend to:
- Validate a specific retrofit or greenfield investment using plant‑level inputs;
- Prioritize vendors by detailed capability and cost comparisons in your target region;
- Run an M&A diligence on prospective targets with fully populated financial scenarios and sensitivity analyses.
Next steps
If you are planning capital expenditure, supplier consolidation, or a technology pilot in 2026, PW Consulting’s full Worldwide Peeling Machines Market report contains the models, validated benchmarks and vendor intelligence necessary to move from strategy to execution with confidence. Contact our team to access the complete dataset, segmented market maps, and the executable playbooks that underpin the recommendations in this briefing.
In an environment where small choices in peeling technology can translate into meaningful differences in yield, compliance and lifetime cost, decision‑makers who combine data‑driven procurement criteria with a service‑centric vendor strategy will capture the greatest value as the market advances through 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Worldwide Peeling Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com