

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Hotel Market to Expand at 6.5% CAGR, New Insights Reveal

Worldwide Hotel Market 2026: Strategic Imperatives from PW Consulting’s Market Intelligence
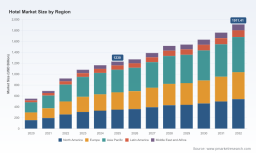
As global travel rebounds beyond pandemic-era constraints, hotel industry stakeholders face a window of strategic opportunity — and complexity. PW Consulting’s new Worldwide Hotel Market report (base year 2025) synthesizes five years of historical performance (2020–2025) and delivers an actionable forecast through 2032. Anchored by a 6.5% compound annual growth rate (CAGR) and a global market base of USD 1,230.0 Billion in 2025, the study maps where value will accumulate, what disruptors will matter most, and how investors, operators, franchisors, and lenders should reposition for 2026 decision cycles.
Intra-Array Submarine Cable Market
Market Snapshot: Scale, Trajectory, and What It Means for 2026
By 2025 the worldwide hotel economy reached a substantively larger scale compared with the early-2020 landscape, reflecting stronger RevPAR recovery and renewed corporate travel. Under a central-case trajectory, the market is projected to expand at a 6.5% CAGR across 2026–2032, with PW Consulting’s modelling pointing to nearly double-digit expansion in aggregate value by 2032. For executives planning capital allocation, talent deployment, or brand expansion in 2026, this macro envelope creates a portfolio of choices — accelerate pipeline and capture share in growth corridors, or defend margins via operational efficiency and direct-booking capture.
ADHD Management Software Market
What the Report Contains (Practical, Hands-on Tools)
- Forward-looking market sizing and scenario forecasts (2026–2032) with sensitivity analysis across demand, pricing, and supply shocks.
- Actionable playbooks for asset owners and operators: conversion vs new-build decision matrices, franchise negotiation checklists, and a CapEx prioritization framework.
- Commercial performance toolkits: RevPAR sensitivity models, dynamic pricing levers, channel-mix optimization templates, and loyalty-program monetization playbooks.
- Regulatory and distribution primer: implications of digital pricing disclosure rules, OTA commission dynamics, and strategies to reclaim direct demand.
- Talent and operations playbook: workforce planning templates, outsourcing vs insourcing decision aids, and automation ROI calculators for front- and back-of-house functions.
- Investment and M&A scanner: deal-screen scorecards, valuation stress-tests under rising construction and labor costs, and integration readiness checklists.
- Regional and segment strategy briefs (available in full report): growth corridors, demand archetypes, and prioritized go-to-market tactics — presented without divulging proprietary granular splits in this release.
- Data appendices and model files: downloadable Excel models and a documented methodology to replicate key scenarios for portfolio-level decision-making.
Competitive Landscape: Who’s Moving — and How to Read Their Moves
The global hotel market remains structurally fragmented, with leading chains expanding distribution while an active base of asset-light franchisors and independent operators compete on niche experiences and cost advantage. The report profiles the sector’s major platform players and synthesizes recent strategic actions to distil playbook insights for 2026.
Worldwide Machine Glazed Uncoated Paper Market
- Marriott International (Bethesda, Maryland, USA) — Marriott continues to press growth through a hybrid approach of new openings and brand depth. Their late‑2025 expansion added substantial room inventory with a pronounced focus on Asia‑Pacific and the Middle East. Strategic takeaway: Marriott’s scale advantage and brand architecture enable rapid market share capture in growth corridors, but investors should assess conversion economics versus greenfield returns in markets with rising construction costs.
- Hilton Worldwide (McLean, Virginia, USA) — With the November 2025 launch of a midscale conversion brand, Hilton is honing conversion-first growth in mature markets. Strategic takeaway: midscale conversions present faster ROI and reduced construction exposure; but success depends on backend distribution and loyalty integration.
- InterContinental Hotels Group (Denham, UK) — IHG’s partnership pipeline emphasizes luxury and lifestyle projects in Europe. Strategic takeaway: co‑development partnerships with institutional real estate managers lower capital intensity for brands while enabling access to premium city-center assets — an essential model for competing where construction and labor inflation compress margins.
- Wyndham Hotels & Resorts (Parsippany, New Jersey, USA) — Focused on asset-light franchise growth, Wyndham’s expansion in India and Southeast Asia underscores the opportunity in economy and midscale conversions. Strategic takeaway: franchise-heavy models are resilient to capex shocks but require robust quality-control and brand-support economics.
- Accor (Issy‑les‑Moulineaux, France) — Accor’s recent openings in Asia and Latin America reflect a dual strategy of market diversification and brand layering. Strategic takeaway: multi-brand portfolios can extract yield across trip purposes, but require disciplined channel strategies to avoid cannibalization.
- Hyatt Hotels Corporation (Chicago, USA) — Hyatt’s emphasis on lifestyle and all-inclusive formats positions it to capture premium leisure rebounds and extended-stay demand. Strategic takeaway: lifestyle is brand-differentiated but asset-intensive; partnerships and management agreements lower balance-sheet exposure.
- Choice Hotels International (Rockville, Maryland, USA) — Primarily franchising in North America, Choice’s model benefits from steady domestic business and leisure flows. Strategic takeaway: domestic consolidation and conversion pipelines are key levers to sustain unit growth in mature markets.
- Radisson Hotel Group (Brussels, Belgium) — Radisson’s global footprint focuses on brand refresh and selective growth. Strategic takeaway: mid-sized international platforms can out-maneuver big chains in tertiary cities with tailored offerings and nimble franchise economics.
Across these competitors, two common strategic moves warrant attention in 2026: accelerating conversion pipelines to mitigate construction inflation, and using brand architecture to segment demand without eroding loyalty returns.
Macro and Operational Headwinds: What to Price into 2026 Plans
- Regulatory friction in distribution: Digital pricing transparency regulations are reshaping OTA economics and increasing the value of direct-booking channels. Operators must reconfigure channel commissions and direct incentives accordingly.
- Labor market pressures: U.S. hotel labor costs rose materially in 2025, reflecting wage inflation and staffing shortages. Workforce productivity improvements and targeted automation will be core margin levers.
- Construction and capex inflation: Material costs rose across 2025, compressing new-build economics and shortening payback horizons. Conversion strategies and refurbishment-first approaches are commercially compelling.
- Revenue recovery pattern: Global RevPAR improved in 2025 amid international travel normalization. However, demand composition is shifting — leisure remains robust while business travel is reaccelerating, driven by corporate spend recovery.
- Business travel tailwinds: Corporate travel spending is rebounding strongly, driving an incremental demand pool that benefits upper-midscale to premium inventory and group business segments.
Strategic Priorities for Decision-Makers in 2026
- Prioritize conversion-capable assets: Where construction inflation compresses new-build returns, conversions and soft-refurbishments produce faster time-to-market and improved IRR profiles.
- Rebalance commercial mix toward direct relationships: Invest in loyalty, CRM, and direct-booking propositions to mitigate OTA share and to capture richer guest data for personalization.
- Embed workforce strategies into operating budgets: Design flexible labor models, invest in multi-skill training, and apply automation where guest experience is not degraded.
- Stress-test pipelines under capex inflation: Use scenario-based valuations that include rising material and labor inputs; consider JV structures or management-led growth to de-risk balance sheets.
- Monetize ancillary revenue: Capture incremental revenue via F&B enhancements, meetings & events optimization, subscription and membership products, and integrated local experiences.
- Adopt a modular sustainability lens: Prioritize energy and water efficiency upgrades with clear payback thresholds to reduce operating costs and meet evolving ESG expectations.
- Design M&A with integration checklists: Target bolt-on asset clusters for synergies in procurement, channel management, and centralized services rather than one-off trophy assets.
Why PW Consulting’s Report Is Strategic for 2026 Decisions
Executives use our market study not just for high-level validation but as a practical decision-making toolkit. The report couples a robust macro forecast (anchored by a 6.5% CAGR through 2032) with granular scenario models, operator playbooks, and transaction-focused analytic templates. It exposes where economics are shifting, quantifies sensitivity to distribution and cost shocks, and provides the operational checklists that translate strategy into implementation.
To honor the trailer principle and protect proprietary modeling, this summary intentionally omits the report’s detailed regional and application splits and the full company-level data appendices. Subscribers and clients receive the complete datasets, interactive model files, and bespoke strategy workshops that convert insights into executable 100‑day plans and three‑year roadmaps.
Next Steps: How to Use These Insights
- For investors: request the deal-screen pack to stress-test target assets under capex and labor inflation scenarios.
- For operators and brands: deploy the conversion decision matrix and the loyalty monetization toolkit to accelerate market share capture with limited capex.
- For lenders and asset managers: use the RevPAR sensitivity models and covenant-ready scenario outputs to align finance structures with operational realities.
PW Consulting is scheduling a limited series of 2026 advisory workshops to walk clients through baseline and downside scenarios, partner matching for conversion pipelines, and implementation playbooks customized to portfolio risk tolerances. For access to the full report, the data appendices, and our model files — including the regional and segment-level breakdowns not presented here — visit PW Consulting’s Worldwide Hotel Market page or contact our research team to arrange a briefing.
In an environment of rising costs and returning demand, 2026 will reward participants who act with analytic rigor, operational discipline, and agile portfolio design. PW Consulting’s report equips leaders to make those decisions with confidence.
For detailed analysis of this topic, please visit the official page: Worldwide Hotel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com