

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Forecast: Worldwide Complicated Urinary Tract Infections Treatment Market Set to Grow at a 6.5% CAGR, New Report Reveals

PW Consulting Strategic Brief: Navigating the Worldwide Complicated Urinary Tract Infections (cUTI) Treatment Market — Tactical Priorities for 2026
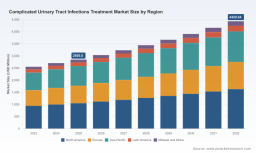
As health systems, pharmaceutical executives, and investors set strategic plans for 2026, our new Worldwide Complicated Urinary Tract Infections Treatment Market report (base year 2025, historical 2020–2025, forecast 2026–2032) delivers a decision-grade view of an evolving therapeutic landscape. The market is on a steady upward trajectory — rising from approximately USD 2,555 million in 2023 to USD 2,850.5 million in 2025 and projected to reach about USD 4,429.6 million by 2032 at a compound annual growth rate (CAGR) of 6.5% over the forecast window. This trajectory reflects a mix of clinical innovation, shifting care settings, and persistent antimicrobial resistance pressures that together create near- and medium-term opportunities — and operational risks — for incumbent manufacturers and new entrants alike.
Worldwide Flight Reservation System Market
Why this report matters for 2026 decision-making
-
Actionable clarity on growth drivers and inflection points: Our analysis translates epidemiology, prescribing signals, and payer levers into tactical timing for launches, label extensions, and formulary negotiations.
Worldwide Permit Software Market -
Forward-looking scenario analysis calibrated to 2026 resource cycles: The report models multiple adoption curves (conservative, base, accelerated) for oral and IV assets, enabling finance teams to stress-test revenue plans and to identify breakpoint years for ROI.
Worldwide Renewable Energy Technology Market -
M&A and licensing playbooks: We identify categories and subsegments where clinical differentiation, regulatory exclusivity, or scarcity of supply can materially increase asset value — crucial for deal teams preparing 2026 pipelines and budgets.
Market trajectory: what the numbers conceal and reveal
The headline growth rate (6.5% CAGR, 2026–2032) packages heterogeneous dynamics. On the demand side, an aging population, higher hospitalization rates for complicated infections, and heightened surveillance for multidrug-resistant organisms sustain baseline volume growth. On the supply side, clinical innovation — including next-generation beta-lactam/beta-lactamase inhibitors, oral carbapenems in late-stage development, and targeted combination therapies — is expanding treatment options and shifting care pathways toward outpatient and step-down models.
However, beneath the aggregate growth are differentiated pockets of margin pressure and tactical opportunity: pricing and reimbursement variability across healthcare systems, the economics of hospital stewardship programs, and the timing of patent cliffs and generic entries that will reallocate value between branded players and generic manufacturers. Our report maps these drivers against a robust financial model that translates epidemiology into revenue sensitivities for 2026 planning.
Competitive landscape — strategic takeaways (not a roster of figures)
The cUTI space is a mix of global pharmaceutical leaders with established antibacterial franchises, small- and mid-cap biotechs advancing novel oral or combination approaches, and regional players focused on formulary penetration within hospitals. Key archetypes and strategic postures emerge:
-
Large integrated pharmas (portfolio defense and lifecycle management): Companies with marketed cephalosporin and beta-lactam combination products are prioritizing lifecycle extensions, label expansions into high-unmet-need subpopulations, and formulary access strategies that emphasize stewardship collaboration with hospitals.
-
Specialist biotech contenders (clinical differentiation and regulatory incentives): Smaller developers pursuing oral carbapenem prodrugs and novel combination therapies are leveraging designations such as QIDP to accelerate regulatory pathways and create near-term exclusivity windows that are valuable to licensing and partnership discussions.
-
Hospital-centric suppliers and generics players (volume and margin play): Distribution-to-hospital models remain central for severe cUTIs, while generics entrants are preparing to monetize patent expiries over the medium term, pressuring pricing trajectories unless mitigated by differentiated clinical data or contracting strategies.
Strategically, incumbents should prioritize defensible assets (e.g., products with demonstrated activity against critical MDR pathogens, strong PK/PD profiles, or compelling step-down oral options), while potential entrants should target regulatory incentives and fast-to-market tactics (partnerships, small indication entries, and targeted hospital campaigns).
Recent developments shaping 2026 priorities
-
Regulatory milestones and approvals have changed therapeutic options available to clinicians, and several recent approvals underscore how regulation can re-order competition and formulary positioning within months.
-
Late-stage clinical readouts for oral agents — including Phase 3 positive topline results announced recently — signal a potential shift from inpatient-only regimens to more outpatient-capable therapies, with meaningful implications for distribution strategy and payer negotiation.
-
Reimbursement updates in major public payers and formulary decisions are already influencing prescribing behavior, and our report models the near-term impact of common payer outcomes on revenue and access.
Regulatory, reimbursement, and patent landscape — implications for 2026 planning
Regulatory incentives such as QIDP designation materially shorten timelines and grant exclusivity corridors that should be central to commercial valuation models. Parallelly, recent decisions by European and U.S. regulators to approve targeted combination agents for limited-use indications demonstrate how regulators balance unmet need against stewardship concerns. For 2026 planning, companies must integrate regulatory timelines, anticipated exclusivity periods, and known patent expiry windows into launch sequencing and repricing scenarios.
Reimbursement dynamics differ by market: coverage decisions and tier placements materially impact uptake in outpatient settings. Our report includes payer decision trees and formulary negotiation playbooks tailored to 2026 budget cycles, identifying which evidence packages and real-world data strategies are most likely to secure favorable access.
Supply chain and operational risks
The cUTI market is sensitive to API availability and manufacturing complexity. Our analysis highlights recent disruptions — including reported shortages of specific beta-lactam APIs — and quantifies the potential commercial impact of supply interruptions and lead-time elongation. For supply chain and operations teams preparing 2026 budgets, the report includes a supplier-risk heat map, mitigation options (dual sourcing, contract manufacturing strategies), and cost implications for inventory strategies aligned to demand volatility.
What’s inside the report — practical, executable content
-
Comprehensive market sizing and forecast model (2020–2032) — scenario-enabled for stress testing through 2026 planning cycles.
-
Granular go-to-market playbooks for hospital and outpatient channels, including contracting, stewardship alignment, and value demonstration templates.
-
Competitive and pipeline intelligence dossiers on leading global players and high-priority biotech assets, with tactical recommendations for partnering, in-licensing, and M&A prioritization.
-
Payer and health-economics frameworks, with sample dossiers and evidence-generation roadmaps to improve formulary positioning in key markets.
-
Operational risk assessments: API and manufacturing supply stress tests, distribution contingencies, and inventory-to-demand optimization levers.
-
Commercial financial model with sensitivity analyses (price, uptake, reimbursement) and a dashboard for board-level scenario briefings.
How executives should use this analysis for 2026 planning
-
R&D and portfolio leads: Use our exclusivity calendars and clinical-readout scenarios to determine which assets should be accelerated, paired, or deprioritized for 2026 filings or partnerships.
-
Commercial teams: Leverage our go-to-market templates to build differentiated hospital access strategies and to prepare value dossiers targeted to expected payer objections during 2026 negotiations.
-
Finance and strategy: Apply the report’s scenario model to capital allocation, M&A valuation caps, and contingency reserves for supply-chain shocks.
-
Supply chain and manufacturing: Implement the report’s supplier risk mitigations and contract manufacturing playbook to maintain continuity through potential API shortages.
Final perspective — an invitation to deeper intelligence
The cUTI treatment market presents a classic combination of steady aggregate growth and localized structural disruption. Learning where clinical innovation intersects with payer pragmatism and supply constraints is essential for converting the 6.5% CAGR into durable commercial returns. PW Consulting’s report equips leaders with the models, playbooks, and tactical intelligence needed to make high-conviction decisions for 2026 and beyond.
For full tables, segment-level forecasts, and the downloadable financial model that underpin these strategic recommendations, please access the full report on the PW Consulting report page or contact our advisory team for a tailored briefing. The executive summary and selected graphical outputs are publicly available; the granular segmentation, modeled scenarios, and deal-ready annexes are reserved for report subscribers and advisory clients.
For detailed analysis of this topic, please visit the official page: Worldwide Complicated Urinary Tract Infections Treatment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com