

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Market Insights: Worldwide Electrical Orchard Sprayer Market to Reach USD 1,000.44 Million by 2032

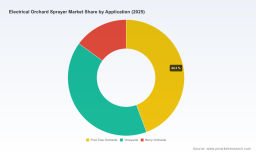
Worldwide Electrical Orchard Sprayer Market — Strategic Outlook for 2026 Decision-Making
PW Consulting is pleased to announce the release of our in-depth market research brief on the Worldwide Electrical Orchard Sprayer Market. Built to be immediately usable by executive teams, product leaders, procurement officers and investors, this briefing synthesizes five years of historical performance, a detailed forward-looking model, and practical decision frameworks to guide capital allocation and go-to-market choices in 2026. The analysis demonstrates where value will be created in the next wave of orchard electrification while intentionally reserving core segmentation tables in order to drive clients to the full report for the granular inputs that underpin commercial decisions.
VCSEL Laser Chips Market
Executive snapshot
Electrification of orchard spraying is no longer a pilot-stage curiosity. Our market model values the global market at approximately USD 631.24 Million in the base year 2025 and forecasts growth to about USD 1,000.44 Million by 2032, representing a compound annual growth rate (CAGR) of 6.8% across the 2026–2032 forecast window. The market has accelerated from the historical period of 2020–2025, driven by advances in battery energy density, autonomy and precision application technologies, and by a faster-than-expected willingness by growers to trade capital expense for operating cost reduction and regulatory compliance.
Worldwide Infrared Transmitting Glass Market
Why this matters for 2026 decision-makers
- Capital allocation: Manufacturers and component suppliers must decide whether to prioritize electrified orchard platforms, hybrid architectures, or modular retrofits. The mid-single-digit CAGR through 2032 signals a growth runway long enough to justify factory retooling, but decision timing will affect margin and market share.
- Technology integration: Battery systems and autonomy stacks are now sufficiently mature to deliver full-shift operation in many orchard use-cases. Third‑party battery packs (notably 60–70 kWh-class systems) have been demonstrated to support 10–12 hours of continuous operation in representative deployments, removing a key operational barrier for adoption.
- Operational economics and sustainability: Precision spot-spraying using AI-powered weed detection has been shown in field demonstrations to cut chemical usage substantially. Where installed, these systems materially reduce input spend and regulatory compliance risk, changing the payback calculus for end users.
- Channel and service model implications: With electrified and autonomous platforms, the aftermarket and software subscription layers become as important as hardware sales. Dealer networks that move from pure equipment sales to outcome-based services will capture disproportionate lifetime value.
What our report delivers — practical tools and proven frameworks
PW Consulting’s report is structured as a commercial playbook for 2026 implementation. We pair a transparent market model with actionable tools designed to accelerate good decisions and de-risk execution:
CTA Head and Neck Analysis System Market
- Proprietary market model (Excel): fully auditable top‑down and bottom‑up demand estimates, scenario toggles (adoption curves, battery-cost declines, regulatory tightening) and sensitivity analysis to test strategic options.
- Five strategic scenarios for 2026–2032: baseline, accelerated electrification, delayed battery rollout, rapid autonomy adoption, and fragmented standards — each with P&L impact for OEMs and expected payback periods for growers.
- Vendor scorecards and supplier due-diligence templates: a standardized assessment across technology readiness, manufacturing scale, channel strength, service capability and regulatory posture.
- Field validation case studies: operational KPIs from commercial pilots that explain the gap between lab claims and on-farm economics — including real-world duty cycles, maintenance profiles and operator acceptance metrics.
- TCO / TCA calculators and financing frameworks: factory-to-farm total cost of ownership worksheets incorporating battery life, chemical-use reductions, labour displacement, and service revenue streams to support procurement decisions and leasing structures.
- Regulatory and safety matrix: regional compliance checklists, data privacy considerations for telematics, and operator-safety design priorities for autonomous spraying in mixed-use orchard environments.
Competitive landscape — what recent moves mean
The vendor environment is transitioning from fragmented hardware specialists toward integrated systems players that combine electrification, autonomy and software. Notable industry developments tracked in the report illustrate these dynamics and the strategic responses required of incumbents and newcomers alike:
- John Deere’s integration of an autonomous electric orchard sprayer platform has been a watershed event. The acquisition completed in 2025 brings a fully electric autonomous herbicide sprayer — built around high-capacity battery packs and advanced AI weed-detection — into a global dealer network. This move signals OEM commitment to bundling autonomy, battery and telematics as a single commercial offering targeted at high-value orchard segments.
- Specialist manufacturers are doubling down on complementary strategies. Select European and Oceania-based suppliers have prioritized compact, fully electric sprayers designed for compatibility with electric tractors and small-farm ergonomics. These firms emphasize modularity, field serviceability and crop-specific application techniques (for example, recapture/recycling technologies for disease control in high-density plantings).
- Product updates from established agricultural equipment brands show a parallel playbook: incremental performance improvements in tank design and control systems paired with simplified operation for specialty crop contexts, making electric options more accessible to traditional buyers.
The net effect: a moderately concentrated market where a small group of well-capitalized OEMs and specialist innovators shape platform standards, while a broad base of niche suppliers address diverse orchard types and regional channel structures. For strategy teams, this means monitoring both headline consolidation moves and the ecosystem of accessory suppliers (battery manufacturers, AI detection software providers, retrofit specialists) that will determine who can deliver end-to-end solutions at scale.
Key operational implications and strategic imperatives for 2026
- Design for serviceability and modular upgrades: Battery and autonomy components evolve quickly. OEMs should design platforms that allow battery swaps, electronic control upgrades and sensor refreshes without full-system replacements.
- Build dealer capacity for electric and software services: Training, tooling and new parts inventories are prerequisites for scaling commercial deployments; dealers that invest here will capture aftersales revenue and reduce downtime for growers.
- Pursue strategic battery and software partnerships: Vertical integration can fast-track capability, but partnering with battery specialists and AI providers preserves capex and accelerates time-to-market.
- Create clear financing and subscription offers: Leasing batteries, offering software-as-a-service for precision application, and bundling maintenance into subscription packages materially reduce buyer friction.
- Operationalize safety and compliance: Autonomous sprayers must embed robust person-detection and automatic pause mechanisms to align with liability expectations in orchard work environments.
How growers and procurement leaders should think about 2026 purchases
- Run TCO scenarios that include chemical-use savings from precision spot-spraying and expected battery replacement cycles; the combination often materially shortens payback for high-input, labor-constrained operations.
- Require field trial data from vendors in similar crop architectures and climates. Benchmarks for spray accuracy, drift reduction and maintenance intervals should be contractually specified.
- Prioritize interoperability: if you are electrifying a fleet, choose solutions that integrate with your preferred tractor OEMs and telematics systems to avoid lock-in and stranded assets.
- Factor in dealer footprint and service SLAs: uptime in spray seasons is a business-critical KPI; ensure vendor contractual commitments reflect real-season response times.
Investor and M&A perspective
John Deere’s strategic move to internalize an autonomous electric sprayer underscores the market’s growing strategic value. Investors evaluating targets should focus on four valuation levers: IP in autonomy and detection models, proven battery integration for full-shift operations, established channel or distribution agreements, and recurring revenue potential from software and service offerings. Our report includes precedent transaction analysis and a valuation sensitivity tool built around those levers to support diligence and offer strategy.
Next steps — how to use PW Consulting’s full report
This briefing is designed to be a decision-ready trailer: it communicates the direction and the levers that matter without disclosing every cell in the model. The full PW Consulting report contains the complete, auditable market model (with regional, type and application splits), supplier scorecards with graded assessments, downloadable TCO calculators and step-by-step implementation roadmaps tailored to grower size segments and regional regulatory regimes.
For teams preparing 2026 budgets and product roadmaps, the full dataset and playbooks will materially shorten evaluation cycles and reduce execution risk. Access to vendor-level segmentation and the full scenario matrices enables precise capital planning, procurement evaluation and go-to-market sequencing that can convert the projected growth runway into defensible revenue streams.
To request the full report, the interactive Excel model, or a tailored briefing for your executive team, please contact PW Consulting through our website and reference the Worldwide Electrical Orchard Sprayer Market 2026 Briefing.
For detailed analysis of this topic, please visit the official page: Worldwide Electrical Orchard Sprayer Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com