

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Tilt & Turn Window Handles Market Set to Expand at a 5.23% CAGR Through 2032

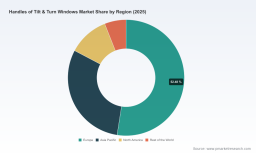
Worldwide Handles of Tilt & Turn Windows Market — Strategic Briefing for 2026 Decision-Makers
Executive preview
As PW Consulting’s lead industry analyst, I present a targeted strategic briefing drawn from our comprehensive Worldwide Handles of Tilt & Turn Windows Market report (base year 2025). The product category—specialised handles and related hardware for tilt & turn windows—sits at the intersection of building energy-performance regulation, materials cost volatility, and accelerating smart-home integration. Our analysis finds the market has recovered from mid‑cycle volatility and is tracking a steady expansion trajectory, underpinned by regulatory retrofit demand and rising preference for durable metal-based hardware. The market size in 2025 was measured at USD 648.5 million and, given current dynamics, we project steady growth at a compound annual growth rate (CAGR) of 5.23% across our 2026–2032 forecast horizon, with long‑term upside if smart‑home and energy retrofits accelerate.
Worldwide Infiltration Marketing Market
Why this briefing matters for 2026 strategic planning
- Pinpointing inflection points: The next 18–36 months will determine winners in both specification‑driven commercial projects and high-volume residential retrofit channels. Companies that move early on energy‑compliant and connected hardware will capture disproportionate share.
- Cost‑to‑value pressure: Manufacturers face higher input costs (notably aluminum) while buyers demand enhanced functionality. Strategic choices on material mix, finish technologies, and supply contracts will materially affect margin outcomes in 2026.
- Consolidation and partnership windows: Industry concentration is moderate—top manufacturers command meaningful but not dominant shares—creating attractive M&A and joint‑venture opportunities for platform expansion or geographic scale.
Market outlook — a data‑led snapshot (high level)
From a macro perspective the handles market shows resilience and structural expansion. After a modest mid‑cycle dip, total market revenue reached USD 648.5 million in 2025. Under our base scenario—reflecting current regulation, construction and retrofit pipelines, and normalised raw‑material inputs—the market grows at a 5.23% CAGR during 2026–2032, reaching an elevated market size by the end of the forecast period. This trajectory reflects steady demand for high‑performing hardware in both new construction and retrofit markets, with periodic acceleration tied to major regulatory milestone years and smart‑home adoption cycles.
Worldwide Productivity Bots Software Market
Dynamics shaping supplier and buyer strategy
- Regulation as demand lever: Updated energy performance standards in major jurisdictions (notably the EU’s EPBD revisions and the UK’s Future Homes/Part L updates) are driving window replacement and specification upgrades. Tilt & turn systems—due to their airtightness, ease of retrofit, and compatibility with advanced locking hardware—are frequently specified in compliance projects.
- Raw‑material volatility: Producer prices for aluminium mill shapes rose materially in 2025 (notable year‑over‑year increases). This has immediate cost implications for metal‑dominant handle portfolios and places a premium on procurement sophistication—longer contracts, metal hedging or strategic alloy substitution where performance allows.
- Material and finish priorities: Aluminum‑based handles continue to gain share where corrosion resistance and weight are priorities; zinc and stainless offerings retain roles where cost or design premium drive selection. Metal finishes and coatings that extend lifespan in coastal or corrosive environments are becoming specification differentiators.
- Smart integration and standards: Smart window hardware is transitioning from niche to mainstream. Recent product launches supporting Matter and robust radio ecosystems create a new vector of value—security, occupant comfort and system‑level energy optimisation. Suppliers who integrate open, cross‑platform connectivity will find easier entry into premium retrofit projects and OEM spec lists.
- Form and fabrication: Trends toward concealed hinges, multi‑point locking and special‑shape window solutions (round tops, trapezoids) are influencing handle design and mounting systems—requiring closer collaboration between handle makers and hardware system suppliers.
Competitive landscape — positioning and implications
The competitive field blends established European system houses with value‑oriented regional suppliers and design‑led premium brands. Market concentration is moderate—top three players collectively hold a meaningful but not overwhelming portion of market sales, leaving room for nimble specialists and regional consolidators.
Worldwide Inorganic Waveplates Market
- HOPPE (Germany) — https://www.hoppe.com
Strengths: Broad design portfolio across multiple series and finishes; strong brand recognition in Europe; integrated security features for tilt & turn. Strategic implication: HOPPE’s design depth makes it a preferred partner for high‑quality residential and bespoke commercial specifications.
- Gretsch‑Unitas (G‑U) (Germany) — https://www.g-u.com
Strengths: Certified hardware meeting EN standards; lockable handle options; engineering focus for modern systems. Strategic implication: G‑U is well positioned for spec‑led projects requiring tested, certified performance—an important differentiator in regulatory procurement.
- MACO (Austria) — https://www.maco.eu
Strengths: Integrated turn & tilt systems for different profile materials; strong OEM and fabricator relationships. Strategic implication: MACO’s multi‑profile capability supports scale through fabrication channels—key for volume growth in retrofit markets.
- Roto Frank (Germany) — https://www.roto-frank.com
Strengths: Focus on aluminium solutions, concealed hinges, and long‑life corrosion performance; recent product updates emphasize design and endurance. Strategic implication: Roto is the go‑to for premium aluminium systems and international manufacturers seeking robust aesthetic and functional solutions.
- Siegenia (Germany) — https://www.siegenia.com
Strengths: Smart handle development and Matter‑ready 2nd generation products; recent FENSTERBAU showcase. Strategic implication: Siegenia’s connectivity roadmap is a blueprint for entrants pursuing smart‑home and retrofit value pools—expect accelerated adoption where installers can upsell connectivity.
- Winkhaus (Germany) — https://www.winkhaus.com
Strengths: High‑performance hardware solutions including concealed hinge options; strong engineering pedigree. Strategic implication: Winkhaus competes strongly on performance features for premium windows and special shapes.
- ASSA ABLOY Fenestration — https://www.assaabloyfenestration.com
Strengths: Global scale, corrosion‑resistant aluminium solutions, and offerings for special shapes. Strategic implication: Benefitting from group scale, ASSA ABLOY targets international OEM channels and specification projects that demand global supply consistency.
- Trojan (UK) — https://www.trojan.co.uk
Strengths: Value and performance for uPVC and common profiles. Strategic implication: Trojan is a go‑to in price‑sensitive segments where installers prioritise reliability and cost control.
- FPL Hardware (US) — https://fplhardware.com
Strengths: Range tailored for tilt‑turn and casement applications; US‑market orientation. Strategic implication: Regionalisation matters—FPL’s portfolio illustrates the advantage of tailoring SKUs to local profile systems and distributor expectations.
- Formani (Netherlands) — https://www.formani.com
Strengths: Design‑led, award‑winning premium handles for architectural projects. Strategic implication: Formani captures premium margins where aesthetics and brand cachet matter, especially in high‑end European retrofits and new build projects.
Recent signals worth watching in 2026
- Siegenia’s launch of a Matter‑version smart handle (Jan 2026) signals a migration to industry standard smart protocols—buyers will increasingly request Matter compatibility in tender documents.
- Roto’s continued promotion of aluminium‑focused tilt & turn systems (2025 updates) highlights ongoing demand for corrosion‑resistant, premium aluminium solutions in international markets.
- Trade show activity (e.g., new products showcased at IBS 2026) indicates suppliers are pushing integrated system narratives—handle + hardware + connectivity—rather than standalone SKUs.
Actionable strategic playbook for 2026
- Procurement and cost management: Lock targeted aluminium volumes under multi‑year contracts where feasible; assess alloy substitution or partial material mix shifts for non‑structural components to protect margin against metal price spikes.
- Product strategy: Prioritise development of energy‑compliant handle assemblies and Matter‑capable smart handles. Invest in robust radio links and cyber‑security certification to reduce installation friction and reassure specifiers.
- Channel and go‑to‑market: Accelerate partnerships with fabricators and window system OEMs. Offer bundled hardware + connectivity packages to installers to increase attachment rates in retrofits.
- Aftermarket and services: Develop retrofit kits and certification packages for energy‑upgrade projects (labelling, testing, and installer training) to capture high‑margin downstream revenues.
- M&A and partnerships: With moderate top‑end concentration, there is strategic logic to bolt‑on acquisitions that fill material, connectivity, or geographic gaps—targeted tuck‑ins can rapidly expand specification reach.
- Regulatory and standards engagement: Proactively engage with certification bodies and standards consortia to ensure product compliance and to influence emerging test protocols for smart window hardware.
What our full report delivers (operational value)
The PW Consulting report goes beyond headline growth to provide decision-ready deliverables for 2026 planning cycles, including:
- Proprietary market sizing and scenario forecasts through 2032 with sensitivity to raw‑material price paths and regulatory accelerants.
- Supply‑chain mapping and a cost‑to‑serve model that isolates procurement levers and margin pressure points.
- Detailed competitor profiles, product matrices, and go‑to‑market playbooks for market entry, expansion, and consolidation strategies.
- Regulatory impact assessment across major jurisdictions and a compliance roadmap for manufacturers and specifiers.
- Commercial tools: pricing frameworks, bundling strategies, and aftermarket monetisation options tailored to manufacturers, distributors and installers.
To respect the role of this briefing as a prelude, we intentionally reserve the granular segment and regional splits, SKU‑level unit economics and modelled price‑elasticity matrices for the full report and interactive dashboard available on our site.
How to use this insight immediately
- Run a 90‑day procurement stress test: model current supplier contracts against a +20% aluminium price scenario and quantify margin exposure.
- Pilot Matter‑capable handle deployments with two installer partners in retrofit projects to validate installation workflows and capture first‑mover premium data.
- Identify one regional M&A target that closes a capability gap (connectivity, coating tech, or fabrication scale) and initiate commercial diligence.
Next steps
PW Consulting’s full Worldwide Handles of Tilt & Turn Windows Market report is the practical resource for teams preparing 2026 budgets, R&D roadmaps, or M&A pipelines. For bespoke briefings, scenario runs, or to access the full dataset and interactive dashboard (including regional and subsegment detail), contact our research team and download the report from the PW Consulting portal. Use the intelligence to convert regulatory and material volatility into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Handles of Tilt & Turn Windows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com