

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: market research
PW Consulting: Global Electric Ambulance Stretchers Market to Rise from USD 560.0M in 2025 to USD 979.19M by 2032 at an 8.31% CAGR — North America Tops with USD 236.05M
By pmarketresearch, 2026-08-12
Worldwide Electric Ambulance Stretchers Market — Strategic Preview for 2026 Decision-Makers
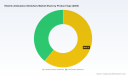
PW Consulting’s latest market study on the Worldwide Electric Ambulance Stretchers market delivers a concise, decision-ready briefing for executives planning capital allocation, product development, procurement, and M&A activity in 2026. The sector has completed a meaningful multi-year expansion: global market revenue grew from approximately USD 385.1 Million in 2020 to USD 560.0 Million in 2025, and our modeling projects continued momentum through the new forecast window. Over the 2026–2032 forecast period the market is expected to grow at a compound annual growth rate (CAGR) of 8.31%, reaching roughly USD 979.2 Million by 2032. These headline figures frame a clear commercial opportunity — and the report drills into the operating levers that will determine which players capture the majority of incremental value.
Worldwide Lactic Acid Polymers Market
Why this matters for 2026 strategy
-
Capital deployment windows are opening across EMS fleets and hospital systems: procurement cycles initiated in 2024–2025 are delivering replacement and expansion orders in 2026. Organizations that align product roadmaps, pricing, and service propositions to fleet procurement timetables will materially improve win rates.
Worldwide Integration Brokerage Software Market -
Technology convergence is shifting purchase criteria from purely mechanical reliability toward integrated fleet management, battery performance and operator ergonomics. Buyers are increasingly valuing telematics-enabled asset management and total cost of ownership (TCO) reductions tied to lower operator injuries and faster turnaround times.
Worldwide IoT Modules Market -
Regulatory and procurement channels remain decisive. While powered wheeled stretchers are exempt from FDA 510(k) premarket notification requirements for Class II devices, compliance expectations remain high: crashworthiness and electrical safety standards (e.g., SAE J3027, BS EN 1789, IEC 60601-1) are baseline requirements in many markets. U.S. federal procurement pathways (including GSA schedules) still materially influence competitive positioning for vendors seeking national-scale contracts.
Market structure and competitive dynamics — what the headlines hide
Market concentration in this sector is meaningful. Our analysis shows a high three-firm concentration and an even higher five-firm concentration (CR3 ~68.5%; CR5 ~79.2%), signaling an oligopolistic structure with a small number of established global suppliers and a larger tail of regional OEMs. That concentration underscores two practical implications for strategy in 2026:
-
Large fleet contracts and specification-led buying favor established brands with demonstrable compliance, service networks, and validated field performance.
-
There is still room for niche entrants and regional manufacturers to win share through targeted differentiation — cost-competitive solutions, integration with local EMS practices, or superior aftermarket service bundles.
On the supplier side, the competitive set blends large multinational medical device companies and specialist OEMs. Notable players included in our landscape mapping include Stryker Corporation and Ferno-Washington (with extensive traction in fleet contracts and product innovation), European manufacturers focused on ergonomics and standards compliance, and a cluster of Chinese and regional producers emphasizing cost competitiveness and local distribution. Our report contains benchmarking plates that compare feature sets, standards compliance, warranty and service footprints, and fleet-reference evidence — but, in keeping with this preview, we intentionally omit full supplier scorecards and line-item revenue splits from this release.
Recent signals that will shape 2026 procurement and product roadmaps
-
Major fleet awards and procurement pilots are accelerating adoption cycles. For example, a large U.S. fleet recently awarded a multi-hundred-unit powered-stretcher contract following a rigorous RFP and field validation process — a reminder that end-to-end support, installation and fastening-system compatibility often decide large buys.
-
Manufacturers continue to refine manuals and operational guidance, reflecting an emphasis on lifecycle support and safety training as differentiators in procurement evaluations.
-
Independent market surveys and government acquisition programs are increasingly cataloguing available powered gurneys, which tends to standardize buyer expectations and reduce time-to-award for vendors that demonstrate tech maturity and compliance.
Key strategic imperatives for manufacturers and buyers
Our fieldwork, buyer interviews, and quantitative modeling identify six priority actions that will deliver disproportionate value in 2026:
-
Prioritize service-enabled differentiation. Manufacturers with integrated fleet telematics, rapid-response spare parts logistics, and structured preventive maintenance programs win longer-term contracts and command pricing premiums.
-
Invest selectively in battery and powertrain innovation. Improvements in battery density, charging cycle life, and hot-swap architectures materially reduce downtime and TCO for fleet operators — and represent high-leverage R&D investments.
-
Align product portfolios with procurement realities. Certification and crash-testing evidence should be ready for RFP submission; compatibility with vehicle fastening systems and stretcher load standards will be non-negotiable in most large tenders.
-
Build go-to-market plays for public-sector channels. For vendors seeking to scale in the U.S., getting onto GSA or equivalent national procurement lists is often a gating factor for large awards.
-
Design aftermarket and financing programs for cash-constrained buyers. Leasing, fleet-as-a-service and bundled maintenance arrangements lower acquisition barriers and increase lifecycle revenue capture.
-
Monitor adjacent innovation vectors. Autonomous loading aids, enhanced crash-energy management, and connected-patient monitoring integration are nascent features that will shift buyer preferences in the medium term.
Competitive profiles — where incumbents and challengers are placing bets
Our competitive deep-dive synthesizes product engineering claims, fleet references, and recent commercial activity. Without reproducing our full vendor scorecards, observe the following high-level takeaways:
-
Stryker Corporation: Strong in fleet-grade integrated cots with telematics capabilities and proven crash-compliant designs — an advantaged position for large institutional buyers and public-sector contracts.
-
Ferno-Washington, Inc.: Demonstrates a two-pronged strategy of product breadth and deep field validation; recent major fleet awards underscore its credibility in U.S. EMS procurements.
-
EU-based manufacturers (representative example): Emphasize ergonomics, compliance with European standards, and ease of technician use — attractive to continental ambulance services and private hospital groups.
-
Regional Chinese OEMs: Compete primarily on cost and fast OEM-to-fleet delivery; increasingly visible in emerging market tenders and price-sensitive segments.
The PW Consulting report provides an actionable competitor playbook — comparative product matrices, procurement win themes, and target-account lists — but these deliverables are reserved for the full report to preserve client value.
Report scope — operationally useful deliverables
This study is explicitly structured to support 2026 execution. Key deliverables include:
-
Market sizing and forecast model (historic 2020–2025, base year 2025, detailed 2026–2032 scenarios) with sensitivity analysis and upside/downside scenarios tied to battery-cost trajectories and public procurement intensity.
-
Procurement playbook for fleet buyers — RFP templates, evaluation scorecards, and TCO calculators to compare competing offers on lifecycle rather than sticker price.
-
Competitive benchmarking plates covering crash standard compliance, telematics capabilities, warranty and service economics, and fleet-referenced reliability data.
-
Supply-chain and manufacturing risk map, highlighting critical components (batteries, actuators, fastening systems) and recommended mitigation strategies.
-
Go-to-market blueprints for market entrants, including channel partnerships, regional regulatory checklists, and a prioritized list of tender targets.
Note: while this public preview presents headline market size and growth rates, detailed regional, product-type and end-user revenue splits — and the granular company-by-company revenue tables and scorecards — are omitted from this release to preserve the report’s commercial intelligence value. Readers seeking those tables and the model workbook will find them in the full report and dataset package.
Practical next steps for executives
-
Vendors: Initiate rapid-gap assessments against the procurement playbook. Prioritize investments that directly impact total cost of ownership (service networks, battery lifecycle programs, telematics) and prepare GSA-equivalent dossiers if pursuing public sector contracts.
-
Buyers (EMS and hospitals): Move evaluation criteria from upfront cost to measurable TCO outcomes. Require telematics and maintenance KPIs in RFPs and negotiate performance-based service terms.
-
Private equity and corporates: Target M&A and minority investments in high-service regional specialists to accelerate market share expansion or access new distribution channels — use CR3/CR5 concentration dynamics to assess consolidation payoff.
How PW Consulting can help
PW Consulting offers tailored strategic support for market entry, M&A diligence, product portfolio prioritization and procurement advisory. For companies setting 2026 budgets and roadmaps, our full report and accompanying dataset provide the revenue granularity, supplier scorecards and TCO models required to make confident decisions. To access the complete study, model workbook, and bespoke advisory options, please visit the report landing page or contact our engagement team for a briefing.
In an industry where safety standards, fleet economics and operational reliability converge, pragmatic strategy and timely execution will determine which organizations lead over the coming six-year growth window. This preview highlights the high-level contours — the full PW Consulting report supplies the calibrated intelligence to act.
For detailed analysis of this topic, please visit the official page: Worldwide Electric Ambulance Stretchers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide High-Speed Spectroscopy Cameras Market to Soar to USD 955.64 Million by 2032 (2026–2032 Forecast, 7.82% CAGR)
By pmarketresearch, 2026-08-12
Worldwide High Speed Spectroscopy Cameras Market: Strategic Imperatives for 2026 Decision‑Makers
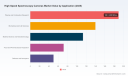
As PW Consulting’s lead industry analyst, I present a focused executive preview of our new market research report on the Worldwide High Speed Spectroscopy Cameras market. The study synthesizes multi‑year historical performance (2020–2025) and delivers a forward view for the 2026–2032 forecast period. We highlight the market’s scale, growth trajectory and the pragmatic intelligence procurement, product development and M&A teams will need to act confidently in 2026 — while intentionally withholding granular segment tables to encourage direct access to the full report for operational data.
Worldwide User Research Software Market
Market at a Glance: Scale and Momentum
The high speed spectroscopy cameras market has moved from a niche, research‑centric domain into a scalable industrial and clinical enabling layer. On a consolidated basis the market reached a notable milestone in our base year, with overall revenue crossing the mid‑hundreds (reported in USD Million for comparability). The market growth profile is robust: our modelling places the compound annual growth rate at 7.82% across the 2026–2032 forecast horizon, projecting the market to be substantially larger by the end of that period.
Worldwide IT Spending in Healthcare Market
Why this matters for 2026 planning: in absolute and relative terms the market is now large enough that product choices, procurement cycles and platform strategies materially affect P&L and technical roadmaps. Buyers must move from “technology evaluation” to “system integration and lifecycle planning” — and vendors must scale repeatable manufacturing, software ecosystems and regulatory readiness to capture value.
Dimming Power Supply Market
Why the 2026 Inflection Is Strategic
- Commercialization of lab‑grade performance. Advances in low‑noise sCMOS and compact SWIR solutions have pushed laboratory capabilities into clinical and factory floors. This is accelerating adoption curves in real‑time spectral analysis for medical diagnostics, industrial inspection and defense applications.
- CapEx windows and procurement behavior. Hospitals, instrument OEMs and high‑throughput factories are treating spectroscopy cameras as multi‑year platform buys rather than single‑project items. Expect procurement timelines to lengthen and specifications to tighten around integration, maintainability and service agreements.
- Convergence with multimodal systems. The strongest near‑term opportunities are in systems where spectroscopy cameras are integrated with imaging, AI inference engines and robotic handling — creating sticky ecosystems and higher lifetime revenue per deployment.
- Regulatory and quality thresholds matter. For medical device integration, compliance with ISO 13485 and common 510(k) pathways in the United States are gating factors. Vendors that embed regulatory design controls and verification artifacts into their product lifecycles will reduce customer adoption friction.
Report Deliverables: What Practitioners Will Find Inside
Our full report is intentionally practical and oriented toward immediate action. Key deliverables include:
- Scenario‑based demand models that map technology choices (e.g., high‑line‑rate sCMOS, EMCCD/ICCD, and InGaAs SWIR variants) to typical buyer journeys in clinical, industrial and research segments.
- Procurement playbooks for OEMs and end‑users: specification checklists, integration risk matrices, warranty and service models, and total cost of ownership templates calibrated for 2–7 year lifecycles.
- Regulatory readiness checklists and a decision tree for embedding cameras into medical devices — covering quality system inputs (ISO 13485), and the common FDA 510(k) considerations for Class II imaging systems.
- Commercial and pricing strategies for vendors: bundling architectures, software licensing models, and go‑to‑market frameworks optimized for hospital systems versus industrial integrators.
- A tailored M&A and partnership playbook: capability gaps to target, valuation accretive integration patterns and three‑tier acquisition scenarios mapped to revenue and IP synergies.
Competitive Landscape — Who Matters and Why
The market architecture is a mix of long‑standing specialist optics firms, scientific camera incumbents and agile hyperspectral OEMs. A few dynamics are decisive in 2026:
- Legacy scientific camera leaders (e.g., firms with deep engineering in sCMOS, EMCCD and cooled CCD platforms) retain strength where sensitivity and low noise remain the primary buyer requirements. These vendors benefit from established distribution into academic and clinical research labs and strong product roadmaps for incremental performance improvements.
- Hyperspectral and SWIR specialists are expanding into high‑speed, process‑grade systems suitable for inline inspection and material analysis. Their edge is optical system integration and domain‑specific software stacks that shorten time‑to‑value for industrial users.
- Miniaturized and OEM‑centric players are winning design‑in engagements where compact form factor, power efficiency and modularity are prioritized — especially for embedded medical devices and robotics.
Illustrative company positioning (high‑level, not exhaustive):
- Andor Technology (Oxford Instruments) — a go‑to for high‑sensitivity sCMOS, EMCCD and cooled CCD systems; strong in scientific and medical research channels with product families optimized for spectroscopy workflows.
- Teledyne Princeton Instruments — competitive in low‑noise, high‑throughput CCD/sCMOS offerings for Raman, hyperspectral and transient spectroscopy; well‑placed in life sciences imaging applications.
- Hamamatsu Photonics — leverages detector R&D and broad photonics product portfolio to serve near‑infrared spectroscopy and clinical imaging opportunities.
- HORIBA Scientific — focuses on cooled sCMOS cameras and integrated spectrometer solutions; strength in biomedical and clinical diagnostic instrument supply chains.
- Specim (Konica Minolta), Headwall, HySpex, Photon etc., XIMEA, BaySpec — these companies represent hyperspectral and compact OEM segments that are accelerating adoption in industrial inspection and medical spectral imaging through tailored optical modules and software toolchains.
Recent product announcements (early 2025–2026) underscore the rapid productization of SWIR and NIR‑SWIR push‑broom and rectangular‑pixel architectures, signaling that vendors are shifting from proof‑of‑concept demonstrations to deployable field units — an inflection that procurement and product teams must anticipate.
Operational Risks and Mitigations
- Integration risk: Optical, mechanical and software interfaces remain the most common source of schedule slippage. Mitigation: require vendor‑supplied integration kits, reference drivers and verified datasets as part of procurement contracts.
- Regulatory drift: Changes in regional device classification or coverage policies can alter reimbursement prospects for clinical applications. Mitigation: early engagement with regulatory consultants and payor strategy teams; maintain modularity so a camera can be reclassified without a full system redesign.
- Supply chain tightness: Advanced sensors and custom ROICs face allocation risks. Mitigation: multi‑sourcing strategies, buffer inventory planning and co‑development agreements with foundries or sensor manufacturers.
- Software lock‑in: Proprietary processing stacks increase switching costs. Mitigation: prefer vendors that provide SDKs and documented APIs; require data‑format portability in contracts.
Actionable Recommendations for 2026 Planning
- Vendors (product teams): Prioritize modular platforms that separate sensor, optics and compute. Ship SDKs and certified integration kits. Make ISO 13485 alignment and 510(k) hygiene part of the product roadmap rather than an afterthought.
- OEMs and integrators: Redesign procurement to evaluate long‑term serviceability and AI inference readiness. Negotiate lifecycle pricing and upgrade paths that reflect sensor and algorithm obsolescence cycles.
- Healthcare providers and device OEMs: Map use cases to reimbursement pathways early. Invest in pilot deployments that capture clinical validation data and interoperability evidence for device submissions.
- Private equity and corporate development: Target acquisitions that provide software differentiation or application‑specific optics IP rather than solely sensor stockpiles. Look for partners with channel strength in high‑value verticals (medical, pharma inspection, defense).
What the Full Report Unlocks
This preview intentionally omits the granular regional, sensor and application split tables that many operational teams require to execute. The full PW Consulting report provides those segmentations, scenario‑based revenue forecasts in USD Million, pricing and margin benchmarks, and downloadable procurement templates. Those datasets are built from 2020–2025 historical performance and our 2026–2032 forecast model, enabling slice‑and‑dice analyses for product planning, territory strategies and investment due diligence.
Final Word: Position Early, Integrate Deep
2026 is the year to move from evaluation to platform deployment. The market’s growth trajectory gives both vendors and buyers a window to lock in advantageous commercial and technical positions — but only if organizations treat spectroscopy cameras as platforms requiring systems engineering, regulatory planning and commercial foresight. PW Consulting’s full report equips leaders with the actionable models, checklists and competitor intelligence to convert that opportunity into tangible revenue and improved clinical and industrial outcomes.
For access to the complete dataset, segmentation tables and vendor scorecards that underpin these conclusions, please visit our report page to request the full Worldwide High Speed Spectroscopy Cameras Market study.
For detailed analysis of this topic, please visit the official page: Worldwide High Speed Spectroscopy Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Ferrite Cable Cores Market to Grow from USD 750.0 Million in 2025 to USD 1,071.63 Million by 2032 at a 5.23% CAGR — Asia Pacific, Cylindrical Cores and Consumer Electronics to Dominate
By pmarketresearch, 2026-08-12
Worldwide Ferrite Cable Cores Market 2026: A Strategic Playbook for Executive Decision-Making
Executive snapshot
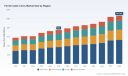
As global electronics architectures accelerate toward higher data rates, electrification, and stricter electromagnetic compatibility (EMC) regimes, ferrite cable cores have shifted from commodity afterthoughts to strategic components. Our new PW Consulting report positions the Worldwide Ferrite Cable Cores Market as a steady-growth sector: the market reached approximately USD 750 million in the report base year (2025) and is forecast to expand at a compound annual growth rate (CAGR) of 5.23% over the 2026–2032 forecast period, moving toward a billion-dollar-plus industry by the horizon. This trajectory reflects blended demand from consumer devices, automotive electrification, data infrastructure, and industrial automation — and it carries concrete implications for procurement, product engineering, and M&A planning in 2026.
Electric Toothbrush Pressure Sensor Market
Why this market matters to corporate strategy in 2026
-
Component economics are now strategic levers. Ferrite cable cores influence system-level EMC performance, certification timetables, and, in certain architectures, perceived product quality. Minor changes in core formulation or geometry can materially affect compliance scope and rework costs.
Digital Supply Chain Finance (SCF) Solution Market -
Supply-chain fragility translates to program risk. Key raw inputs for ferrite—iron oxide, manganese and zinc—are sourced predominantly in a concentrated geography, exposing OEMs and tier suppliers to supply disruptions, trade actions and price volatility. In 2024–2025, policy shifts and material tightness fed through to higher unit costs and longer lead times for specific ferrite chemistries.
Automotive Multi-domain Fusion Market -
Technology waves create product bifurcation. Emerging high-speed standards, automotive Ethernet, EV charging, and expanded 5G bands are pushing demand for higher-permeability formulations and cores capable of suppressing noise well into the multi-gigahertz range. That is creating a premium tier of product and qualification requirements where suppliers with advanced materials and design capabilities can capture outsized margins.
Market trajectory and the near-term forecast
The market’s baseline in 2025 provides a pragmatic foundation: growth is reliable, not explosive. Our model projects a consistent expansion driven by steady replacement cycles in consumer electronics, accelerating electrification in transport, and infrastructure buildouts in data centers and telecom. The 5.23% CAGR we report accounts for cyclical device replacement, structural upgrades (e.g., USB4/PCIe Gen5, automotive-grade components), and incremental price inflation linked to raw material dynamics. For strategic planners, this means predictable addressable market growth but asymmetric upside concentrated in segments that demand specialized cores and fast qualification cycles.
Competitive landscape — positioning and tactical moves
The sector displays moderate concentration: a handful of global incumbents combine scale, material science capability, and channel access, while numerous regional and low-cost players address volume commodity demand. Market concentration metrics underline the dichotomy between scale and specialization; the top-tier suppliers retain meaningful presence, but there remains room for technology-focused entrants to carve niche leadership.
-
TDK Corporation (Tokyo) continues to invest in high-permeability snap-on solutions designed for next-generation telecom and automotive Ethernet applications, aligning product launches with 5G and high-speed cable trends. Recent introductions advertise suppression capabilities out to higher gigahertz bands, signaling clear R&D emphasis on advanced formulations and precision manufacturing.
-
Murata Manufacturing (Nagaokakyo) leverages strengths in compact bead and filter technologies to serve mobile, PC, and high-speed data cable markets. Their presence at trade venues underscores a go-to-market strategy that pairs miniaturization with integrated EMC solutions for space-constrained designs.
-
Laird Technologies (DuPont) has pursued automotive-grade validation, achieving certifications attractive to EV and charging-system OEMs. Such qualification is a high barrier to entry and a differentiator for suppliers targeting automotive Tier 1 relationships.
-
Fair-Rite and similarly specialized firms emphasize material breadth and catalog depth, supporting rapid design cycles for high-speed interfaces and niche industrial applications.
-
European and multinational players (e.g., Ferroxcube/Yageo, Vacuumschmelze, Mitsubishi Materials, Samsung Electro-Mechanics) combine regional manufacturing footprints with localized technical support — a compelling mix where tariff or logistics risk is elevated.
-
Low-cost and regional suppliers from Asia remain important for high-volume, price-sensitive cable assemblies, particularly in consumer and legacy industrial segments.
Recent supplier moves to watch
-
Product innovation is active: suppliers have announced new high-permeability snap-on cores and catalog updates explicitly address high-speed interfaces and automotive Ethernet needs.
-
Qualification matters: automotive-grade certifications for cable cores (e.g., AEC-Q200) are becoming a procurement prerequisite for EV and charging-system suppliers.
-
Trade-show activity and catalog refreshes point to supplier strategies that bundle design support with product breadth, reducing upstream engineering friction for OEMs adopting new standards.
Supply-chain dynamics and regulatory context
Procurement and program managers must read the supply environment carefully. The production chain for ferrite chemistry is concentrated in a limited set of geographies, and that concentration has been a vector for policy and price shocks. Trade measures implemented in recent years have had a direct effect on landed costs for certain import channels. Concurrently, regulatory constraints—most notably persistent restrictions on hazardous substances in electronics—require materials and processes that ensure compliance across global markets.
Practically, the market has seen unit-price inflation and extended lead times for specific ferrite types. Where nickel-zinc chemistries are required, buyers are experiencing substantially longer lead times. These dynamics make buffer strategies, second-source qualification, and early supplier engagement essential actions for 2026 program plans.
Strategic implications and recommended executive actions for 2026
-
Develop tiered procurement strategies: segment purchases into “qualified premium” (specialized, high-permeability cores for high-speed/automotive programs) and “volume commodity” lanes, and negotiate different contract structures accordingly.
-
Prioritize supplier qualification early: timelines for automotive and high-speed interface approvals can become the critical path on new product introductions. Build qualification gates into product roadmaps and invest in extended collaboration with material suppliers for joint testing.
-
Mitigate raw-material concentration risk: diversify material sources, consider strategic inventory for critical chemistries, and evaluate near-shore or regional production partnerships where tariff and logistics risk is material.
-
Pursue cost-to-serve optimization: where price sensitivity dominates, consider design simplification that reduces the number or complexity of cores per assembly; where performance is differentiated, invest in premium formulations and corresponding price capture strategies.
-
Monitor regulatory and standards evolution: EMC standards, RoHS-like restrictions, and automotive qualification standards will continue to shape allowable materials and testing requirements—early compliance planning reduces rework and avoids costly recalls.
-
Scan M&A selectively: mid-sized suppliers with unique material science capabilities or regional manufacturing footprints can be attractive bolt-on targets for companies aiming to secure technology or shorten supply chains.
What the PW Consulting report delivers (practical, on-the-desk tools)
-
Validated market sizing and a transparent forecasting model for 2026–2032, supporting scenario analysis across demand, pricing and lead-time sensitivities.
-
Competitive intelligence dossiers on the industry’s key players, including capabilities maps, recent product and certification moves, and strategic positioning assessments.
-
Supply-chain risk matrices that synthesize raw-material exposure, geopolitical and tariff risk, and supplier concentration into prioritized mitigation options.
-
Actionable procurement playbooks and qualification timelines tailored to automotive, data-communications and consumer-electronics programs.
-
Scenario-based recommendations for localization, inventory strategy and cost-recovery levers that facilities, sourcing and product teams can implement within 6–12 months.
-
Templates for commercial negotiations and technical specifications that reduce cycle time for new supplier integrations.
How to use this intelligence in 2026 planning cycles
Position the report as a planning asset: embed its forecast scenarios into your FY+1 budget, use supplier-risk scoring in your supplier-development plans, and prioritize core qualifications for any program with automotive or high-speed data requirements. For C-suite and board discussions, the material helps quantify the trade-offs between near-shoring, inventory expense and potential cost pass-through to OEM customers.
Final note — depth available, details reserved
This release outlines the strategic contours and practical actions executives should consider when ferrite cable cores intersect with their product roadmaps. PW Consulting’s full report contains the granular charts, regional breakouts, supplier scorecards and downloadable forecasting models that supply-chain, product and corporate-development teams need to execute. In keeping with our “trailer” approach, we have presented the strategic thrusts and operational imperatives here while reserving the full segmented datasets, appendices and proprietary models for the comprehensive report.
To access the complete Worldwide Ferrite Cable Cores Market report, with downloadable forecasting models and supplier dossiers, please visit PW Consulting’s market research portal or contact your PW Consulting account executive for institutional licensing and customized briefings tailored to your programs.
For detailed analysis of this topic, please visit the official page: Worldwide Ferrite Cable Cores Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Laminating Lithium‑ion Capacitor Market Poised to Reach USD 1,500.67 Million by 2032 (Forecast 2026–2032)
By pmarketresearch, 2026-08-12
Worldwide Laminating Lithium‑ion Capacitor Market — Strategic Intelligence for 2026 Decision‑Makers
PW Consulting today releases a forward‑looking industry brief drawn from our comprehensive report, Worldwide Laminating Lithium‑ion Capacitor Market (base year 2025). With the laminated lithium‑ion capacitor (LIC) sector entering a rapid growth phase, boards, corporate strategists and investors must recalibrate manufacturing footprints, supplier relationships and product roadmaps now to capture scale and margin as the market expands. This executive announcement highlights the strategic levers and actionable implications contained in the full study while deliberately preserving the report’s detailed segmentation and proprietary model outputs for subscribers.
Worldwide Nonprofit Payment Gateway Software Market
Why 2026 is a Strategic Inflection Point
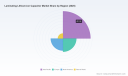
Our market model — built on five years of historical observation and seven years of scenario forecasting — shows the laminated LIC market accelerating from an estimated USD 456.28 Million in 2025 to USD 540.87 Million in 2026, with a compound annual growth rate (CAGR) of 18.54% across the 2026–2032 forecast window. Underpinning this growth are converging demand signals from renewable energy, industrial automation, transportation electrification and grid modernization, alongside manufacturing innovations that reduce cost and raise energy density.
Worldwide Cherry Oil Market
For 2026 planning cycles, that growth profile creates a short window for capacity investments that will determine which suppliers secure OEM partnerships and project pipelines through the end of this decade. The headline numbers in the full PW Consulting report quantify revenue pools by use case and technology variant, but the strategic insight we present here is directional: 2026 is the year to decide whether to invest for share in an expanding pie or to adopt an asset‑light, partnership‑first play.
Endocrine Disruptor Testing Market
What the Full Report Enables — Practical, Transactional Intelligence
- Robust market sizing and top‑down revenue pools by use case and product architecture, with sensitivity scenarios that stress-test price, raw material and adoption assumptions.
- Supply chain and cost‑build analyses that identify critical inputs, cost thresholds and supplier concentration risk across electrode materials, lithium pre‑doping and laminated cell assembly.
- Technology roadmaps comparing laminated LIC constructions versus alternative formats, with implications for manufacturing capital intensity, yield, and integration with existing lithium‑ion battery lines.
- Competitive benchmarking and capability matrices for leading LIC players, including manufacturing footprint, product formats, validated applications and strategic partnerships.
- Commercial playbooks for OEM engagement, channel strategies for utilities and industrial customers, and template commercial terms for licensing, co‑development and toll manufacturing.
- M&A and investment screening tools with target profiles, valuation sensitivities and integration checklists tailored to LIC subsegments.
These deliverables make the report tactical for 2026: procurement teams can set multi‑year contracts with material suppliers; R&D leaders can prioritize pre‑doping and laminated electrode process investments; and corporate development teams can identify acquisition targets that plug capability gaps without overpaying for underutilized capacity.
Key Strategic Dynamics Shaping Decisions in 2026
- Manufacturing modality and scale: Laminated cell production benefits from processes similar to Li‑ion pouch manufacturing, which creates optionality for players with existing battery lines. Strategic choices include retrofitting existing Li‑ion lines, investing in dedicated laminated LIC capacity, or outsourcing via toll‑manufacturing partnerships.
- Raw material economics and feedstock concentration: LIC performance hinges on activated carbon for electrodes and lithium pre‑doping. Industry sourcing is concentrated in biomass‑derived activated carbon, which dominated supercapacitor feedstocks in recent years. Cost thresholds materially affect unit economics — supply disruptions or price spikes will rapidly compress margins for low‑value, thin‑margin applications.
- Process innovations and licensing: Recent licensing of lithium pre‑doping methods enables some manufacturers to adopt lower‑cost production flows using standard Li‑ion equipment. Adopting proven pre‑doping routes or securing exclusive arrangements will be a differentiator for scale players.
- Geopolitical and tariff pressures: Tariff regimes and geopolitical risks are driving nearshoring decisions and supplier diversification for critical materials. Companies must model alternative sourcing scenarios and inventory buffers as part of 2026 procurement plans.
- Concentration and consolidation: The sector shows moderate concentration at the top of the market, leaving room for both strategic partnerships and bolt‑on acquisitions. Expect continued consolidation as incumbents and strategic investors compete to secure module‑level solutions for transportation and grid applications.
Competitive Landscape — Who to Watch
The report includes detailed profiles of the market’s core players and their strategic postures. Highlights for 2026 guidance:
- LICAP Technologies, Inc. (Sacramento, USA): Focused on dry electrode and activated dry electrode manufacturing, LICAP has recently scaled domestic capacity and pursued collaborations to adapt dry electrode routes for laminated LIC production. Their expansion and OEM collaborations make them a leading innovator for high‑throughput pouch‑compatible electrode processes.
- Musashi Energy Solutions Co., Ltd. (Japan): With established mass production of laminated and prismatic hybrid supercapacitors, Musashi’s safety and compliance achievements reinforce their play in stationary and industrial ESS markets. They represent a low‑execution‑risk partner for integrators seeking certified systems.
- SPEL Technologies (India): A key supplier of thin, laminated pouch formats, SPEL’s small‑form‑factor approach and cost competitiveness position them well for telecom backup and light industrial applications where form factor and cost are paramount.
- VINATech (Korea/Vietnam) and JTEKT (Japan): Both are pursuing hybrid designs and efficient, smart factory production. Their emphasis on low leakage and manufacturing automation addresses the yield and quality constraints that matter most at scale.
- Other notable participants: Specialty manufacturers across China, Japan, South Korea and Europe provide complementary capacity and local market access. The competitive map in the full report includes capability scoring, channel strengths and recent corporate developments.
Recent corporate moves underscore the near‑term strategic dynamics: domestic facility expansions, manufacturing collaborations with OEMs, and product certifications for energy storage systems have shifted the operational baseline. These developments are catalogued and interpreted in the report to help buyers assess counterparty risk and execution timelines.
Actionable Recommendations for 2026 Planning
Based on our scenarios and supplier assessments, PW Consulting recommends that executives consider the following actions this planning cycle:
- Decide capacity posture early: Lock in or commit to modular capacity increases now if your ambition is to capture system‑level contracts in transportation or grid services. Lead times for qualified laminated LIC production — from line commissioning to qualified yields — are measurable in quarters, not weeks.
- Secure raw material optionality: Negotiate multi‑tier supply agreements for activated carbon and lithium precursors, and colocate inventory options with strategic suppliers. Consider alternative activated carbon feedstocks and invest in supplier development to reduce exposure to single‑source shocks.
- Pursue selective licensing and partnerships: Licensing pre‑doping or dry electrode manufacturing technologies can be faster and less capital‑intensive than greenfield investments; evaluate licensing terms against projected margin uplift and time to volume.
- Embed scenario planning into procurement: Stress test procurement contracts for tariff shocks and logistics disruptions. Nearshoring or regional manufacturing may justify higher short‑term capital spending to preserve long‑term customer access.
- Design for integration: Product roadmaps should prioritize module‑level standardization to lower integration friction with OEMs and energy integrators; standardized mechanical and electrical interfaces accelerate adoption.
Risk and Opportunity Matrix
The laminated LIC market offers high upside but also concentrated technical and supply risks. The key risk vectors we model for 2026 are raw material price shocks, yield and qualification delays, and geo‑political trade frictions. Countervailing opportunities come from scale economies, process licensing, and application wins in fast‑moving segments such as renewable energy buffer systems and traction‑adjacent power smoothing.
Our report presents probability‑weighted scenarios and an interactive sensitivity model enabling executives to quantify the value of mitigation options — for example, the trade‑off between capital invested in in‑house pre‑doping versus licensing a proven process.
How the Report Supports Transactional and Operational Decisions
- Commercial diligence for VC and corporate M&A teams: target shortlists, valuation sensitivities and integration risk scoring.
- Supply chain strategy for procurement: supplier scorecards, alternative sourcing maps and contract term templates.
- Manufacturing and CapEx planning for operations: build vs. buy analyses, retrofit cost curves and ramp‑to‑yield timelines.
- Product and business development playbooks for sales: use‑case prioritization, channel strategy and partner negotiation checklists.
Call to Action
PW Consulting’s Worldwide Laminating Lithium‑ion Capacitor Market report combines primary interviews, plant visits, supplier cost models and proprietary adoption modeling to translate macro growth into executable plans. For executives making 2026 commitments — from board‑level capital allocation to supply chain and product roadmap choices — the report supplies the empirical basis and strategic frameworks required to act with confidence.
Access to the full dataset, annotated competitive profiles, and the interactive sensitivity model is available through PW Consulting’s research portal. We invite decision‑makers to contact our team for a briefing and to request the subscriber pack, which includes the detailed segmentation outputs and client‑specific scenario runs that have been withheld here to protect the report’s proprietary value.
For detailed analysis of this topic, please visit the official page: Worldwide Laminating Lithium-ion Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Silver‑Coated FEP Film Market to Reach USD 228.73 Million by 2032, Says New Report
By pmarketresearch, 2026-08-12
Worldwide Silver Coated FEP Film Market: Strategic Imperatives for 2026 — PW Consulting Insights
PW Consulting's latest market intelligence brief on the Worldwide Silver Coated FEP Film Market (base year 2025, historical 2020–2025, forecast 2026–2032) synthesizes proprietary primary research, supplier audits, and scenario-based financial modelling to equip executives with decision-grade insight for 2026. The global market reached approximately USD 144.13 Million in 2025 and — under our base-case trajectory (CAGR 6.82% through 2032) — is projected to expand to roughly USD 228.73 Million by 2032, with an early-cycle transition visible in the 2026 projection. This briefing is designed as a strategic “trailer”: we disclose high-conviction implications, competitive positioning, and actionable frameworks while reserving granular segment-by-segment tables for the full report to encourage direct engagement with the source model.
AI-powered Software Market
Why the Silver Coated FEP Film Market Is a 2026 Strategic Priority
-
Mission-critical applications in space and cryogenic systems are converging with accelerating commercial satellite deployments and renewed government investments in deep-space exploration. That convergence creates both predictable base demand and episodic, program-driven spikes — a combination that favors suppliers who can pair materials expertise with production agility.
Worldwide Veterinary Capital Equipment Market -
Despite a relatively compact absolute market size, the market exhibits sustained mid-single-digit compound expansion (6.82% CAGR in our base forecast). The growth profile makes silver coated FEP not just a tactical procurement item but a strategic component where supply assurance, long-term cost management, and co-development matter.
Bamboo Products Processing Equipment Market -
Market structure is concentrated: the top three suppliers account for a dominant share of available capacity (CR3 ~62.4%) and the top five suppliers cover an even larger proportion (CR5 ~81.15%). This concentration amplifies supplier influence on price, lead times, and technology roadmaps — a double-edged sword for buyers and investors contemplating supplier partnerships or M&A.
What the Full Report Delivers (Practical, Transaction-Ready Content)
-
Transparent market sizing and a linked, downloadable financial model (USD, revenue unit: Million) with base-year calibration (2025) and an open workbook for sensitivity testing across price and volume scenarios.
-
Demand-side mapping across end-use categories, procurement rhythm matrices, and buyer specification templates that translate thermal, optical, and mechanical requirements into vendor selection criteria.
-
Supply-side diagnostics: capacity maps, lead-time banding, minimum order profiles, and supplier scorecards built from primary interviews and factory visits.
-
Raw-material exposure and hedging playbook — linking silver price trajectories to margin impact, pass-through mechanisms, and contract clause language for fixed-price/escalator arrangements.
-
Technology roadmap and R&D investment thesis — comparative durability/reflectivity performance of silver-coated FEP variants, emerging alternatives, and qualification pathways for aerospace/space-grade acceptance.
-
Commercial playbooks: go-to-market options for component suppliers, integrators, and OEMs including JV structures, co-development agreements, strategic inventory buffers, and tactical hedging instruments.
Competitive Landscape — What Procurement and Strategy Teams Must Know
Our primary research highlights a compact competitive set with differentiated capabilities rather than a commoditized supplier base. Three illustrative profiles:
-
Dunmore Aerospace (Bristol, PA, USA) : A long-tenured supplier with over 35 years of domain-specific experience in silver coated FEP variants (including ITO and SiO2 overlays). Dunmore’s strengths are technical depth in thermal control applications, qualification heritage for satellite MLI and second-surface mirror use, and integrated coating/process controls that shorten qualification cycles for new programs. For buyers, Dunmore presents a lower technical-risk option but with premium pricing dynamics tied to its specialized know-how.
-
SQUID3 Space (USA) : A more nimble entrant focused on tape and thin-film formats, including ITO-coated Teflon solutions for Flexible Optical Solar Reflectors (FOSR), cryogenic applications, and defense optics. SQUID3 competes on responsiveness, latter-stage customization, and partnerships with system integrators seeking faster development timelines. Its model favors close co-engineering relationships over pure commodity supply.
-
Sheldahl (historical operations; Northfield, MN, USA) : Known historically for one-sided silver coated FEP with protective overcoats (e.g., Inconel) for second-surface mirror applications. While its operations have been integrated or restructured across various owners, the Sheldahl lineage remains an intellectual asset in specialty coatings and legacy program support — especially where end-of-life spares and sustainment matter.
Tactically, the concentration metrics (CR3 ~62.4%; CR5 ~81.15%) imply supplier leverage. Strategic buyers should therefore prioritize a mix of supplier diversification, contractual protections, and selective co-investment to influence capacity expansion when needed.
Raw-Material Volatility: A Non-Trivial Risk in 2026
Silver price volatility has moved from a background risk to a potential margin driver. Industry reporting indicates materially higher price points in 2025 and early 2026 — with J.P. Morgan projecting an average near USD 81/oz for 2026 and spot reports peaking near USD 95/oz in early March 2026 amid renewed geopolitical tension. For thin-film manufacturers, silver cost can represent a disproportionate share of variable cost per unit area; consequently, sudden price moves compress margins, encourage substitution initiatives, and can trigger renegotiation of long-cycle government contracts.
Actionable implications:
-
Procurement should adopt tiered hedging strategies tied to program timelines (e.g., partial forwards for near-term contracts; options for multi-year commitments) and embed explicit pass-through clauses in long-term purchase agreements.
-
R&D and product teams must accelerate qualification of lower-silver-use coatings and multilayer protective strategies that preserve optical/thermal performance while reducing silver intensity or enabling recovery/recycling at end-of-life.
Strategic Recommendations for 2026 Decision-Making
To convert market insight into competitive advantage, PW Consulting recommends the following priority actions for 2026:
-
Supply Resilience First: Implement a two-tier sourcing strategy: a primary technology partner (for qualification and co-development) and secondary qualified suppliers for volume flexibility. Where program-critical, secure committed capacity through supply agreements with defined penalties and incentive structures.
-
Cost and Price Risk Management: Negotiate hybrid pricing (fixed base + indexed variable) to balance predictability and fairness. Use financial instruments to hedge raw-material exposure where internal treasury capabilities exist.
-
Co-Invest for Differentiation: For OEMs targeting accelerated missions or novel thermal architectures, consider co-funding capacity upgrades or pilot lines tied to volume guarantees — a fast way to lock-in priority production slots and influence roadmap direction.
-
Standardize Specs to Reduce Qualification Burden: Drive industry adoption of standardized film specifications and testing protocols across programs to lower supplier switching costs and accelerate time-to-flight for new suppliers.
-
Monitor Competitive Consolidation Opportunities: Given high concentration, strategic M&A or minority investments in niche coating specialists can yield asymmetric returns by internalizing supply and technology assets.
-
Embed Lifecycle and Sustainability Metrics: Incorporate recycling potential and end-of-life recovery into procurement scoring to reduce long-term material exposure and align with sustainability mandates.
Scenario Planning: Timing Investments to Risk-Reward
Use the PW Consulting financial model to stress-test three near-term scenarios:
-
Base Case (6.82% CAGR): Continued moderate expansion driven by commercial satellite deployment and a steady program pipeline. Under this scenario, disciplined procurement and moderate hedging are sufficient.
-
Upside Case: Faster-than-expected program approvals and larger defense procurements accelerate demand. Vertical integration or capacity co-investment pays off, and first-mover buyers secure pricing and delivery advantages.
-
Downside/Cost-Shock Case: Extended silver price spikes or supply-chain disruption elevate total landed cost and compress demand elasticity. In this environment, contingency inventory and material substitution accelerate.
Conclusion — How to Use This Insight in 2026
For leaders setting 2026 priorities, silver coated FEP film represents a strategic component class: modest in absolute market size but pivotal in technical systems where failure is not an option. PW Consulting’s analysis shows a market growing on a mid-single-digit CAGR to 2032, dominated by a handful of capable suppliers and exposed to raw-material volatility. The immediate priority for procurement, program management, and corporate development teams should be to convert that structural insight into concrete actions: secure capacity where needed, align contracts to raw material realities, and invest selectively in technology and supplier partnerships.
This press synopsis is intentionally selective. The full Worldwide Silver Coated FEP Film Market report contains the detailed regional and application splits, thickness-by-thickness demand curves, supplier scorecards, the complete downloadable financial model, and contract-level clause templates that operational teams can deploy. For the granular tables, scenario workbooks, and supplier benchmarking that will directly inform 2026 procurement and investment decisions, please consult the full PW Consulting report and model on our website.
For detailed analysis of this topic, please visit the official page: Worldwide Silver Coated FEP Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Handheld Medical Equipment Market Forecast to Reach USD 101,721.46 Million by 2032, Backed by an 8.25% CAGR (2026–2032)
By pmarketresearch, 2026-08-12
Worldwide Handheld Medical Equipment Market — Strategic Outlook for 2026
PW Consulting’s latest market study on the Worldwide Handheld Medical Equipment Market delivers an actionable, board-level lens on a rapidly evolving space poised to reshape care delivery over the coming decade. Grounded in a 2025 base year and a seven‑year forecast horizon (2026–2032), the report synthesizes historical performance (2020–2025), regulatory inflection points, technology adoption curves, and competitor positioning to inform critical decisions in 2026. Our top‑line projection: the global market — measured in USD Million — grew to approximately 58,400 (base year 2025) and is forecast to expand at a compound annual growth rate (CAGR) of 8.25%, crossing the 100,000 mark by the end of the forecast window. This trajectory demands that executives calibrate R&D, regulatory strategies, channel investments, and M&A plays now, not later.
Worldwide Biomass Recycling Market
Why this market matters for 2026 decision cycles
-
Acceleration of point-of-care and home-based care models is forcing hospitals, payers, and device makers to rethink capital allocation and service models. Handheld devices are no longer niche; they are integral to de‑centralized clinical pathways.
Current Limiting Power Fuses Market -
Technological convergence — miniaturized imaging, AI inference at the edge, multimodal sensors and smartphone connectivity — is compressing time‑to‑value for product iterations, but also raising the bar for regulatory evidence and post‑market surveillance.
Worldwide Database Marketing Market -
Regulatory expectations are maturing in parallel: FDA 510(k) routes remain central for many device categories, and international safety standards such as the IEC family are increasingly referenced in clearance and procurement criteria. Companies must treat regulatory strategy as a revenue enabler, not a compliance cost center.
Market trajectory at a glance (strategic implications)
Our topline series shows robust expansion from mid‑2020s baselines into the early 2030s, underpinned by sustained demand across emergency, ambulatory, and remote care settings. For product and corporate strategists, three implications stand out:
-
Product roadmaps should prioritize modularity and software-defined features that can be validated and updated post‑market, enabling platform economics and recurring revenue streams.
-
Commercial models must hybridize direct clinical channels with digital marketplaces and OEM partnerships to capture both institutional and consumer demand.
-
Regulatory and health‑economics evidence generation (including real‑world data studies) will be decisive in negotiating hospital formularies and payer reimbursement in 2026 and beyond.
Key demand and technology drivers
-
Edge AI and embedded analytics: AI‑powered diagnostics and workflow automation are accelerating clinician adoption by reducing interpretation time and lowering operator dependency.
-
Miniaturized imaging and sensor fusion: Whole‑body point‑of‑care imaging and multi‑parameter monitoring in compact form factors enable new clinical pathways in remote and resource‑constrained settings.
-
Integration with digital health ecosystems: Seamless connectivity to EHRs, telemedicine platforms, and care management systems is becoming a procurement prerequisite rather than an optional feature.
-
Regulatory harmonization pressures: Manufacturers must navigate a patchwork of device classifications and safety standards (including IEC guidance for imaging and radiation safety), which materially affects time‑to‑market and IP planning.
Regulatory and safety dynamics — what to build into 2026 plans
Recent regulatory activity underscores the importance of early, evidence‑first design. Several handheld imaging and monitoring devices have advanced through FDA 510(k) pathways, reinforcing the need for substantial‑equivalence strategies and compliance with IEC safety standards for electrical and imaging performance. For organizations planning clinical trials or submission strategies in 2026, the operational checklist must include pre‑submission engagement with regulators, integrated clinical validation protocols that support both safety and comparative effectiveness claims, and a robust post‑market surveillance plan to capture real‑world performance data that will influence subsequent procurement cycles.
Competitive landscape — positioning and strategic moves
The competitive map is diverse, spanning legacy medical device majors, fast‑growing speciality entrants, and software‑first startups. Leading incumbents maintain advantages in channel access, institutional trust, and broad product portfolios, while newer players push innovation at the device + software junction. Key strategic postures we observed among the major participants include:
-
Platform extensibility: Established players are evolving handheld devices into platform gateways — integrating monitoring, imaging, and decision support to capture recurring service revenue.
-
Vertical specialization: Startups and specialist manufacturers are focusing on high‑value use cases (e.g., smartphone‑connected ultrasound, AI ECG analyzers, handheld ophthalmic imaging) to win clinical niches before scaling.
-
Regulatory and clinical credibility: Several firms have prioritized incremental FDA clearances and clinical collaborations to build trust among hospital procurement teams and payers.
Representative company positioning (select examples)
-
Large diversified medtech firms continue to leverage installed bases and cross‑selling to introduce handheld variants of core products — an approach that reduces sales friction in institutional channels.
-
Specialty innovators are exploiting smartphone ecosystems and subscription models to target outpatient and home care segments, focusing on rapid software iteration and data analytics monetization.
-
Regional OEMs and low‑cost providers are competing on price and distribution in emerging markets, forcing global players to consider localized product strategies and tiered offerings.
Recent approvals and industry signals
-
Early 2026 saw notable regulatory activity: an FDA 510(k) clearance for a spectral imaging handheld wound assessment device, highlighting the combining of spectral data with AI for objective tissue assessment.
-
Also in 2026, a next‑generation AI‑enhanced handheld 12‑lead ECG system received FDA clearance, extending automated cardiac determinations and reinforcing the role of AI in ambulatory diagnostics.
-
Late‑2025 clearances included portable dental X‑ray units and enhancements to handheld robotic surgical components cleared for specific procedural applications — all pointing to an expanding envelope of handheld use cases that require targeted regulatory planning.
-
These approvals signal two broader themes: regulators are increasingly receptive to software‑enabled handheld devices when supported by comparative evidence, and clinical buyers are prepared to adopt devices that demonstrably improve workflow efficiency or diagnostic yield.
What PW Consulting’s report delivers (practical, actionable content)
-
Comprehensive market sizing and forecast (USD Million), with base year 2025 and a 2026–2032 forecast built from primary interviews, device shipment models, and reimbursement scenarios.
-
Strategic segmentation frameworks to prioritize product investment and go‑to‑market (note: the public summary intentionally withholds granular subsegment tables to preserve competitive insight; full segmentation matrices are available in the full report).
-
Regulatory playbook: stepwise guidance for 510(k) pathways, IEC safety alignment, pre‑submission engagement, and evidence generation approaches tailored to handheld imaging/monitoring classes.
-
Commercial readiness checklists: channel selection heuristics, pricing and bundling strategies, and pilot design templates to accelerate adoption in hospital and remote care settings.
-
Deal pipeline and M&A lenses: criteria for target screening, integration risks, and synergie capture models designed specifically for device + software healthtech consolidation.
-
90+ company profiles and a curated tracker of regulatory clearances and clinical studies, updated to include the most recent 2025–2026 developments.
Recommendations for executives planning 2026 actions
-
Embed regulatory and HTA considerations into product design from day one — build validation studies that answer both safety and health‑economic questions to shorten procurement cycles.
-
Pursue modular platforms rather than point devices: capture upgrade paths via software and services, which materially improve lifetime value and defensibility.
-
Prioritize clinical partnerships for real‑world evidence generation; hospitals and payers increasingly require population‑level outcomes data to support reimbursement and purchasing.
-
Balance rapid innovation with quality systems: rapid software releases are valuable, but must be paired with robust cybersecurity and post‑market surveillance to avoid regulatory setbacks.
-
Consider selective M&A to acquire specialized AI capabilities or regional distribution in high‑growth markets where organic expansion would be slow or cost‑inefficient.
Next steps and how to use the full report
For corporate strategy teams, product leaders, and investment committees, this research functions as both an early‑warning system and a playbook. The high‑level numbers and growth rates in this briefing demonstrate the scale of the opportunity; the full PW Consulting report provides the granular subsegment data, competitive dashboards, and scenario models needed to finalize budgets, technology roadmaps, and M&A screens for 2026. To access detailed breakdowns, interactive forecasting tools, and our proprietary vendor scorecards, please consult the full report and appendices available on the PW Consulting website.
PW Consulting remains available to support tailored briefings, in‑depth competitor deep dives, and regulatory readiness workshops to convert the market opportunity into measurable business outcomes in 2026.
For detailed analysis of this topic, please visit the official page: Worldwide Handheld Medical Equipment Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Worldwide Oyster Shell Calcium Market to Rise from USD 513.35 Million in 2025 to USD 772.93 Million by 2032 at a 6.02% CAGR — Asia‑Pacific, Powdered Form and Dietary Supplements Lead
By pmarketresearch, 2026-08-12
Worldwide Oyster Shell Calcium Market — Strategic Briefing for 2026 Decision‑Makers
As PW Consulting’s Lead Industry Analyst, I present a focused executive briefing designed to equip corporate leaders, investors and supply‑chain strategists with the high‑level intelligence they need to make confident, actionable choices in 2026. Our new market research—the Worldwide Oyster Shell Calcium Market report—synthesizes a six‑year historical base (2020–2025) and a detailed forecast window (2026–2032). The global market, measured in USD Million, is projected to expand from a 2025 base to a materially larger opportunity by 2032 at a compound annual growth rate (CAGR) of 6.02%.
Worldwide Social Engineering Attack Defense Solution Market
Why this market matters in 2026
- Oyster shell calcium is moving from a niche raw material to a strategic feedstock across dietary supplements, animal nutrition, food & beverage, pharmaceuticals and select agricultural applications. The material’s combination of bioavailable calcium, circular‑economy sourcing potential and relatively simple processing makes it attractive to both incumbents and new entrants.
- Our topline forecast shows steady expansion through 2032; companies that align product development, supply chain resilience and regulatory preparedness in 2026 will capture disproportionate share as demand matures.
- The market’s competitive structure reflects moderate concentration: our concentration metrics indicate that the top three players account for a significant, but not dominant, portion of global supply; the top five broaden that control further. That market structure creates opportunities for mid‑tier players to specialize or consolidate.
Top‑line trajectory (what the numbers mean for strategy)
PW Consulting’s model uses a 2025 base year and spans a robust historical window to detect durable trends. The market grows at a steady CAGR of 6.02% across the 2026–2032 forecast period, reaching a substantially higher total by 2032. For strategic planners, that growth rate implies predictable demand expansion but also rising expectations from downstream customers: tighter quality controls, more value‑added formulations, and differentiated sustainability credentials will become de‑facto buying criteria.
Worldwide Pharmaceutical Storage Cabinet Market
Demand drivers and structural forces
- Demographic and nutritional trends: Aging populations in several large markets and growing health‑conscious consumer segments are increasing demand for calcium supplements and fortified foods.
- Animal protein intensification: Feed formulations are evolving to include precise mineral supplementation; oyster shell calcium’s cost‑to‑benefit profile keeps it relevant for feed producers seeking sustainable mineral sources.
- Regulatory momentum and quality expectations: As oyster‑derived inputs move into regulated spaces (pharmaceutical excipients, certain food applications), traceability, impurity control and documented provenance are becoming non‑negotiable.
- Sustainability and circular sourcing: Reclamation and upcycling of shellfish waste appeal to ESG‑focused buyers and can be a differentiator in supplier selection—provided suppliers can quantify lifecycle benefits.
- Supply chain dynamics: Localized collection points, processing capacity and logistics to end markets create regional cost and lead‑time differentials that influence commercial strategy.
What this means for 2026 corporate priorities
Companies that treat 2026 as the year to professionalize their approach will outperform. That means shifting from opportunistic sourcing to programmatic procurement, and from transactional sales to solution selling. Specific, high‑impact actions include:
Mobile Fetal Monitor Market
- Operational readiness: Validate processing protocols (particle size distribution, purity targets, contaminant screening) against the requirements of priority end markets; invest in certification where ROI justifies.
- Supply security: Establish multi‑node sourcing strategies and strategic inventory buffers to mitigate seasonality and localized supply shocks.
- Product differentiation: Develop fractionation and surface‑treatment capabilities to serve higher‑margin applications (e.g., pharma‑grade excipients, specialty food applications).
- ESG and traceability: Implement chain‑of‑custody systems; quantify carbon and waste diversion benefits to unlock premium procurement lists and institutional buyers.
- M&A and partnerships: Consider bolt‑on acquisitions that add processing capacity or geographic access, and JV structures with shell collection networks to secure feedstock while reducing exposure to commodity price swings.
Competitive landscape — what the leading players reveal
The market includes a mix of specialized manufacturers, regional processors and integrated suppliers. Three illustrative firms from our company profiling illustrate strategic archetypes:
- Carich Biotechnology Co., Ltd. (Taichung, Taiwan) — A producer focused on high‑purity oyster shell calcium carbonate powders suitable for dietary supplements and pharmaceutical uses. Companies like Carich signal the premium end of the market where certification, particle specification and product consistency command higher margins.
- Viet Delta Industrial Co., Ltd. (Ho Chi Minh City, Vietnam) — A regional exporter providing ground oyster shell powder grades used in animal feed, agricultural amendments and basic nutrition. Players in this bracket compete on cost, volume capability and logistics to regional feed mills and commodity buyers.
- Eiwa Chemical Industrial Co., Ltd. (Osaka, Japan) — A supplier of processed oyster shell calcium for food supplements and functional materials, representing a mid‑to‑high‑value proposition with an emphasis on processed forms and technical support.
Together, these profiles highlight three strategic paths: premium, specification‑driven supply; cost‑efficient commodity supply; and technical/partnered supply for formulation customers. Our concentration analysis shows a market where the top three firms control a meaningful share, and the top five extend that control—the implication is an open landscape for well‑funded entrants and smart consolidators alike.
Risks and regulatory considerations
- Contaminant and heavy metal limits: Global buyers are tightening standards—non‑compliant lots can be rejected and damage supplier reputation.
- Feedstock variability: Biological feedstocks exhibit intrinsic variability; failure to manage it erodes margins and trust with downstream formulators.
- Environmental and permitting constraints: Shell collection and processing have local environmental impacts; permitting delays or local opposition can create supply deficits.
- Price volatility and trade barriers: While raw material cost swings are generally constrained, transport costs and trade policy shifts can compress margins rapidly.
Report contents — practical, transaction‑ready intelligence
To support executive action, our full report delivers a practitioner’s toolkit rather than a purely academic narrative. Highlights include:
- Transparent methodology, data tables and our forecast engine (2026–2032) that clients can re‑run under alternate assumptions.
- Demand models segmented by application, form and region, with scenario outputs and sensitivity testing to guide sizing decisions and capex planning. (Note: the public briefing omits granular segment allocations; the full dataset is available through our subscription channel.)
- Supplier scorecards and a mapped supply‑chain topology showing sourcing nodes, processing hubs and logistics corridors.
- Commercial playbooks: procurement checklists, contract clauses to de‑risk quality and delivery, and pricing negotiation frameworks.
- Regulatory matrix and certification pathway guides for supplement and pharmaceutical buyers.
- Strategic M&A screening criteria and an M&A dashboard that prioritizes targets by strategic fit, integration difficulty and expected ROIC.
How to use this intelligence in 2026
Decision timelines and actionable triggers matter. Use our framework to align short, medium and long‑term moves:
- Short term (0–12 months): Run supplier audits, secure multi‑source contracts with quality penalties and invest in traceability pilots for priority SKUs.
- Medium term (12–36 months): Pursue targeted capacity expansions (or acquisitions) focused on high‑margin product forms; integrate ESG metrics into commercial terms to access premium channels.
- Long term (36+ months): Move upstream where appropriate—secure feedstock streams, invest in innovations that reduce impurity profiles, and build proprietary processing steps that create switching costs.
Scenario planning — what to prepare for
Our forecasting engine produces a base case aligned with current demand momentum, and alternative scenarios that stress supply interruptions, accelerated sustainability adoption, or faster reformulation in downstream industries. The strategic takeaway: build flexibility into contracts and capex plans so you can scale up to capture upside or preserve cash through headwinds without losing market access.
Concluding recommendation
For organizations evaluating oyster shell calcium exposure in 2026, the choice is tactical clarity: treat the material as a strategic input and align procurement, product development and sustainability narratives accordingly. The market’s steady CAGR and the evolving buyer expectations reward early standardization and purposeful investment. Entities that move now to professionalize quality assurance, lock in diversified feedstock and articulate credible sustainability claims will enter 2027 with both resilience and optionality.
Next steps and how to access the full report
This briefing intentionally showcases the strategic insights and practical content of PW Consulting’s Worldwide Oyster Shell Calcium Market report while reserving the detailed segmentation tables, regional and application breakdowns, and the full financial model for the report itself. For companies preparing 2026 budgets, procurement RFPs or M&A screens, accessing the full dataset and our interactive forecast model is the fastest route from insight to execution.
- Download the full report for a complete set of data‑driven segmentations, supplier scorecards and executable playbooks.
- Engage PW Consulting for a tailored workshop to translate the report’s scenarios into a customized 18‑month action plan.
Contact PW Consulting to schedule a briefing with our lead analyst team and obtain the full report and model access. Equip your 2026 strategy with market‑grade intelligence that converts growth projections into competitive advantage.
For detailed analysis of this topic, please visit the official page: Worldwide Oyster Shell Calcium Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Premium pet-care surge: PW Consulting predicts 6.45% CAGR for worldwide prescription cat food market through 2032
By pmarketresearch, 2026-08-12
Worldwide Prescription Cat Food Market — Strategic Preview for 2026 Decisions
PW Consulting’s latest market study on the Worldwide Prescription Cat Food Market delivers an actionable, decision-oriented briefing for executive teams preparing strategic moves in 2026. Built on a robust base year of 2025 and a seven-year forecasting horizon, the study synthesizes historical performance, near-term headwinds, and medium-term opportunity sets into a pragmatic playbook for portfolio managers, commercial leads, M&A teams, and supply‑chain directors.
Worldwide Sales Coaching Software Market
At a glance: macro trajectory you can rely on
-
Market scale and momentum — Our model uses 2025 as the analytical base and projects a compound annual growth rate (CAGR) of 6.45% through the forecast window. The sector’s multi‑year trajectory reflects both clinical demand growth and widening adoption of vet‑prescribed nutrition as a care modality.
Current Limiting Power Fuses Market -
Concentration dynamics — The prescription cat food market remains highly consolidated. The leading global manufacturers collectively command a large majority of market value, an important consideration when assessing distribution access, promotional leverage with veterinary partners, and margin dynamics.
RNA Sample Preservation Solution Market -
Resilience across cycles — Historical patterns (2020–2025) demonstrate resilience even as raw‑material and regulatory noise intensified; the sector’s durability is rooted in prescription status, clinical substitution barriers, and embedded relationships with veterinary professionals.
Why this matters for 2026 corporate decisions
-
Portfolio prioritization: With steady mid‑single‑digit CAGR and predictable clinical demand, companies should re‑weight investments toward high‑ROIC product lines (palatability, renal and urinary care formulations, and targeted dry/wet product engineering). The market’s structural characteristics favor deep clinical differentiation over broad low‑cost positioning.
-
Commercial model optimization: Prescription channels (veterinary clinics, hospital networks) continue to be the primary recommendation point. However, omnichannel commercialization—integrating clinic stocking programs, e‑commerce fulfillment for repeat prescriptions, and tele‑vet partnerships—will define winners in customer lifetime value and adherence.
-
Supply chain and margin management: Input‑cost volatility has become a recurring risk. Effective 2026 playbooks will include indexed procurement agreements, dual‑sourcing of critical proteins, and flexible formula platforms that preserve therapeutic integrity while enabling material substitutions under regulatory guardrails.
Competitive landscape: strategic posture of the leaders
Our competitive audit focuses on the global incumbents who shape clinical standards, distribution norms, and innovation benchmarks. Three manufacturers consistently shape market direction through R&D, vet education programs and global distribution reach.
-
Hill’s Pet Nutrition — Hill’s remains a benchmark in therapeutic formulations and veterinary channel presence. Its Prescription Diet line is positioned around classic clinical indications (e.g., renal, urinary, gastrointestinal, dermatology), and recent product introductions underscore an ongoing emphasis on palatability and condition‑specific innovation. For 2026 strategy, Hill’s scale and deep vet relationships enable aggressive portfolio refresh cycles and clinic loyalty programs.
-
Royal Canin — Royal Canin’s Veterinary Diet range is notable for formulation breadth and targeted clinical claims. Recent formula updates focused on palatability and clinical adherence highlight a tactic of incremental product improvement to protect pricing and shelf prominence. Royal Canin’s brand equity in veterinary channels makes it a natural partner for co‑developed clinical trials and practice‑level education.
-
Nestlé Purina PetCare — Purina’s Pro Plan Veterinary Diets combine clinical positioning with consumer‑grade brand recognition. Recent portfolio and packaging updates reflect a focus on consumer perception and channel activation. Purina’s advantage is cross‑channel competence—leveraging broad retail and veterinary distribution to optimize trial funnels and subscription behaviors.
Recent company developments—product launches, formula updates, and portfolio refreshes—signal that incumbents are prioritizing palatability, packaging convenience and clinical evidence to sustain adherence and pricing power. For dealmakers and portfolio managers, this implies that buy‑and‑build plays should emphasize complementary clinical niches, intellectual property around formulation, and access to veterinary prescription networks.
Supply, regulation and risk: what to watch in 2026
-
Raw material inflation and pass‑through discipline — Protein and meal prices remain a live input risk. Procurement strategies that combine hedging, long‑term contracts and formula modularity will reduce margin volatility. Our scenario work shows that firms with flexible bill‑of‑materials and rapid reformulation capabilities preserve gross margins best under sustained input inflation.
-
Regulatory compliance and label governance — Prescription diets require veterinary substantiation and must align with established nutrient profiles. Labeling standards and nutritional adequacy statements are enforceable; manufacturers need disciplined label governance, especially for multi‑jurisdiction launches. Non‑compliance risk is not only regulatory but also commercial, as vets and distributors avoid products that create legal exposure.
-
Supply security and traceability — Increasing regulatory scrutiny on imports and manufacturing registration elevates the value of traceable, auditable supply chains. Firms with robust traceability and certified manufacturing footprints can convert compliance into commercial differentiation, particularly in markets with strict import controls.
-
Recall environment — The current recall landscape for major prescription cat food brands is notably clean. Nonetheless, brand risk from potential safety issues remains asymmetrical. Investment in rapid‑response quality systems and transparent communications protocols is a non‑discretionary insurance cost for 2026.
What the PW Consulting report delivers — practical, executable modules
This release is designed as an operational tool, not an academic exercise. Key deliverables include:
-
Executive dashboards with scenario‑based revenue and margin projections, configurable by channel and by strategic action (pricing, mix shift, procurement hedging).
-
Commercial playbooks for clinic penetration, e‑commerce integration, and adherence programs—complete with salesforce incentives, sample promotional mechanics, and subscription economics.
-
Product innovation roadmaps prioritizing palatability optimization, therapeutic ingredient sourcing, and format differentiation (dry/wet/therapeutic treats) with a gating checklist for scale‑up and claims substantiation.
-
M&A and partnership due‑diligence templates—value drivers, integration-risk checklists, and synergy calculators tailored to the prescription segment.
-
Supply‑chain playbook addressing procurement contracts, dual‑sourcing decision matrices, and factory footprint optimization scenarios under differing raw‑material price shocks.
-
Regulatory tracker and compliance heatmap covering core jurisdictions with recommended action items for labeling, registration and cross‑border shipment readiness.
Actionable recommendations for 2026 (prioritized)
-
Lock in strategic procurement agreements and invest in formula platform modularity to absorb commodity swings without compromising clinical profiles.
-
Accelerate clinic‑centric loyalty programs and tele‑vet partnerships to protect prescription flows while building direct‑to‑patient adherence channels via subscriptions.
-
Prioritize product enhancements that materially improve palatability and owner convenience—these drive adherence and justify premium pricing in clinical segments.
-
Assess M&A opportunities not merely for revenue scale but for access to vet networks, unique formulation IP, and local manufacturing that reduces import friction.
-
Operationalize recall‑ready quality systems and transparent communications protocols to safeguard brand value and commercial continuity.
Methodology and confidence framing
Findings are built on historical performance through 2025, proprietary channel checks, primary interviews with veterinary professionals, input‑cost modeling and scenario simulations across a seven‑year forecast window. While the report surfaces directional value pools and tactical levers, it purposefully refrains from publishing core subsegment value splits in this public summary to protect the integrity of the full analytical model and to guide readers to the detailed subscriber deliverable for transaction‑grade data.
Next steps: where to get the full toolkit
This preview is intended to give 2026 leadership teams a clear line of sight on strategic priorities while reserving the proprietary, transaction‑ready details for the full PW Consulting report. The comprehensive deliverable contains the segmented demand model, channel economics by market, product‑form breakouts, and downloadable decision templates that are essential for capital allocation and M&A execution.
To obtain the full report, model files and client briefing options, PW Consulting is accepting a limited number of bespoke bootcamps for executive teams in Q3–Q4 2026. Contact our market leads to schedule a confidential walkthrough and to receive the complete data set and recommendations you’ll need to act decisively.
For detailed analysis of this topic, please visit the official page: Worldwide Prescription Cat Food Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecasts Worldwide Aircraft Windows Market to Expand at a 4.25% CAGR in the 2026–2032 Forecast Period
By pmarketresearch, 2026-08-12
Worldwide Aircraft Windows Market — Strategic Insights for 2026 Decision-Making
Executive snapshot
PW Consulting’s new Worldwide Aircraft Windows Market report delivers a concise, actionable intelligence package designed to inform procurement, design, MRO, and investment decisions in 2026. The global market for aircraft windows and transparencies is on a measured upward trajectory: from a base of approximately USD 868 million in our 2025 baseline, the market is projected to expand at a compound annual growth rate of 4.25% through the 2026–2032 forecast horizon, reaching roughly USD 1.16 billion by 2032. These headline numbers reflect a market driven by sustained passenger demand, regulatory maintenance cycles, and material- and platform-specific technology transitions — all of which are unpacked in the report with pragmatic recommendations for near-term action.
Subscription-Based Digital Comics Market
Why this report matters for 2026
As OEMs, Tier-1 suppliers, MRO operators, and fleet owners prepare budgets and supplier strategies for 2026, they need market intelligence that translates macro momentum into concrete choices: which material technologies to prioritize, how to structure aftermarket contracts to capture long-term replacement cycles, and where to position capacity or investment to capture retrofit and new-build windows demand. The report bridges strategically relevant forecasting with operational insight — providing scenario-based projections, replacement-cycle models calibrated to regulatory pressure, and supplier-performance benchmarks. It is intentionally deep on implications while preserving proprietary segmentation detail to incentivize direct access to the full study.
Manned Aircraft Modified Drone Market
What the report contains — practical, transaction-ready content
- Robust market sizing and a 2020–2032 time series that supports capital planning and revenue-statement modeling; headline totals and growth rates are included for boardroom-level decisions.
- Scenario analysis that maps demand drivers (fleet growth, narrowbody delivery cadence, retrofit cycles, and regulatory-driven replacements) into three investment outcomes for 2026–2028.
- Supplier and aftermarket playbooks: RFP templates, warranty language considerations, and cost-to-serve benchmarks tailored to windows and windshields.
- Technology and materials roadmap linking optical performance, weight trade-offs, and manufacturability — with decision matrices for material selection in new-build vs retrofit programs.
- MRO & lifecycle modeling: recommended inspection intervals, predictive-replacement triggers, and parts-repair-vs-replace decision trees that align with FAA/EASA compliance trends.
- Commercial due-diligence annexes for investors: revenue sensitivity analyses, margin compression scenarios, and acquisition scorecards for consolidation plays.
Market trajectory and the implications for strategic planning
Two quantitative anchors drive the report’s strategic recommendations. First, the market’s mid-single-digit CAGR underscores steady, not explosive, growth — supporting disciplined capital allocation rather than aggressive bet-the-company expansions. Second, the projected increase in absolute market size from the 2025 baseline to the 2032 forecast signals meaningful aftermarket and retrofit opportunity as fleets age and regulatory replacement cycles compress. Together, these anchors argue for a dual-focused strategy in 2026: optimize supply chain and manufacturing efficiency to protect margins in near-term OEM contracts; and scale aftermarket capabilities (repair facilities, spares distribution, certification support) to capture recurring revenue that compounds over the decade.
Orthopedic Perioperative Rehabilitation Aids Market
Competitive landscape — who moves first matters
The industry remains concentrated around a set of established, technically sophisticated suppliers whose portfolios span original equipment and aftermarket transparencies. These incumbents combine materials expertise, coatings technology, and certification depth — competencies that create high entry barriers and shape supplier selection criteria for airlines and OEMs.
- PPG Aerospace (United States) — a leader in OEM and aftermarket transparencies, with advanced coating systems that address UV protection and optical fidelity. ( https://www.ppg.com/en-US/aerospace)
- GKN Aerospace (United Kingdom) — a dominant provider of military transparency systems and a major commercial supplier, known for extensive in-service windows fleets and coating expertise. ( https://www.gknaerospace.com)
- Saint-Gobain Aerospace (France) — trusted supplier to airlines and emerging eVTOL projects; recently announced an ongoing partnership with Lilium to supply transparencies for the Lilium Jet, underscoring cross-platform opportunities. ( https://www.saint-gobain-aerospace.com)
- Lee Aerospace (Wichita, KS, United States) — specialist in FAA-approved windows for business and general aviation with strong aftermarket upgrade and support capabilities. ( https://leeaerospace.com)
- The NORDAM Group (United States) — positions itself across repair, overhaul, and manufacturing for transparencies within a broad MRO portfolio. ( https://www.nordam.com)
- Gentex Corporation (United States) — applies optical and protective systems know-how to aerospace transparencies, with an emphasis on material performance.
- Established FAA-PMA and niche suppliers — including long-tenured players in the general aviation segment — continue to control significant fleet-specific aftermarket relationships.
From a strategic standpoint, the window suppliers that secure integrated OEM partnerships and build scalable aftermarket networks will be best positioned to translate the steady market growth into durable revenue streams. The PW report benchmarks each major supplier across certification breadth, coating IP, aftermarket footprint, and historical in-service fleet exposure to help executives prioritize partners and M&A targets.
Sector dynamics and technology trends to watch in 2026
- Material substitution and weight optimization: Advances in polycarbonate and advanced acrylic formulations offer substantial weight savings over glass, supporting fuel-efficiency goals on narrowbodies and regional aircraft. Manufacturers and airlines weighing retrofit options should quantify life-cycle fuel savings against incremental certification and maintenance costs.
- Coatings and optical performance: Demand for coatings that combine UV blocking, abrasion resistance, and anti-fog properties is increasing — particularly as new missions (eVTOL, business aviation) require broad operating envelopes.
- Regulatory influences: FAA and EASA inspection and replacement guidance are shortening effective windshield life for certain fleets, generating predictable aftermarket demand. Fleet owners should align their MRO contracts to capture volume discounts and reduce AOG exposure.
- Production cadence and OEM delivery schedules: Sustained narrowbody deliveries from late 2020s onward underpin a steady intake of new-build windows, while the retrofit market captures end-of-life and regulatory-driven replacements.
Risk factors and what they mean for decision-makers
While steady, the market is not without risks. Supply-chain disruptions in polymer feedstocks or coatings chemistries could elevate lead times and costs; certification delays for novel materials (e.g., next-gen polycarbonate laminates) could stall retrofit programs; and competitive price pressure from concentrated manufacturing hubs could compress margins. The report provides sensitivity analyses that map input-cost shocks, certification lag scenarios, and concentrated-supplier outages to revenue and margin outcomes — enabling procurement and finance teams to stress-test 2026 budgets.
Recommended 2026 playbook — five immediate actions
- Right-size aftermarket capacity: Lock in long-term MRO agreements with tiered pricing that reward volume commitments and shared risk for inventory obsolescence.
- Prioritize material pilots: Execute two controlled in-service trials (one new-build platform, one retrofit) for advanced polycarbonate/aerospace acrylic to validate weight and lifecycle claims before broad roll-out.
- Negotiate coating IP and service levels: When selecting suppliers, combine technical performance clauses with fixed lead-time SLAs and penalty structures tied to AOG-critical parts.
- Invest in predictive-inspection capability: Deploy inspection analytics that translate optical degradation signals into deterministic replacement triggers to reduce unnecessary replacements and AOG events.
- Build partnership options for emerging platforms: For players evaluating eVTOL or urban air mobility exposure, secure option agreements with suppliers experienced in cross-platform transparencies to preserve first-mover advantages.
How PW Consulting supports execution
Our practice couples the market report with hands-on implementation services: supplier selection workshops, MRO process redesign, and certification support planning. For investors, we provide acquisition diligence packets that include forecast sensitivity tables, margin normalization scenarios, and integration risk readouts. The full report also contains red-teamed counterarguments and governance checklists that help boards and investment committees debate the trade-offs inherent in material transitions and aftermarket commitments.
Conclusion — next steps
For executives setting strategy in 2026, the aircraft windows market offers attractive, predictable opportunities: stable growth, recurring aftermarket revenue, and technology-driven differentiation. The nuanced choices — which materials to endorse, which suppliers to partner with, and how to structure aftermarket economics — will determine which organizations convert market expansion into sustainable margins. PW Consulting’s Worldwide Aircraft Windows Market report provides the analytical foundation and practical toolkits to make those decisions with confidence. To access the full dataset, supplier scorecards, and the redacted segmentation tables that support scenario modeling, please consult the report page and accompanying annexes for subscription access.
For detailed analysis of this topic, please visit the official page: Worldwide Aircraft Windows Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Report: Worldwide Portable Chromatography Systems Market Poised to Grow at 5.86% CAGR During 2026–2032
By pmarketresearch, 2026-08-12
Worldwide Portable Chromatography Systems Market — Strategic Implications for 2026
PW Consulting’s new market study on Worldwide Portable Chromatography Systems synthesizes five years of historical performance (2020–2025) and a forward-looking forecast (2026–2032) to deliver a pragmatic, decision-oriented playbook for executives entering or expanding in this fast-maturing segment. The sector is on a steady growth trajectory — our forecast reflects a compound annual growth rate (CAGR) of 5.86% from 2026 through 2032 and a market that reaches approximately USD 1.5 billion by 2032. The 2025 intermediate milestone sits just above the USD 1.0 billion mark, and 2026 is modeled as an inflection year in which several technology, regulatory and commercial vectors converge to re-shape competitive advantage.
Worldwide Acid and Alkali Etching Resistant Ink Market
Why this report matters for 2026 decision-makers
- Strategic timing: 2026 is a pivot year for field-deployable analytics. Vendors and buyers who align product roadmaps, channel strategies and regulatory preparedness now will capture disproportionate share as adoption accelerates.
- Investment prioritization: With predictable mid-single-digit CAGR ahead, capital allocation must target margin-enhancing features — battery operation, modularity, cloud-native data handling, and consumables lock-in — rather than broad-based capacity expansion.
- Procurement and TCO: Total cost of ownership in field chromatography increasingly favors integrated service models. Buyers should move beyond purchase-price analysis to lifecycle ROI that accounts for consumables, calibration, field service and data compliance.
- Regulatory gatekeeping: Compliance posture (ISO lab accreditation, medical-device versus research-use designations, regional CE/510(k) clearances) directly impacts addressable market and time-to-revenue. This is a make-or-break axis for 2026 go-to-market plans.
What the report delivers — practical outputs for immediate use
- Actionable forecasting: A reproducible market model with top-line scenarios (baseline, upside, downside) and sensitivity levers for pricing, adoption latency, and service revenue conversion. Note: this press release highlights macro trajectory; the report contains the full segment-level tables and interactive dashboards.
- Vendor benchmarking and capability maps: Side-by-side assessments of leading OEMs on portability, throughput, analytical performance, software & connectivity, aftermarket economics and field-readiness.
- Commercial playbooks: Pricing templates, channel strategies (direct vs distributor), tender playbooks for public sector and defense, and sales enablement materials tailored to environmental, forensic, food-safety and clinical prospects.
- Procurement & CAPEX/OPEX tools: TCO calculators, consumables burn-rate models, and outsourcing vs in-house analytics decision trees for sample-to-answer deployments.
- Regulatory and reimbursement checklist: A concise compliance roadmap covering ISO 15189, device labeling distinctions, applicable CPT codes and regional certification timelines to de-risk commercialization.
- Risk register and mitigation playbooks: Supply chain contingencies (critical raw materials pricing), IP/standards risks, and practical mitigation actions prioritized for 2026.
- Primary-case studies: Field deployments with quantified ROI, service-delivery models, and lessons learned from early-adopter programs.
Competitive landscape — interpretive analysis (what leaders are betting on)
The incumbent technology OEMs are rapidly converting laboratory-grade heritage into field-proven platforms. Our competitive review focuses on capability differentiation, route-to-market effectiveness, and aftermarket monetization potential.
Worldwide Asphalt Crushers Market
- Agilent Technologies (Santa Clara, CA) — Building on lab-grade LC strengths, Agilent’s portable LC configurations and microfluidic chip solutions position it as a leader for high-precision field pharma and forensic workflows. Recent product launches emphasize battery operation and ruggedized form-factors; their challenge is translating premium lab perception into economical field propositions.
- Thermo Fisher Scientific (Waltham, MA) — Thermo’s modular approach across UHPLC and ion chromatography targets environmental and regulatory monitoring customers who require certified workflows. Regulatory milestones (recent EU clearances on portable IC upgrades) reduce market friction in highly regulated pockets and accelerate procurement cycles.
- Waters Corporation (Milford, MA) — Waters is leveraging compact UPLC platforms and bioanalysis miniaturization to win field-deployable clinical and life-sciences contracts. Strengths include high-accuracy analytics and established relationships in regulated laboratories; the key to broader adoption is simplifying user experience for non-specialist field operators.
- Shimadzu Corporation (Kyoto, Japan) — Shimadzu’s portable UHPLC showcases a strong value proposition for food-safety and on-site testing with new autosampler capabilities demonstrated at major trade shows. Their global channel footprint and local service network are competitive advantages in distributed markets.
- PerkinElmer (Waltham, MA) — With cart-based LC-MS systems, PerkinElmer plays to markets where mobility is essential but lab-grade analytics must be preserved. Their focus on integrated sample-to-answer chemistries creates stickiness with end-users dependent on validated methods.
- Scion Instruments (Livingston, UK) — A niche innovator in portable GC modules, Scion’s modular philosophy and smaller scale permit rapid iteration for energy and environmental use-cases. Their route to scale will depend on alliances with larger instrument OEMs or value-added resellers.
Market concentration metrics indicate a moderately consolidated market: the top three players capture a material portion of the market, while the top five extend control to a clear majority. This structure favors strategic partnerships, selective M&A, and a two-tier market for premium vs. cost-optimized solutions.
Worldwide Stainless Steel Lunch Container Market
Regulatory, reimbursement and standards dynamics to factor into 2026 plans
- Accreditation and lab standards: ISO 15189:2022 accreditation norms increasingly apply to clinical deployments of portable systems, imposing QA program requirements and documentation burdens that should be anticipated during product development.
- Reimbursement signals: Diagnostic and outpatient reimbursement frameworks — exemplified by CPT code coverage relevant to column chromatography procedures — create new payor pathways. Vendors should evaluate whether device profiles can be positioned to access these billing avenues.
- Device labeling constraints: Regulatory guidance limits the marketing of “research use only” portable GC systems for diagnostic claims in many jurisdictions; firms must architect parallel regulatory strategies for research vs clinical claims to avoid market access bottlenecks.
Supply chain realities and input-cost pressure
Critical material inputs are not trivial; for example, medical-grade PEEK tubing — required for USP/ISO-compliant LC fluidics — carries a premium that materially affects unit economics (sector pricing benchmarks indicate a range of approximately USD 50–100 per meter for USP Class VI-compliant tubing). For manufacturers and procurement leads, this implies three immediate actions: secure strategic sourcing agreements, design for material flexibility without compromising compliance, and evaluate partial vertical integration for high-volume consumables to protect margins.
Actionable recommendations for 2026 (prioritized)
- Q1–Q2 2026 — De-risk & prepare: Finalize regulatory pathways for target geographies; run reimbursement feasibility for clinical use-cases; lock in critical consumable contracts with tier-1 suppliers; and pilot two site-specific field deployments to validate service models.
- Mid-2026 — Commercialize and scale selectively: Launch modular offerings tailored to 2–3 prioritized verticals where the required compliance posture and willingness-to-pay align. Deploy outcome-based contracts (subscription or equipment-as-a-service) in parallel to capture recurring revenue.
- Late 2026 and beyond — Expand and consolidate: Pursue bolt-on M&A to acquire complementary field-proven modules, software analytics, or service networks. Invest in digital data pipelines and remote calibration capabilities to minimize on-site service costs and improve unit economics.
How to use the full report
This press briefing intentionally highlights our strategic conclusions and the macro market trajectory while withholding detailed segment tables and vendor market-share schedules that many executives rely upon to finalize procurement and investment decisions. The full PW Consulting report includes granular segmentation by product, region and end-user, downloadable financial models denominated in USD (revenue unit: Million), a database of primary interviews and R&D roadmaps from OEMs, and an interactive scenario builder tailored for M&A due diligence and capital planning.
For firms planning tactical moves in 2026 — including OEM product launches, distributor partnerships, private equity diligence or government procurement bids — the full dataset and playbooks in the report provide the operational detail necessary to act with confidence.
To obtain the complete study, proprietary vendor scorecards, and the downloadable forecast workbook that powers our recommendations, please visit the PW Consulting report page (link in the official release). PW Consulting stands ready to support bespoke diligence, ROI modeling, and go-to-market execution for organizations preparing to compete effectively in the portable chromatography landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Chromatography Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com