

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting Report: Worldwide Portable Chromatography Systems Market Poised to Grow at 5.86% CAGR During 2026–2032

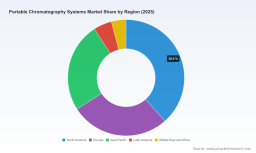
Worldwide Portable Chromatography Systems Market — Strategic Implications for 2026
PW Consulting’s new market study on Worldwide Portable Chromatography Systems synthesizes five years of historical performance (2020–2025) and a forward-looking forecast (2026–2032) to deliver a pragmatic, decision-oriented playbook for executives entering or expanding in this fast-maturing segment. The sector is on a steady growth trajectory — our forecast reflects a compound annual growth rate (CAGR) of 5.86% from 2026 through 2032 and a market that reaches approximately USD 1.5 billion by 2032. The 2025 intermediate milestone sits just above the USD 1.0 billion mark, and 2026 is modeled as an inflection year in which several technology, regulatory and commercial vectors converge to re-shape competitive advantage.
Worldwide Acid and Alkali Etching Resistant Ink Market
Why this report matters for 2026 decision-makers
- Strategic timing: 2026 is a pivot year for field-deployable analytics. Vendors and buyers who align product roadmaps, channel strategies and regulatory preparedness now will capture disproportionate share as adoption accelerates.
- Investment prioritization: With predictable mid-single-digit CAGR ahead, capital allocation must target margin-enhancing features — battery operation, modularity, cloud-native data handling, and consumables lock-in — rather than broad-based capacity expansion.
- Procurement and TCO: Total cost of ownership in field chromatography increasingly favors integrated service models. Buyers should move beyond purchase-price analysis to lifecycle ROI that accounts for consumables, calibration, field service and data compliance.
- Regulatory gatekeeping: Compliance posture (ISO lab accreditation, medical-device versus research-use designations, regional CE/510(k) clearances) directly impacts addressable market and time-to-revenue. This is a make-or-break axis for 2026 go-to-market plans.
What the report delivers — practical outputs for immediate use
- Actionable forecasting: A reproducible market model with top-line scenarios (baseline, upside, downside) and sensitivity levers for pricing, adoption latency, and service revenue conversion. Note: this press release highlights macro trajectory; the report contains the full segment-level tables and interactive dashboards.
- Vendor benchmarking and capability maps: Side-by-side assessments of leading OEMs on portability, throughput, analytical performance, software & connectivity, aftermarket economics and field-readiness.
- Commercial playbooks: Pricing templates, channel strategies (direct vs distributor), tender playbooks for public sector and defense, and sales enablement materials tailored to environmental, forensic, food-safety and clinical prospects.
- Procurement & CAPEX/OPEX tools: TCO calculators, consumables burn-rate models, and outsourcing vs in-house analytics decision trees for sample-to-answer deployments.
- Regulatory and reimbursement checklist: A concise compliance roadmap covering ISO 15189, device labeling distinctions, applicable CPT codes and regional certification timelines to de-risk commercialization.
- Risk register and mitigation playbooks: Supply chain contingencies (critical raw materials pricing), IP/standards risks, and practical mitigation actions prioritized for 2026.
- Primary-case studies: Field deployments with quantified ROI, service-delivery models, and lessons learned from early-adopter programs.
Competitive landscape — interpretive analysis (what leaders are betting on)
The incumbent technology OEMs are rapidly converting laboratory-grade heritage into field-proven platforms. Our competitive review focuses on capability differentiation, route-to-market effectiveness, and aftermarket monetization potential.
Worldwide Asphalt Crushers Market
- Agilent Technologies (Santa Clara, CA) — Building on lab-grade LC strengths, Agilent’s portable LC configurations and microfluidic chip solutions position it as a leader for high-precision field pharma and forensic workflows. Recent product launches emphasize battery operation and ruggedized form-factors; their challenge is translating premium lab perception into economical field propositions.
- Thermo Fisher Scientific (Waltham, MA) — Thermo’s modular approach across UHPLC and ion chromatography targets environmental and regulatory monitoring customers who require certified workflows. Regulatory milestones (recent EU clearances on portable IC upgrades) reduce market friction in highly regulated pockets and accelerate procurement cycles.
- Waters Corporation (Milford, MA) — Waters is leveraging compact UPLC platforms and bioanalysis miniaturization to win field-deployable clinical and life-sciences contracts. Strengths include high-accuracy analytics and established relationships in regulated laboratories; the key to broader adoption is simplifying user experience for non-specialist field operators.
- Shimadzu Corporation (Kyoto, Japan) — Shimadzu’s portable UHPLC showcases a strong value proposition for food-safety and on-site testing with new autosampler capabilities demonstrated at major trade shows. Their global channel footprint and local service network are competitive advantages in distributed markets.
- PerkinElmer (Waltham, MA) — With cart-based LC-MS systems, PerkinElmer plays to markets where mobility is essential but lab-grade analytics must be preserved. Their focus on integrated sample-to-answer chemistries creates stickiness with end-users dependent on validated methods.
- Scion Instruments (Livingston, UK) — A niche innovator in portable GC modules, Scion’s modular philosophy and smaller scale permit rapid iteration for energy and environmental use-cases. Their route to scale will depend on alliances with larger instrument OEMs or value-added resellers.
Market concentration metrics indicate a moderately consolidated market: the top three players capture a material portion of the market, while the top five extend control to a clear majority. This structure favors strategic partnerships, selective M&A, and a two-tier market for premium vs. cost-optimized solutions.
Worldwide Stainless Steel Lunch Container Market
Regulatory, reimbursement and standards dynamics to factor into 2026 plans
- Accreditation and lab standards: ISO 15189:2022 accreditation norms increasingly apply to clinical deployments of portable systems, imposing QA program requirements and documentation burdens that should be anticipated during product development.
- Reimbursement signals: Diagnostic and outpatient reimbursement frameworks — exemplified by CPT code coverage relevant to column chromatography procedures — create new payor pathways. Vendors should evaluate whether device profiles can be positioned to access these billing avenues.
- Device labeling constraints: Regulatory guidance limits the marketing of “research use only” portable GC systems for diagnostic claims in many jurisdictions; firms must architect parallel regulatory strategies for research vs clinical claims to avoid market access bottlenecks.
Supply chain realities and input-cost pressure
Critical material inputs are not trivial; for example, medical-grade PEEK tubing — required for USP/ISO-compliant LC fluidics — carries a premium that materially affects unit economics (sector pricing benchmarks indicate a range of approximately USD 50–100 per meter for USP Class VI-compliant tubing). For manufacturers and procurement leads, this implies three immediate actions: secure strategic sourcing agreements, design for material flexibility without compromising compliance, and evaluate partial vertical integration for high-volume consumables to protect margins.
Actionable recommendations for 2026 (prioritized)
- Q1–Q2 2026 — De-risk & prepare: Finalize regulatory pathways for target geographies; run reimbursement feasibility for clinical use-cases; lock in critical consumable contracts with tier-1 suppliers; and pilot two site-specific field deployments to validate service models.
- Mid-2026 — Commercialize and scale selectively: Launch modular offerings tailored to 2–3 prioritized verticals where the required compliance posture and willingness-to-pay align. Deploy outcome-based contracts (subscription or equipment-as-a-service) in parallel to capture recurring revenue.
- Late 2026 and beyond — Expand and consolidate: Pursue bolt-on M&A to acquire complementary field-proven modules, software analytics, or service networks. Invest in digital data pipelines and remote calibration capabilities to minimize on-site service costs and improve unit economics.
How to use the full report
This press briefing intentionally highlights our strategic conclusions and the macro market trajectory while withholding detailed segment tables and vendor market-share schedules that many executives rely upon to finalize procurement and investment decisions. The full PW Consulting report includes granular segmentation by product, region and end-user, downloadable financial models denominated in USD (revenue unit: Million), a database of primary interviews and R&D roadmaps from OEMs, and an interactive scenario builder tailored for M&A due diligence and capital planning.
For firms planning tactical moves in 2026 — including OEM product launches, distributor partnerships, private equity diligence or government procurement bids — the full dataset and playbooks in the report provide the operational detail necessary to act with confidence.
To obtain the complete study, proprietary vendor scorecards, and the downloadable forecast workbook that powers our recommendations, please visit the PW Consulting report page (link in the official release). PW Consulting stands ready to support bespoke diligence, ROI modeling, and go-to-market execution for organizations preparing to compete effectively in the portable chromatography landscape.
For detailed analysis of this topic, please visit the official page: Worldwide Portable Chromatography Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com