

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Global Electric Ambulance Stretchers Market to Rise from USD 560.0M in 2025 to USD 979.19M by 2032 at an 8.31% CAGR — North America Tops with USD 236.05M

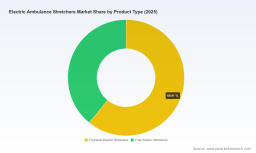
Worldwide Electric Ambulance Stretchers Market — Strategic Preview for 2026 Decision-Makers
PW Consulting’s latest market study on the Worldwide Electric Ambulance Stretchers market delivers a concise, decision-ready briefing for executives planning capital allocation, product development, procurement, and M&A activity in 2026. The sector has completed a meaningful multi-year expansion: global market revenue grew from approximately USD 385.1 Million in 2020 to USD 560.0 Million in 2025, and our modeling projects continued momentum through the new forecast window. Over the 2026–2032 forecast period the market is expected to grow at a compound annual growth rate (CAGR) of 8.31%, reaching roughly USD 979.2 Million by 2032. These headline figures frame a clear commercial opportunity — and the report drills into the operating levers that will determine which players capture the majority of incremental value.
Worldwide Lactic Acid Polymers Market
Why this matters for 2026 strategy
-
Capital deployment windows are opening across EMS fleets and hospital systems: procurement cycles initiated in 2024–2025 are delivering replacement and expansion orders in 2026. Organizations that align product roadmaps, pricing, and service propositions to fleet procurement timetables will materially improve win rates.
Worldwide Integration Brokerage Software Market -
Technology convergence is shifting purchase criteria from purely mechanical reliability toward integrated fleet management, battery performance and operator ergonomics. Buyers are increasingly valuing telematics-enabled asset management and total cost of ownership (TCO) reductions tied to lower operator injuries and faster turnaround times.
Worldwide IoT Modules Market -
Regulatory and procurement channels remain decisive. While powered wheeled stretchers are exempt from FDA 510(k) premarket notification requirements for Class II devices, compliance expectations remain high: crashworthiness and electrical safety standards (e.g., SAE J3027, BS EN 1789, IEC 60601-1) are baseline requirements in many markets. U.S. federal procurement pathways (including GSA schedules) still materially influence competitive positioning for vendors seeking national-scale contracts.
Market structure and competitive dynamics — what the headlines hide
Market concentration in this sector is meaningful. Our analysis shows a high three-firm concentration and an even higher five-firm concentration (CR3 ~68.5%; CR5 ~79.2%), signaling an oligopolistic structure with a small number of established global suppliers and a larger tail of regional OEMs. That concentration underscores two practical implications for strategy in 2026:
-
Large fleet contracts and specification-led buying favor established brands with demonstrable compliance, service networks, and validated field performance.
-
There is still room for niche entrants and regional manufacturers to win share through targeted differentiation — cost-competitive solutions, integration with local EMS practices, or superior aftermarket service bundles.
On the supplier side, the competitive set blends large multinational medical device companies and specialist OEMs. Notable players included in our landscape mapping include Stryker Corporation and Ferno-Washington (with extensive traction in fleet contracts and product innovation), European manufacturers focused on ergonomics and standards compliance, and a cluster of Chinese and regional producers emphasizing cost competitiveness and local distribution. Our report contains benchmarking plates that compare feature sets, standards compliance, warranty and service footprints, and fleet-reference evidence — but, in keeping with this preview, we intentionally omit full supplier scorecards and line-item revenue splits from this release.
Recent signals that will shape 2026 procurement and product roadmaps
-
Major fleet awards and procurement pilots are accelerating adoption cycles. For example, a large U.S. fleet recently awarded a multi-hundred-unit powered-stretcher contract following a rigorous RFP and field validation process — a reminder that end-to-end support, installation and fastening-system compatibility often decide large buys.
-
Manufacturers continue to refine manuals and operational guidance, reflecting an emphasis on lifecycle support and safety training as differentiators in procurement evaluations.
-
Independent market surveys and government acquisition programs are increasingly cataloguing available powered gurneys, which tends to standardize buyer expectations and reduce time-to-award for vendors that demonstrate tech maturity and compliance.
Key strategic imperatives for manufacturers and buyers
Our fieldwork, buyer interviews, and quantitative modeling identify six priority actions that will deliver disproportionate value in 2026:
-
Prioritize service-enabled differentiation. Manufacturers with integrated fleet telematics, rapid-response spare parts logistics, and structured preventive maintenance programs win longer-term contracts and command pricing premiums.
-
Invest selectively in battery and powertrain innovation. Improvements in battery density, charging cycle life, and hot-swap architectures materially reduce downtime and TCO for fleet operators — and represent high-leverage R&D investments.
-
Align product portfolios with procurement realities. Certification and crash-testing evidence should be ready for RFP submission; compatibility with vehicle fastening systems and stretcher load standards will be non-negotiable in most large tenders.
-
Build go-to-market plays for public-sector channels. For vendors seeking to scale in the U.S., getting onto GSA or equivalent national procurement lists is often a gating factor for large awards.
-
Design aftermarket and financing programs for cash-constrained buyers. Leasing, fleet-as-a-service and bundled maintenance arrangements lower acquisition barriers and increase lifecycle revenue capture.
-
Monitor adjacent innovation vectors. Autonomous loading aids, enhanced crash-energy management, and connected-patient monitoring integration are nascent features that will shift buyer preferences in the medium term.
Competitive profiles — where incumbents and challengers are placing bets
Our competitive deep-dive synthesizes product engineering claims, fleet references, and recent commercial activity. Without reproducing our full vendor scorecards, observe the following high-level takeaways:
-
Stryker Corporation: Strong in fleet-grade integrated cots with telematics capabilities and proven crash-compliant designs — an advantaged position for large institutional buyers and public-sector contracts.
-
Ferno-Washington, Inc.: Demonstrates a two-pronged strategy of product breadth and deep field validation; recent major fleet awards underscore its credibility in U.S. EMS procurements.
-
EU-based manufacturers (representative example): Emphasize ergonomics, compliance with European standards, and ease of technician use — attractive to continental ambulance services and private hospital groups.
-
Regional Chinese OEMs: Compete primarily on cost and fast OEM-to-fleet delivery; increasingly visible in emerging market tenders and price-sensitive segments.
The PW Consulting report provides an actionable competitor playbook — comparative product matrices, procurement win themes, and target-account lists — but these deliverables are reserved for the full report to preserve client value.
Report scope — operationally useful deliverables
This study is explicitly structured to support 2026 execution. Key deliverables include:
-
Market sizing and forecast model (historic 2020–2025, base year 2025, detailed 2026–2032 scenarios) with sensitivity analysis and upside/downside scenarios tied to battery-cost trajectories and public procurement intensity.
-
Procurement playbook for fleet buyers — RFP templates, evaluation scorecards, and TCO calculators to compare competing offers on lifecycle rather than sticker price.
-
Competitive benchmarking plates covering crash standard compliance, telematics capabilities, warranty and service economics, and fleet-referenced reliability data.
-
Supply-chain and manufacturing risk map, highlighting critical components (batteries, actuators, fastening systems) and recommended mitigation strategies.
-
Go-to-market blueprints for market entrants, including channel partnerships, regional regulatory checklists, and a prioritized list of tender targets.
Note: while this public preview presents headline market size and growth rates, detailed regional, product-type and end-user revenue splits — and the granular company-by-company revenue tables and scorecards — are omitted from this release to preserve the report’s commercial intelligence value. Readers seeking those tables and the model workbook will find them in the full report and dataset package.
Practical next steps for executives
-
Vendors: Initiate rapid-gap assessments against the procurement playbook. Prioritize investments that directly impact total cost of ownership (service networks, battery lifecycle programs, telematics) and prepare GSA-equivalent dossiers if pursuing public sector contracts.
-
Buyers (EMS and hospitals): Move evaluation criteria from upfront cost to measurable TCO outcomes. Require telematics and maintenance KPIs in RFPs and negotiate performance-based service terms.
-
Private equity and corporates: Target M&A and minority investments in high-service regional specialists to accelerate market share expansion or access new distribution channels — use CR3/CR5 concentration dynamics to assess consolidation payoff.
How PW Consulting can help
PW Consulting offers tailored strategic support for market entry, M&A diligence, product portfolio prioritization and procurement advisory. For companies setting 2026 budgets and roadmaps, our full report and accompanying dataset provide the revenue granularity, supplier scorecards and TCO models required to make confident decisions. To access the complete study, model workbook, and bespoke advisory options, please visit the report landing page or contact our engagement team for a briefing.
In an industry where safety standards, fleet economics and operational reliability converge, pragmatic strategy and timely execution will determine which organizations lead over the coming six-year growth window. This preview highlights the high-level contours — the full PW Consulting report supplies the calibrated intelligence to act.
For detailed analysis of this topic, please visit the official page: Worldwide Electric Ambulance Stretchers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com