

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide Laminating Lithium‑ion Capacitor Market Poised to Reach USD 1,500.67 Million by 2032 (Forecast 2026–2032)

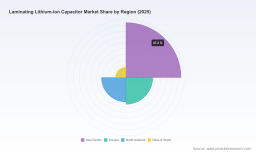
Worldwide Laminating Lithium‑ion Capacitor Market — Strategic Intelligence for 2026 Decision‑Makers
PW Consulting today releases a forward‑looking industry brief drawn from our comprehensive report, Worldwide Laminating Lithium‑ion Capacitor Market (base year 2025). With the laminated lithium‑ion capacitor (LIC) sector entering a rapid growth phase, boards, corporate strategists and investors must recalibrate manufacturing footprints, supplier relationships and product roadmaps now to capture scale and margin as the market expands. This executive announcement highlights the strategic levers and actionable implications contained in the full study while deliberately preserving the report’s detailed segmentation and proprietary model outputs for subscribers.
Worldwide Nonprofit Payment Gateway Software Market
Why 2026 is a Strategic Inflection Point
Our market model — built on five years of historical observation and seven years of scenario forecasting — shows the laminated LIC market accelerating from an estimated USD 456.28 Million in 2025 to USD 540.87 Million in 2026, with a compound annual growth rate (CAGR) of 18.54% across the 2026–2032 forecast window. Underpinning this growth are converging demand signals from renewable energy, industrial automation, transportation electrification and grid modernization, alongside manufacturing innovations that reduce cost and raise energy density.
Worldwide Cherry Oil Market
For 2026 planning cycles, that growth profile creates a short window for capacity investments that will determine which suppliers secure OEM partnerships and project pipelines through the end of this decade. The headline numbers in the full PW Consulting report quantify revenue pools by use case and technology variant, but the strategic insight we present here is directional: 2026 is the year to decide whether to invest for share in an expanding pie or to adopt an asset‑light, partnership‑first play.
Endocrine Disruptor Testing Market
What the Full Report Enables — Practical, Transactional Intelligence
- Robust market sizing and top‑down revenue pools by use case and product architecture, with sensitivity scenarios that stress-test price, raw material and adoption assumptions.
- Supply chain and cost‑build analyses that identify critical inputs, cost thresholds and supplier concentration risk across electrode materials, lithium pre‑doping and laminated cell assembly.
- Technology roadmaps comparing laminated LIC constructions versus alternative formats, with implications for manufacturing capital intensity, yield, and integration with existing lithium‑ion battery lines.
- Competitive benchmarking and capability matrices for leading LIC players, including manufacturing footprint, product formats, validated applications and strategic partnerships.
- Commercial playbooks for OEM engagement, channel strategies for utilities and industrial customers, and template commercial terms for licensing, co‑development and toll manufacturing.
- M&A and investment screening tools with target profiles, valuation sensitivities and integration checklists tailored to LIC subsegments.
These deliverables make the report tactical for 2026: procurement teams can set multi‑year contracts with material suppliers; R&D leaders can prioritize pre‑doping and laminated electrode process investments; and corporate development teams can identify acquisition targets that plug capability gaps without overpaying for underutilized capacity.
Key Strategic Dynamics Shaping Decisions in 2026
- Manufacturing modality and scale: Laminated cell production benefits from processes similar to Li‑ion pouch manufacturing, which creates optionality for players with existing battery lines. Strategic choices include retrofitting existing Li‑ion lines, investing in dedicated laminated LIC capacity, or outsourcing via toll‑manufacturing partnerships.
- Raw material economics and feedstock concentration: LIC performance hinges on activated carbon for electrodes and lithium pre‑doping. Industry sourcing is concentrated in biomass‑derived activated carbon, which dominated supercapacitor feedstocks in recent years. Cost thresholds materially affect unit economics — supply disruptions or price spikes will rapidly compress margins for low‑value, thin‑margin applications.
- Process innovations and licensing: Recent licensing of lithium pre‑doping methods enables some manufacturers to adopt lower‑cost production flows using standard Li‑ion equipment. Adopting proven pre‑doping routes or securing exclusive arrangements will be a differentiator for scale players.
- Geopolitical and tariff pressures: Tariff regimes and geopolitical risks are driving nearshoring decisions and supplier diversification for critical materials. Companies must model alternative sourcing scenarios and inventory buffers as part of 2026 procurement plans.
- Concentration and consolidation: The sector shows moderate concentration at the top of the market, leaving room for both strategic partnerships and bolt‑on acquisitions. Expect continued consolidation as incumbents and strategic investors compete to secure module‑level solutions for transportation and grid applications.
Competitive Landscape — Who to Watch
The report includes detailed profiles of the market’s core players and their strategic postures. Highlights for 2026 guidance:
- LICAP Technologies, Inc. (Sacramento, USA): Focused on dry electrode and activated dry electrode manufacturing, LICAP has recently scaled domestic capacity and pursued collaborations to adapt dry electrode routes for laminated LIC production. Their expansion and OEM collaborations make them a leading innovator for high‑throughput pouch‑compatible electrode processes.
- Musashi Energy Solutions Co., Ltd. (Japan): With established mass production of laminated and prismatic hybrid supercapacitors, Musashi’s safety and compliance achievements reinforce their play in stationary and industrial ESS markets. They represent a low‑execution‑risk partner for integrators seeking certified systems.
- SPEL Technologies (India): A key supplier of thin, laminated pouch formats, SPEL’s small‑form‑factor approach and cost competitiveness position them well for telecom backup and light industrial applications where form factor and cost are paramount.
- VINATech (Korea/Vietnam) and JTEKT (Japan): Both are pursuing hybrid designs and efficient, smart factory production. Their emphasis on low leakage and manufacturing automation addresses the yield and quality constraints that matter most at scale.
- Other notable participants: Specialty manufacturers across China, Japan, South Korea and Europe provide complementary capacity and local market access. The competitive map in the full report includes capability scoring, channel strengths and recent corporate developments.
Recent corporate moves underscore the near‑term strategic dynamics: domestic facility expansions, manufacturing collaborations with OEMs, and product certifications for energy storage systems have shifted the operational baseline. These developments are catalogued and interpreted in the report to help buyers assess counterparty risk and execution timelines.
Actionable Recommendations for 2026 Planning
Based on our scenarios and supplier assessments, PW Consulting recommends that executives consider the following actions this planning cycle:
- Decide capacity posture early: Lock in or commit to modular capacity increases now if your ambition is to capture system‑level contracts in transportation or grid services. Lead times for qualified laminated LIC production — from line commissioning to qualified yields — are measurable in quarters, not weeks.
- Secure raw material optionality: Negotiate multi‑tier supply agreements for activated carbon and lithium precursors, and colocate inventory options with strategic suppliers. Consider alternative activated carbon feedstocks and invest in supplier development to reduce exposure to single‑source shocks.
- Pursue selective licensing and partnerships: Licensing pre‑doping or dry electrode manufacturing technologies can be faster and less capital‑intensive than greenfield investments; evaluate licensing terms against projected margin uplift and time to volume.
- Embed scenario planning into procurement: Stress test procurement contracts for tariff shocks and logistics disruptions. Nearshoring or regional manufacturing may justify higher short‑term capital spending to preserve long‑term customer access.
- Design for integration: Product roadmaps should prioritize module‑level standardization to lower integration friction with OEMs and energy integrators; standardized mechanical and electrical interfaces accelerate adoption.
Risk and Opportunity Matrix
The laminated LIC market offers high upside but also concentrated technical and supply risks. The key risk vectors we model for 2026 are raw material price shocks, yield and qualification delays, and geo‑political trade frictions. Countervailing opportunities come from scale economies, process licensing, and application wins in fast‑moving segments such as renewable energy buffer systems and traction‑adjacent power smoothing.
Our report presents probability‑weighted scenarios and an interactive sensitivity model enabling executives to quantify the value of mitigation options — for example, the trade‑off between capital invested in in‑house pre‑doping versus licensing a proven process.
How the Report Supports Transactional and Operational Decisions
- Commercial diligence for VC and corporate M&A teams: target shortlists, valuation sensitivities and integration risk scoring.
- Supply chain strategy for procurement: supplier scorecards, alternative sourcing maps and contract term templates.
- Manufacturing and CapEx planning for operations: build vs. buy analyses, retrofit cost curves and ramp‑to‑yield timelines.
- Product and business development playbooks for sales: use‑case prioritization, channel strategy and partner negotiation checklists.
Call to Action
PW Consulting’s Worldwide Laminating Lithium‑ion Capacitor Market report combines primary interviews, plant visits, supplier cost models and proprietary adoption modeling to translate macro growth into executable plans. For executives making 2026 commitments — from board‑level capital allocation to supply chain and product roadmap choices — the report supplies the empirical basis and strategic frameworks required to act with confidence.
Access to the full dataset, annotated competitive profiles, and the interactive sensitivity model is available through PW Consulting’s research portal. We invite decision‑makers to contact our team for a briefing and to request the subscriber pack, which includes the detailed segmentation outputs and client‑specific scenario runs that have been withheld here to protect the report’s proprietary value.
For detailed analysis of this topic, please visit the official page: Worldwide Laminating Lithium-ion Capacitor Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com