

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
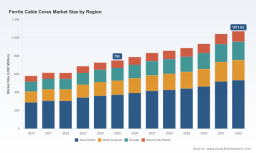
PW Consulting: Worldwide Ferrite Cable Cores Market to Grow from USD 750.0 Million in 2025 to USD 1,071.63 Million by 2032 at a 5.23% CAGR — Asia Pacific, Cylindrical Cores and Consumer Electronics to Dominate

Worldwide Ferrite Cable Cores Market 2026: A Strategic Playbook for Executive Decision-Making
Executive snapshot
As global electronics architectures accelerate toward higher data rates, electrification, and stricter electromagnetic compatibility (EMC) regimes, ferrite cable cores have shifted from commodity afterthoughts to strategic components. Our new PW Consulting report positions the Worldwide Ferrite Cable Cores Market as a steady-growth sector: the market reached approximately USD 750 million in the report base year (2025) and is forecast to expand at a compound annual growth rate (CAGR) of 5.23% over the 2026–2032 forecast period, moving toward a billion-dollar-plus industry by the horizon. This trajectory reflects blended demand from consumer devices, automotive electrification, data infrastructure, and industrial automation — and it carries concrete implications for procurement, product engineering, and M&A planning in 2026.
Electric Toothbrush Pressure Sensor Market
Why this market matters to corporate strategy in 2026
-
Component economics are now strategic levers. Ferrite cable cores influence system-level EMC performance, certification timetables, and, in certain architectures, perceived product quality. Minor changes in core formulation or geometry can materially affect compliance scope and rework costs.
Digital Supply Chain Finance (SCF) Solution Market -
Supply-chain fragility translates to program risk. Key raw inputs for ferrite—iron oxide, manganese and zinc—are sourced predominantly in a concentrated geography, exposing OEMs and tier suppliers to supply disruptions, trade actions and price volatility. In 2024–2025, policy shifts and material tightness fed through to higher unit costs and longer lead times for specific ferrite chemistries.
Automotive Multi-domain Fusion Market -
Technology waves create product bifurcation. Emerging high-speed standards, automotive Ethernet, EV charging, and expanded 5G bands are pushing demand for higher-permeability formulations and cores capable of suppressing noise well into the multi-gigahertz range. That is creating a premium tier of product and qualification requirements where suppliers with advanced materials and design capabilities can capture outsized margins.
Market trajectory and the near-term forecast
The market’s baseline in 2025 provides a pragmatic foundation: growth is reliable, not explosive. Our model projects a consistent expansion driven by steady replacement cycles in consumer electronics, accelerating electrification in transport, and infrastructure buildouts in data centers and telecom. The 5.23% CAGR we report accounts for cyclical device replacement, structural upgrades (e.g., USB4/PCIe Gen5, automotive-grade components), and incremental price inflation linked to raw material dynamics. For strategic planners, this means predictable addressable market growth but asymmetric upside concentrated in segments that demand specialized cores and fast qualification cycles.
Competitive landscape — positioning and tactical moves
The sector displays moderate concentration: a handful of global incumbents combine scale, material science capability, and channel access, while numerous regional and low-cost players address volume commodity demand. Market concentration metrics underline the dichotomy between scale and specialization; the top-tier suppliers retain meaningful presence, but there remains room for technology-focused entrants to carve niche leadership.
-
TDK Corporation (Tokyo) continues to invest in high-permeability snap-on solutions designed for next-generation telecom and automotive Ethernet applications, aligning product launches with 5G and high-speed cable trends. Recent introductions advertise suppression capabilities out to higher gigahertz bands, signaling clear R&D emphasis on advanced formulations and precision manufacturing.
-
Murata Manufacturing (Nagaokakyo) leverages strengths in compact bead and filter technologies to serve mobile, PC, and high-speed data cable markets. Their presence at trade venues underscores a go-to-market strategy that pairs miniaturization with integrated EMC solutions for space-constrained designs.
-
Laird Technologies (DuPont) has pursued automotive-grade validation, achieving certifications attractive to EV and charging-system OEMs. Such qualification is a high barrier to entry and a differentiator for suppliers targeting automotive Tier 1 relationships.
-
Fair-Rite and similarly specialized firms emphasize material breadth and catalog depth, supporting rapid design cycles for high-speed interfaces and niche industrial applications.
-
European and multinational players (e.g., Ferroxcube/Yageo, Vacuumschmelze, Mitsubishi Materials, Samsung Electro-Mechanics) combine regional manufacturing footprints with localized technical support — a compelling mix where tariff or logistics risk is elevated.
-
Low-cost and regional suppliers from Asia remain important for high-volume, price-sensitive cable assemblies, particularly in consumer and legacy industrial segments.
Recent supplier moves to watch
-
Product innovation is active: suppliers have announced new high-permeability snap-on cores and catalog updates explicitly address high-speed interfaces and automotive Ethernet needs.
-
Qualification matters: automotive-grade certifications for cable cores (e.g., AEC-Q200) are becoming a procurement prerequisite for EV and charging-system suppliers.
-
Trade-show activity and catalog refreshes point to supplier strategies that bundle design support with product breadth, reducing upstream engineering friction for OEMs adopting new standards.
Supply-chain dynamics and regulatory context
Procurement and program managers must read the supply environment carefully. The production chain for ferrite chemistry is concentrated in a limited set of geographies, and that concentration has been a vector for policy and price shocks. Trade measures implemented in recent years have had a direct effect on landed costs for certain import channels. Concurrently, regulatory constraints—most notably persistent restrictions on hazardous substances in electronics—require materials and processes that ensure compliance across global markets.
Practically, the market has seen unit-price inflation and extended lead times for specific ferrite types. Where nickel-zinc chemistries are required, buyers are experiencing substantially longer lead times. These dynamics make buffer strategies, second-source qualification, and early supplier engagement essential actions for 2026 program plans.
Strategic implications and recommended executive actions for 2026
-
Develop tiered procurement strategies: segment purchases into “qualified premium” (specialized, high-permeability cores for high-speed/automotive programs) and “volume commodity” lanes, and negotiate different contract structures accordingly.
-
Prioritize supplier qualification early: timelines for automotive and high-speed interface approvals can become the critical path on new product introductions. Build qualification gates into product roadmaps and invest in extended collaboration with material suppliers for joint testing.
-
Mitigate raw-material concentration risk: diversify material sources, consider strategic inventory for critical chemistries, and evaluate near-shore or regional production partnerships where tariff and logistics risk is material.
-
Pursue cost-to-serve optimization: where price sensitivity dominates, consider design simplification that reduces the number or complexity of cores per assembly; where performance is differentiated, invest in premium formulations and corresponding price capture strategies.
-
Monitor regulatory and standards evolution: EMC standards, RoHS-like restrictions, and automotive qualification standards will continue to shape allowable materials and testing requirements—early compliance planning reduces rework and avoids costly recalls.
-
Scan M&A selectively: mid-sized suppliers with unique material science capabilities or regional manufacturing footprints can be attractive bolt-on targets for companies aiming to secure technology or shorten supply chains.
What the PW Consulting report delivers (practical, on-the-desk tools)
-
Validated market sizing and a transparent forecasting model for 2026–2032, supporting scenario analysis across demand, pricing and lead-time sensitivities.
-
Competitive intelligence dossiers on the industry’s key players, including capabilities maps, recent product and certification moves, and strategic positioning assessments.
-
Supply-chain risk matrices that synthesize raw-material exposure, geopolitical and tariff risk, and supplier concentration into prioritized mitigation options.
-
Actionable procurement playbooks and qualification timelines tailored to automotive, data-communications and consumer-electronics programs.
-
Scenario-based recommendations for localization, inventory strategy and cost-recovery levers that facilities, sourcing and product teams can implement within 6–12 months.
-
Templates for commercial negotiations and technical specifications that reduce cycle time for new supplier integrations.
How to use this intelligence in 2026 planning cycles
Position the report as a planning asset: embed its forecast scenarios into your FY+1 budget, use supplier-risk scoring in your supplier-development plans, and prioritize core qualifications for any program with automotive or high-speed data requirements. For C-suite and board discussions, the material helps quantify the trade-offs between near-shoring, inventory expense and potential cost pass-through to OEM customers.
Final note — depth available, details reserved
This release outlines the strategic contours and practical actions executives should consider when ferrite cable cores intersect with their product roadmaps. PW Consulting’s full report contains the granular charts, regional breakouts, supplier scorecards and downloadable forecasting models that supply-chain, product and corporate-development teams need to execute. In keeping with our “trailer” approach, we have presented the strategic thrusts and operational imperatives here while reserving the full segmented datasets, appendices and proprietary models for the comprehensive report.
To access the complete Worldwide Ferrite Cable Cores Market report, with downloadable forecasting models and supplier dossiers, please visit PW Consulting’s market research portal or contact your PW Consulting account executive for institutional licensing and customized briefings tailored to your programs.
For detailed analysis of this topic, please visit the official page: Worldwide Ferrite Cable Cores Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com