

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
PW Consulting: Worldwide High-Speed Spectroscopy Cameras Market to Soar to USD 955.64 Million by 2032 (2026–2032 Forecast, 7.82% CAGR)

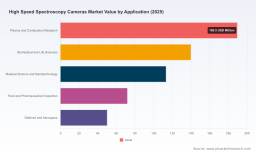
Worldwide High Speed Spectroscopy Cameras Market: Strategic Imperatives for 2026 Decision‑Makers
As PW Consulting’s lead industry analyst, I present a focused executive preview of our new market research report on the Worldwide High Speed Spectroscopy Cameras market. The study synthesizes multi‑year historical performance (2020–2025) and delivers a forward view for the 2026–2032 forecast period. We highlight the market’s scale, growth trajectory and the pragmatic intelligence procurement, product development and M&A teams will need to act confidently in 2026 — while intentionally withholding granular segment tables to encourage direct access to the full report for operational data.
Worldwide User Research Software Market
Market at a Glance: Scale and Momentum
The high speed spectroscopy cameras market has moved from a niche, research‑centric domain into a scalable industrial and clinical enabling layer. On a consolidated basis the market reached a notable milestone in our base year, with overall revenue crossing the mid‑hundreds (reported in USD Million for comparability). The market growth profile is robust: our modelling places the compound annual growth rate at 7.82% across the 2026–2032 forecast horizon, projecting the market to be substantially larger by the end of that period.
Worldwide IT Spending in Healthcare Market
Why this matters for 2026 planning: in absolute and relative terms the market is now large enough that product choices, procurement cycles and platform strategies materially affect P&L and technical roadmaps. Buyers must move from “technology evaluation” to “system integration and lifecycle planning” — and vendors must scale repeatable manufacturing, software ecosystems and regulatory readiness to capture value.
Dimming Power Supply Market
Why the 2026 Inflection Is Strategic
- Commercialization of lab‑grade performance. Advances in low‑noise sCMOS and compact SWIR solutions have pushed laboratory capabilities into clinical and factory floors. This is accelerating adoption curves in real‑time spectral analysis for medical diagnostics, industrial inspection and defense applications.
- CapEx windows and procurement behavior. Hospitals, instrument OEMs and high‑throughput factories are treating spectroscopy cameras as multi‑year platform buys rather than single‑project items. Expect procurement timelines to lengthen and specifications to tighten around integration, maintainability and service agreements.
- Convergence with multimodal systems. The strongest near‑term opportunities are in systems where spectroscopy cameras are integrated with imaging, AI inference engines and robotic handling — creating sticky ecosystems and higher lifetime revenue per deployment.
- Regulatory and quality thresholds matter. For medical device integration, compliance with ISO 13485 and common 510(k) pathways in the United States are gating factors. Vendors that embed regulatory design controls and verification artifacts into their product lifecycles will reduce customer adoption friction.
Report Deliverables: What Practitioners Will Find Inside
Our full report is intentionally practical and oriented toward immediate action. Key deliverables include:
- Scenario‑based demand models that map technology choices (e.g., high‑line‑rate sCMOS, EMCCD/ICCD, and InGaAs SWIR variants) to typical buyer journeys in clinical, industrial and research segments.
- Procurement playbooks for OEMs and end‑users: specification checklists, integration risk matrices, warranty and service models, and total cost of ownership templates calibrated for 2–7 year lifecycles.
- Regulatory readiness checklists and a decision tree for embedding cameras into medical devices — covering quality system inputs (ISO 13485), and the common FDA 510(k) considerations for Class II imaging systems.
- Commercial and pricing strategies for vendors: bundling architectures, software licensing models, and go‑to‑market frameworks optimized for hospital systems versus industrial integrators.
- A tailored M&A and partnership playbook: capability gaps to target, valuation accretive integration patterns and three‑tier acquisition scenarios mapped to revenue and IP synergies.
Competitive Landscape — Who Matters and Why
The market architecture is a mix of long‑standing specialist optics firms, scientific camera incumbents and agile hyperspectral OEMs. A few dynamics are decisive in 2026:
- Legacy scientific camera leaders (e.g., firms with deep engineering in sCMOS, EMCCD and cooled CCD platforms) retain strength where sensitivity and low noise remain the primary buyer requirements. These vendors benefit from established distribution into academic and clinical research labs and strong product roadmaps for incremental performance improvements.
- Hyperspectral and SWIR specialists are expanding into high‑speed, process‑grade systems suitable for inline inspection and material analysis. Their edge is optical system integration and domain‑specific software stacks that shorten time‑to‑value for industrial users.
- Miniaturized and OEM‑centric players are winning design‑in engagements where compact form factor, power efficiency and modularity are prioritized — especially for embedded medical devices and robotics.
Illustrative company positioning (high‑level, not exhaustive):
- Andor Technology (Oxford Instruments) — a go‑to for high‑sensitivity sCMOS, EMCCD and cooled CCD systems; strong in scientific and medical research channels with product families optimized for spectroscopy workflows.
- Teledyne Princeton Instruments — competitive in low‑noise, high‑throughput CCD/sCMOS offerings for Raman, hyperspectral and transient spectroscopy; well‑placed in life sciences imaging applications.
- Hamamatsu Photonics — leverages detector R&D and broad photonics product portfolio to serve near‑infrared spectroscopy and clinical imaging opportunities.
- HORIBA Scientific — focuses on cooled sCMOS cameras and integrated spectrometer solutions; strength in biomedical and clinical diagnostic instrument supply chains.
- Specim (Konica Minolta), Headwall, HySpex, Photon etc., XIMEA, BaySpec — these companies represent hyperspectral and compact OEM segments that are accelerating adoption in industrial inspection and medical spectral imaging through tailored optical modules and software toolchains.
Recent product announcements (early 2025–2026) underscore the rapid productization of SWIR and NIR‑SWIR push‑broom and rectangular‑pixel architectures, signaling that vendors are shifting from proof‑of‑concept demonstrations to deployable field units — an inflection that procurement and product teams must anticipate.
Operational Risks and Mitigations
- Integration risk: Optical, mechanical and software interfaces remain the most common source of schedule slippage. Mitigation: require vendor‑supplied integration kits, reference drivers and verified datasets as part of procurement contracts.
- Regulatory drift: Changes in regional device classification or coverage policies can alter reimbursement prospects for clinical applications. Mitigation: early engagement with regulatory consultants and payor strategy teams; maintain modularity so a camera can be reclassified without a full system redesign.
- Supply chain tightness: Advanced sensors and custom ROICs face allocation risks. Mitigation: multi‑sourcing strategies, buffer inventory planning and co‑development agreements with foundries or sensor manufacturers.
- Software lock‑in: Proprietary processing stacks increase switching costs. Mitigation: prefer vendors that provide SDKs and documented APIs; require data‑format portability in contracts.
Actionable Recommendations for 2026 Planning
- Vendors (product teams): Prioritize modular platforms that separate sensor, optics and compute. Ship SDKs and certified integration kits. Make ISO 13485 alignment and 510(k) hygiene part of the product roadmap rather than an afterthought.
- OEMs and integrators: Redesign procurement to evaluate long‑term serviceability and AI inference readiness. Negotiate lifecycle pricing and upgrade paths that reflect sensor and algorithm obsolescence cycles.
- Healthcare providers and device OEMs: Map use cases to reimbursement pathways early. Invest in pilot deployments that capture clinical validation data and interoperability evidence for device submissions.
- Private equity and corporate development: Target acquisitions that provide software differentiation or application‑specific optics IP rather than solely sensor stockpiles. Look for partners with channel strength in high‑value verticals (medical, pharma inspection, defense).
What the Full Report Unlocks
This preview intentionally omits the granular regional, sensor and application split tables that many operational teams require to execute. The full PW Consulting report provides those segmentations, scenario‑based revenue forecasts in USD Million, pricing and margin benchmarks, and downloadable procurement templates. Those datasets are built from 2020–2025 historical performance and our 2026–2032 forecast model, enabling slice‑and‑dice analyses for product planning, territory strategies and investment due diligence.
Final Word: Position Early, Integrate Deep
2026 is the year to move from evaluation to platform deployment. The market’s growth trajectory gives both vendors and buyers a window to lock in advantageous commercial and technical positions — but only if organizations treat spectroscopy cameras as platforms requiring systems engineering, regulatory planning and commercial foresight. PW Consulting’s full report equips leaders with the actionable models, checklists and competitor intelligence to convert that opportunity into tangible revenue and improved clinical and industrial outcomes.
For access to the complete dataset, segmentation tables and vendor scorecards that underpin these conclusions, please visit our report page to request the full Worldwide High Speed Spectroscopy Cameras Market study.
For detailed analysis of this topic, please visit the official page: Worldwide High Speed Spectroscopy Cameras Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com