

@pmarketresearch
- Followers 0
- Following 0
- Updates 5116
Category: IT & Electronics
PW Consulting: Next-Gen Advanced Batteries to Reach USD 324M by 2032 (7.1% CAGR)
By pmarketresearch, 2026-07-13
Next-Generation Advanced Batteries Market — Strategic Preview for 2026 Decision-Makers
Executive snapshot
As governments and corporations pursue decarbonization and electrification, next-generation battery technologies have moved from laboratory promise to boardroom priority. PW Consulting’s latest market study — Next-Generation Advanced Batteries Market (base year 2025, forecast 2026–2032) — quantifies a clear upward trajectory: the global market expanded substantially through the first half of the decade and is projected to continue growing at a compound annual growth rate of approximately 7.1% across the forecast horizon. For executives planning capital allocation, strategic partnerships, or R&D roadmaps in 2026, this study reframes risk and opportunity with pragmatic, decision-grade insight.
Next-Generation Advanced Batteries Market
Why this preview matters for 2026 decisions
-
Timing matters: 2026 is the inflection year for many commercialization and scale-up milestones. Several pilot lines, validation programs, and gigafactory projects are transitioning toward industrialization, creating short windows to secure supply, intellectual property positions, and offtake arrangements.
Next-Generation Advanced Batteries Market -
Value at scale: while early-stage technologies still present execution risk, the market-size trajectory underscores material commercial potential. Our study translates macro momentum into portfolio-level consequences — which technology bets compress time-to-market, which require additional material-security measures, and which demand alternative go-to-market models.
Next-Generation Advanced Batteries Market -
Concentration and competitive dynamics: the market is meaningfully concentrated among a small set of frontrunners. The leading three firms control a dominant share of the market’s revenue and technology mindshare; the five largest firms widen that moat further. For incumbents and new entrants alike, understanding where the power centers sit is essential for negotiating JV terms, licensing deals, or vertical integration.
Market trajectory and macro context
From a quantifiable perspective, the global advanced-batteries market has more than recovered from pandemic-induced disruptions and is set on a sustained expansion path through 2032. The base-year assessment (2025) provides a robust benchmark for board-level scenario planning; the forecasted CAGR of about 7.1% reflects a market driven by transportation electrification, grid-scale storage needs, and incremental adoption across industrial and consumer segments. PW Consulting’s models integrate demand-side drivers, manufacturing scale economics, and technology learning curves to produce actionable topline forecasts and downside scenarios for 2026 planning cycles.
Key dynamics shaping 2026 strategy
-
Capital deployment and industrial policy: large-scale public and private investments have reshaped capacity expectations. A pronounced pipeline of announced manufacturing projects and significant federal funding streams have materially derisked certain buildout scenarios, but they also raise the stakes for choosing the right technology partners and geographic footprints.
-
Technology readiness vs. deployment cadence: advanced chemistries (e.g., solid-state, sodium-ion, metal-air variants) show differentiated maturation timelines. Several firms have moved from cell-level R&D into validation and pilot production, prompting a two-speed market where early commercial adopters will enjoy first-mover advantages if they can accept near-term premiums for performance.
-
Supply-chain and raw-material dynamics: upstream investments and new mining/processing capacity are changing availability patterns for critical inputs. At the same time, next-generation chemistries alter raw-material requirements — both an opportunity and a supply-chain re-engineering challenge.
-
Standardization and industrialization: pilot production counts and emerging roadmaps for solid electrolytes and related systems show that manufacturing know-how is consolidating. Standardization milestones and qualification roadmaps in 2026 will determine which platforms are scalable and which remain experimental.
-
Regulatory tailwinds: infrastructure and incentive policies continue to accelerate deployment. Recent legislative measures and funding programs have made battery manufacture and domestic supply-chain investments a strategic priority in several markets, altering cost, competitiveness, and partnership rationales.
Competitive landscape — who matters and why
Our competitive analysis synthesizes company-level strategy, technology readiness, and recent milestones to help buyers and investors prioritize engagements. Select examples from the report illustrate the diversity of strategic postures:
-
QuantumScape (San Jose, CA): pursuing lithium-metal solid-state cells with a focus on validating automotive-rate cycle life and integration with large OEM platforms. Recent cell validations at automotive discharge profiles underscore a pivot from lab proofs to vehicle-system validation.
-
Solid Power (Louisville, CO): specializing in all-solid-state lithium-metal cells for EVs and storage, with partnerships oriented toward automotive OEM qualification and scale-up support.
-
Enovix (Fremont, CA): advancing high-energy-density silicon-anode architectures with manufacturing designs optimized for compact, high-energy applications.
-
Factorial Energy and ProLogium: both prioritize solid-state approaches but differ in material pathways and commercialization strategies; one emphasizes material innovation to improve safety and scalability, while the other is actively executing on gigafactory buildouts in locations aimed at serving localized demand pools.
-
Ambri and Peak Energy: target long-duration and grid-focused applications with distinct chemistries (molten-salt, sodium-ion), representing an alternative risk/reward profile for system integrators and utilities.
-
Smaller technology suppliers (e.g., Natrion, SES AI) are important as enablers — supplying separators, electrolyte technologies, and cell designs that can be licensed or co-developed at scale.
These snapshots are expanded in the report with supplier maps, capability matrices, and scenario-tested competitive playbooks. Recent corporate events — from cell validation milestones to gigafactory announcements and pilot-line investments — are surfaced and interpreted for 2026 strategic action.
What PW Consulting’s full study delivers (practical content)
PW Consulting’s full report is designed as an operational toolkit for executives making capital and partnership decisions this year. It includes:
-
Granular, model-driven demand forecasts across the 2026–2032 horizon, accompanied by sensitivity analyses and downside stress cases to test portfolio robustness.
-
Technology readiness assessments and commercialization timelines: not just TRL scores, but manufacturability indices and capital-intensity profiles for alternate technology paths.
-
Supply-chain risk maps and raw-material scenarios that account for announced capacity pipelines, funding flows, and geopolitical variables.
-
Competitive benchmarking: R&D positioning, patent landscapes, and a “partner fit” matrix to fast-track M&A, JV, or licensing conversations.
-
Investment playbooks and project prioritization frameworks calibrated for CFOs and investment committees, with hurdle-rate and payback analyses tailored to different risk appetites.
-
Operational checklists for establishing pilot lines, transitioning to mass production, and accelerating qualification with OEMs and system integrators.
-
Regulatory and incentive navigation guides, detailing how major policy instruments and funding windows can be leveraged in market entry and expansion strategies.
How to use this intelligence in 2026
-
Prioritize optionality: use our decision tree to size investments that preserve optionality across two or three technically plausible chemistries rather than committing to a single-path long-lead asset prematurely.
-
Lock strategic partnerships early: for buyers and OEMs, securing validated cell supply or co-development agreements in 2026 will shorten OEM qualification cycles and provide competitive differentiation into the early 2030s.
-
De-risk procurement: integrate raw-material hedging and multi-sourcing strategies informed by our supply-chain scenarios to mitigate single-source exposure during scale-up.
-
Align policy and capital plays: synchronize investment timing with anticipated policy funding windows and local incentive programs to maximize subsidy capture and reduce capital costs.
-
Plan for standardization outcomes: invest in modular manufacturing and qualification processes that can adapt to emerging standards and reduce retooling risk as production practices converge.
Closing — the competitive edge for 2026
For corporate leaders and investors, 2026 will separate strategic winners from laggards. The market’s structural growth, coupled with concentrated competitive dynamics and accelerating industrial policy, creates a narrow opportunity corridor for those who plan deliberately: secure validated partners, stage investments to preserve flexibility, and align internal operating models to a faster qualification cadence. PW Consulting’s Next-Generation Advanced Batteries Market study is calibrated to these realities — offering the forecast precision, scenario analytics, and operational playbooks decision-makers need right now.
Next step
This preview intentionally highlights the strategic signals without disclosing the proprietary segment-level forecasts and granular supplier economics contained in the full report. For the complete dataset, interactive models, and tailored advisory options to inform your 2026 capital and partnership decisions, access the full study and our consulting services through PW Consulting’s report portal.
For detailed analysis of this topic, please visit the official page: Next-Generation Advanced Batteries Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Outdoor LED Display Market Poised for 9.8% CAGR Through 2032
By pmarketresearch, 2026-07-13
Outdoor LED Display Market — Strategic Imperatives for 2026
Executive snapshot
As PW Consulting’s lead industry analyst, I have consolidated our latest Outdoor LED Display Market study into a concise strategic briefing designed to inform board-level and operational decisions in 2026. The market has moved from niche digital signage into a core component of urban infrastructure and brand experience. Our base-year assessment (2025) shows a market size of USD 212.34 Million (USD Million), having expanded steadily since 2020, and our modeling projects a sustained compound annual growth rate (CAGR) of 9.8% through the 2026–2032 forecast window, with the market trajectory pointing toward roughly USD 406.86 Million by 2032. These headline metrics define the commercial opportunity — but success will be decided in the details of product differentiation, supply-chain resilience, and go-to-market alignment.
Outdoor LED Display Market
Why this research matters for 2026 decision-makers
-
Actionable timing: With the market accelerating in 2026, capital allocation decisions (R&D, capacity build, M&A) made this year will determine who captures the next wave of demand.
Outdoor LED Display Market -
Risk-precision: Volatility in inputs and regulation means procurement and product roadmaps must be reconfigured from “cost-first” to “resilience-first.”
Outdoor LED Display Market -
Commercial leverage: As price competition softens, companies that can sell integrated solutions (hardware + software + service) will capture outsized margins.
-
Operational playbooks: The report translates macro growth into executable plans — procurement clauses, supplier scorecards, modular product roadmaps, and ROI models tailored to outdoor applications.
Macro trajectory and strategic implications
The headline growth rate (9.8% CAGR) and doubling-scale projection to the end of the forecast horizon are signals that Outdoor LED is maturing from a capital-intensive hardware market into a recurring-revenue ecosystem. For executives, the implications are threefold:
-
Invest selectively in differentiation: Not every segment of the market will deliver equivalent margins. Where long-term contracts, mission-critical performance (e.g., stadiums, traffic management), and certifications matter, buyers will pay premiums for proven durability and service guarantees.
-
Prioritize service and platform layers: With hardware commoditization trending downward in parts, the fastest route to margin expansion is adding operations, content, and maintenance services that lock in customers.
-
Model scenarios, not point forecasts: Given supply-side shocks and regulatory shifts, board-level planning must incorporate multiple cases (base, constrained-supply, accelerated-adoption) — our report provides the calibrated models and sensitivity analyses to do that quickly.
Competitive landscape — who moves the needle
The market concentration metrics indicate a moderately consolidated landscape (CR3 approximately 47%, CR5 around 52%), meaning a handful of global and regional players exert significant influence, while a deep tail of specialist manufacturers and integrators pursues niche opportunities. Key archetypes we profile include:
-
Engineering-led stadium and mission-critical vendors: Companies like Daktronics focus on high-reliability sports and outdoor video-board installations optimized for extreme conditions and long life cycles.
-
Premium consumer-technology incumbents: Global electronics firms offer high-brightness, architectural-grade solutions and push innovation on pixel pitch and industrial design for commercial clients.
-
Asia-based scale manufacturers: Several Shenzhen-headquartered firms leverage manufacturing scale to supply both rental and fixed outdoor solutions, with a strong emphasis on IP-rated cabinets and cost-performance balance.
-
Specialist innovators and challengers: Emerging brands focus on aluminum cabinet designs, IP68 protection, and modular systems that simplify installation and service for urban deployments.
Recent industry moves matter as well. Licensing alliances and product launches in late 2025 and early 2026 (including strategic licensing to strengthen systems, and high-brightness product introductions) signal shifting competitive dynamics: intellectual property and platform-rich solutions will be decisive differentiators in 2026.
Supply chain, materials and regulatory realities
2025–2026 exposed material and regulatory vulnerabilities across the value chain. Key dynamics we analyze in the report include:
-
Component cost pressure: LED packaging experienced price increases in 2025, and aluminum and rare-earth cost volatility has materially increased manufacturing cost baselines for cabinets and phosphors.
-
Regulatory constraints: Export controls and licensing requirements from major producers of specialty inputs have created path-dependence in sourcing strategies for red-phosphor and related materials.
-
Manufacturing economics shifting: Announcements of manufacturer price increases in early 2026 shifted competition away from low-price into quality- and service-led differentiation, compressing the traditional low-margin arbitrage model.
For procurement and operations teams, the practical takeaway is simple: hedging, near-shoring, multi-sourcing, and longer-term offtake agreements will be table stakes to maintain margins and delivery reliability. Our supplier scorecards and contract templates are designed to operationalize these choices immediately.
Five practical moves for 2026
-
Re-balance R&D spending toward durability and modularity. Invest in IP that reduces field-service time and improves MTBF; modular panels and repair-friendly cabinets reduce lifecycle costs and win installations with long-term maintenance contracts.
-
Renegotiate procurement with escalation mechanisms. Shift fixed-price short-term contracts to indexed agreements with clear pass-through or hedging clauses for rare earths and aluminum to protect margins.
-
Build a services-first GTM. Pilot subscription or managed-service offerings in high-density urban and stadium accounts to convert one-time capital sales into recurring revenue streams.
-
Pursue selective partnerships and licensing. Strategic IP deals and component licensing can accelerate time-to-market for premium propositions while avoiding heavy upfront capital investment in new die/package technologies.
-
Execute scenario-based capacity planning. Use our demand/constraint scenarios to prioritize capacity expansion where ROI thresholds are met under stressed-supply cases; delay or partner where they are not.
What the report contains — practical, executable assets
Our full study is structured to deliver both strategic insight and operational utility. Highlights include:
-
Historic and forecast market sizing (base year 2025; forecast 2026–2032) with scenario bands that reflect supply, regulatory, and adoption risks.
-
Competitive benchmarking and supplier scorecards — capability matrices that prioritize product reliability, IP strength, and service coverage.
-
Supply-chain heatmaps and mitigation playbooks — recommended supplier diversification plans, hedging approaches, and procurement contract templates.
-
Go-to-market playbooks by buyer archetype — procurement checklists and commercial terms tailored to stadium integrators, municipal projects, DOOH networks, and transport authorities.
-
Financial tools — capex calculators, lifecycle cost models, and ROI templates that allow rapid evaluation of new product investments and M&A targets.
-
Regulatory and material risk maps — actionable alerts and control points for materials like europium oxide and for jurisdictions imposing export/licensing controls.
We intentionally refrain from publishing granular, segment-level outputs in this briefing because comparative segment forecasts, regional splits, and weighted pricing scenarios are part of the full deliverable suite and are essential to bespoke commercial decisions.
How to use this intelligence in 60–180 days
-
60 days: Implement priority procurement clauses, launch a supplier scorecard review, and begin RFPs that include durability and service KPIs.
-
90 days: Run a pilot managed-service offering in a targeted city or venue and align sales incentives around recurring revenue conversion.
-
180 days: Decide on R&D investments or licensing deals using our ROI templates and scenario outputs, and initiate any shortlisted M&A or partnership discussions.
Concluding perspective — opportunity framed by discipline
The Outdoor LED Display market in 2026 represents a compelling growth runway: headline metrics point to sustained double-digit growth through the decade, but the playing field has changed. Material cost volatility, supply and regulatory shocks, and a shift from price competition to quality/service differentiation mean that success will go to firms that combine engineering excellence with disciplined supply-chain strategy and service-led commercial models. Our report provides the data, playbooks, and executable templates to turn the macro opportunity into repeatable advantage — and the full segment-level forecasts, competitor scorecards, and downloadable financial models are available in the complete PW Consulting study.
Next step
To access the full dataset, segmented forecasts, supplier rankings, and implementation kits that underpin these recommendations, please visit the report page or contact PW Consulting’s industry desk. The full deliverable includes the granular inputs you need to operationalize the five moves above and to stress-test your 2026 investment plan against realistic supply and regulatory scenarios.
For detailed analysis of this topic, please visit the official page: Outdoor LED Display Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Image Capture Cards Market to hit USD 3,160M by 2032 — 9.8% CAGR
By pmarketresearch, 2026-07-13
Image Capture Cards Market — 2026 Strategic Brief (PW Consulting)
As enterprises plan capital allocation, product roadmaps, and go-to-market moves for 2026, the Image Capture Cards market presents a compelling mix of sustained growth, concentrated incumbent power, and material operational risk. Our latest study — grounded in a 2020–2025 historical backbone and a 2026–2032 forecast horizon — documents a robust structural expansion driven by multimedia proliferation across gaming, streaming, professional AV, medical imaging, conferencing and security workflows. The market has progressed from under a billion USD in 2020 to roughly USD 1.65 billion in our 2025 base year and is projected to continue growing at a near-double-digit compound annual growth rate (~9.8%) through the forecast window, reaching multibillion-dollar scale by 2032. This brief explains why that trajectory matters for strategic choices in 2026 and which levers senior executives should prioritize.
Image Capture Cards Market
Why this report is a must-read for 2026 decision makers
-
Actionable signal in a noisy market: We translate macro growth into decision-ready implications for R&D prioritization, channel strategy, and pricing models, without overreliance on vendor anecdotes.
Image Capture Cards Market -
Risk-to-reward mapping: The study overlays demand growth with supply fragility — enabling procurement and product leaders to align inventory, qualify alternate suppliers, and quantify retention cost for premium positioning.
Image Capture Cards Market -
Competitive posture diagnostics: You’ll get a pragmatic read on where to defend, where to attack, and where consolidation is likely to accelerate — key for M&A and strategic partnerships in 2026.
-
Compliance and architecture playbook: For enterprises deploying capture technology into regulated environments, the report gives a design checklist for data localization and privacy-safe ingestion pipelines.
Report contents — practical elements (teaser)
-
Market sizing and trajectory: Clear historical base (2020–2025) and scenario-modeled forecasts for 2026–2032 that quantify upside/downside under alternative adoption and supply assumptions.
-
Demand-side use-case deep dives: Comparative economics and integration complexity across primary end markets to help prioritize product features and certification efforts.
-
Technology and product taxonomy: Objective breakdown of form factors (PCIe, USB, M.2), I/O standards (SDI/HDMI/12G, frame-rate and color-depth trade-offs), and emerging architectures (FPGA, ASIC, SoC-based capture acceleration).
-
Supplier risk matrix: Lead-time sensitivity, concentration of advanced-foundry exposure, and component-level bottleneck scenarios with mitigations and contingency cost estimates.
-
Commercial playbooks: Recommended pricing frameworks, tiered warranty/service models, and channel incentive structures designed to defend premium ASPs while accommodating low-cost OEM pressure.
-
Competitive profiles and scenario-ready M&A watchlist: Strategic positioning, product roadmaps, and acquisition fit analyses for leading incumbents and high-potential challengers.
-
Decision-support assets: Excel-based TCO and ROI models, supplier selection scorecards, and a 12–36 month tactical rollout planner.
Key market dynamics shaping 2026 strategy
-
Structural demand growth vs. commoditization pressure — The market’s near-10% CAGR masks heterogenous unit- and value-growth dynamics. Higher-end professional capture solutions tied to broadcast, medical and pro AV remain a margin pool where innovation (e.g., multi-channel, low-latency 4K/8K capture) yields pricing power, while entry-level streaming/gaming capture is increasingly contested by low-cost OEMs. Strategic implication: protect premium tiers with integrated software/services and shorten new-product cycles to stay ahead of low-cost cannibalization.
-
Supply-chain fragility is now a business strategy variable — The semiconductor disruptions of 2021–2022 exposed concentrated foundry dependencies and long lead times for specialized capture ASICs and high-speed SerDes components. For 2026, companies must treat advanced component access as a strategic asset: dual-sourcing, design-for-availability (DFx), and pre-allocated capacity agreements will materially alter time-to-market and gross margin outcomes.
-
Regulatory and data-localization complexities — Increasingly stringent data localization and privacy rules in multiple jurisdictions are influencing system architecture decisions for video ingestion and edge processing. Enterprises purchasing capture solutions need to evaluate whether vendors can offer localized firmware, on-prem ingest with controlled telemetry, and contractual guarantees to avoid regulatory friction.
-
Concentration and competitive balance — The market demonstrates moderate-to-high concentration among several established vendors, creating an environment where nimble challengers and aggressive OEMs can win share through price, niche performance advantages, or bundled ecosystems. We identify tactical windows for partnerships and tuck-in acquisitions that can accelerate enterprise reach or technical capability.
Reading the competitive landscape
-
Magewell (Nanjing) — Strategic posture: product-led with a broad capture family across PCIe, USB and M.2. Strengths include a wide validated device matrix and a steady cadence of product launches (notably a high-bandwidth USB Capture SDI 4K Pro announced at NAB 2025). Implication: Magewell is positioned to defend professional and prosumer customers who value interoperability and rapid integration; competitors must match software ecosystem compatibility to compete effectively.
-
Datapath (Derby, UK) — Strategic posture: high-performance multi-channel capture for complex AV installations. Strengths lie in multi-input scalability and enterprise-grade support. Implication: Datapath is the default for high-density, mission-critical deployments; new entrants should target adjacent value-adds such as integrated analytics to unbundle share.
-
Blackmagic Design (Melbourne) — Strategic posture: strong appeal to creative professionals with high-fidelity DeckLink PCIe cards supporting up to 8K workflows. Strengths include brand-recognition in production ecosystems and a product set that spans ingest/playback. Implication: Blackmagic’s positioning creates a premium benchmark; rivals must either match technical specs or pivot to specialized vertical integrations (e.g., medical imaging certifications).
-
Anyoyo (China) — Strategic posture: cost-competitive USB capture cards targeted at streaming and gaming. Strengths include aggressive price points and fast time-to-market. Implication: They continue to compress entry-level margins; incumbents will need service differentiation or channel exclusivity to preserve ASPs at the lower end.
Strategic priorities for 2026 (recommended actions)
-
Secure critical components now — Negotiate capacity or long-lead commitments for any ASICs, high-speed SerDes, and specialized FPGA capacity that underpin next-generation capture features. Model the P&L implications of pre-booking versus spot procurement across high/low demand scenarios.
-
Productize software and services — Bundle capture hardware with firmware-driven differentiation, cloud connectors, and latency-optimized SDKs to create recurring revenue and increase switching costs.
-
Adopt a two-track GTM — Maintain channel breadth for volume capture devices while deploying a direct, solution-sales team for enterprise and regulated verticals that require certification and customization. Use tiered warranties and support SLAs as monetizable levers.
-
Pursue targeted M&A or partnerships — Prioritize acquisitions that fill gaps in software, AI-driven analytics, or regional compliance capabilities. For pure-play hardware vendors, partnering with CDN/cloud or UC-platform providers accelerates market penetration for latencysensitive applications.
-
Invest in compliance-by-design — For enterprise customers operating across jurisdictions, offer deployment templates and contractual commitments that address data residency, firmware auditability, and telemetry minimization.
-
Differentiate through performance certs — Invest in independent third-party validation (latency, color fidelity, multi-channel sync) to create defensible procurement advantages for broadcast and medical buyers.
How PW Consulting’s report supports execution
-
Scenario-ready market models: Translate the study’s growth trajectories and supply scenarios into bespoke forecasts for your product lines or geographic priorities.
-
Supplier-risk heatmap: Rapidly identify single points of failure and quantify mitigation costs under three sourcing strategies.
-
Commercial playbooks: Pre-built pricing ladders, warranty structures and channel commission templates calibrated to maintain revenue per unit in an increasingly price-sensitive environment.
-
M&A screening filters: Priority criteria and scorecards derived from technical fit, go-to-market synergies, and integration risk to accelerate 90-day diligence.
In short, the Image Capture Cards market offers compelling upside for firms that combine product differentiation with pragmatic supply-chain strategy and regulatory-aware deployment architectures. The market’s near-term expansion is clear from our base-year and forecast figures, but value capture in 2026 will be uneven: winners will be those who insulate critical inputs, monetize software and services, and make disciplined channel and M&A choices.
This brief surfaces the strategic thrusts and near-term actions. For the granular breakdowns, proprietary segmentation, and the suite of decision-support tools referenced above, access the full PW Consulting report and interactive models on our site. The report will provide the detailed segment economics and downloadable assets you need to convert the market’s growth into sustainable enterprise advantage.
For detailed analysis of this topic, please visit the official page: Image Capture Cards Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Pet Medicine Market to hit USD 24.03B by 2032 — 7.2% CAGR (2026–2032)
By pmarketresearch, 2026-07-13
Pet Medicine Market — Strategic Outlook and Decision Framework for 2026
As pet ownership continues to rise and owners increasingly treat companion animals as family members, the pet medicine market is transitioning from a niche veterinary sector into a strategic growth arena for pharmaceutical and animal-health players. Our PW Consulting Pet Medicine Market study crystallizes this opportunity: the global market expanded from USD 9.5 Billion in 2020 to USD 14.8 Billion in 2025 and—driven by therapeutic innovation, channel evolution, and higher per-animal spend—is projected to grow at a compound annual growth rate (CAGR) of 7.2% to reach roughly USD 24.0 Billion by 2032. This briefing outlines why these dynamics matter for 2026 corporate decision-making and how leaders should prioritise actions without revealing the fine-grained segmentation that is reserved for the full report.
Pet Medicine Market
Why this study matters for 2026 strategic choices
- Board-level clarity: Quantifies market scale and medium-term trajectory to justify resource allocation across R&D, commercial expansion, and M&A.
- Portfolio prioritisation: Signals where to allocate development budgets between small molecules, biologics, vaccines and supplements given changing clinical and commercial return profiles.
- Go-to-market alignment: Maps the shifting balance across clinics, retail and digital channels so commercial models can be adapted to where veterinarians and owners actually transact.
- Risk-adjusted planning: Translates regulatory and supply-chain noise into actionable mitigation paths tied to probability-weighted scenarios.
Macro and clinical trends shaping 2026 strategy
The market’s steady mid-single-digit CAGR masks two important accelerants. First, therapeutic innovation—particularly targeted therapies and next-generation small molecules—has increased addressable spend per patient. Recent regulatory milestones, including the FDA’s approval pathways for novel modalities and the first oral oncology treatment for canine lymphoma, are expanding treatment options and opening higher-value clinical niches. Second, distribution and purchasing behavior are fragmenting: while veterinary clinics remain central to diagnosis and prescribing, retail and digital channels are growing rapidly, prompting new commercial models.
Pet Medicine Market
At the same time, regulators are more active and visible. The FDA Center for Veterinary Medicine’s enforcement actions and approvals are reshaping product claims, labelling strategies and promotional conduct for 2026 launches. Notable regulatory events—such as an FDA warning to a major competitor over promotional claims and subsequent approvals of new drug classes—underline the need for an integrated regulatory-commercial playbook.
Pet Medicine Market
Competitive landscape — what to watch in 2026
The competitive set is composed of a mix of global pharma incumbents and specialized animal-health companies with differentiated R&D and channel capabilities. Key firms profiled in the study include:
- Merck Animal Health (Rahway, NJ) — A leader in companion-animal therapeutics with a strong late-stage pipeline and recent product approvals for conditions such as allergic dermatitis; their regulatory momentum and broad commercial field force make them a formidable competitor for specialty franchises. ( https://www.merck-animal-health.com)
- Zoetis (Parsippany, NJ) — Deep expertise in biologics and chronic-care products for pets; strong global distribution and data-driven animal health capabilities position them well in higher-value therapeutic categories. ( https://www.zoetis.com)
- Elanco Animal Health (Indianapolis, IN) — Focused on specialty pet medicines with recent launches in pruritus indications; regulatory scrutiny over promotional practices highlights reputational and compliance risks. ( https://www.elanco.com)
- Boehringer Ingelheim (Duluth, GA) — Robust R&D in chronic and parasitic conditions, with strengths in integrated animal-health services and product portfolios. ( https://www.boehringer-ingelheim.com)
- Bayer Animal Health (Leverkusen, Germany) — Strong in preventive care and parasitic controls, with notable consumer-facing brand recognition and retail partnerships. ( https://www.bayer.com)
- Vetoquinol (Magny-Vernois, France) — Specialist producer with agility in mid-market therapeutic categories and strong ties to veterinary practitioners. ( https://www.vetoquinol.com)
Competitive implications for 2026: incumbents with deep field sales and strong regulatory teams will defend core chronic-care segments, while agile specialty players and biotech partnerships will target high-growth niches created by novel modalities. The sector’s concentration—where the top three and top five players command a material share of the market—creates both defensive moat benefits and pockets of opportunity for focused innovators.
Regulatory and supply-chain dynamics to prioritise
- Regulatory enforcement and approvals: Elevated regulator activity means product claims, clinical endpoints and post-market surveillance must be aligned early in development to avoid launch delays or reputational damage.
- API and input risk: Proposed tariffs and concentration in API sourcing can materially increase costs and create bottlenecks; dual-sourcing and regional manufacturing flexibility should be modelled as part of capital planning.
- Commercial compliance: Warning letters and promotional scrutiny underline the need for compliant digital marketing, veterinarian engagement protocols, and field-sales training.
- Reimbursement and out-of-pocket dynamics: The largely out-of-pocket nature of companion-animal medicine requires robust owner-value messaging; consider pilot pricing models tied to demonstrated outcomes.
Practical strategic playbook for 2026
Translate insights into near-term actions. The following playbook is oriented to executives preparing 2026 budgets and three-year plans:
- Re-balance R&D portfolios toward high-value modalities: Prioritise projects with clear differentiation (e.g., targeted cytokine inhibitors, monoclonal antibodies) and acceptable regulatory pathways.
- Invest in regulatory capability: Hire or partner for veterinary-specific regulatory expertise to shorten approval timelines and reduce enforcement risk.
- De-risk supply chains: Implement dual-sourcing for critical APIs and consider regional fill/finish capacity to avoid tariff and transport disruptions.
- Adapt commercial models to omnichannel: Strengthen clinic relationships for prescribing while building scalable digital retail funnels and subscription services for chronic care.
- Pursue tuck-in M&A and strategic alliances: Target capabilities (digital prescribing platforms, diagnostics, biologics manufacture) that accelerate route-to-market and margin expansion.
- Build real-world evidence (RWE) programs: Capture outcome and safety data via clinic networks to support premium pricing and payer conversations where applicable.
- Design compliance-first marketing: Update promotional materials and training to reflect recent regulatory actions and guardrails.
- Scenario test your business plan: Run upside/downside cases around regulatory delays, API cost inflation and channel displacement to set contingency budgets.
What the full PW Consulting report contains (teaser)
The published study is designed for executive teams and investment committees. Highlights include:
- A detailed market model (historical 2020–2025 and forecast 2026–2032) with transparent assumptions and sensitivity testing.
- Segment-level analysis across product types, animal types, distribution channels and regions, plus growth drivers—note that full segmentation tables and company share data are available in the paid report.
- Comprehensive company profiles and capability-mapping for leading and challenger firms, including commercial footprints and pipeline positioning.
- Regulatory timeline and impact analysis covering recent FDA actions, approvals and likely near-term guidance that will affect launch strategies.
- Supply-chain vulnerability assessment and mitigation playbook with cost-to-implement estimates.
- Actionable go-to-market playbooks tailored to large incumbents, mid-sized players and new entrants—with recommended investment horizons and ROI thresholds.
- Financial impact analyses and M&A screens identifying asset types and geographies likely to produce immediate synergies.
- An executive-ready slide pack and an editable Excel model for in-house scenario planning.
How to use these insights in your 2026 decision cycle
For CEOs and CFOs: use the market trajectory and scenario outputs to set R&D run-rate, capital allocation and M&A priorities. For Heads of R&D and Regulatory: recalibrate development roadmaps to prioritise modalities with clearer veterinary pathways and fund early regulatory engagement. For Commercial leaders: craft omnichannel models that preserve veterinarian engagement while monetising convenience-driven retail and digital channels. And for Strategy and Corporate Development teams: screen potential targets using the study’s deal filters and valuation templates to accelerate due diligence.
Our approach follows the “preview” principle: this note surfaces the strategic contours and the most consequential actions for 2026, while the full PW Consulting Pet Medicine Market report contains the granular segmentation, company share tables and model files needed to execute with confidence. For teams preparing budgets, pipelines or M&A pipelines in 2026, the report converts market trajectory into executable program roadmaps and quantifies the trade-offs inherent in each strategic choice.
To access the full dataset, scenario models, and company-level analysis that support the recommendations above, please consult the source publication. PW Consulting stands ready to run tailored workshops to translate these findings into your 2026 operating plan.
For detailed analysis of this topic, please visit the official page: Pet Medicine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Online Sports Betting Market to Reach USD 286.3M by 2032 at 9.85% CAGR — PW Consulting
By pmarketresearch, 2026-07-13
Online Sports Betting Market 2026: Strategic Preview for Executive Decision-Makers
As PW Consulting’s Senior Strategic Advisor and Head Industry Analyst, I present a high-level, decision-focused briefing that distills our latest Online Sports Betting Market study into the strategic imperatives CFOs, heads of product, and corporate development teams must act upon in 2026. This is a “trailer” of our full research: it reveals direction, dynamics, and implications you need to prioritize, while reserving the granular segmentation and sensitive numeric breakouts for the full report.
Online Sports Betting Market
Market Trajectory: What the Topline Means for Strategy
The online sports betting market has moved from a niche digital pastime to a mainstream consumer channel within a single business cycle. Measured on a consistent base-year basis, global revenue expanded steadily through the first half of the decade and reached an inflection by 2025. The market posted material growth between 2020 and 2025 and — under our central scenario — is set to continue expanding at a compound annual growth rate (CAGR) of roughly 9.85% over the 2026–2032 forecast window. By 2026 the market advances further from its 2025 base and continues a trajectory that, if uninterrupted by major regulatory shocks, roughly doubles market scale by the end of our forecast.
Online Sports Betting Market
Why the topline matters: a near-double market size within a single planning horizon changes the math of customer acquisition, technology investment, and regulatory engagement. Growth at this pace compresses the timeline for ROI on platform builds, makes scale economies achievable faster for vertically integrated operators, and shifts competitive advantage toward firms that combine regulatory footprint, brand reach, and real-time operational excellence.
Online Sports Betting Market
Strategic Implications for 2026 Corporate Decision-Making
- Prioritize architectural scalability now: At ~10% CAGR, platforms will be handling materially higher peak loads and concurrent live-event bets. Organizations should move from ad-hoc cloud solutions to architecture designs that balance latency, resilience, and compliance. Hybrid-cloud patterns and edge/local-zone deployments (used by leading operators) are becoming standard for live-betting latency SLAs and data residency requirements.
- Treat regulation as a product constraint and a growth lever: Recent regulatory resets — including new rulemaking directives from the U.S. regulatory apparatus in early 2026 — mean that legal frameworks will change in ways that affect product design, contract structures, and partnership models. Companies that embed regulatory scenario planning into product roadmaps will avoid costly rework and can turn compliance into a competitive moat through faster market entry.
- Optimize go-to-market via strategic partnerships: As brand and distribution remain decisive, strategic alliances with media, sports leagues, and retail channels accelerate user acquisition and deepen engagement. Partnership plays that bundle content, loyalty, and payment experiences outperform stand-alone customer-acquisition strategies.
- Monetize beyond the wager: Ecosystem monetization — through adjacent casino, prediction markets, and cross-sell into lotteries or fantasy products — materially increases lifetime value. The highest-performing operators are integrating multi-product “super app” architectures that keep users within a single commerce and loyalty layer.
- Embed responsible gaming and AML into front-line UX: Responsible gaming and anti-money-laundering tooling are now core product features, not compliance afterthoughts. Solutions that provide real-time risk signals and seamless remediation preserve trust and reduce regulatory friction.
Operational and Technology Imperatives
Operational excellence in 2026 requires three concurrent investments: infrastructure that meets latency and residency requirements; engineering practices that support continuous deployment across jurisdictions; and analytics capabilities that enable real-time margin management.
- Edge and local-zone deployment: Leading operators are using local cloud zones to meet strict data residency and latency needs for live betting. Enterprises planning national or multi-jurisdictional rollouts should evaluate local-zone and edge computing as part of their 18–36 month infrastructure roadmap.
- Hybrid cloud for compliance and portability: Hybrid solutions that leverage Azure Arc, Nutanix, and similar technologies provide a repeatable pattern for compliant multi-jurisdictional processing while reducing vendor lock-in.
- Real-time analytics and risk controls: Live in-play wagering magnifies exposure to both fraud and margin erosion. Investing in streaming analytics and automated limit-adjustment engines is now table stakes.
Competitive Landscape: Who’s Winning and Why
The market’s competitive structure shows moderate concentration: the top three operators account for a meaningful share of revenue and the five largest players capture a clear majority of consolidated market power. This mix creates both opportunity and pressure: scale matters, but differentiated propositions can still win share.
- DraftKings Inc. (Boston) — DraftKings continues to execute a vertically integrated playbook, blending sportsbook and adjacent product lines while leveraging media partnerships. Recent moves to expand a unified “super app” will put pressure on smaller operators to improve cross-product journeys.
- FanDuel / Flutter (New York) — FanDuel’s dual capability in daily fantasy and sportsbook, underpinned by Flutter’s capital and international muscle, keeps it at the center of U.S. regulated market competition.
- bet365 Group (UK) — bet365 remains a global benchmark for live betting features and product reliability. Its cross-jurisdictional operational playbook is a practical case study in regulatory and technical execution at scale.
- Entain and Flutter (UK / Global) — Both companies continue to leverage multi-brand portfolios to target diverse customer segments across regulated markets.
- U.S. casino-integrated operators (Caesars, MGM, Penn National) — Integration with retail gaming, loyalty, and hospitality assets yields unique cross-sell economics, especially in states with retail/online hybrid models.
- Specialists and challengers (PointsBet, others) — Niche propositions focused on product innovation (in-play mechanics, marketplace differentiation) can grow regionally and become attractive M&A targets for scale players looking to fill capability gaps.
Notable recent developments reflect evolving battlegrounds: exclusive media-provider partnerships, rollouts of enterprise-level fraud and geolocation tooling, and product expansions into unified gaming super apps. These moves accelerate winner-take-most dynamics in channels where distribution and engagement depth drive LTV/cost-of-acquisition economics.
Regulatory and Policy Context — What to Watch in 2026
Regulatory dynamics are the single largest source of upside and downside risk to 2026 plans. Key themes:
- Rulemaking momentum: A prominent U.S. regulatory authority reversed prior guidance and initiated fresh rulemaking in early 2026, signaling a period of legal clarification. Companies should assume a dynamic regulatory environment and build flexible compliance controls.
- Cross-border data policies: National-level data residency and cross-border transfer rules remain uneven. Operators adopting hybrid-compute and localized processing reduce execution risk and accelerate market entry.
- Responsible gaming expectations: Regulators and stakeholders expect proactive harm-minimization features. Operators that operationalize these expectations into product design will reduce enforcement risk and strengthen brand trust.
M&A, Partnerships, and Capital Allocation Guidance
With near-double growth projected over the planning horizon and meaningful concentration among incumbents, the M&A and partnership landscape is active and tactical. Key advisory points for 2026:
- Buy vs. build calculus: If your strategic imperative is rapid market entry or capability acquisition (e.g., live-betting engine, geolocation compliance suite, or a multi-product loyalty layer), acquisition of specialist assets can be materially faster than in-house development—provided integration plans are disciplined.
- Balance sheet and timing: Growth at this scale rewards front-loaded investment in customer acquisition and product differentiation. However, overpaying for scale without an operational plan to sustain margins is the single most common value-destroying path.
- Partnership archetypes: Content/distribution partnerships, regulated-market operating partnerships, and technology licensing models each solve different problems. Choose the archetype that aligns with your control requirements and time-to-market constraints.
What the Full PW Consulting Report Delivers
Our complete Online Sports Betting Market study is designed for practitioners making 12–36 month strategic bets. Highlights include:
- Integrated market sizing and forecast models (base year 2025) with scenario sensitivity for regulatory and macroeconomic shocks.
- Actionable go-to-market playbooks for market entry, product bundling, and loyalty-driven retention.
- Operational blueprints for technology, data residency, and live-event scaling, including vendor shortlists and cost-of-ownership frameworks.
- Detailed competitive profiles and M&A playbooks for both buyers and sellers—covering integration risks and capture opportunity timelines.
- Regulatory impact matrices and pre-approved contract language templates for key market-entry and partner arrangements.
- Scorecards and KPIs for real-time monitoring of operational risk, margin performance, and regulatory compliance.
Importantly, while this preview outlines the market’s macro growth and strategic themes, the full report contains the granular segmentation, regional and device-level insights, and model-ready spreadsheets necessary to operationalize these recommendations. Those datasets are intentionally withheld here to preserve the integrity and commercial value of the full research.
Final Recommendation: What to Do in Q2–Q4 2026
- Immediate action: complete a 90-day technical and regulatory readiness assessment focused on latency, data residency, and AML/responsible gaming controls.
- Six-month horizon: finalize partnership and media strategies that prioritize distribution reach and cross-product retention economics; begin selective integrations with cloud local-zone or edge providers where necessary.
- 12–36 months: allocate capital toward M&A or organic build programs that secure leadership in at least one high-return jurisdiction or product vertical, ensuring a defensible path to scale.
The online sports betting market in 2026 is at a strategic inflection: growth is robust, competitive stakes are higher, and regulatory complexity requires disciplined execution. For boards and executive teams, the question is not if the market will grow, but who will capture the economics of that growth. PW Consulting’s full Online Sports Betting Market report gives you the prioritized, executable intelligence to answer that question with confidence.
Access the Full Report
To obtain the detailed segmentation, model-ready forecasts, and the operational playbooks referenced here, please visit our full study page or contact your PW Consulting representative. The full report provides the data and tools your leadership team needs to convert 2026 market momentum into sustainable market leadership.
For detailed analysis of this topic, please visit the official page: Online Sports Betting Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Laser Micromachining Market to Hit USD 606.48M by 2032 (7.6% CAGR)
By pmarketresearch, 2026-07-13
Laser Micromachining Market: Strategic Imperatives for 2026 — PW Consulting Industry Brief
Executive summary
The laser micromachining market is at an inflection point. After steady expansion through the early 2020s, the market reached an estimated USD 366.25 Million in our base year (2025) and is projected to expand at a compound annual growth rate (CAGR) of 7.6% over the 2026–2032 forecast period, reaching roughly USD 606.48 Million by 2032. These headline metrics reflect the combined effect of robust demand in high-precision sectors, accelerating adoption of ultrafast and fiber laser technologies, and steady improvements in throughput and cost-efficiency that make micromachining competitive against traditional micro-CNC and etching processes.
Laser Micromachining Market
Why this matters for corporate decision-making in 2026
-
Timing and scale: The mid-2020s are the window where practical performance gains translate directly into procurement, capacity, and product design choices. With a clear multi-year growth trajectory, capital allocation for laser-based microprocessing is no longer exploratory — it is strategic. Decisions made in 2026 will determine whether firms are technology leaders or late adopters across the next product cycle.
Laser Micromachining Market -
Cost and productivity inflection: Our sector analysis indicates laser micromachining can reduce labor costs by up to 70% relative to traditional CNC approaches in precision manufacturing contexts. This reshapes unit economics for small-feature, high-mix production runs, particularly in electronics, medical devices, and advanced packaging.
Laser Micromachining Market -
Regulatory and safety obligations: Compliance is now a commercial constraint. Recent regulatory developments — including the EU Machinery Regulation requirements for CE-marking of laser equipment, FDA expectations for laser-controlled medical device processes, ISO 11553-1 industrial laser safety standards, and national laser safety standards such as China GB/T 7247.1 — must be built into procurement, validation, and supplier selection strategies. Non-compliance risks slow market entry, unexpected costs, and damaged customer relationships.
-
Market structure: The competitive landscape shows meaningful concentration at the top: the three largest suppliers account for a majority share of the market footprint (CR3 ~58%), while the top five raise this concentration to approximately 68% (CR5 ~68%). This mixed structure of strong incumbents and innovative challengers creates both partnership opportunities and competitive threats depending on your go-to-market approach.
What the PW Consulting report delivers — practical, decision-grade outputs
Our report is designed for commercial leaders, procurement teams, product architects, and corporate development executives who need actionable intelligence in 2026. Key deliverables include:
- Validated market sizing and forward-looking scenario modeling (base year 2025, forecast 2026–2032) with sensitivity tests tied to technology adoption and macroeconomic variation.
- Technology roadmaps that match laser types to applications and cost buckets, including practical trade-offs for ultrafast, fiber, excimer and CO2 platforms.
- A battery of procurement tools: supplier shortlists, vendor scorecards, sample RFP language, and compliance checklists aligned with EU/FDA/ISO/GB standards.
- Operational playbooks for factory integration, including process qualification templates, cycle-time optimization guides, and maintenance/Spare Part strategies to manage uptime.
- Commercial models and ROI templates to compare CAPEX vs OPEX deployment scenarios, including break-even horizons under conservative and aggressive adoption curves.
- Competitive landscape dossiers and go-to-market maps highlighting strategic options: OEM partnerships, captive manufacturing, contract micromachining, and licensing.
- Dealflow and M&A screening heuristics tailored to market concentration metrics and technology gaps, plus illustrative transaction case studies.
- Executive dashboards and investment memos that translate technical findings into board-ready recommendations.
Competitive landscape snapshot — who matters and why
The market blends global incumbents with specialized innovators. Below is a condensed, practical read on the firms shaping supply-side dynamics in 2026 and why they matter to decision-makers.
-
Coherent (United States) — Strength: precision manufacturing lasers and systems targeted at high-accuracy cutting, drilling, marking and ablation. Strategic implication: attractive as a systems partner for industrial OEMs and display/semiconductor capital equipment integrators seeking turnkey solutions.
-
IPG Photonics (United States) — Strength: fiber-laser sources optimized for microprocessing, microwelding and microdrilling. Strategic implication: core supplier for players prioritizing high beam quality and reliability; recent industry recognition underscores product maturation and scale readiness.
-
TRUMPF Group (Germany) — Strength: industrial-grade cutting and marking systems (TruLaser series) with deep process control. Strategic implication: favored by manufacturers requiring robust factory integration and service footprints across mature industries.
-
Han’s Laser Technology Industry Group (China) — Strength: comprehensive portfolio for precision cutting and processing with strong regional distribution. Strategic implication: competitive option for cost-sensitive high-volume deployments and regional supply security.
-
GF Machining Solutions (Switzerland) — Strength: dedicated micromachining machines for micro-engraving, shaping and drilling. Strategic implication: appealing to precision tool users and contract manufacturers servicing advanced medical and aerospace niches.
-
AMADA WELD TECH (Japan) — Strength: Delta Laser systems and femtosecond integration for ablation, drilling and surface texturing. Strategic implication: relevant for product teams pursuing next-level surface functionalization and micro-assembly.
-
3D-Micromac (Germany) — Strength: laser micro-structuring for semiconductors, sensors and packaging. Strategic implication: a go-to for advanced packaging and sensor OEMs seeking tight process controls and niche expertise.
-
Oxford Lasers (UK), Lasea (Belgium), OpTek Systems (UK) — Strength: high-precision marking, microstructuring and high-speed material removal respectively. Strategic implication: specialized suppliers that can supply capability gaps or co-develop bespoke solutions for electronics and industrial customers.
Recent market activity and signals
- Trade shows and demonstrations in early 2026 have accelerated visibility for femtosecond and compact high-power sources — notable public showcases include platforms focused on ultra-precise micromachining and fiber-based solutions.
- Industry awards and technology recognition in 2026 are validating new single-mode, high-power laser sources that materially change throughput assumptions for certain microprocessing applications.
- Regional compliance events and standard updates have increased the bar for supplier validation, creating an opening for certified integrators and a hurdle for small scale entrants without compliance capabilities.
Strategic actions we recommend for 2026
-
Portfolio review: Map your product roadmaps to micromachining capabilities now. For R&D teams, prioritize feasibility pilots with femtosecond and high-brightness fiber lasers where material quality or microfeature integrity is a differentiator.
-
Procurement & compliance: Require CE/FDA/ISO conformity evidence in RFPs and budget for validation time. Compliance documentation is a commercial lever — early-certified partners shorten time-to-market.
-
Manufacturing footprint: Use our CAGR-backed capacity planning templates to decide between in-house adoption vs contract micromachining partnerships. Consider hybrid models where high-mix, low-volume work is outsourced while high-volume, IP-sensitive processes are retained.
-
Partnering & M&A: With top-tier suppliers commanding significant share, targeted acquisitions or strategic alliances are effective routes to access advanced beam sources, process know-how, or distribution in key regions.
-
Service & aftermarket: Build service and spare-part strategies into procurement decisions; equipment uptime and process reproducibility are major differentiators for OEM customers.
Practical next steps — a 90-day plan for executives
- Initiate a technology pilot with one incumbent and one specialist supplier to validate process performance on your critical materials.
- Commission a compliance gap analysis focused on EU/FDA/ISO/China laser standards to avoid procurement delays.
- Use PW Consulting’s vendor scorecard to shortlist three suppliers for a formal RFP and a two-week on-site evaluation phase.
- Run a rapid CAPEX vs OPEX scenario using our ROI templates to determine the most economic deployment pathway based on your projected volumes using the 7.6% market growth baseline.
Closing — the report as the next strategic lever
This brief is a strategic “trailer.” It surfaces the critical dynamics, the competitive map, and the decision levers that matter in 2026 — but it intentionally omits the granular regional and application-level splits and the supplier-level revenue details that are essential for transaction-grade decisions. The full PW Consulting Laser Micromachining Market report contains those detailed regional and application segmentation tables, interactive scenarios, supplier scorecards, and downloadable procurement templates that operational teams need to execute quickly and confidently.
For teams planning capital commitments, supplier negotiations, or M&A activity in 2026, acquiring the full report is the recommended next step. PW Consulting’s analysts are available to walk clients through tailored readouts that turn the forecast and market structure into a concrete implementation roadmap.
For detailed analysis of this topic, please visit the official page: Laser Micromachining Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Print-On-Demand Software Market Poised for 31.1% CAGR Through 2032
By pmarketresearch, 2026-07-13
Print On Demand Software Market — Strategic Preview for 2026 Decision-Makers
As PW Consulting’s Senior Strategy Advisor and Chief Industry Analyst, I present a focused preview of our flagship market research on the Print On Demand (POD) Software market. This article synthesizes the report’s most consequential insights for executives planning capital allocation, product roadmaps, or M&A strategies in 2026 — while preserving the detailed segment-level intelligence available in the full study.
Print On Demand Software Market
Why this research matters for 2026
-
Rapid adoption windows: The POD software market is moving from niche automation projects into enterprise-grade workflows. Companies that lock in integrations and fulfillment partnerships in 2026 will enjoy durable advantages as the market scales.
Print On Demand Software Market -
Strategic inflection point: Our base year is 2025, and the near-term horizon (2026–2032) frames decisions on capacity, platform architecture, and channel expansion that determine market leadership.
Print On Demand Software Market -
Regulatory and cost pressure: New privacy requirements and evolving cloud licensing practices mean that TCO and contract design are now as strategic as feature parity.
Market trajectory — headline macro picture
The POD software market has experienced rapid expansion through 2025, growing from roughly $1.3 billion (2020) to about $3.3 billion in our base year, 2025. Our forecast projects that investment and adoption will accelerate meaningfully in 2026 and beyond — with the market expanding to roughly $4.4 billion in 2026 and on a path to exceed $22 billion by 2032. That growth implies a compound annual growth rate of approximately 31.1% across the forecast window.
What these headline numbers tell us: this is not incremental software substitution. Buyers are consolidating multiple functions — storefront orchestration, automated SKU generation, order routing, production scheduling, and fulfillment — into platform-level investments. The pace of adoption and the scale of the opportunity justify strategic bets in 2026, but the timing and structure of those bets will materially influence competitive outcomes.
Key market dynamics shaping 2026 choices
-
Shift from point tools to composable platforms — Buyers increasingly expect POD platforms to operate as orchestration layers that manage third‑party printers, multiple fulfillment partners, logistics providers and storefronts via robust APIs and event-driven automation. Integration capability is the new table stake.
-
Fulfillment density and distributed production — The economics of POD are driven by proximity to consumer and inventory-lite models. Software that optimizes routing across a distributed fulfillment network adds immediate margin and delivery-time advantages.
-
Automation wins on unit economics — End-to-end automation (from design templates and mockups to print-ready file validation and shipping labels) reduces manual touchpoints and labor exposure — a critical lever as labor rules and privacy laws change in 2026.
-
Regulatory & procurement pressures — Emerging state privacy laws now require data protection assessments for automated processing, while federal and enterprise buyers face new cloud licensing and vendor-surcharge practices that increase the effective cost of integrated cloud workflows. Platform architecture and contracting sophistication are therefore central to procurement decisions.
-
Specialized verticalization — Successful vendors will pair core POD orchestration with domain IP — e.g., textile DTG workflows, decorator network management, or brand-storefront experiences — to justify pricing and reduce churn.
Competitive landscape — strategic positioning of core providers
The competitive field is heterogeneous: established print-technology companies, agile SaaS orchestration providers, and free or open-entry solutions co-exist. Below are concise strategic takeaways on representative vendors covered in the study.
-
Fulfill Engine (United States): Positions as an all-in-one platform with deep API connectivity, white-label storefront capabilities, and automation for production and fulfillment across e‑commerce and decorator networks. Strategic edge: orchestration-first product design that targets enterprise partners and multi-operator ecosystems. Consideration for buyers: evaluate long-term integration and revenue-sharing terms to avoid lock-in.
-
MPODx (United States): Focuses on automating product creation, order fulfillment, packaging and shipping directly via e-commerce integrations. Strategic edge: simplicity and automation for SMB-to-midmarket merchants. Consideration: assess scalability of fulfillment routing logic and quality-control workflows for higher-volume enterprise deployments.
-
Kornit Digital / KornitX (Israel): Brings an end-to-end offering tailored to digital textile printing, combining SaaS workflow with a global fulfillment network and on-demand production for apparel. Strategic edge: vertical specialization in textile DTG with integrated hardware partnerships. Consideration: firms needing cross-category flexibility should weigh KornitX’s deep apparel workflows against more horizontal orchestration platforms.
-
Durst Software & Solutions (Italy): Optimizes web-to-print and POD for smart print factories and high-volume automated production. Strategic edge: industrial-grade production planning and integration with high-throughput presses. Consideration: best fit for partners focused on scaling factory automation rather than consumer storefront features.
-
MarketPrint (Germany): Offers a free POD software entry point for online shop operators emphasizing order processing, automated printing workflows and UX optimization. Strategic edge: low-cost adoption funnel and rapid time-to-live for merchants. Consideration: monetization and enterprise-readiness vary; evaluate support and SLA provisions for mission-critical operations.
-
PrintNow (United States): Delivers web-to-print storefronts with dynamic pricing, product customization, and integration to 140+ fulfillment partners. Strategic edge: broad partner network and retail-ready storefront features. Consideration: vendor performance across the partner network is heterogeneous; governance tooling and SLAs are differentiators.
Recent market moves highlight how these strengths convert to scale. A notable April 2026 partnership expanded Durst’s reach into MENA markets via a regional integrator, signaling that localized e-commerce and regulatory expertise is a decisive factor for geographic expansion. Similarly, an expanded collaboration in early 2025 between a leading fulfillment operator and a textile-printing hardware provider demonstrates that capacity investments (e.g., fleet deployments of high‑speed DTG systems) are being paired with software orchestration to win share.
Implications for buyers and investors in 2026
-
Negotiate contract levers that align incentives — As cloud licensing practices and vendor pricing models shift, buyers should build true TCO models that include licensing surcharges, integration lift, and ongoing vendor migration costs. Consider outcome-based pricing where feasible.
-
Prioritize modularity and data governance — With new privacy assessment obligations, prefer architectures that allow for regional data segmentation, robust logging, and clear vendor security attestations.
-
Target pilot-to-scale pathways — Run two parallel pilots: one to validate integration and unit economics with local fulfillment partners, and another to stress-test peak volumes and edge-case returns workflows. The ability to reach scale quickly separates winners from also-rans.
-
Account for labor and skill shifts — Automation will reduce repetitive roles but raise demand for cloud-integration engineers, data-protection officers, and fulfillment orchestration specialists. Plan for reskilling and selective outsourcing.
-
Consider M&A as an acceleration tool — For incumbents, acquiring orchestration or fulfillment-network capabilities can shorten time-to-market and lock in partner exclusivity. For investors, software firms with proven workflows and partner pipelines are high-conviction targets.
What the full PW Consulting report delivers (operational view)
This research is designed to be immediately actionable for strategy, procurement, product, and M&A teams. Key deliverables include:
-
Proprietary market-sizing models (historical 2020–2025 and base-year 2025 validation) and scenario-based forecasts through 2032.
-
Vendor scorecards and capability matrices aligned to buyer archetypes (enterprise brands, platform partners, fulfillment networks, and SMB marketplaces).
-
Integration playbooks for API-first architectures, event-driven order routing, and multi‑print-farm orchestration.
-
Commercial negotiation templates that neutralize cloud-surcharge exposures and clarify TCO levers.
-
RFP checklists and technical acceptance criteria for proofs-of-concept and pilot-to-scale transitions.
-
Scenario planning modules exploring alternative futures (e.g., accelerated regionalization, hardware-backed vertical consolidation, the impact of stricter privacy regimes).
How to use this research in 90 days
-
30 days — Use the vendor scorecards and RFP checklist to shortlist 2–3 platform partners and run aligned pilot charters with clear success metrics.
-
60 days — Execute integration sprints and validate routing, SLA adherence, and cost-per-order baselines; stress-test privacy and export controls.
-
90 days — Make a go/no-go decision on platform roll-out, finalize commercial terms that include migration rights, and begin capacity alignment with fulfillment partners for a Q4 scaling window.
Final perspective
The Print On Demand software market presents a rare combination of rapid growth, structural demand for orchestration, and a window where integration and commercial design meaningfully determine competitive advantage. With a projected CAGR north of 30% through 2032 and a market that moves from billions into the tens of billions in the coming years, 2026 is the year to convert exploratory budgets into strategic commitments — but to do so with disciplined contracting, modular architectures, and network-aware product strategies.
For executives seeking the complete dataset, vendor-by-vendor scoring, and the executable playbooks referenced here, the full PW Consulting Print On Demand Software Market report provides the models and appendices necessary to operationalize these insights. Access to the full report and supporting deliverables is available via our research portal.
For detailed analysis of this topic, please visit the official page: Print On Demand Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
All-In-One CRM to Reach USD 175B by 2032 at 12.4% CAGR — PW Consulting
By pmarketresearch, 2026-07-13
All‑In‑One CRM Software Market: Strategic Frames for 2026
Executive snapshot
By 2025 the All‑In‑One CRM Software market had matured into a billion‑dollar category with clear momentum: from roughly 50.5 billion USD in 2020 the market expanded to approximately 83.2 billion USD in 2025. PW Consulting’s forecast models project continuation of this trajectory, reaching roughly 96.7 billion USD in 2026 and more than 175.0 billion USD by 2032 — an effective compound annual growth rate of 12.4% over the 2026–2032 forecast horizon. This pace reflects both accelerating adoption of agentic AI, broader cloud modernization, and the commercialization of automation at scale.
All-In-One CRM Software Market
Why this research matters for 2026 decision-makers
-
Timing is now strategic: 2026 is a turning point where pilots and point solutions must either scale into platform bets or be retired. The market growth profile shows a window for aggressive platform capture during enterprise digital transformation programs.
All-In-One CRM Software Market -
Vendor choice is multi‑dimensional: decisions are no longer about feature checklists alone. You must evaluate platform composability, AI modality support, data residency and governance, integration cost, and a vendor’s route to ongoing value delivery.
All-In-One CRM Software Market -
Capital allocation requires precision: whether you represent corporate IT, a business unit owner, or an investor, the market’s growth and concentration dynamics demand calibrated investment and M&A playbooks to secure defensible positions.
Macro takeaways for 2026 planning
-
Scale and speed: With the market nearly doubling over the previous five years and still expanding at double‑digit CAGR, procurement cycles should prioritize scalable architectures that reduce marginal integration cost as usage grows.
-
Cloud‑first is table stakes: The dominant delivery model is cloud, enabling frequent product updates, built‑in analytics, and rapid AI upgrades. On‑premises remains relevant for niche regulatory reasons but is not the growth vector.
-
Consolidation dynamics: Market concentration metrics indicate a moderate top‑end concentration — leading vendors control a majority but there remains substantial runway for challenger platforms offering specialization, vertical depth, or disruptive pricing and go‑to‑market models.
-
AI drives re‑segmentation: Agentic AI and autonomous connectors are creating new product layerings — from smart agents that execute routine sales activity to autonomous marketing orchestration that reduces manual campaign labor.
What this report gives you — in practical terms
PW Consulting’s All‑In‑One CRM Software Market study is designed as an operational playbook for 2026. Key deliverables include:
-
Robust market sizing and demand modeling (historical 2020–2025, base year 2025, forecast 2026–2032) expressed in consistent USD billion terms and stress‑tested under alternative adoption scenarios.
-
Vendor scorecards that go beyond capability matrices to evaluate developer ecosystems, AI partner readiness, integration velocity, and realistic TCO profiles over three‑ and five‑year horizons.
-
Go‑to‑market and buyer decision frameworks with step‑by‑step procurement templates, RFP checklists, and implementation risk heatmaps tailored for enterprises and channel partners.
-
M&A and investment diagnostics highlighting build vs buy inflection points, defensible moats, and realistic exit multiples under conservative and aggressive growth scenarios.
-
Integration blueprints for common enterprise architectures, including data governance patterns, identity orchestration, and recommended middleware approaches to prevent long tail technical debt.
Competitive landscape — how leading vendors are positioning
The competitive field is a mix of global platform incumbents, scale challengers, and specialist stacks. Key dynamics we track across vendors include platform breadth, AI/agent roadmaps, verticalization strategies, and partner ecosystems.
-
Salesforce — The Customer 360 narrative continues to center Salesforce’s strategy: uniting sales, service, marketing, commerce, and agent capabilities into an operational fabric. Recent product releases in 2026 extended Agentforce capabilities and analytics across the Customer 360 suite, underlining a push to capture higher‑value enterprise deals and to lock in cross‑cloud data advantages.
-
HubSpot — HubSpot’s Customer Platform emphasizes usability and an agentic ecosystem. The Spring 2026 Spotlight introduced Breeze Agents and smarter deal progression features, signaling an intent to lower the activation cost for midmarket accounts while progressively moving upmarket.
-
ActiveCampaign — ActiveCampaign’s strategy is to operationalize autonomous marketing. In early 2026 the company shipped an autonomous marketing connector for Anthropic’s Claude, illustrating how third‑party LLM integrations are being productized to reduce human orchestration in campaign execution.
-
Creatio — Creatio positions itself as an AI‑native no‑code platform. Recent enterprise wins demonstrate its appeal to institutions seeking rapid configuration and cross‑org unification without heavy engineering lift.
-
Zoho CRM — Zoho continues to push deeper automation into daily workflows. Q1 2026 updates focused on workflow ergonomics and natural language formula generation, reinforcing Zoho’s strategy of embedding pro‑productivity tools at low cost.
-
Specialists and SMB stacks — Vendors like 1CRM, ConvergeHub, Salesmate, and others compete on focused use cases: order management, loyalty, lead prioritization, and price‑performance for SMBs. These vendors remain important acquisition targets and talent pools for larger platforms building vertical depth.
Technology and operational dynamics shaping vendor advantage
-
Agentic AI is redefining workflows: Embedded AI agents that can execute prospecting, follow‑ups, and parts of service workflows shift value from feature breadth to agent effectiveness and observability.
-
No‑code / low‑code matters beyond speed: Platforms that let business users compose end‑to‑end processes reduce governance friction, but successful deployments demand strong guardrails and audit trails.
-
Data governance as a competitive moat: Vendors that can provide enterprise‑grade data controls, lineage, and cleanroom capabilities will win larger deals where privacy and compliance are non‑negotiable.
-
Partner ecosystems compress time‑to‑value: System integrators and ISVs that package vertical accelerators (e.g., financial services member onboarding, retail loyalty orchestration) will shorten sales cycles and increase stickiness.
Strategic playbook: what each stakeholder should prioritize in 2026
-
Enterprise CIO / CDO: Build a 36‑month platform roadmap that budgets for AI enablement, data plumbing, and a vendor consolidation plan. Prioritize platforms with composable APIs and clear migration paths for legacy CRM data.
-
Chief Revenue / Marketing Officers: Test agentic automations in controlled pilots tied to revenue KPIs. Expect initial lift in lead conversion and operational efficiency; measure net impact on pipeline economics, not just activity metrics.
-
ISVs and system integrators: Invest in packaged vertical accelerators and clear SLAs for AI behavior. Time‑to‑value packaged solutions will beat bespoke implementations in most midmarket segments.
-
Private equity and strategic investors: Focus diligence on recurring revenue quality, partner attrition metrics, and the asset’s capacity to plug into larger platform ecosystems. The best targets will show defensible product differentiation and accelerating net retention.
Why PW Consulting’s report is the right toolkit for 2026
We combine quantitative rigor (full historical series 2020–2025; base year 2025; detailed forecasts 2026–2032; currency in USD billions; modeled at a 12.4% CAGR through the forecast window) with qualitative, execution‑oriented insight: vendor playbooks, implementation checklists, and acquisition scorecards. The study is intentionally structured to support both strategic and tactical workstreams — from boardroom strategy to procurement and implementation squads.
Next steps — how to use this preview
-
Request the full vendor scorecards to benchmark platform choices against your integration and AI maturity.
-
Use the TCO and migration templates to model three migration pathways — lift‑and‑shift, phased modernization, and greenfield replacement — and quantify incremental savings and business outcomes.
-
Engage PW Consulting for a short diagnostic to map your CRM estate to the market’s growth segments and identify immediate efficiency levers for 2026.
Closing
The All‑In‑One CRM Software market in 2026 is neither a commodity nor a simple vendor selection exercise — it is a strategic architecture decision that will shape go‑to‑market execution and customer economics for years. PW Consulting’s research provides the macro context, competitive read, and practical tools you need to make those decisions with confidence. For full segmentation tables, granular regional and use‑case analysis, and vendor benchmarking data, consult the complete report and supporting datasets.
For detailed analysis of this topic, please visit the official page: All-In-One CRM Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
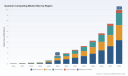
Quantum Computing Market — Strategic Imperatives for 2026 Decision‑Making
Executive snapshot
Quantum computing is transitioning from laboratory breakthrough to enterprise agenda item. Our latest PW Consulting market study, anchored on a 2025 base year and covering historical performance (2020–2025) with forecasts to 2032, places the industry on a sustained high‑growth trajectory. The market expanded rapidly over the first half of the decade—moving from single‑digit millions to a multi‑hundred‑million to low‑billion USD environment—and reached approximately USD 1.5 Billion in 2025. Under a central scenario, we model a robust compound annual growth rate of 29% through 2032, bringing the global market close to USD 10 Billion by the end of the forecast period.
Quantum Computing Market
That pace of expansion is not uniform: technology pathways (superconducting, trapped‑ion, photonic, annealing and others), infrastructure maturity (cloud access, colocated devices, dedicated on‑prem systems), and regulatory regimes all create pockets of rapid adoption alongside areas where integration remains nascent. This asymmetry is precisely why 2026 is a critical pivot year for corporate and public sector decision‑makers.
Quantum Computing Market
Why this report matters for 2026 strategy
Many organizations will face a classic build‑versus‑buy decision in 2026. Early adopters that delay architecture choices risk higher conversion costs and longer runways to production; those that commit too aggressively risk vendor lock‑in or stranded investments if competing modalities leapfrog expectations. Our study is designed to inform those tradeoffs with scenario‑driven, actionable guidance.
Quantum Computing Market
- Timing: Identify the commercial inflection points that matter for procurement windows, pilot budgeting, and multi‑year roadmaps.
- Risk management: Quantify operational and supply‑chain risks (device reproducibility, cryogenics, interconnects, component sourcing) and map mitigation levers you can implement today.
- Vendor strategy: Build a defensible partner portfolio—when to partner with hyperscalers, when to co‑invest with specialist vendors, and when to favor multi‑vendor/cloud neutrality to preserve optionality.
- Regulatory & geopolitical readiness: Translate export controls, domestic incentives, and regional industrial strategies into practical compliance and sourcing playbooks.
What’s inside the report — practical, transaction‑grade tools
The PW Consulting study is deliberately operational. Beyond high‑level forecasts and trend analysis, the report includes: scenario models (fast technical progress vs. conservative adoption), vendor due‑diligence templates, total cost of ownership models for cloud vs. on‑prem deployments, capex phasing roadmaps keyed to technical milestones, and an M&A playbook for acquiring quantum‑era IP and talent. We also provide implementation blueprints for use cases where quantum advantage is plausible in the near to mid term—covering optimization, simulation of complex materials/chemistry, and early hybrid classical‑quantum machine learning experiments.
- Interactive financial models you can parameterize with your own cost and revenue assumptions.
- Vendor scorecards and integration checklists for procurement teams.
- Regulatory compliance checklists aligned to recent export control and regional industrial policy changes.
- Workforce and skills transition plans to bridge classical HPC, AI, and quantum engineering teams.
Competitive landscape — capabilities, positioning, and tactical takeaways
The market is consolidating around a set of capability clusters rather than a single winner‑takes‑all outcome. Leading technology suppliers fall into distinct strategic typologies: hyperscale integrators offering cloud access and cross‑platform marketplaces; specialist device companies advancing particular qubit modalities; and vertically integrated vendors selling systems to research and national infrastructure customers.
- Hyperscale platforms: Established cloud providers are moving beyond access to build proprietary device capability and hybrid orchestration. Expect differentiated value from combined cloud, tooling, and data services that lower customer integration costs.
- Device specialists: Companies focused on one modality (superconducting, trapped‑ion, photonic, neutral‑atom, annealing, silicon spin, etc.) are executing on performance roadmaps—many are now offering cloud access and targeted commercial systems for application pilots.
- Systems integrators and regional champions: A cohort of firms is commercializing full‑stack solutions and selling into supercomputing centers, national labs, and industrial incumbents requiring on‑prem or dedicated installations.
Key examples from our competitive matrix (profiles included in full report): IBM’s superconducting roadmap and System One architecture; Google Quantum AI’s emphasis on error correction and logical qubits; Microsoft’s multi‑modal Azure Quantum strategy; Amazon Braket’s marketplace approach coupled with its proprietary cat‑qubit development; D‑Wave’s annealing platforms optimized for combinatorial optimization; IonQ and Quantinuum’s trapped‑ion advancements; photonics entrants targeting fault‑tolerant roadmaps; and regional players pursuing national infrastructure deployments. The leading vendors collectively produce a market that is moderately concentrated—top players hold substantial, but not overwhelming, shares—creating room for strategic partnerships and niche leadership.
Recent market catalysts and structural drivers
Several developments converging in 2024–2026 materially reshape strategic choices for 2026:
- Policy and incentives: Significant public programs and incentive agreements are accelerating domestic manufacturing and systems engineering priorities, with funds targeted at reproducibility, cryogenics, and interconnects—areas that materially affect supply‑chain risk and timing.
- Standardization and benchmarking: Regional standards initiatives and benchmarking coordination are beginning to create interoperable performance baselines—this will reduce buyer due diligence burden but also raise the bar for vendors that cannot demonstrate measurable benchmarks.
- Technological bottlenecks: Cryogenics, in‑vacuum control electronics, and error‑correction overhead remain primary engineering constraints. Advances in these areas materially shorten the time to commercially useful quantum workloads.
- Private capital and distributed systems: New funding rounds and commercial system launches—especially in distributed quantum networking and logical qubit demonstrations—signal that we are moving into a capital‑intensive commercialization phase where deployments will be differentiated by systems engineering and integration rather than raw qubit counts alone.
Strategic implications by decision area
- Procurement & architecture: Favor modular architectures that allow swap‑out of device providers and prioritize hybrid orchestration. Shortlist vendors based on integration overhead, not just headline qubit metrics.
- R&D and IP strategy: Participate in consortia and standards bodies to influence benchmarks and secure early access to interoperability frameworks; consider minority equity stakes or co‑development to secure priority roadmaps.
- Regulatory & supply chain: Reassess sourcing strategies in light of export control regimes and national industrial strategies—plan for segmented supply chains and localized redundancy for mission‑critical projects.
- Workforce & partnerships: Invest in cross‑training classical HPC and quantum engineers; prioritize partnerships with cloud providers for rapid pilot execution while building in‑house capability for differentiated production workloads.
What PW Consulting recommends today (high level)
- Adopt a two‑track strategy: run near‑term pilots to validate primitive advantage in tightly scoped use cases, while establishing architectural guardrails and supplier optionality to capture medium‑term production opportunities.
- Prioritize investments in integration: spend on systems engineering, cryogenic interfaces, and software toolchains now to reduce future migration costs.
- Engage in standards and policy dialogues: active participation shortens compliance timelines and can influence the shape of benchmarking that will determine procurement decisions.
- Use incentives strategically: align proposals to public funding that targets shared bottlenecks—this can materially accelerate timelines and lower capex.
Next steps — where to find the detailed intelligence
This article is a strategic preview. The full PW Consulting Quantum Computing Market report contains the granular segmentation, vendor scorecards, downloadable financial models, scenario dashboards, and step‑by‑step implementation guides that procurement, R&D and C‑suite teams will use to make defensible 2026 decisions. We have intentionally withheld detailed regional and application share tables in this preview to preserve the value of the complete dataset and analytic tools included in the full deliverable.
For organizations preparing to make procurement, partnership, or investment decisions in 2026, the complete report provides the transaction‑grade analysis required to move from pilot to production with confidence: side‑by‑side technology comparisons, detailed integration timelines, regulatory checklists, and bespoke advisory options from PW Consulting to tailor roadmaps to your strategic objectives.
Contact PW Consulting to access the full report, interactive models, and advisory engagement options to convert the quantum market’s projected growth into measurable business outcomes for 2026 and beyond.
For detailed analysis of this topic, please visit the official page: Quantum Computing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Single-Use Sensors Market 2026: Strategic Playbook for Bioprocess Leaders
Executive snapshot
As single-use technologies become standard across biologics manufacturing, single-use sensors have emerged from niche components to strategic levers for process control, speed-to-clinic and cost optimization. Our PW Consulting Single Use Sensors Market study (base year 2025; historical 2020–2025; forecast 2026–2032) quantifies this transition: the market reached approximately USD 392.0 Million in 2025 and is set to expand at a compound annual growth rate (CAGR) of 14.2% over the forecast window, crossing roughly USD 984.0 Million by 2032. For executives preparing decisions in 2026, these macro signals are not theory — they are the economic backdrop that will shape procurement, R&D prioritization, partnerships and M&A for the next three to five years.
Single Use Sensors Market
Why this matters for 2026 strategic decisions
-
From tactical sourcing to platform strategy: The rapid growth of demand for disposable sensors transforms them from commodity purchases into critical path elements for single-use bioprocess platforms. Decisions made in 2026 about supplier qualification, platform compatibility and inventory buffers will determine time-to-market for new drug candidates and the resilience of commercial supply chains.
Single Use Sensors Market -
Regulatory and validation timings are decisive: Unlike many consumables, sensors require integration into process validation, sterilization regimes and quality systems (ISO 13485, USP Class suitability, gamma sterilization validation). Lead times for qualification can be measured in quarters; delaying a decision on sensor platform architecture in 2026 can cascade into missed clinical or commercial milestones.
Single Use Sensors Market -
Cost-to-serve and unit economics: As adoption scales, the per-run economics of single-use bioprocesses are increasingly sensitive to sensor selection — both direct unit cost and indirect impacts such as validation, reuse of electronics, and sensor reliability. The market’s double-digit CAGR signals both pricing pressure and opportunity for differentiated, value-based offerings.
What our report delivers — practical assets for 2026 planning
The report is structured to be operationally actionable for leadership teams and program managers. Highlights include:
-
Proprietary market sizing and forecast model (2020–2032) with scenario analyses that stress-test adoption curves and technology substitution effects under multiple commercialization timelines.
-
Technology roadmaps identifying near-term (1–2 years) and medium-term (3–6 years) innovations in sensor chemistries, sterilization compatibility (e.g., gamma-sterilizable designs), and integration approaches (patches, inline, preinstalled cartridges).
-
Vendor scorecards and procurement playbooks that map supplier capabilities (manufacturing certifications, cleanroom class, materials compliance) to the operational requirements of biomanufacturers.
-
Regulatory and validation checklists tailored for single-use sensor adoption, including recommended testing regimes, documentation strategies for FDA/EMA submissions, and change-control templates to reduce downstream risk.
-
Commercial frameworks — pricing strategies, channel models (OEM, direct, distributor), and contract terms crafted for 2026 negotiation cycles.
-
M&A and partnership decision matrices that help evaluate bolt-on opportunities versus internal development, with payback timelines under current market growth assumptions.
Competitive landscape: how incumbents and specialists stack up
The competitive field is a mix of specialized innovators and capitalized instrument OEMs. Our market concentration analysis shows an industry moving toward consolidation: the top three players account for a meaningful portion of market share while the top five are responsible for the majority of sales — a structure that creates both barriers and strategic openings.
-
PendoTECH (Portsmouth, NH, USA) — Strengths: certified manufacturing (FDA-registered, ISO 13485), controlled cleanroom production and a portfolio spanning pressure, pH, conductivity, temperature and optical sensors. Implication: well positioned to supply GMP-grade sensor assemblies and attractive OEM partnerships.
-
Levitronix (Bedford, MA, USA) — Strengths: LEVIFLOW ultrasonic inline flow sensors built from gamma-robust polypropylene and compliant materials. Implication: differentiates via non-invasive flow measurement and materials engineered for sterilization robustness — a clear fit for operators prioritizing sterility assurance.
-
Broadley-James (Irvine, CA, USA) — Strengths: SingleSense® line of preinstalled pH, DO and pCO2 sensors with long shelf life and FDA-compliant materials. Implication: value proposition centers on convenience and reduced assembly risk for bag-based workflows.
-
Hamilton Company (Reno, NV, USA) — Strengths: patch-style single-use pH and DO sensors designed for compatibility across bioreactor bag platforms. Implication: platform-agnostic interoperability that appeals to multi-vendor facilities.
-
Sartorius AG (Göttingen, Germany) — Strengths: integrated single-use sensors with gamma-sterilizable options and deep bioreactor integration. Implication: as a systems supplier, Sartorius can bundle sensors with bioreactor platforms to capture higher share of wallet.
-
Thermo Fisher Scientific (Waltham, MA, USA) — Strengths: acquisition-driven expansion (e.g., Finesse Solutions optical sensors) and global commercial reach. Implication: ability to quickly scale new sensor technologies via established channels.
-
Danaher Corporation (Washington, DC, USA) — Strengths: Cytiva platform provides established routes to market for single-use probes and sensors. Implication: major incumbent with integration advantages and cross-selling opportunities across process equipment.
-
Parker Hannifin Corporation (Cleveland, OH, USA) — Strengths: flow and pressure monitoring solutions tied to fluidic systems. Implication: well-suited for integrated process control offerings where sensors are bundled with fluid handling equipment.
-
Eppendorf AG (Hamburg, Germany) — Strengths: sensor patches and optical pH/DO solutions geared to single-use bioreactors. Implication: focuses on ease-of-use and integration for benchtop and small-scale manufacturing.
Strategically, the field presents three archetypes buyers will face in 2026: (1) system integrators that bundle sensors with platforms, (2) specialized suppliers offering differentiated chemistries or form factors, and (3) OEM/contract manufacturers providing private-label solutions. Each archetype implies different negotiation levers and risk profiles.
Key strategic imperatives for 2026
-
Lock down validated supplier lanes early: Prioritize supplier qualification and cross-validate sterilization claims. Given validation lead times, locking agreements and performing interoperability tests in 2026 prevents downstream delays.
-
Design for compatibility: Choose sensor architectures that minimize platform lock-in (e.g., interoperable electronics or modular patch interfaces) to protect portfolio flexibility as the market evolves.
-
Prioritize sterilization-proof materials and supply security: Gamma-robust materials and USP-compliant polymers will be table stakes for broad adoption. Secure multiple material sources and audit supply chains for critical polymers.
-
Use procurement as a strategic lever: Negotiate volume-based pricing tied to validated performance metrics, but also include clauses for rapid ramp-up support and co-development for future sensor features.
-
Scan for bolt-on innovation targets: For platform vendors and private-equity-backed companies, 2026 is fertile for targeted M&A — buying specialty sensor tech can accelerate capability without long internal development cycles.
A pragmatic decision framework for 2026
When assessing options this year, apply a two-step framework:
-
Qualify (Now): Regulatory fit (materials, ISO/FDA), sterilization compatibility, and manufacturing certifications. These are non-negotiables and should be verified through audits or third-party validation reports.
-
Optimize (Next 6–18 months): Total cost of ownership (unit cost, validation cost, failure rate), integration roadmap (electronics, data compatibility), and strategic optionality (IP, co-development rights).
Closing: why our report is a 2026 decision catalyst
For executives, 2026 will be a year where sensor decisions compound into competitive advantage or operational drag. Our report provides the empirically grounded market sizing and the playbooks that translate those numbers into procurement actions, product roadmaps and M&A priorities. We intentionally preview strategic signals here while withholding the granular regional, application and price-point tables that operational teams use to run negotiations and build business cases — those proprietary segment matrices, supplier scorecards and transaction-ready models are available in the full PW Consulting Single Use Sensors Market report.
Contact PW Consulting to schedule a brief that maps the report’s insights directly to your 2026 roadmap and procurement calendar. In a market growing at double-digit rates and reshaping how biologics are developed and commercialized, timely choices about sensors will be disproportionately consequential.
For detailed analysis of this topic, please visit the official page: Single Use Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com